Investors should be careful what they wish for in hoping for an aggressive Fed rate cutting cycle, given stocks tend to do better when cuts are slow and steady.
When we’re viewing markets, it’s not surprising sentiment shifts quickly if we don’t instantly see the anticipated results. Market pundits quickly point fingers and determine the Fed, economists, and participants are wrong. Reactions can be powerful in number and sway momentum for stocks and/or bonds.
After a decade of consistent outperformance, Japanese small caps began underperforming their large cap peers in 2018, a trend that has accelerated since 2023.
This week’s data reflects the resilience of the U.S. economy. Currently, the economy is holding steady with jobless claims in the 230,000 range and recent inflation data showing stability. Friday’s inflation report was essentially at expectations and indicates that the Federal Reserve (Fed) will make a rate cut of at least 25 basis points (bps) at the September meeting. Whether the cut is 25 or 50 will depend mostly on this week’s employment report.
In this edition, Harold Evensky explores the challenges facing sustainable and active funds, the implications of the new DOL Fiduciary Rule, and the value of long-term performance projections. With candid observations and critical analysis--read on to gain perspective on navigating the complex world of investing, the importance of risk management, and the role of fiduciary advisors in securing your financial future.
A soft landing for the U.S. economy still appears to be the most likely outcome.
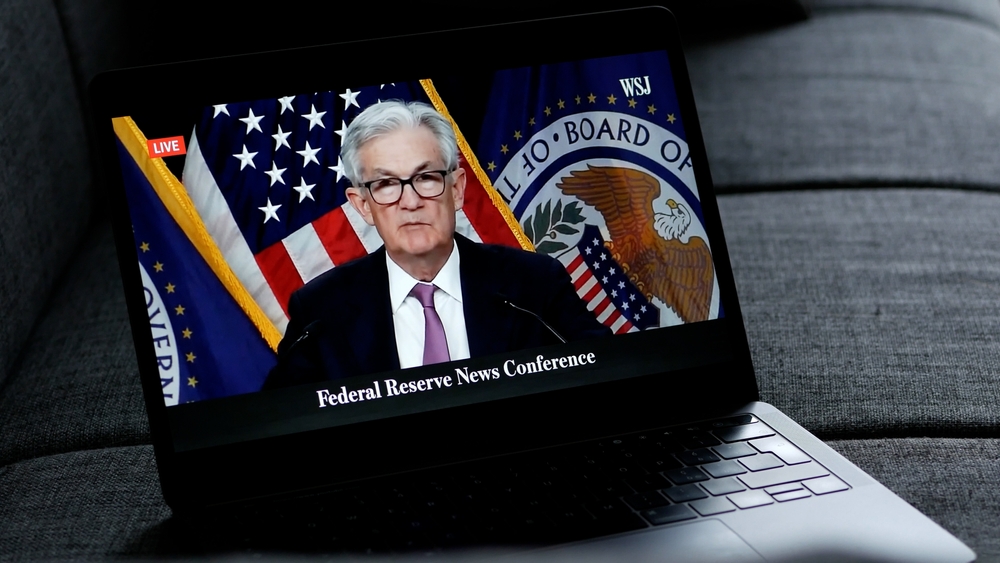
With his Jackson Hole speech, Federal Reserve Chair Jerome Powell all but promised rate cuts were coming. That’s cool. But it is why that matters.
After a bit of an early-August swoon, the stock market came roaring back in the last few weeks of the month. The S&P 500 finished up 2.4%, though certainly in the early days of August, that did not feel like a particularly likely outcome. In client conversations a few days into the selloff, our feeling was to stay put and not tinker with the portfolios we suggested in early August.
In our view, stagflation scenarios tend to be worse for balanced portfolios than recessions.
I asked my great friend and business partner David Bahnsen, who is about as politically wired as anyone and one of the truly great economic and investment minds, to reflect on the intersection of politics and markets. It is a quick, balanced, and reasonable read...
As I write this, gold continues to trade above $2,500 an ounce after surging past the psychologically important level for the first time ever in mid-August. For seasoned gold mining investors, this should be a moment of validation. After all, the yellow metal has long been seen as the ultimate hedge against economic uncertainty.
Has the tide turned decisively against King Dollar? A fall of around 5% in the greenback versus major currencies in the past two months, pushing the dollar index to a 13-month low, suggests its post-pandemic surge has meaningfully faltered.
Investors pursuing widely followed 60/40 strategies should consider swapping out bonds for commodities, according to strategists at Bank of America Corp.
The Federal Reserve’s preferred measure of underlying US inflation rose at a mild pace and household spending picked up in July, reinforcing policymakers’ plan to start cutting interest rates next month.
When you see that behavior at extreme valuations, it tends to be a sign of underlying skittishness and risk aversion. When valuations are setting record extremes because the news can’t get any better, even a slightly less optimistic outlook becomes a risk.
China's economic transformation presents both challenges and opportunities for global markets.
Forecasting anything, let alone something as complicated as the economy, is fraught. Stretches of decent growth and low inflation that look, in retrospect, like happy days, can be upended by unforeseen events. Covid, the descent into recession and the sharp rebound are just a few examples. Errors, unfortunately, are an unavoidable part of trying to map the future.
Last week’s meeting of central bankers in Jackson Hole was a kind of victory lap for the Fed. It may have also marked the peak of its power.
Many recent studies have been done on the economics of different generations. Researchers want to know if Millennials and Gen Z are in fact worse off than their Boomer and Gen X parents. There are quite a few ways to look at this data.
Those warning that the US Federal Reserve is dragging the economy down are deeply mistaken. Far from being too restrictive, US monetary policy is almost certainly too loose, judging by the robustness of financial markets and broader economic conditions even after 500 basis points of interest-rate hikes.
The path for lower rates in the U.S. has finally arrived.
While short-term fluctuations and sudden selloffs have tested the markets, key indicators such as corporate profits, employment data, and economic resilience have held firm.
The level of U.S. Treasury yields and the changing shape of the Treasury yield curve provide investors with critical feedback regarding the market’s expectations for economic growth, inflation, and monetary policy
Chair Jerome Powell cemented a shift in focus from inflation to employment last week when he said that the Federal Reserve does not seek a further cooling in the labor market. It was a welcome message for those concerned about an economic slowdown. But there are reasons to expect today’s sluggish hiring environment to persist at least into early next year, frustrating job seekers and policymakers alike.
US Treasury yields edged higher after resilient economic reports prompted traders to slightly trim their expectations for the scope of Federal Reserve easing this year.
Nvidia Corp.’s earnings report was impressive by virtually any metric — except its own recent history.
In an election year, we are bound to hear a lot of commentary about the merits and drawbacks of both major candidates’ economic policies. History shows that while a president’s policies can make life easier or more difficult for various sectors of the economy, U.S. Federal Reserve (Fed) policy has much more impact on the economy overall.
An extended period of elevated interest rates may have long-term implications for both consumers and businesses—affecting how investors value company shares.
We analyze Federal Reserve Chair Jay Powell’s comments about the potential for rate cuts in September and beyond.
The healthcare sector offers a compelling mix of defensive characteristics and growth potential driven by innovation. It also features ample dispersion that presents stock pickers with an opportunity to parse potential leaders and laggards in pursuit of above-market return.
The latest retail sales report seems to have given Wall Street something to cheer about. Headlines touting resilience in consumer spending increased hopes of a “soft landing” boosting the stock market.
At the recent central-bank symposium at Jackson Hole, Federal Reserve Chairman Jerome Powell delivered a widely expected message on interest rates: “The time has come for policy to adjust.” He all but confirmed that the Fed would cut rates by at least a quarter-point when its policymakers next meet in September.
With a September interest-rate cut all but certain and attention turning to the pace of future reductions, Federal Reserve officials are coalescing around a gradual approach to the last mile of their inflation fight.
The most glaring uncertainties today, which contributed to early August seeing some of the largest market moves in the last several years, are the risks associated with the Federal Reserve’s dual mandate.
With US payroll and unemployment data surprising to the downside two Fridays ago, Treasury markets quickly repriced the probability of impending recession, helping set off a volatility spike in stocks across the world. According to Bloomberg, economists’ consensus probability of a US recession in the next twelve months is now approximately 30%.
A Soft Landing Scenario Is Still a Realistic Base Case.
Elevated budget deficits imply growing US Treasury issuance. Receding demand from central banks could leave more price-sensitive buyers to pick up the slack. Who are the buyers of US government debt, and how is the market responding? In part two of our series, let’s examine Treasury market supply and demand.
The 19th Century American author Mark Twain once said: “Travel is fatal to prejudice, bigotry, and narrow-mindedness, and many of our people need it sorely on these accounts. Broad, wholesome, charitable views of men and things cannot be acquired by vegetating in one little corner of the earth all one’s lifetime.”
It’s been the ultimate no-brainer for more than a year: Park your money in super-safe Treasury bills, earn yields of more than 5%, rinse and repeat. Or as billionaire bond investor Jeffrey Gundlach put it last October, “T-bill and chill.”
Happy National Cheap Flight Day! Yes, you heard that right—there is a national celebration day to mark the start of a lull in travel demand. Who knew this would be a day to celebrate? Regardless, it’s good news for consumers as airfares should continue their recent downward trend!
We all knew it was coming…and in Jackson Hole, Federal Reserve Chairman Jerome Powell said it will come next month. He said, “the time has come,” and the futures markets have priced in either a 25 or 50 basis point rate cut at the meeting on September 18.
Powell’s remarks in Jackson Hole were more dovish than I anticipated. Powell did not hedge; the clear direction of policy was lowering rates. The focus of the Federal Reserve’s (Fed's) narrative was shifting away from inflation risk to employment.
Profitable bond trading opportunities arise when your expectations about Fed policy differ from those of the market. Therefore, with the Fed seemingly embarking on a series of interest rate cuts, it behooves us to appreciate how many interest rate cuts the Fed Funds futures market expects and over what period.
In his annual Jackson Hole speech, Fed Chair Powell assessed the post-pandemic U.S. economy and suggested rate cuts are coming soon.
That anthem was characteristic of the era. After two decades of economic frustration, free market policies had prompted a surge of growth and a bull market for stocks. The captains of industry were corporate raiders, who purchased companies, slashed expenses, pushed up prices and reaped outsized rewards.
As a businessman and ex-business owner, the idea of firms ‘hoarding’ workers never made sense. As an economist, the idea of firms hoarding workers never made sense either.
The market’s 8.5% decline during August sent shockwaves through the media and investors. The drop raised concerns about whether this was the start of a larger correction or a temporary pullback. However, a powerful reversal, driven by investor buying and corporate share repurchases, halted the decline, leading many to wonder if the worst is behind us.
This week we take a not-so-random walk through the data, trying to simplify what is actually a fairly complex subject. I think it is quite fun, but also important. Let's dive in.
This week, before she accepted the Democratic Party’s nomination for president, Vice President Kamala Harris threw her support behind President Joe Biden’s tax proposals for 2025, which include a steep 44.6% capital gains rate and an unprecedented 25% tax on unrealized gains.
Economic indicators are released every week to provide insight into a country’s overall economic health. They serve as essential tools for policymakers, advisors, investors, and businesses because they allow them to make informed decisions regarding business strategies and financial markets.