WisdomTree, Inc.

Hitting Reset: Top Reasons for Market Optimism Post Elections
Declines of that size usually accompany a recession. This one arrived while earnings were growing at double digits. In our view, that makes it a reset, not a breakdown. Here are our top reasons for why we are optimistic about equities heading into 2027.
Strong Jobs Report Reinforces Outlook and Market Rotation
The employment report was extraordinarily strong, with approximately 165,000 jobs created, well above expectations, and upward revisions of 84,000 for the previous two months. Almost all the gains were in the private sector, with manufacturing adding 19,000 jobs.
Tech Weakness Fuels Bond Rally and Value Rotation
The Federal Reserve meeting last week was largely uneventful. The S&P 500 and the 10-year Treasury yield ending the trading session almost exactly where they stood before the Fed’s announcements. Despite some disagreements within the Fed, there was virtually no forward guidance.
Holding the Line
The Federal Open Market Committee (FOMC) decided to keep rates unchanged, maintaining the fed funds trading range at 3.75% to 4.00%. After some early back and forth on the chances for a rate hike at this gathering, this result was largely expected. In fact, fed funds futures were pricing in more than a 90% chance that the fed funds target would remain unchanged.
Mind the $2 Trillion Gap
With the recent movements in both the stock and bond markets, there was some noteworthy news that got kind of lost. Indeed, the U.S. government posted a $1.99 trillion budget deficit for fiscal year (FY) 2026. While technically it is not a record amount of red-ink, it represented the largest non-COVID-related shortfall ever recorded in modern history.
Value Breakout Shows Benefits of Diversification
There was very little macroeconomic news last week, but there was certainly no shortage of action in the markets. We saw an extraordinarily sharp rotation out of growth and into value, with both the Russell Value Index and the S&P Value Index reaching all-time highs even as the Nasdaq suffered one of its largest recent selloffs. That is a dramatic divergence, but historically it is not unprecedented.
Investing in a 5% Bond World: The Barbell
The number one question we tend to receive is: Where are long-term interest rates headed from here? Right behind it is: How do I invest in the bond market, not only for right now but also for the future? In our opinion, investors should be prepared for this elevated “normal” rate setting for the foreseeable future. We wanted to address both questions by examining how to prepare a bond portfolio for a 5% world.
AI Buildout Drives Yields and Market Rotation
Earnings now have become the central market focus this week. Bank results have been somewhat mixed, and the market will need confirmation that profits outside the largest technology companies are strengthening. I still do not believe the overall equity market is excessively valued, but investors should expect continued volatility between growth and value as expectations for AI spending shift.
Equities: On Hikes and Highs
Central banks are tightening, and stocks are still within reach of their highs. The Fed hiked on September 16 for the first time since 2023, and the 10-year Treasury yield touched 5.34% this month, its highest level since 2002. Even so, the S&P 500 sits within roughly 2.5% of its record, and Japanese equities recently set fresh all-time highs.
Investing in a 5% World
One of the hallmarks for the U.S. economy over the last few years has been its resiliency. This calendar year has been no exception as the war in the Middle East led many a market prognosticator to pencil in the potential for a recession stemming from the effects of the Middle East war.
Same Investment Goal, Different Starting Point: The Case for SMAs
We see a reason for advisors to evaluate the support surrounding the strategy. Questions about onboarding existing holdings, applying restrictions, monitoring tax budgets and managing ongoing trading belong with the implementation provider. Understanding exposures and portfolio fit is where our consultation team can help.
Rising Real Rates Signal Stronger Growth: Upgrading Equity View
The market continues to hold near all-time highs despite pressure from higher bond yields. This week brought relatively little economic data, but the important takeaway is that the underlying economy still looks strong. High-frequency indicators, jobless claims and consumer spending data continue to point to solid growth, while this week’s CPI, PPI and retail sales reports will provide the next important test for both the economy and the Federal Reserve.
Opportunities Go Global
Global investing is changing. Geopolitical tensions, shifting trade relationships, energy costs and divergent central-bank policies are increasingly influencing which companies and markets are best positioned to navigate the environment.
Softer Jobs Data Gives Fed Room to Pause
The latest employment report was softer on the headline numbers, but I thought the underlying details were quite constructive. Payroll growth came in below expectations and the prior two months were revised downward, yet labor-force participation increased and the workweek stabilized rather than declining as expected.
Higher Bond Yields Go Global
The sell-off in U.S. Treasury (UST) yields has continued pretty much in an unabated fashion In fact, multi-year high watermarks are being achieved throughout the fixed coupon maturity curve. The most widely followed development was the UST 10-year yield rising to its highest level since 2007.
Surging Real Yields Test a Resilient Market
The bond market has become the central story for investors. The remarkable development over the past several weeks is not rising inflation expectations but rising real interest rates. Real rates have increased roughly 40 basis points in just three weeks, one of the sharpest moves I can remember over such a short period. Meanwhile, longer-term inflation expectations have actually edged slightly lower.
When Do You Start Paying Attention? A Lesson from NVIDIA’s 2018 Financial Results
I do not know whether quantum computing is in that kind of window right now. Nobody does, and I am suspicious of anyone who claims certainty in either direction. What I can say is that the pattern-matching is uncomfortably familiar.
Custom Models, Your Way, Powered by a Shared CIO
For many advisory firms, portfolio management creates a practical tension. Standardized models can simplify implementation and support scale, yet they may not reflect a firm's investment philosophy, tax realities, legacy holdings or preferred managers. Building every portfolio internally preserves control, but it also demands time, systems and ongoing investment oversight.
Higher Rates Test Stocks, But Growth Endures
The Federal Reserve delivered the 25-basis-point increase the markets had largely anticipated, but the overall message was somewhat more hawkish than expected. The decision was unanimous, and the new dot plot points to another rate increase this year. Four participants apparently see the possibility of raising rates at each remaining meeting, so there is clearly a meaningful hawkish contingent on the FOMC.
What Would You Do With 9 Extra Hours a Week?
Advisors outsourcing at least 20% of assets reported saving 9.1 hours per week, or approximately 473 hours annually. WisdomTree research found 90% of investors welcomed third-party model portfolios, suggesting clients may be more comfortable with outside expertise than advisors expect.
The Case for Small-Cap Investing: A Cyclical Story, Not a Broken One
Open any market commentary today and the conversation is dominated by giants. Mega-cap technology companies command outsized shares of major indexes, and the private markets tell a similar story, as we watch companies increasingly staying private well past the point where they once would have gone public.
Fed Watch: Finally, ‘Walkin’ the Walk’
The Federal Open Market Committee (FOMC) decided to raise rates by a quarter-point, bringing the new fed funds trading range to 3.75%–4.00%. The money and bond markets had been pricing in a potential rate hike at this gathering, and Warsh & Co. ultimately determined that such a move was warranted. That said, the ‘rate hike’ story does not end here.
Higher Inflation Tests Fed and Markets
The August employment report was much stronger than expected and reinforces my view that the U.S. economy remains remarkably resilient. Payrolls increased by 162,000, above every estimate, while revisions added another 55,000 jobs to the previous two months.
How to approach the market amid changing leadership
Join the investment strategists at WisdomTree for an educational webcast that explores portfolio position going into the second half of 2026.
Strong Jobs Data Raises Fed Pressure

The August employment report was much stronger than expected and reinforces my view that the U.S. economy remains remarkably resilient. Payrolls increased by 162,000, above every estimate, while revisions added another 55,000 jobs to the previous two months. The workweek increased by one-tenth of an hour, the household survey was extremely strong, and the participation rate finally moved higher.
Gold Monthly August 2026: Sentiment Turns More Positive
With recent data weakening the case for an immediate increase in rates, markets have sharply pared expectations for near-term tightening, with a hike no longer fully priced before early 2027.3 This moderation in rate-hike fears has been supportive for gold.
Following the Capital through Geopolitical Change
Geopolitical headlines can quickly move markets, but investors do not need to predict every headline to identify potential opportunity. The more useful question is what governments, businesses and consumers are doing in response to a changing strategic environment, and which companies may benefit.
Warsh Gets an A: Re-focused Fed on the Right Key Principles
Kevin Warsh’s Jackson Hole speech was notably hawkish. But I came away from the speech even more confident in Warsh and thought it was one of the best speeches I’ve heard from a Federal Reserve chair. Most importantly, Warsh is refocusing on factors missing from the Fed’s framework for years: an explicit recognition that money supply and bank credit matter for the Fed’s inflation outlook.
Markets Hold Firm as Inflation Risks Build
Markets continue to hold up remarkably well as we move through the traditionally difficult second half of August, but the risks beneath the surface have shifted. Commodity prices are rising, money growth remains stronger than I would like, and long-term interest rates are again testing important levels.
Bessent & Warsh Go Down the Jackson Hole
Without a doubt, the number-one story in the financial markets of late has been the run-up in longer-dated Treasury (UST) yields. Indeed, headlines in both traditional and social media have centered on the fact that bond yields are now at levels not seen in nearly 20 years, or the time period right before the Financial Crisis hit in 2007.
Strong Earnings Support Stocks Despite Softer Economic Data
The market continues to impress, with the S&P 500 reaching another record high despite a surprisingly weak retail sales report. I had to look twice at the numbers because the weakness was broad, including the important control group, with the previous month also revised slightly lower.
What’s Driving Treasury Yields Higher?
There’s been no summer vacation for the bond market this year. It seems there’s a new headline every day that needs to be processed and responded to. In terms of Treasuries (UST), yields at the back-end of the curve have risen in notable fashion and have resulted in rates being at levels not seen in almost twenty years in some cases.
Soft Payrolls, Strong Earnings Reinforce Bullish Outlook
The market was jolted by a much weaker-than-expected employment report, sending Treasury yields sharply lower as investors quickly reduced the odds of another Federal Reserve rate hike. At first glance, the payroll number looked alarming, particularly when combined with sizable downward revisions to prior months and unexpectedly soft wage growth.
Is the Bond Market Putting Warsh in a Corner?
While the outcome of the July FOMC meeting itself was in line with expectations, the aftermath has proven to be far more challenging for the money and bond markets, especially for longer-dated maturities, a.k.a. duration. Investors, as well as Fed Chairman Warsh, have quickly discovered something we have been highlighting about over the last few months: a lack of forward guidance can have unintended consequences.
Tax-Aware Portfolio Transitions: Why the Transition Matters as Much as the Portfolio

New clients frequently arrive with portfolios that have been built over many years, often across multiple market cycles and advisory relationships. While these portfolios may have generated strong returns, they can also contain concentrated positions, legacy holdings or allocations that no longer align with the client's objectives.
Warsh’s Communication Misstep Doesn’t Change the Bigger Picture
The market spent much of this week trying to interpret what Fed Chair Kevin Warsh meant rather than what he actually said and that was entirely avoidable. The decision to leave rates unchanged was defensible. What wasn’t defensible was Warsh’s lack of explanation.
Will June Inflation Be as Good as It Gets?
One of the most noteworthy data points during July was the June CPI report. While some moderation in price pressures was expected, the actual ‘cooling’ in inflation that was reported was greeted as a long sought after welcome development by the financial markets.
Fed Watch: Is It a Matter of When, Not If?
Once again, the Federal Open Market Committee (FOMC) decided to remain ‘on hold’, keeping the fed funds trading range at 3.50%–3.75%. Although there had been earlier conjecture in the money and bond markets the Fed may raise rates at the July gathering, that sentiment ultimately faded, and the final result was largely expected.
Rising Oil and Real Yields Test Equity Leadership
The market encountered its stiffest test in months last week as rising oil prices, higher bond yields, and renewed scrutiny of AI capital spending combined to pressure many of the year’s biggest winners. Easing tensions over the weekend have buoyed stocks. If the Strait of Hormuz was opened, I believe the market would be 5% to 10% higher.
The Big Shareholder Diluters Are Out of Vogue
As markets place a greater premium on shareholder-friendly capital allocation, companies that consistently combine buybacks with dividends may be better positioned to outperform.
Equity Takeaways from Our H2 2026 Economic & Market Outlook
The equity bull market is expected to continue through the second half of 2026, supported by resilient U.S. growth, AI investment and solid earnings.
A New ‘Warsh’ Cycle
Kevin Warsh’s early overhaul of Federal Reserve communication and policymaking suggests investors should prepare for a higher-for-longer rate environment with greater uncertainty around policy signals.
Equity Takeaways from Our H2 2026 Economic & Market Outlook
The equity bull market is expected to continue through the second half of 2026, supported by resilient U.S. growth, AI investment and solid earnings.
Cooling AI Frenzy Reveals a Healthier Bull Market
The market received encouraging inflation news last week as both the CPI and PPI came in below expectations, as inflation pressures moderate. A negative monthly CPI print effectively removed any concern about an immediate Federal Reserve rate hike.
Scouring For Non-Tech Sectors
In June we pointed out that Health Care looks cheap. Even though it has been rallying hard of late, the sector continues to trade at a 59% price-to-sales discount to the S&P 500, despite having an 18% return on equity (ROE) that is just a hair below the 19% ROE accorded the S&P 500.
Oil Stays Calm as Strong Earnings Keep Bull Market Intact
Despite renewed geopolitical tensions in the Middle East, markets continue to display remarkable resilience. Major equity averages sit within striking distance of new all-time highs while oil, perhaps the biggest surprise of the year, remains anchored in the low $70s despite renewed hostilities.
Quantum Computing Goes Mainstream: What 2 Executive Orders Mean for Investors
For investors who have been tracking this space, the signing is a continuation of a policy architecture that has been assembling with surprising speed.
Closing the Curtain on Rate Cuts
The June jobs report underscored our thesis that while the labor market remains in the 'economic plus column,' some of the prior months' increases in new hiring seemed a bit too high.
Jobs Report Masks a Still-Resilient Economy
The June employment report’s headline readout was softer than expected, but the details reinforce my view that the U.S. economy remains on a stable footing. Headline payroll growth disappointed, yet the previous two months—which had surprised to the upside—were revised lower, bringing hiring back toward a pace that is far more consistent with a mature expansion.
‘Warshing’ the Balance Sheet
There’s no doubt the most important aspect to the June FOMC meeting was the fact that policymakers kept the Fed funds rate unchanged and removed its prior easing bias. But, this was not just your normal, run-of-the-mill policy gathering. It was Kevin Warsh’s first meeting as Fed Chair and instead of being a ‘rubber stamp’ for rate cuts, as some market observers were opining, the new FOMC leader put his stamp on the Fed in a different way.
Economic Resilience, Fading Inflation Supporting Value Rotation
The sharp retreat in oil prices has dramatically altered the market narrative. Just weeks ago, investors feared a renewed inflation shock from the conflict with Iran. Instead, crude has fallen back toward pre-conflict levels, Treasury yields have declined, and markets have begun rotating aggressively away from the large tech hyperscaler, the Magnificent Seven, that dominated recently and toward more cyclical and value-oriented sectors.
Model Portfolios Are Mainstream. Now Advisors Want Personalization.
Model portfolios have helped many advisors solve for scale. The next challenge is more nuanced: how do advisors keep that scale while delivering more personalization, tax awareness and differentiated value to clients?
A ‘Warsh’ Out at the Fed
New Fed Chair Kevin Warsh is already reshaping policy communication by reducing forward guidance, questioning the dot plot’s future and emphasizing real-time data, potentially increasing Treasury market volatility.
Why the Tech Giants Are Always in the Room
On May 5, 2026, researchers from Cleveland Clinic, RIKEN, and IBM successfully simulated a 12,635-atom protein complex using quantum-centric supercomputing, a problem relevant to drug discovery that classical computing could not match at comparable speed and accuracy.
Disinflation Trend Keeps Rate Hikes Unlikely
The most important development this week was not the Federal Reserve meeting itself, but the sharp and unexpected decline in oil prices. Just days ago, many market participants expected crude to remain elevated amid ongoing tensions in the Middle East. Instead, WTI crude briefly traded with a 73 handle, only modestly above its pre-conflict levels and far below the $90-$100 range that many feared.
Glass and Light: The Infrastructure Layer of the Quantum Market Is Missing
Co-packaged optics, the technology of integrating lasers and optical components directly into network switches rather than using pluggable modules, is becoming the standard architecture for large-scale GPU clusters, and Nvidia needed to lock in supply for the buildout it is planning.
Fed Watch: The Changing of the Guard Finally Arrives
Once again, the Federal Open Market Committee (FOMC) decided to remain ‘on hold’, keeping the fed funds trading range at 3.50%-3.75%. This result was largely expected by the markets. Of course, one of the more notable aspects to this gathering was that it represented Kevin Warsh’s first official policy meeting as Fed Chairman.
The Rise of the American State-Owned Enterprise
The slippery slope never fails. Go back to the 1979 Chrysler bailout and we can find the roots of the US government’s current predilection for getting involved in stocks and bonds.
Falling Oil Prices Reinforce Bullish Outlook
As we go to press, fighting in the Mideast has escalated, sending crude higher, but stocks, in early Monday trade, have shown remarkable stability following Friday’s deep selloff.
Are Bessent’s Hands Tied?
The rise in U.S. Treasury (UST) yields, specifically the ten-year note, since late February has captured the attention of global investors in a very visible fashion. Just a couple of weeks ago, headlines were blaring that the UST 10-year yield had reached its highest level since the beginning of 2025, leaving market participants to wonder: What comes next?
Could the ‘I’ in AI Stand for Inflation?
Even if the Middle East war does find a lasting settlement, the specter of inflation appears poised to hang over the markets. Indeed, while employment data had, up until recently, been the primary focus for investors, arguably, inflation reports have now moved into the ‘leaderboard’ position.
Falling Yields Reinforce Equity Market Resilience
The market continues to demonstrate remarkable resilience. Lower oil prices, easing Treasury yields, and the relentless buildout of artificial intelligence infrastructure are still providing a favorable backdrop for risk assets.
The U.S. Government Just Became a Quantum Investor
The U.S. government’s decision to invest $2 billion directly into nine quantum-computing companies through minority equity stakes—not just grants—signals a major shift toward treating quantum as a strategic commercial industry, with potential implications for investors seeking targeted exposure through funds like the WisdomTree Quantum Computing Fund (WQTM).
Potential Iran Settlement Sends Market To Highs
Yes, we have been there before, only to be disappointed. But the market smells a real settlement to open Hormuz, and WTI oil briefly dipped below 90 for the first time in weeks. If an opening occurs, expect the market to continue its march upward, as the momentum trade gathers strength.
‘Warsh’ and Dry
I still don’t think the Fed is close to a rate hike, but for the upcoming June FOMC meeting, a shift in the language of the policy statement from an easing bias to one of a ‘balanced’ outlook seems to be the most likely scenario. However, the fed funds futures market has now fully priced in a rate hike for March 2027, a remarkable shift from its pre-war status of discounting almost three rate cuts for the same timeframe.
The Mag Seven’s Free Cash Flow Withers
Stocks’ rally off the March 30 lows has been nothing short of wild, with internal market dynamics showing some performance divergences that we haven’t seen for decades. For example, in the first 6 weeks of the rally, the S&P 500 Growth index beat the S&P 500 Low Volatility Index by more than any other 6-week window on record.
China Summit Disappointment Stresses Markets
Markets ended last week under pressure as the optimism that had been building around a potential geopolitical breakthrough faded quickly. The China summit did not deliver the progress that had been hoped for. The Boeing aircraft order was smaller than expected; there was no meaningful movement on Iran; the Taiwan issue was brought forward in a way that unsettled markets; and the hoped-for easing of tensions around the Strait of Hormuz did not materialize.
What’s ‘Under the Hood’ of Your Core Bond Position?
Typically, an investor’s traditional bond portfolio begins with a cornerstone, or core holding of some sort. From either a strategic or tactical perspective, a core fixed income position provides the investor with some ballast to help anchor any other strategies that may be included.
A Resilient Labor Market Delays Fed Cuts
Last week was very strong for the market narrative because the economic data continued to show resilience where it matters most: jobs, earnings, and investor confidence. The latest payroll report was not just stronger than expected; it showed broad private-sector strength, with government jobs actually declining and the prior month revised higher. That is an important distinction.
Powell Stays…Should the Dot Plot?
The April FOMC meeting’s four dissents and resistance to maintaining an easing bias signal a higher bar for rate cuts under incoming Chair Warsh, suggesting investors may favor Treasury floating-rate strategies to navigate a prolonged “higher-for-longer” environment.
When is 100 Not a Good Score?
While the Middle East war takes on the lion’s share of headlines, and rightfully so, there has been another development in bond-land that has gone relatively unnoticed. Indeed, one concern that crops up in the U.S. Treasury (UST) market is the potential for higher budget deficits from the already lofty current reading.
Fed Bias Shifts and Earnings Reinforce Bullish Outlook
The Federal Reserve held rates steady as expected last week, but the real story was the shift in tone inside the Committee. Three dissents in favor of moving to a neutral bias are highly unusual, and I do not recall seeing dissents on a bias in this way before.
The efficient core: How to set your portfolio up for success in today’s environment
Join the experts at WisdomTree for an educational webcast exploring how an efficient core can add diversification without compromising on the essentials.
Robust 2026-2027 Earnings Growth is a Live Probability
The stock market would love to see nothing more than the labor market holding up. Time and again, we find monetary policy having a beautiful, lagged effect in the jobless claims series. We are of the view that the cumulative 175 basis points of Fed rate cuts that hit the market in 2024 and 2025 is exactly what the labor market needs in 2026-2027. We will soon find out if manufacturing employment continued to mend in April.
Powell’s Last Stand & What Comes Next?
For the third consecutive policy gathering, the Federal Open Market Committee (FOMC) decided to remain ‘on hold,’ keeping the fed funds trading range at 3.50%–3.75%. This result was largely expected by the markets. Unfortunately for the Fed, the policymakers are in a challenging position of juggling incoming economic and inflation data as well as the uncertainties emanating from the Middle East war.
Strong Earnings with AI Boom Offset Oil Fears
Markets continue to ebb and flow with every headline out of Iran and the Strait of Hormuz, but the most important message from the markets is resilience. Earnings season is off to a very strong start, with roughly a 75% beat rate, and the AI investment cycle continues to provide a powerful tailwind for equities.
Markets in Context: Noise vs. Fundamentals
Markets are being pulled in multiple directions. Geopolitical tensions, questions around Federal Reserve policy and the rapid rise of artificial intelligence are all competing for investor attention.
Peace Setback, but Liquidity and War Spending Lift Equities
Clearly the path to peace is not as easy as it looked last Friday when the easing in Middle East tensions, the reopening of the Strait of Hormuz to commodity flows, and the sharp retreat in oil prices calmed fears on the most immediate macro threat to equities.
Inflation’s First Official Debut
The Middle East war has replaced tariff-driven inflation concerns with fears of rising energy prices feeding through the economy. On Friday, the Bureau of Labor Statistics (BLS) released its March CPI report, when markets received their first ‘official’ glimpse of how the surge in energy prices has begun to impact the U.S. inflation setting.
Weighing the Impact of the Middle East War
The war in the Middle East has brought about an elevated uncertainty quotient when examining the U.S. macro backdrop. The resultant rise in energy prices is being looked at as both a potential ‘tax on the economy’ as well as a catalyst for a near-term elevation in inflation.
Money Growth and Oil Renew Inflation Risks
The market remains remarkably resilient, but I have expressed a more cautious outlook in the near term as rising oil prices and a renewed pickup in money growth complicate the inflation outlook.
What Happens Next
Developments in the Middle East continue to be, without a doubt, taking center stage for the financial markets. However, it’s important to keep tabs on the U.S. macro-outlook, especially the labor market and inflation aspects.
Long-Term Bullish, Near-Term Cautious
The economy continues to show resilience, and the March jobs report reinforced that view. Payroll growth came in stronger than expected, prior months were not meaningfully revised away, and the unemployment rate edged lower. Wage growth eased, but the broader message was clear: the labor market remains too firm to support any near-term case for Fed easing.
Trump and the Global Chessboard
Markets often react sharply to geopolitical developments, but just as often, they overreact. Investors today are grappling with heightened global tensions, rising oil prices and uncertainty around central bank policy. The key question is whether these risks meaningfully alter the economic outlook or simply create short-term volatility.
Strait Risk and Yields Pressure Markets
Given the rise in the 10-year Treasury yield and oil prices, the case for near-term Fed cuts has weakened materially. That is the key message from this market.
About That $4 Gasoline
At the risk of leaving aside the flow-through of the crude oil price into expenses such as electricity, trucking, and so on, let’s just look at the pocketbook hit from filling up the family car specifically.
Iran Risk Rises Sharply, Fed Sees Stronger Growth, Markets Fear Oil
Faster productivity growth lifts earnings, improves the long-run fiscal arithmetic, and allows the economy to run stronger without recreating the inflation regime of 2022. Historically, markets are slow to recognize when the supply side of the economy has improved. This time should be no different. The productivity story is more durable than this week’s Iran developments, which is dominate trading over the near term.
What Tax Season Reveals About Portfolio Implementation
In practice, many advisors use SMAs alongside ETFs, not instead of them—combining the scalability of ETFs with the customization and tax management SMAs can provide.
Short-Term Oil Risk, Long-Term Market Strength
The market ended last week with a more cautious tone as rising oil and the widening Middle East conflict bring a fresh layer of uncertainty. I could see the markets experiencing a 10% correction from the recent highs. We are not anticipating a major decline for the S&P 500, but the mood has clearly changed.
One Week Later
A surprise 92k decline in February nonfarm payrolls and a rise in the unemployment rate to 4.4% signal some labor market softening, though stronger ISM manufacturing and services readings and still-low jobless claims suggest the broader U.S. growth backdrop remains intact.
Don’t Take All the Credit
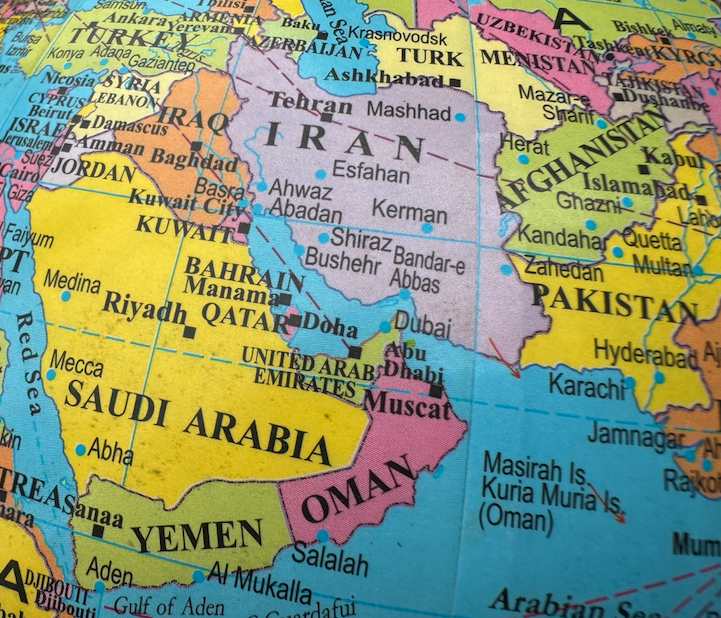
Prior to the conflict in the Middle East, the U.S. financial markets were being confronted with headlines and attendant concerns surrounding the credit markets.
Lack of Progress in Iran Triggers Oil Spike, Raises Correction Risk
Markets face a complicated mix of signals. The payroll report came in dramatically weaker than expected, several standard deviations below forecasts, and prior months were revised downward. Taken together, the last two months essentially show zero payroll growth.
The Case for Local Currency and Active Management in a Softening Dollar Environment
For over a decade, the narrative surrounding emerging market (EM) debt has been dominated by a single, overpowering force: the United States Dollar. As the greenback surged from the mid-2010s through the early 2020s, investors seeking yield in emerging markets largely sought shelter in "hard currency" debt—bonds issued by emerging nations but denominated in U.S. dollars.
AI-Driven Productivity Offsets Job Fears
The market spent the week digesting a modestly hotter PPI print, a pullback in NVIDIA after earnings, and a move in the 10-year Treasury yield below 4 percent.
A World Without the ‘Dot Plot’?
As speculation builds around a Warsh-led Federal Reserve, the prospect of eliminating the ‘dot plot’ could mark a major shift in forward guidance—potentially increasing rate volatility and reshaping how fixed income markets price policy risk.
There is No AI Apocalypse
The recent report by Citrini Research paints a frightening future of massive AI- induced unemployment, crashing stock markets, rising default rates, and a general descent into economic chaos.
So Many Dollar Bears
After peaking above 114 in September 2022, the dollar index has spent the last several years drifting lower, touching 96 a few weeks ago before stabilizing at 97.68 as we write. Much of that move has stemmed from weakness relative to the euro specifically.
Trade Ruling Adds Uncertainty, May Boost Earnings
Fourth-quarter GDP came in at 1.4%, a sharp markdown from early estimates that were inflated by a temporary collapse in the trade deficit.
AI Anxiety Masks Broadening Equity Strength
Last week delivered exactly what the market needed on the economic data front: confirmation that inflation continues to cool while the labor market remains firmly intact. The CPI came in softer than expected, finally reflecting the long-awaited deceleration in rental costs.
Weighing in on Warsh
Kevin Warsh’s nomination for Fed Chairman initially reassured bond markets by offering a known, crisis-tested Fed veteran with a reputation as an inflation hawk, reducing uncertainty at a critical juncture for monetary policy.
Affordability & Ten-Year Treasury Yields
The mid-term elections are still more than eight months away, but that hasn’t stopped stories and headlines being posted about possible outcomes and what are perhaps the main drivers come voting day. Without a doubt, the number one issue appears to be the notion of affordability, and of course, what plans do the Republicans and Democrats have in store to address this issue.
Dow 50,000 Confirms Broadening Bull Market
Just eight years ago we were celebrating 25,000, which means equities have doubled in less than a decade. By the Rule of 72, that’s roughly a 9% annual return including dividends—nominal, yes, but still a powerful reminder that equities continue to reward patience even through extraordinary volatility, policy shocks, and repeated predictions of recession.
Fed Watch: Can I Place You on Hold?
As was widely expected, the Federal Open Market Committee decided to pause their rate cuts at the January meeting, keeping the fed funds trading range at 3.50%–3.75%. For those keeping track, the Fed had lowered ‘the funds rate’ by 75 basis points (bps) during the final three FOMC meetings of 2025.
The Primary Rationale for the Gold Bull’s Run is Persistent Apathy
The near-perfect timing of gold breaking through $5,000 while silver sliced through $100 has grabbed the market’s attention.
Another Shutdown? Markets Digest January Noise
The key point is that nothing in the incoming data since December has undermined the Fed’s prior message. The economy remains strong, jobless claims are hovering near 200,000, and recession fears continue to recede.
Markets Absorb Inflation Noise as Rotation Broadens
Markets pushed to new highs again last week as investors looked past headline inflation noise and focused on improving breadth beneath the surface.
What Aren’t the Markets Considering for 2026?
While the breaking news regarding the Fed receiving subpoenas from the Department of Justice will no doubt garner the lion’s share of Fed-related headlines in the days and weeks ahead, we wanted to roll the clock back and delve into what the markets should be looking at in terms of upcoming traditional monetary policy decisions.
Productivity Surprise Supports 2026 Setup
Last week delivered some of the more surprising macro data I’ve seen in years: very slow job growth, but stable unemployment, and a sudden surge in output that materially lifts the outlook for earnings heading into 2026.
Market Momentum Holds in 2026 as January Risks Loom
The market enters 2026 on a fundamentally solid footing, even if the year-end trading days were choppier than the traditional year-end rallies we often see. Economic momentum exiting 2025 was strong.
The Answer to the Curve Steepener: Active/Passive Barbell
As we get ready to close out 2025, one stand-out trend in the U.S. Treasury (UST) market has been the steepening of the yield curve. The question now is whether this trend will continue into 2026, and if it does, how should investors position their bond portfolios?
About the “Weakening” Labor Market: Are You Sure?
We guess if you say something enough, a lot of people will start to believe it. The current refrain is that the labor market is cold, weak, struggling. A Google search for “labor market” is eye opening. The first five headlines use the words ‘weakened,’ ‘troubling,’ ‘risky,’ ‘slowing,’ and ‘warning signs.’
Cooling CPI and Resilient Growth Support Stocks
The market’s big “aha” moment last week was a CPI print that came in meaningfully cooler than expected, followed immediately by the usual chorus that it must be “distorted.”
The Fed's Silent Dissenters
While only two official dissenters opposed the December rate cut, dot-plot projections reveal that six Fed members, including four “silent dissenters,” were against easing, signaling deeper division within the Fed than headlines suggest.
What the December FOMC Meeting Means for 2026
Join the experts at WisdomTree for an educational webcast covering the biggest takeaways from the final FOMC meeting of 2025 and how to set yourself up for success in 2026.
Fed Signals A Dovish Tilt and Market Rotation
The Federal Reserve delivered a "dovish version of the hawkish cut," confirmed by the market's rally, new equity highs, and subtle shifts in leadership. The surprising effective end of Quantitative Tightening and a softening inflation framework underscore a clear turn toward accommodation and ample market liquidity.
Fed Set For Hawkish Cut As Labor Data Baffle
The first full week of the holiday shopping season confirmed what I was looking for: consumers are still spending, and they are not being spooked by tariffs or headlines. Black Friday sales were solid, and the weekend into Cyber Monday largely matched expectations.
The Problem with “Quantum Supremacy”
The field of quantum computing has shifted its focus from the short-lived concept of "quantum supremacy" to a more measurable goal: quantum advantage, which emphasizes reproducible, domain-specific results that verifiably outperform classical systems.
India: The Reset That Strengthened the Case
After a difficult 12 months, India's equity story is quietly regaining its rhythm. Valuations that once looked stretched have compressed to more defensible levels, policy continuity after the 2024 election has reassured markets and the long-term growth engine, powered by demographics, digital infrastructure and industrial reshoring, remains intact.
Black Friday Shifts As Rates And Tech Reprice
The recent Thanksgiving week provided a crucial snapshot of the changing economy, highlighted by a shift in holiday shopping to early online sales and a significant drop in the 10-year Treasury yield below 4%.
The Mag 7 Has a Capital Expenditure Problem
This article questions if the high valuation multiples are justified, arguing that investors will soon need to see actual cash flow results from this massive CapEx bonanza.This aggressive spending has caused their collective free cash flow growth to turn negative, raising concerns since stock valuation is based on future free cash flow.
Fed Uncertain as AI Capex Jitters Shakeout Speculation
Markets traded with an unusual mix of strong micro data and fragile macro sentiment last week and nowhere was that clearer than the reaction to Nvidia’s excellent earnings. The fundamentals showed strong demand, a robust product cycle, and clean forward guidance—yet the stock slumped after an early surge.
A House Divided?
With the federal government shutdown now over, until the end of January at a minimum, the money and bond markets have turned their attention back to the Fed. Specifically, the conjecture is centered on whether another rate cut will be forthcoming at the December 10 FOMC meeting.
Fed Hawkishness Misreads Inflation; Stay Ready to Buy
Markets wobbled as Washington’s shutdown drama ended, but I don’t view last week’s pullback as the start of a bear market. The Dow just printed fresh highs, breadth rotated toward quality and defensive stocks, and the weakness centered on AI-linked capex stories repricing risks associated with the capex buildouts.
Could the End of QT Lead to a New Round of QE?
The Fed can turn QE back on like they did in the latter part of 2019, most likely by buying T-bills. It is important to note that this would be purely a technical mechanism for the funding markets and not a dual mandate monetary policy consideration.
How to Approach Today’s Unique Late-Cycle Market
Join the experts at WisdomTree for an in-depth look at the broader macroeconomic picture and a product due diligence session covering practical strategies for dealing with the challenges ahead
Economy Holding In Amid Shutdown and Mixed Labor Signals
Markets are balancing this risk against the belief that the impasse will resolve soon, with short‐term “betting markets” still implying only a modest probability of prolonged gridlock ahead of the Thanksgiving travel week.
Want to Go Long Duration? Not Recommended at This Time
The age-old question in fixed income is when should I go long duration? Over the last two years, this has been an ongoing query for investors. More recently, with the Federal Reserve resuming rate cuts, it has come back on the front burner for sure.
Deal With It
There is (another) framework for a deal with China. That is a positive for risk markets. There is increasing evidence of waning tariff effects on company earnings and outlooks. That is a positive for risk markets. The interaction of the two is by far the most intriguing.
Powell Leaves Questions on Further Cuts
The Halloween week Fed meeting was more trick than treat for bonds with only a mild and temporary scare for stocks. As soon as Chair Powell signaled the next cut is “not a foregone conclusion – far from it!,” the Dow swooned before recovering about half the drop, while the 10-year drifted higher.
Unlocking Opportunities in the U.S. & Beyond
Join the experts at WisdomTree for an educational webcast that explores the current realities of the market, looks at where equity opportunities could emerge, and unpacks how to position fixed income portfolios as rates change.
“Political Clarity” is Pushing Japan Higher
Part of the reason behind Japanese stocks’ discount to the U.S. is the profitability gap; the U.S. has a Return on Equity (ROE) of 18.3%, while Japan’s broad market has yet to break above 10% on that measure (though some forecasters believe Japan will get its act together).
Earnings Strength Trumps Tariffs, Supports Rally
Energy and commodities are not flashing red. Oil ticked up from depressed levels amid new sanctions on certain Russian producers, but on a multi-month basis crude is still lower, and the broader Bloomberg-style commodity basket has been roughly flat over six to nine months.
What If: The Other Side of the Trade
Up to now, the Federal Reserve and the bond market have been operating under the assumption that the employment setting has been cooling in a somewhat visible fashion. In fact, recent comments from Powell & Co. underscore how the employment aspect of their dual mandate is where the greater risk may lie.
Bitcoin, Gold and the Hard-Money Renaissance: A Practical Playbook for Allocators
The most useful conversations about crypto don't start with block times or cryptography; they start with the monetary system. When money supply compounds and confidence in policy waxes and wanes, investors may reach for hard assets—tangible, scarce resources with intrinsic use value whose supply is difficult or costly to expand.
Credit Jitters Seem Overblown, But Fed Cut Nears
The 10-year Treasury briefly tested 4% and slipped just below, exactly what you’d expect when credit jitters boost demand for safe collateral. Real yields eased as well, consistent with a modest risk-off bid. Treasuries remain the cleanest hedge when credit fears pop, and that relationship asserted itself again last week.
The Macro Backdrop
There is little question that the key economic storyline of Q3 was the fact that new job creation was not anywhere near as solid as the markets and, perhaps more importantly, the Fed believed.
Narrowing the Short List for Fed Chair
As the calendar has now turned squarely into Q4, the sweepstakes for who will be nominated as next Chair of the Federal Reserve will no doubt increase.
The Fed’s Balancing Act
The financial markets have been laser-focused on upcoming policy decisions from the Fed, and rightfully so. Following the resumption of the current rate cut cycle, investors have been wondering what exactly this second phase will ultimately look like.
Thinking about income allocations in today’s environment
Join the experts at WisdomTree for a product due diligence session focused on their active-passive barbell approach to income.
Rare Earths Blowup: Prelude to a Final Deal?
Trump’s threat to impose 100% tariffs roiled markets Friday, and clearly, if implemented, would send stocks much lower. But this may also be the last salvo before a final deal is worked out.
Jensen Huang and the Billion-Fold Future of Intelligence
NVIDIA’s $100 billion partnership with OpenAI signals a paradigm shift, as demand for AI compute infrastructure surges beyond even the boldest forecasts.
“Flying Blind” in the Shutdown?
With official economic data on pause during the government shutdown, investors are left with limited visibility. Kevin Flanagan explains how markets are leaning on private sources and Fed signals to fill the gap.
Fed Cut In Sight As Inflation Cools
Markets digested a quiet jobs Friday without the official payrolls report, but the signal from the other indicators was clear enough: the labor market is slowing at the margin but not falling off a cliff.
The Economy is On Firmer Ground Than Some Suspect
Market sentiment has come a long way since the Tariff Tantrum. Earlier this year, the VIX volatility index shot up into the 60s, a fear level previously seen in such episodes as the October 1987 crash and during 2008’s rolling bank insolvencies.
Inflation Steady as Q4 Becomes Tariff Test
Inflation gave markets exactly what they wanted last week—no surprises.
Is the U.S. Dollar at a Crossroads?
In 2025, the U.S. dollar's image of unassailable strength is being rigorously questioned. The U.S. government budget deficit remains stubbornly elevated, hovering just north of 6% of gross domestic product (GDP), and the debt-to-
Two More Cuts Anticipated
Stocks and bonds staged a roller coaster on Fed day but finished essentially where they began—an apt metaphor for a market digesting a quarter-point cut, a split dot-plot, and a Chair intent on starting an easing cycle without declaring victory.
Uncertainty abounds - how can you adjust your portfolio?
Join the thought leaders at WisdomTree for an educational webcast exploring why what worked yesterday might not work going forward and how you can best prepare for today’s environment.
Fed Watch: Will It Be Déjà vu All Over Again?
Although the Fed does focus on its dual mandate of employment and inflation, there is no question that the primary focus right now is on the employment side of the equation, especially given the recent stalling out in new job creation.
When Will the Treasury Yield Curve Normalize?
One question we’ve been fielding quite a bit of late is what do you think the Treasury (UST) yield curve will do?
Dot Plot To Set the Tone
Last week’s data sharpened the focus on the pivotal Fed meeting this week. I expect a 25-basis point cut, with real potential for dissents on both sides. Markets are actively gaming out a larger move, but the bar for 50 is still high and would likely require a notably weak retail sales print.
Margins, Mid-Caps and Market Resilience
In a recent LinkedIn newsletter, we highlighted how mid-caps have historically delivered a compelling mix of growth and resilience, the "sweet spot" between innovation and maturity.
Treasury Yields: How Low Can We Go?
It’s no understatement to say this could have been the most anticipated jobs report in quite some time.
From Gray Areas to Green Lights: U.S. Digital Assets Enter the Mainstream
This summer has been a big one for digital assets in the U.S., with major policy steps moving forward in Washington. The White House has been clear that the goal is to strengthen American leadership in digital financial technology, and the bills and executive actions we've seen over the past two months all fit under that theme.
Cuts Are Coming: A Tailwind for Stocks
The market got exactly what it needed last week: confirmation that the economy is slowing—not collapsing—and that the Federal Reserve has the green light to start cutting rates. Payroll gains softened, manufacturing remains weak, and broader job slack is showing up with U-6 underemployment rising to 8.1%.
What Will Light a Fire under Small Caps?
The house of pain continues with small caps, at least on a relative basis. Year-to-date, the S&P 600 index has posted a 3.0% gain, so it's not like money is being burned. But still, even the Bloomberg Aggregate Bond index is up 4.9% YTD and the S&P 500 is up 10.9%.
Share Buybacks are Full Steam Ahead
Nvidia made a splash last week, or maybe an anti-splash, when it reported earnings and stated an intention to buy back $60 billion in stock.
Waiting on Walmart: One Retailer, Many Signals
While investors often look to the Federal Reserve for macroeconomic signals, Walmart’s earnings may offer even more insight. As a barometer of consumer behavior, pricing trends and tariff impacts, Walmart is a must-watch for anyone trying to understand the real-time U.S. economy.
Powell Pivot Clears Path for Rate Cuts
Chair Powell’s speech at Jackson Hole was a proper and long overdue pivot—and the markets immediately rejoiced. This was the dovish signal investors had been hoping for, and even stronger than I expected Powell to deliver.
Steeper Curves Ahead
Following the softer-than-expected July jobs report, the money and bond markets have fully embraced the narrative that a Fed rate cut will be coming at the September FOMC meeting.
All Eyes on Jackson Hole
We received a slew of economic data this past week, but the true market mover lies ahead this Friday: Chair Powell’s upcoming Jackson Hole address.
India’s Headlines Got Worse. The Investment Case Got Better.
Despite headline noise from U.S. tariffs and mixed earnings, India’s structural growth pillars—credit expansion, services exports and infrastructure delivery—remain firmly intact in 2025.
Time to Find Out: What Tariffs, Earnings and the Fed Are Really Telling Us
Sam Rines explains why it's time to find out what really drives returns in a shifting macro environment.
September Rate Cut Looms as Fed Doves Gain Sway
The first full week of August offered a concise lesson in how quickly the policy calculus can shift when both politics and data align. Equity markets wobbled after reports that Governor Christopher Waller, not Kevin Warsh, is now the front runner for the next Fed chair.
A Silver Lining of Dollar Weakness? Potential Earnings Growth
2025 has been historically turbulent for the dollar, with declines of a magnitude last observed during the global financial crisis
Reform the Fed and Bring Back the Funds Market
As the Federal Reserve (Fed) conducts its quinquennial review of monetary policy, it must recognize the severe shortcomings of its current policy framework.
Friday’s Employment Bombshell
Friday’s employment report produced the greatest downward revision in jobs in over half a century (excluding COVID), This is my interpretation of the fallout:
Some 2021 References Fit. Others Do Not
It happened quickly. One minute, the focus was on the furious nature of stocks’ rebound off the April 8 lows. The next minute you start hearing strategists, including ourselves, making references to 2021.
Fed Watch: See You in September?
For the fifth meeting in a row, the Federal Open Market Committee (FOMC) decided to keep rates unchanged, leaving the Fed Funds trading range at 4.25%–4.50%.
Surprisingly Positive Tariffs
With August tariff extensions looming, several major companies are now guiding for reduced tariff impacts, a shift that has helped boost market sentiment this earnings season.
Bitcoin and Gold: Three Model Forecasts for 2030 and Beyond
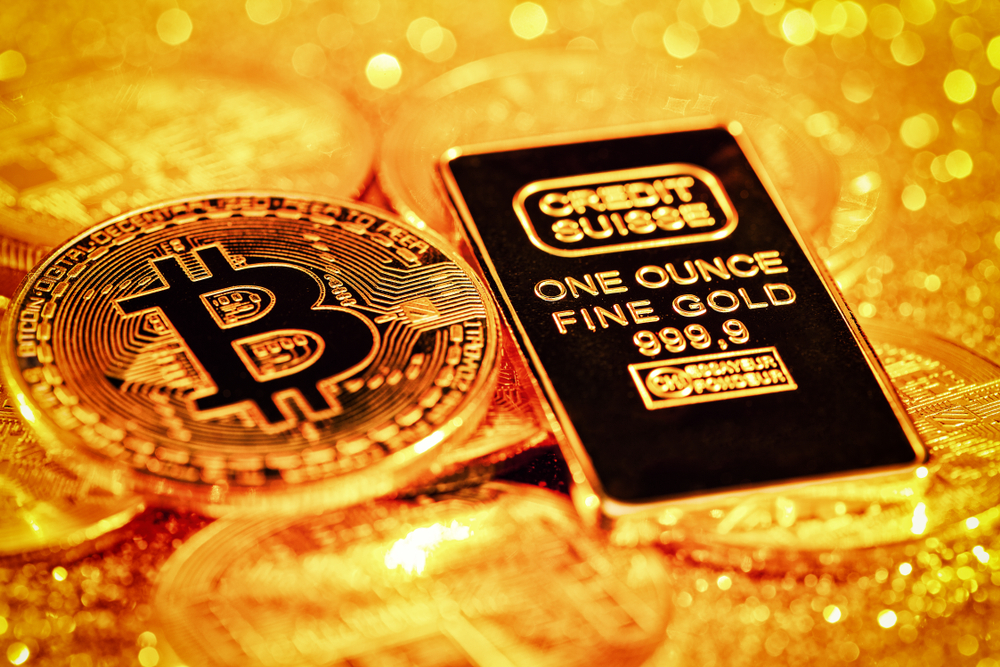
With inflation proving to be sticky, sovereign debt burdens escalating, and trust in institutions coming under scrutiny, investors are reassessing the role that hard assets play in protecting and preserving long-term purchasing power.
Corporate Guidance Key as Tariffs Threats Resurface
Markets continued their strong run last week before pulling back slightly as a flurry of tariff rhetoric hit the wires. It’s important to understand markets are rallying because they assume these tariff threats are more political posturing than lasting economic policy.
No Rate Cut for You…At Least Not Yet
One of the more storied headlines this year has been President Trump’s disappointment with the Fed for not cutting rates. We should all know by now that the President cannot fire a Fed Chair simply because he/she is not lowering interest rates to their liking.
At the Midway Point: Returning to the Fundamentals
Liberation Day seems like a lifetime ago. But the 90-day pause is almost over, and—thus far—there are few deals that have been consummated.
Jobs Report Better Than Feared
The headline employment figure came in stronger than expected and better than feared following the weak ADP report, but the details were far from a blockbuster.
Prevailing Skepticism Means Rally Has More Room
Markets notched fresh all-time highs on Friday with a positive tone and geopolitical outlook. Swift retreat in oil back to pre-strike levels, combined with friendlier NATO negotiations and de-escalated fighting in Iran restored risk appetite.
ETFs Are Evolving—Is Your Portfolio Strategy Keeping Up?
In a recent newsletter, we explored the explosive growth of ETFs and the implications for portfolio construction. In this follow-up blog post, Lauren and I wanted to take that conversation a step further—diving deeper into how advisors can navigate the ever-expanding ETF universe while staying true to their investment philosophy.
Why More Advisors than Ever are Personalizing Portfolios with Tax-Efficient SMAs
As the advisory landscape continues to evolve, one theme is increasingly clear: advisors need more flexibility to meet the diverse and growing expectations of their clients.
Understanding the Primary and Secondary Markets in ETFs
ETFs have surged in popularity thanks to their transparency, low costs and tax efficiency. But behind the scenes, a unique dual-market system powers their liquidity and accessibility.
A Sentiment Shift Favors Dollar Bulls
It wasn’t too long ago that you could confidently proclaim that most of the Street was ebullient, maybe even wildly so, with respect to the greenback’s prospects.
Markets Taking U.S. Strike Well
The U.S. strike on Iran over the weekend has added a modest premium to oil, and in the Sunday evening market, stocks opened only slightly lower. Any resolution to the crisis could send stocks to new all-time highs.
Fed Watch: In No Hurry
For the fourth meeting in a row, the Federal Open Market Committee (FOMC) decided to keep rates unchanged, leaving the Fed Funds trading range at 4.25%–4.50%.
A Goldilocks Inflation Moment, Tariffs and All
Despite consumer fears of 1970s-style inflation, actual CPI has cooled to just 2.4%. Jeff Weniger makes the case that we may be living in a Goldilocks scenario, where price trends align with a stable and balanced economic environment.
Muted Market Response to Iran Attacks
This week’s market resilience in the face of rising geopolitical tensions underscores an important structural shift. The Israeli strikes and broader Middle East dynamics, while concerning, sparked only a modest reaction—a far cry from the volatility such events triggered in past decades.
The Compute Capital Supercycle: AI’s Silent Infrastructure Revolution
In the history of technological progress, there's often a critical misreading. We think the leap is in the product—the engine, the chip, the app.
The More Things Change, the More They Stay the Same
In the current land of uncertainty the markets and investors find themselves in, the monthly Employment Situation report is ‘must-see TV’ and will remain that way for the foreseeable future.
The Infrastructure That Lets the Future Happen
If we lived in a world where mobile signals were visible, the sky would shimmer like a storm—layers of frequencies rolling over rooftops, crossing oceans and saturating valleys.
Jobs Report Yields Sigh of Relief
Last week’s employment report was an important stabilizer for the markets. After concerning revisions and weak ADP numbers raised recession alarms, Friday’s payrolls print calmed fears on labor market deterioration.
Trump, Powell & Rates: Tariffs On, Tariffs Off
With tariffs toggling on and off and a major tax bill still in flux, investors should brace for headline-driven volatility through July, particularly around trade and fiscal policy.
Economic Data Surprises, While China Tensions Resurface
The economic narrative took a decisive turn last week. A stunning collapse in the trade deficit suggests we could be looking at near 4% GDP growth in the second quarter—a massive upward revision from the consensus of 2%.
Gold's Safe-haven Status to Propel it to Significant New Highs
Gold reached a fresh all-time high in April, continuing its strong upward trajectory over the past six months.
Investors May Sell in May Until Japan’s JGB Problem Goes Away
Remember last July and August when the yen carry trade blew up? At the time, the central bank surprised the market by signaling a faster pace of rate hikes than expected. Investors sold foreign currency, bought back yen and sent markets into a tailspin.
Markets Absorb the Noise, Stay Constructive
Friday’s market tremor was ignited not by economic data, which brought limited new releases, but by revived political uncertainty—specifically, President Trump’s abrupt reinvigorated tariff threats.
Welcome to the End of Tasks
In 2025, AI crossed a subtle but monumental threshold: it stopped just answering questions and started executing goals.
Putting a Downgrade in Perspective
What investors thought was going to be a nice start to a weekend in May got turned around with a late Friday announcement that Moody’s had just downgraded the U.S. long-term credit rating.
The Real AI Revolution Is Accessibility
In a year dominated by multimodal marvels and reasoning breakthroughs, perhaps the most economically significant shift in AI went largely underplayed: cost collapse.
Downgrades, Debt, and Durable Optimism
After Friday’s close, Moody’s downgraded U.S. treasuries, as S&P had 14 years ago, in 2011. I criticized the downgrade then…and I do now. The government cannot technically default, as the Fed can always buy the bonds for any auction.
Are We Half-Way to a Recession?
After a brief reprieve from all the recession talk while the Fed was raising rates to decades-old high watermarks, the ‘R’ word has come back into vogue once again post-Liberation day.
Income Without the Volatility…or Credit Exposure
Our overarching theme for U.S. fixed income has been, and will continue to be, based on the premise that interest rates will stay at more historically “normal” levels, but that, within this backdrop, investors will face heightened volatility.
Aligning Your Exposures to the Evolving Landscape
Join the thought leaders at WisdomTree for a robust look at the market and unpack the insights that can help you position your portfolio for success.
Fed's Rigidity Risks Recession as Tariffs Start to Bite
The surprisingly large reduction in mutual tariffs between China and the U.S. announced early Monday morning has sent the markets flying. Trump has softened his approach dramatically and markets are expecting future deals. The base case: everyone at 10%, China at say 20% is still a jump, but at least will likely prevent a recession. Trade and tariffs remain the main focus for markets.
Buffett Steps Back, His Insights Remain
Warren Buffett opened his 60th—and final as CEO—Berkshire Hathaway annual meeting with the same understated clarity that has defined his career: "This is my 60th annual meeting... I think it'll be the best yet."
Fed Watch: Still Waiting
Once again, the Federal Open Market Committee (FOMC) decided to keep rates unchanged at today’s meeting, leaving the Fed Funds trading range at 4.25%-4.50%, keeping the level for overnight money 100 basis points (bps) below last year’s peak reading.
When Markets Shake, Advisors Steady the Ship
Market headlines may change daily, but the role of a financial advisor remains remarkably consistent: to be the calm in the storm, the strategist with a plan and—most importantly—the voice of reason when clients need it most.
Markets Betting on Tariff Relief But Impact Still Lurks
Despite negative GDP growth in Q1 and global trade tensions, markets are showing surprising resilience. Investors are betting tariffs will not bite as hard as feared earlier in April and that deals will emerge to soften the blow.
Top Lessons from Professor Siegel This April
April was a volatile and policy-sensitive month in the markets. Every week, my colleagues and I were joined by Professor Jeremy Siegel to discuss how macroeconomic data, Federal Reserve policy and the variety of tariff proposals from President Trump shaped sentiment and the investment landscape.
AI’s Great Flattening: What Happens when Everyone Is State-of-the-Art?
In the early years of the artificial intelligence (AI) race, performance benchmarks told a clear story: a handful of frontier models, developed by a few dominant labs, consistently outperformed the rest. In 2024, that changed.
The Supply Chain Has Seen This Before
First, let’s check the market action. Fortunately for stocks, the public has come around to a thesis that the sky is not falling, though there are a ton of market viewers who remain decidedly skeptical that the worst is behind us.
Markets Resilient Despite Tariff Turmoil
The markets rebounded strongly last week, holding ground despite the lingering cloud of uncertainty surrounding tariffs and trade negotiations. Importantly, while tariffs and dollar weakness are stirring short-term concerns, long-term inflation expectations remain firmly anchored, setting a strong case for the Federal Reserve to begin cutting rates.
The New Gold Story: Who’s Buying, and Why
There's a tectonic shift unfolding in global finance—subtle in appearance, but profound in implication. The traditional signposts of market anxiety—stocks, bonds, even crypto—are being bypassed in favor of something far older: gold.
Powell Downplays Progress, Risks Becoming Trump’s Scapegoat
Despite mounting evidence of disinflation and a weakening economy, Chair Powell’s tone remains too hawkish—and I believe that’s a mistake. The latest inflation readings came in soft, money supply growth continues to undershoot, and even jobless claims are inching higher.
Agentic AI: The New Frontier of Intelligence That Acts
The hype cycle around artificial intelligence (AI) often moves faster than the capabilities it touts.
The Fed Can Use the “Alphabet” if Need Be
The month of April will unfortunately go down in financial market folklore as being one of the more noteworthy on record.
Resilience or Recession? Markets on Edge
As we write this, stocks have bounced back as Trump retreated from electronic tariffs from China. Nevertheless, this was a remarkable week for markets with Trump’s tariff policy taking center stage for market stress across stocks, bonds and currencies.
Trump, Powell & Rates: The Post-Liberation Day Edition
With the financial markets still wrestling with the tariff announcements from last week, one thing is still certain: uncertainty remains an integral part of the investment landscape.
Tariff Turbulence Raises Recession Odds
Markets faced more volatility as Trump’s aggressive tariff measures injected both economic and political uncertainty into the system.
Rising Sun, Rising Wages: Japan's Market Signals New Opportunity
Compensation dynamics are commanding investor attention once more. For the first time in decades, Japan's pay increases—finalized at +5.46% in this year's shunto negotiations—have notably exceeded compensation growth rates in the United States.
The Rhythm of Style: Value vs. Growth in Developed International Markets—Part 1
Investors often debate the merits of value versus growth investing, but when it comes to developed international equities, the conversation isn't static; it moves in cycles.
Growth Stocks Lead Selloff Amid Trade Fears
Markets sold off sharply Friday and in the early Monday hours, and I do not believe inflation data was the culprit.
Not That Keynote—Jensen Style
On March 18, 2025, Jensen Huang stepped onto the stage at Nvidia's GPU Technology Conference (GTC) in San Jose with the presence of a man who knows he's about to redefine the trajectory of an industry—again. His message was clear: AI has hit an inflection point, and if you're not paying attention, you're already behind.
Trump, Powell & Rates: The Pre-April 2nd Edition
As the first quarter comes to a close, there is one word that has become the new go-to term to describe the investment backdrop: uncertainty.
A World Under Construction
The global economy is undergoing an unprecedented wave of industrial and infrastructure expansion, driving relentless demand for commodities across energy, metals and agriculture.
Fed Holds Steady as Markets Brace for Tariff Clarity

First, the market is rallying on news that the targeted tariffs that Trump is planning to introduce on April 2 may be more limited than initially feared. Let’s hope that is the case.
Big Tech's Market Reset: Why This Pullback is Different

Despite recent pullbacks, history shows that periods of market fear often present opportunities, as seen with Amazon, Apple and Nvidia in past downturns.
Fed Watch: Let’s Just Wait and See

For the second meeting in a row, the Federal Open Market Committee (FOMC) decided to keep rates unchanged, leaving the Fed Funds trading range at 4.25%–4.50%.
From the Beltway to Main St.: Certain Uncertainty

In the understatement of 2025 thus far, the headlines emanating from Washington, D.C., have been fast and furious. Whether they be tariff-related, involving federal government cuts or geopolitical in nature, there has been a headline for many facets that investors could think of.
Tariffs Shake Markets as Sentiment Plummets

This morning’s retail sales report is a bit of relief. The economy, as of the end February, is not in free fall as the control group increase of 1.0% offset the same decline in January. Nevertheless, the underlying concerns that emerged over the last few days cannot be ignored.
Discounting the D.C. Effect in the Bond Market

One thing we have seen underscored in 2025 is that the bond market can change its mind very quickly, particularly as it relates to policy emanating from Washington, D.C. Following President Trump’s election win, the dominant theme in the U.S. Treasury (UST) arena was that his Administration’s policies would lead to higher budget deficits, increasing UST supply and, ultimately, higher rates for maturities like the 10-Year yield.
Becoming Your Client’s Financial MD: A New Advisory Mindset

In today’s rapidly evolving financial landscape, advisors are expected to be more than just portfolio managers. Clients don’t just want investment recommendations—they seek a trusted partner who understands their financial needs, offers strategic guidance and provides peace of mind during turbulent times.
From AI to Infrastructure: The 10 Investment Themes Defining the Next Five Years

Global investment themes are shifting toward infrastructure, cybersecurity and energy expansion as demand outpaces supply in key sectors.
Markets Struggle for Direction as Uncertainty Mounts

Last week brought another wave of volatility to the markets, with investors grappling with mixed economic signals, geopolitical developments, and ongoing trade policy uncertainty.
Trump’s Economic Landscape: What Investors Need to Know

One month into President Donald Trump’s new term, financial markets are adjusting to a rapidly shifting economic and policy environment. Investors are watching closely as tariffs, interest rate expectations and regulatory changes take center stage.
Tariff Uncertainty Weighs on Markets as Growth Slows

While investors were fixated on inflation data Friday, the most significant surprise came from the advanced trade balance, which posted an unprecedented $37 billion deterioration
Buffett’s 2024 Vision: What Investors Can Learn from Six Decades of Letters

For more than half a century, Warren Buffett has penned annual letters that chronicled economic and market shifts while underscoring Berkshire Hathaway's steady philosophy yet ever-evolving outlooks. With Buffett's 2024 letter freshly published, we take this opportunity to contrast his latest views with the remarkable continuity of his investment philosophy.
Trump 2.0: Infrastructure Week Finally Arrives

The long-anticipated “infrastructure week” has finally arrived. This is a cornerstone of the administration’s agenda.
Leading the Financial Revolution: Senator Lummis, Bitcoin and the Future of U.S. Digital Policy
Senator Cynthia Lummis (R-WY) takes a pivotal role in shaping how America approaches cryptocurrency and blockchain technology.
Tariff Uncertainty Looms
Equities were continuing to grind higher until Friday’s selloff, as the market got caught up in weaker economic data and potential tariff changes, which could shake up earnings expectations and global trade flows.
Coming in Hot

Following the relatively solid January Employment Situation report, the market’s undivided attention, at least economic data-wise, then turned to the latest CPI reading. Indeed, with the jobs aspect of the Fed’s dual mandate clearly showing no urgency to cut rates further at this time, the question then turned to the inflation portion of the policy maker’s mission.
Public vs. Private Credit: Finding Their Lanes in 2025

Private credit has been one of the most talked-about segments in fixed income markets over the last few years.
Markets Resilient Despite Inflation Jitters, Tariff Uncertainty

This week brought a mixed bag of economic data, yet markets continue to demonstrate impressive resilience.
Strong Jobs Report, But Tariffs Take Focus

The employment report was uniformly strong except for one component: the average hours worked per week fell to the lowest level since the pandemic, which may be weather related.
Smart Savings: How AI Is Helping Companies Do More With Less

Faced with escalating labor expenses—from wages to benefits—businesses are rethinking traditional workforce expansion. Instead, they are investing in AI technologies that promise scalability, efficiency and unparalleled productivity.
When Investors Own Canada and Don’t Realize It

There weren’t too many market observers who penciled in higher tariffs on Canada than on China, but that’s where things stood, at least for a few hours, before Trump struck a deal with Prime Minister Justin Trudeau yesterday.
Trump, Powell and Rates: A Look Ahead

The first month of 2025 is now in the rearview mirror, and investors recently experienced a fortnight (14 days) of headline-making activity, ranging from President Trump taking office, the January FOMC meeting, and of course, the developments surrounding the DeepSeek news.
A Pivotal Week: Tech Shift, Fed Patience, Tariff Turbulence

What a week! Markets were rocked by a series of developments—from AI news that could reshape the tech sector, to the Fed’s policy stance, and the tariffs on Mexico, Canada, and China that could inject fresh uncertainty into global trade.
Fed Watch: A Pause That Refreshes?

For the first time since the Fed began cutting rates at their September FOMC meeting, the voting members decided to keep rates unchanged to begin 2025.
Looking Back at Equity Factors in Q4 2024 with WisdomTree

Looking back to 2024, global equity markets remained resilient despite a challenging final few weeks. U.S. equities led both annually and quarterly, buoyed by robust corporate earnings, supportive fiscal policies and market optimism following the Republicans’ red sweep in November.
From Underperformance to Opportunity: Biotech's Case for 2025

Despite continued underperformance in 2024, the biotech sector enters 2025 with a brighter outlook driven by groundbreaking innovations like mRNA cancer vaccines and CRISPR-based therapies.
Markets Resilient Amid Historic Week and Fed Meeting in Focus

Donald Trump’s second term as president came with a flurry of executive orders and his policies are rippling across the global markets.
Navigating Earnings Season: Margins for Error

As we kick off 2025, the landscape is rich with competing narratives and evolving dynamics.
Just How 'Rich' Is U.S. Credit?

When investors have been looking to allocate funds within the U.S. fixed income markets, credit has seemingly been viewed as being perhaps too “rich,” or expensive, in relative terms.
What about QT?
All of the attention when it comes to future Fed monetary policy decisions has been laser-focused on rate cuts. We would have to concur, and rightfully so. However, that doesn’t mean investors should take their eyes off the ball and not consider the Fed’s balance sheet.
Inflation Tames, Economy Gains: A Resilient Start to 2025

This past week brought promising news for the markets and the broader economy. Inflation data came in at or below expectations, while economic indicators, including housing starts and retail sales, demonstrated surprising resilience.
Titans of Tomorrow: Quantum Computing and Robotics on the Brink of Revolution

In 2025, two titans of technology stand at the forefront of innovation: quantum computing and robotics. Each offers a vision of a future transformed, where the impossible becomes achievable and industries are redefined.
The Future of AI: How NVIDIA’s Vision Is Shaping Our World

At CES 2025, Jensen Huang, CEO of NVIDIA, offered a compelling vision of AI’s future—one that combines bold technological advances with practical applications.
Economic Resilience Meets “Higher for Longer” Rates

As we kick off 2025, the economic landscape showcased a strong economy and resilient job market even as higher interest rates weigh on market sentiment. This week’s data underscore the delicate interplay between inflation expectations, real growth, and the Federal Reserve’s policy stance.
Five Alive: Where Is the Treasury 10-Year Yield Headed?

As we enter 2025, there has been a lot of conjecture about a return to the 5% threshold.


How to Drive Organic Growth: Insights From FINNY

Eden Ovadia, CEO of FINNY, joined WisdomTree’s Office Hours to share actionable growth insights for advisors.
AI Market Leaders: How Equity Performance Is Evolving among AI Innovators

The AI market has evolved significantly in the past two years, shifting from a heavy reliance on mega-cap and semiconductor dominance to a more diverse set of beneficiaries.
2025 Outlook: Moderated Returns, A Rotation Possible

Last week’s market volatility was not surprising for readers of these commentaries, as I anticipated a jarring adjustment to readouts from the Fed Dot Plot that suggested less rate cuts in 2025.
2025 Economic & Market Outlook: Turning the Page

For 2025, the financial markets will be entering a new chapter in the ever-evolving policy story. Indeed, not only will the U.S. economy be operating under a new political and attendant fiscal backdrop, but it will also be in the midst of a different monetary policy setting—rate cuts, not the after-effects of rate hikes.
Fed Watch: A 25-Basis Point Stocking Stuffer

As expected, the Fed delivered a 25-basis point rate cut at the December FOMC meeting, but what comes next is far from clear. Kevin Flanagan explains why future rate moves depend on shifting economic signals and why the Fed’s definition of “neutral” may be evolving.
Surging Tech Stocks, a Hawkish Fed Cut, and Regulatory Shifts

Last week’s market narrative was defined by yet another extraordinary surge in tech stocks, inflation developments generally aligning with expectations, and anticipation of the upcoming Federal Reserve meeting.
Over-Exuberant Positioning for a December Rally
Last week we processed robust economic data and growing clarity on Federal Reserve policy, instilling a consensus view for a strong market that is now well reflected in positioning.
When Will the “Bill” Come Due?
A couple of weeks ago, we wrote about how the deficit had come back into focus for the U.S. financial markets.
Opportunities in Biotechnology Will Follow Advancements in the Science

The WisdomTree BioRevolution Fund (WDNA) is showing signs of recovery, reflecting renewed investor confidence in biotechnology innovation.
Economic Resilience Continues to Impact Rate Outlook

This week’s data and market momentum solidified the case for a resilient U.S. economy, defying concerns of an imminent slowdown. Initial jobless claims dropped to a five-month low, reinforcing the strength of the labor market, while GDP growth projections hover around an impressive 2.5%.
Japan Needs M&A to Change the Vibe

To judge by the action in some foreign markets, Donald Trump’s election is pricing in economic winter.
Economic Strength Drives Jump in Long-Term Rates

Last week showcased the complexities driving markets and the economy, with inflation data, Federal Reserve commentary, and political developments at the forefront. While inflation metrics in the CPI came in as expected, the PPI surprised on the higher side, pushing up estimates for the Fed's preferred PCE inflation gauge.
How to Approach Today’s New Rate Regime
The macroeconomic overview presents ambiguity. In the face of U.S. elections, falling rates, and a host of trends that could shape the market, investors need to find a smart approach.


A Closer Look at the Budget Deficit

While the primary focus for the financial markets has been on the continued resilient U.S. economy and what the current Fed rate cut cycle will ultimately look like, there has been another topic that has been making the rounds in the bond arena: the budget deficit.
Jobs Report Signals Another Fed Cut This Week

Last week's jobs report hit a "sweet spot" for the markets, confirming enough economic cooling to signal potential Fed rate cuts without yet sparking fears of a recession. I expect a 25-basis-point cut from the Fed this week and Powell may set us up for a data-dependent pause in December.
2024 Economic & Market Outlook: The Final Stretch
Here we are, another calendar quarter down with one more to go in 2024, and investors have yet to see a “hard landing” emerge.
Resilience Persists Amid Rate, Election Uncertainty

This week’s economic indicators continue to reflect a resilient U.S. economy despite the ongoing pressure from higher interest rates. Jobless claims dropped to 227,000, indicating a steady labor market. Durable goods orders came in strong, aligning with estimates, and GDP growth for Q3 is expected to come in between 3% and 3.25%, a robust figure by most standards.
The Race to Fiscal and Monetary Stimulus

The U.S. election outcome is anyone’s guess, so let’s try to game out the winners and losers from the candidates’ major policy proposals.
Strong Retail Sales and Rising Yields Signal Resilience

The latest economic data reveals a resilient economy, led by strong retail sales and a surprising drop in jobless claims. Despite some weakness in manufacturing, industrial production, and housing, overall economic strength is reflected in the projected third-quarter real GDP growth, expected to come in at a robust 3%—largely driven by productivity gains. This productivity led rebound is very positive and this confirms that despite tighter monetary conditions, the real economy remains strong.
Stock Surge Defies Mixed Economic Data

This past week saw a notable surge in the stock market, pushing it to all-time highs, despite mixed economic data. Inflation figures, jobless claims, and sentiment reports have been uneven, but markets remain resilient, with the VIX hovering around 20—a sign that fear persists among investors.
Some Best Practices for Trading ETFs: Seeking to Maximize Your Investment Efficiency

Exchange-traded funds (ETFs) have grown in popularity as one of the most flexible and accessible investment vehicles available today. Offering a blend of stock-like liquidity and mutual fund-like diversification, ETFs can serve as a core component in the portfolios of both novice and experienced investors
It’s the Economy…

The Fed’s “recalibration” of monetary policy is more than just about shifting to rate cuts. It also involves where the policy maker is now placing its greater emphasis on setting the course for easing in the future. Rather than inflation being the primary driver in the decision-making process, labor market activity has now taken center stage, and with that, one could argue, for the Fed, it’s now about the economy.
Rising Productivity Shows Economy Remains Resilient

The jobs report closed last week with robust read outs of an official number that beat economist expectations. Below the surface, however, hours worked fell to levels often associated with recessions. This juxtaposition of more workers clocking fewer hours suggests that while employment figures are up, the quantity of work didn’t expand much.
Navigating High-Yield Bonds: Opportunities, Risks and Fallen Angels

Over the past several years, high-yield bonds have delivered impressive returns, outperforming most other sectors of the fixed income market.
Money Supply Growth Eases Hard Landing Fears

The M2 money supply growth rate in the U.S. accelerated, marking the first time the monthly change exceeded a 5% annualized rate after several months of more moderate increases. A 5% money supply growth is a desirable target, as it reflects 2-3% growth in the economy with 2% inflation. Thus, the uptick in money growth is reassuring and supports the possibility that we will avert a hard landing for the economy.
The Appeal of Agency Mortgage-Backed Securities in a Shifting Economic Landscape

While agency mortgage-backed securities offer compelling valuations, not every mortgage is created equally.


The advisor’s guide to customizable portfolios
Join the thought leaders at WisdomTree for an overview of their Portfolio Solutions platform and how advisors leverage WisdomTree’s investment expertise.
Understanding the Potential Effects of Tax Policy on Corporate Earnings
Corporate tax rate policy is a routine hot-button issue during every presidential election cycle, and this year’s campaign is no different.
Fed Watch: “Cut” to the Chase
After much anticipation, the Fed finally delivered a rate cut at the September FOMC meeting. The amount had been the subject of a great deal of speculation of late, and the voting members decided on a half-point reduction to kick off this easing cycle, bringing the new Fed Funds trading range down to 4.75%–5%.
Market Strength as Rate Cuts Loom

The markets closed quite strong last week and were approaching all-time highs again for the S&P 500. The most recent Presidential debate shifted the odds markets, as Harris became a 55-45 favorite on the betting site PredictIt and a very slight favorite on Polymarket. It is positive for the risk markets which did not pull back with Harris gaining strength.
Positioning for a Small-Cap Market Rotation in Our Model Portfolios

Due to balance sheet concerns, the higher-for-longer interest rate environment has been a significant headwind for the relative performance of U.S. small-cap equities.
What’s Hot: Nvidia Earnings, What’s Not: Investor Reactions

Nvidia’s strong earnings exceeded expectations, but the stock fell as investors recalibrated their expectations given its high valuation.
The Fed’s “Balancing” Act

Post-Jackson Hole and now post-jobs report, the markets can settle in for a rate cut at next week’s FOMC meeting.
The Case for Bold Fed Rate Cuts
Last week’s big day in the markets and for the economy was on Friday. I characterized the jobs report as being weakish—not disastrous but certainly not strong. The payroll report came in a bit short of expectations with weak lowered revisions to past reports, and although the unemployment rate adjustment was expected, the U-6 unemployment rate, a broader measure of labor underutilization, continued to rise indicating underlying weakness in the job market.
Inflation Now Taking a Back Seat

With Labor Day now in the rearview mirror, the money and bond markets will no doubt become laser focused on the September FOMC meeting. Yes, Fed Chair Powell telegraphed that a rate cut is forthcoming, but he also emphasized how monetary policy is still data dependent.
A Careful Recalibration Needed

This week’s data reflects the resilience of the U.S. economy. Currently, the economy is holding steady with jobless claims in the 230,000 range and recent inflation data showing stability. Friday’s inflation report was essentially at expectations and indicates that the Federal Reserve (Fed) will make a rate cut of at least 25 basis points (bps) at the September meeting. Whether the cut is 25 or 50 will depend mostly on this week’s employment report.
Navigating Earnings Season: Tailwinds of Tomorrow

With his Jackson Hole speech, Federal Reserve Chair Jerome Powell all but promised rate cuts were coming. That’s cool. But it is why that matters.
There’s Another New Carry Trade in Town

Is the Japanese yen carry trade back on? Tough question. We think it is, now that the Bank of Japan has toned down its hawkish rhetoric. More on that later. Still, even if we are wrong, the reality is that the market will be talking about the violent ructions of August 2024 for the rest of our careers.
Powell Did Well at Jackson Hole

Powell’s remarks in Jackson Hole were more dovish than I anticipated. Powell did not hedge; the clear direction of policy was lowering rates. The focus of the Federal Reserve’s (Fed's) narrative was shifting away from inflation risk to employment.
Where Are the AI Revenues? A Look at Mega-Cap Tech Sales Multiples

Since the release of ChatGPT, mega-cap technology companies poised to profit from AI-enhanced software tools or cloud AI-model training capabilities have seen a surge in their stock prices. Yet, many have yet to realize significant AI-driven revenue growth, let alone a substantial impact on their bottom lines.
Anticipation for Powell’s Jackson Hole Speech

I have received a lot of blowback from my recommendation that the Federal Reserve (Fed) drop the Fed Runds Rate by 150 basis points (bps) over the next several weeks. Certainly, the data has come in stronger than I (and many others) have anticipated. Particularly surprising was the drop in jobless claims, now nearer to the midpoint of my 200k to 240k range after breaching the upper limit.
The Treasury Rally Ticket Needs to Be Validated

The recent U.S. Treasury yield rally is compared to a similar rally in Q4 2023, driven by expectations of a shift in Federal Reserve policy.
Cutting Rates Without the Fed

The financial markets appear to be rather confident the Fed will finally begin its rate cutting process at the September Federal Open Market Committee meeting, at a minimum. The debate has now shifted as to what this easing cycle will ultimately look like.
Calm Markets Amid Fed Uncertainty

Last Monday morning, I tried to shake up the conversation about how far behind the curve the Federal Reserve (Fed) is currently by suggesting an inter-meeting 75 basis points (bps) cut and another 75 bps cut in September.
It's Time for the Fed to Cut Permalink

Never before in my history studying the Federal Reserve (Fed) has the Fed’s policy come into question immediately following the Fed decision.
Fed Watch: This May Be the Last Time

Once again, the Fed kept rates unchanged at the July FOMC meeting. As a result, the Fed Funds trading range remains in the 5.25%–5.50% band that was introduced exactly a year ago and still resides at a more than 20-year high watermark.
Navigating Earnings Season: From Pricing With Margin

Coming into this earnings season, one of the most intriguing questions was how well the consumer-facing companies would be able to maintain their pricing power. The new algorithm for success is a bit more complicated than “raise prices by x.”
Indications of Easing Inflationary Pressures

The economic data is coming in very good for markets. Starting with GDP, we observed a modest growth rate of around 2% in the first half of the year. While not spectacular, it’s far from recessionary conditions. This level of growth, with slight inventory accumulation, suggests a stable economic backdrop.
Looking Back at Equity Factors in Q2 2024 With WisdomTree
The second quarter began with inflation concerns causing a negative return in April, but improved inflation led to a more hopeful market in May and June, with AI and semiconductor stocks leading.
Don’t Fight the Tape. The Market Is on Small Caps.

The big story making the rounds this summer is the spike in the small-cap Russell 2000 since the release of the latest Consumer Price Index (CPI) report, which shocked the market by printing 0.0% month-over-month in June.
Bitcoin Halving and Mining Update: Mid-2024 Perspective

The bitcoin halving event in April 2024 reduced the block reward for miners, which is expected to increase bitcoin’s price.
Politics, Economy, and Tech Impacting Sentiment

This week's commentary reflects a mixture of political, economic, and technical challenges facing investors. Let’s begin with the political landscape which continues to heavily influence sentiment.
Navigating Earnings Season: The Death of Price over Volume

Welcome to the second installment of our new blog series, “Navigating Earnings Season,” where I examine the world of earnings reports from major companies — giants like JP Morgan and Pepsi, as well as niche players in various sectors.
Dominating Factors Determining the Course
The assassination attempt against former President Trump gave a bump to his odds of becoming president, as they rose from 60% to 67% on Monday morning on Predictit.org.
2024 Economic & Market Outlook: Half-Time Report

Heading into the second half of 2024, it appears the markets are no longer focusing on the odds for a recession.

When Will the Yield Curve “Un”Invert?

The UST yield curve has been inverted, but there is speculation about when it will “un-invert" and move out of negative territory.
Will the Fed Cut Rates before Reaching 2% Inflation?

The outlook for the Federal Reserve (Fed) through the first six months of 2024 has been a bit of a roller-coaster ride to say the least. While one could argue the overarching premise has been for rate cuts, it has certainly not been a smooth ride.
Time for a Rate Cut?

The employment report from last Friday, in my view, was weak. Although the headline number came in slightly above expectations, the composition was troublesome, with more than 110k jobs subtracted from the last two months and private sector jobs lagging.
Market Reacts to Presidential Debate

The presidential debate was the big story of the week and revealed a mild market preference for former President Trump. Notably, during the 90 minutes of the debate when there was no other market news, S&P 500 Futures rose 10 points, due to Trump’s business-friendly policies despite his higher-policy unpredictability.
Staking a “Claim” With Inverted Curves
Remember when an inverted yield curve used to predict recessions? Here we are about two years removed from the Treasury yield curve moving into negative territory, and the U.S. economy has yet to move into recession territory. The economy’s resilience has certainly been a surprisingly welcome development and has left many a market participant wondering what happened.
Fed Policy Implications Amid Seasonal Trends

Recent economic data slightly underperformed expectations, though nothing dramatically concerning. Jobless claims dipped just below the 240K level, which is something to watch closely. Claims above this threshold have historically been indicative of labor market weakness, which could influence Federal Reserve (Fed) policies.
Consumer Staples Need a Weak Jobs Market

Is the labor market okay? Depends on who you ask. The answer to that question should be a strong guidepost for whether you like Consumer Staples relative to the broad market.
Mixed Economic Signals: Inflation Down, Claims Up
Last week’s inflation data was very encouraging, with key indices like the Consumer Price Index and the Producer Price Index coming in below expectations. Stay up to date with the latest commentary from Professor Siegel.
The Costco Economy

The shift in consumer behavior toward buying more discretionary items is attributed to the deceleration of inflation, according to Costco management.
The Prices Don’t Feel Right: Unraveling the Inflation Perception

Inflation is not fun. And—for the past 30 years—it has largely been a non-issue for consumers. That dynamic has changed. The relevant question is whether this is something persistent and meaningful or simply a fleeting feeling.
Fed Watch: At the Midway Point

Once again, the Fed kept rates unchanged at the June FOMC meeting. As a result, the Fed Funds trading range remains in the 5.25%–5.50% band that was introduced in July last year, and still resides at a more than 20-year high-water mark.
Why India Remains Our Favorite Emerging Markets Growth Story Post-Election

India’s equity markets have experienced strong growth and momentum, with rising incomes and political stability contributing to the country’s potential for accelerated growth.
Case for Currency Hedging: Weak Currency Benefits Europe and Japan

In today’s complex global economy, currency fluctuations play a crucial role in shaping investment outcomes. While we’ve previously emphasized the importance of currency hedging in a U.S. investor’s international portfolio, there’s a subtle aspect that often goes unnoticed: the positive impact of weak currencies for Japanese and European companies and U.S. tolerance of it as a check on Chinese exports.
A Cushion Against Potential Economic Turbulence
There was a significant reaction in the bond market to the latest job growth figures, which exceeded expectations. The positive surprise led to a sharp 10 basis point rise in long bond yields. Interestingly, equity markets remained resilient in the face of this increase, suggesting a collective market relief that we are not heading toward a slowdown or recession.

Deflated Expectations

Here we are through the first five months of 2024, and you could say the more things change, the more they stay the same. What exactly do we mean, you might ask?
Awaiting a Crucial Employment Report
The story that captured all media attention last week was Donald Trump’s guilty verdict. But the Trump conviction had no effect on the markets or predicted probabilities in betting markets for him becoming president.
U.S. Credit: We’re Not in Uncharted Territory

While the money and bond markets continue their Fed-watch saga, there is one constant that we have been emphasizing for the fixed income landscape: a new rate regime.
Navigating Inflation: The FOMC’s Single Mandate

The Federal Open Market Committee is always data-dependent. But the dependency is not always the same. There are times when inflation matters more than the labor market, and times when the situation is reversed. Every regime is unique. There is never a perfect corollary to a previous experience. This time is not different.
The Bull Market is Still Intact

Economic reports from the past week provided reassurance following the previous week's disappointments. Stay up to date on the current conditions with the latest commentary from Professor Siegel.
Data Dependency = Volatility

There is no question that Fed policy remains the primary force driving the money and bond markets for the third year in a row.
Asian Stock Markets Have Become Anti-Correlated

The consensus has egg on its face with respect to Chinese stocks. It wasn’t supposed to be this way. Entering this year, one of the big concerns—and the primary reason for China’s ugly multi-year bear market—was the country’s destiny with a “4-handle” on gross domestic product (GDP) growth.
Navigating Economic Signals with Optimism
Despite the overall positive response from the markets last week, the data presented its share of ups and downs. Stay up to date on the varied indicators with the latest commentary from Professor Siegel.
A Pivotal Week for the Markets

Last week was quiet on the economic and data front. The one high frequency data indicator we did receive was jobless claims, which ticked up after a dull stretch of near constancy. The jobless claims figure came in at 231,000, which is at the higher end of my preferred range of 200-240k.
No Stag, Sticky Flation

It seems that every few years, the term “stagflation” gets floated around to describe the current and/or prospective U.S. macro landscape.
How to Approach the Shifting Rate Environment
Join the thought leaders at WisdomTree to learn all about strategies catered to meet this market moment.
A Slow but Steady Path

The markets rightly experienced a significant relief last week. Stay up to date on last week’s Fed meeting with the latest commentary from Professor Siegel.
Fed Watch: Push It Back, Push It Back, Way Back

Once again, the Fed kept rates unchanged at the May FOMC meeting. As a result, the Fed Funds trading range remains in the 5.25% to 5.50% band introduced in July 2023 and still resides at a more than 20-year high-water mark.


Is It Time to Back Away from Big Tech?

The economy, inflation, interest rates and market valuations drive the key questions facing advisors. Does the tech stock landscape mirror the boom of 1996 or the bust of 2000? What will be the impact of Meta's inaugural dividend payment? Is now the time to increase allocations to international Markets? What are the challenges faced by retail banks by not providing competitive rates and the resulting opportunity cost of holding cash? Finally, we will address the complexities advisors face in investment management, client growth, and retention.
2024 Economic & Market Outlook
As 2023 draws to a close, what will 2024 have in store for investors? It appears this Fed rate hike cycle is over and now we pivot to potential rate cuts. But not until inflation has sufficiently cooled. As we've seen before, a lot can happen in the meantime.
Our 2024 Economic & Market Outlook covers:
- Is the recession of 2023 coming in 2024?
- What the “new rate regime” means for portfolios and strategic asset allocations
- Trends and opportunities in Fixed Income and Equities
The Global Edge: What Will “Higher for Longer” Actually Mean?

As major central banks in developed economies gear up for the next phase of monetary policy, the key question on the minds of global investors is what lies ahead. A consensus among central bankers suggests that rates will continue to stay in restrictive territory, with no cuts on the horizon in the near term. Given this backdrop, the central question for the coming year is deciphering the implications of "higher for longer." This shift in monetary policy will undoubtedly have far-reaching consequences for investment strategies, requiring careful assessment and adaptation as the financial landscape evolves.
Finding Opportunities in a Challenging Fed Environment
Join the thought leaders at WisdomTree and VettaFi for a robust discussion about the challenges and opportunities available in the fixed income space.
What’s Yield Got to Do, Got to Do with It?

Today’s inflationary market landscape is fraught with risks for investors. Despite these circumstances, Scott Welch and Kevin Flanagan outline how bond investors can generate yield.
U.S. Mid-Caps Remain Attractive After July’s Rally

July offered investors a slight reprieve from the market volatility that has characterized the first half of 2022.
Be Greedy when Others Are Fearful

Let’s talk about something few people have any interest in talking about this year.
Opportunities in Asset-Backed Fixed Income

On the latest episode of the Behind the Markets podcast, we had a fascinating conversation with Don Kohn, former Federal Reserve vice chair, and Dave Goodson, Head of Securitized Fixed Income and Senior Portfolio Manager at Voya Investment Management.
Yen Weakness May Support Japan Equities

Can a weakening yen (JPY) continue to bolster Japanese equity markets?
The Nearly Unlimited Demand for Better Energy Storage

At this point, where do we honestly see ourselves on the journey to more and better energy storage solutions?
Looking for Recession Clues in All the Wrong Places?

How quickly the narrative has shifted back and forth in the money and bond markets.
A Realistic Framing of the Progress in Artificial Intelligence

Let’s face it—we love exciting announcements. Why talk about the small technical improvements of a given artificial intelligence (AI) system when you can prognosticate about the coming advent of artificial general intelligence (AGI)? However, focusing too much on AGI risks missing many incremental improvements in the space along the way.
Mid-Cap and Small-Cap Dividends Shine amid Volatility

In our third of three posts on small-cap valuations, let’s examine how focusing on dividend payers amid a volatile market backdrop has provided excess returns, with even lower valuations.

A Strategy for Volatile Markets in 2022

Investors often look for ways to enhance income, lower a portfolio’s overall expected volatility or even help manage taxable gains.
The WisdomTree Q2 2022 Asset Class and Risk Factor Review and Outlook

Regular readers of WisdomTree blogs know that we are firm believers in both asset class and risk factor diversification when building our Model Portfolios.
The WisdomTree Q2 2022 Economic and Market Outlook in 10 Charts or Less

When reviewing the current state of the global economy and investment markets, we recommend focusing on market signals and weeding out market noise.
The Stock Market Threw Its Interest Rate Rules of Thumb out the Window

Something in the market changed about a half-year ago. A dandy old “truism” that had made the rounds for ages got scrapped.
Looking Abroad for Dividend Income

Value has trounced growth this year, and high dividend companies have outperformed. Matt Wagner discusses the global dividend investment opportunity: emerging markets.
Will the Future Be Web3, Metaverse or Open Source?

“Web3” has emerged as a buzzword over the last few months.
What Lies around the Corner for Digital Assets?

Digital assets have grown exponentially in the past decade. After the recent crypto sell-off, Benjamin Dean discusses what may lie ahead in the digital assets ecosystem.
The WisdomTree Q1 2022 Economic and Market Outlook in 10 Charts or Less

When reviewing the current state of the global economy and investment markets, we recommend focusing on market signals and weeding out market noise.
The New Year Reset: The WisdomTree U.S. Value Fund

One of WisdomTree’s flagship value Funds made some notable changes at the start of the new year.
2022 Economic & Market Outlook

2021 has been a year of notable economic growth after unexpected change caused by the COVID-19 pandemic. In our Economic and Market Outlook for 2022, we lay out some of the “known unknowns” we believe could significantly affect the investing landscape...
China and India Energy: Two Countries for the Same Tale?

For India and China, 2021 is a tale of two equity markets. But when it comes to energy—particularly coal-generated electricity—the two countries are remarkably similar. Liqian Ren discusses the potential impact of this reliance on India and China’s economic growth.
Checking In on Risk Factor Diversification

This article is relevant to financial professionals who are considering offering Model Portfolios to their clients.
The Markets Continue to Rethink the 60/40 Portfolio

We believe the traditional 60/40 portfolio will face significant headwinds in meeting investor objectives as we move through this decade and the next. Against this backdrop, Scott Welch discusses how WisdomTree seeks to challenge the traditional 60/40 approach.
The Dividends of a Quality and Growth Factor Approach

