


The market’s overwhelmingly favorable reaction to President Trump’s first speech to a joint session of Congress was not necessarily surprising: President Trump veered away from the more protectionist and nationalistic tone of his inaugural address to instead deliver a more hopeful, conciliatory and unifying speech.
PIMCO

Commentary
Inflation Is Sticky, But This Isn’t 2022 All Over Again
October’s U.S. Consumer Price Index (CPI) data came in hotter than consensus expectations, delivering another disappointing inflation report for a Federal Reserve that has become increasingly vocal about its focus on price stability.
Commentary
Where to Seek Diversification From the AI Investment Theme
The U.S. midterm election results could slow the AI buildout and near-term issuance but are unlikely to materially reduce its ultimate scale or financing needs. The pace of supply may slow, but concentration risk is unlikely to dissipate, reinforcing the case for diversification into high quality securitized products and emerging markets (EM).
Commentary
Campaign Spending: The Hidden Boost Behind U.S. Consumer Resilience
Following the U.S. midterm elections, investors will naturally focus on what the results mean for fiscal policy, geopolitics, and the regulatory outlook. But there’s another more immediate way the midterms have already mattered for the economy: The campaigns themselves have provided a meaningful boost to U.S. growth.
Commentary
Commercial Real Estate: A Reset, Not a Replay
One concern raised by the recent backup in rates is whether CRE is about to relive the stress of 2023, when depressed post-pandemic office demand coincided with rising rates and a regional bank crisis, including Silicon Valley Bank and First Republic Bank. The selloff in public REITs suggests investors are repricing property values for a higher-rate world.
Commentary
Policy Options Are Available Now to Lower U.S. Mortgage Rates
Rising U.S. Treasury yields have added fresh strain to the U.S. housing market. The average 30-year mortgage rate, which generally tracks the 10-year U.S. Treasury yield plus a mortgage spread, rose to 7.5% in October 2026, according to Mortgage Bankers Association data, worsening an affordability crunch that remains a top concern among U.S. households.
Commentary
Is AI Crowding Out the Rest of the Economy?
The AI investment boom has become one of the largest sources of demand in the U.S. economy. Announced annual capital spending across large U.S. technology companies points to more than $1 trillion in desired investment, up dramatically from only a few years ago.
Commentary
The Other Side of Higher Yields
We have been arguing that the reset higher in yields has restored the dual role of bonds in multi-asset portfolios: providing attractive income while once again offering the potential for meaningful risk mitigation. This month’s tech market turbulence has provided a clear example: As equities came under pressure, U.S. Treasury yields fell amid a flight to safety, allowing duration to behave like a diversifier again.
Commentary
October Fed Meeting Preview: A Pause Is Still a Recalibration
The Federal Open Market Committee (FOMC), the policy-setting group within the U.S. Federal Reserve, meets on 27–28 October to discuss the economic outlook and appropriate monetary policy. We expect the FOMC to hold the policy rate at 3.75%–4.0% while keeping a clear tightening bias.
Commentary
Improved Optics But Unchanged Economics in Software Loans
This year, the software sector has been one of the worst-performing pockets of the leveraged loan market amid fears that AI would severely disrupt existing business models. The sector’s underperformance has also weighed on the leveraged loan asset class as a whole, given its more than 10% weight in the overall Morningstar LSTA US Leveraged Loan Index.
Commentary
The AI Investment Boom Goes Beyond America
In light of accelerating global fragmentation and geopolitical conflict, many governments and businesses are investing in resilience. That imperative has coincided with the emergence of AI, a technology that can expand the frontier of what is possible. As a result, technology security is becoming a pillar of national economic security strategy.
Commentary
Green Shoots and Legacy Risks in Direct Lending
While redemption pressure in nonlisted BDCs (funds that invest in small and midsize private U.S. businesses) has eased from its peak, it remains materially above the industry standard 5% quarterly redemption threshold. As a result, capital continues to leave the asset class, forcing managers to look to preserve liquidity, moderate deployment, and, at the margin, tighten financing conditions.
Commentary
Growth Holds, Risks Widen
As globalization recedes, governments and businesses have stronger incentives to invest in building more resilient societies and supply chains. That imperative has coincided with the emergence of artificial intelligence, creating a powerful interaction between technological innovation and economic security.
Commentary
An Oil Shock (Mostly) Like No Other
Seven months into the U.S.–Iran conflict, few historical analogues have held. The trajectory of oil prices has been consistent with previous geopolitical shocks, but the market response elsewhere has looked strikingly different. U.S. Treasury yields have moved notably higher, for example, while credit spreads have remained remarkably resilient.
Commentary
Monetary Policy Through the Lens of Financial Conditions
AI could be a transformative force for the Fed’s policy framework. Elevated investment demand – now coupled with positive wealth effects that are necessitating tighter financial conditions – could eventually give way to a positive supply impact from higher productivity growth that could allow for easier financial conditions without inflationary implications.
Commentary
Hyperscalers Are Repricing, Not Displacing (So Far)
AI-related borrowers have accounted for nearly a quarter of nonfinancial U.S. dollar (USD) supply year-to-date, yet spreads for non-AI issuers have not widened meaningfully. Instead, hyperscaler spreads have widened, suggesting the market is absorbing the AI supply shock at its source.
Commentary
The U.S. Housing Market Becomes a More Local Story
As bond yields have risen, mortgage rates are again facing upward pressure, extending the U.S. housing market's post-pandemic affordability challenges. Beyond mortgage rates, trends in wage growth, taxes, and insurance costs also continue to shape the affordability outlook.
Commentary
A Recalibration, Not a Rate-Hike Cycle
Looking ahead, markets are priced for additional hikes. And our base case is that the FOMC will likely deliver one or two more 25-bp rate hikes through this year and into early next. However, looking further out, anticipating appropriate Fed policy through a financial-conditions-targeting framework has its own limitations. Hence, a neutral rate anchor is still useful.
Commentary
AI Capex and the Limits of Crowding Out
A popular narrative for the rise in bond yields over the past few months is that the debt-funded AI capital expenditure cycle is crowding out the Treasury market. The crowding-out argument can appear compelling: AI companies are expected to continue to issue unprecedented amounts of debt at a time when Treasury supply remains elevated. Because both ultimately draw from the same pool of investor capital, yields must rise to clear the market.
Commentary
September Fed Hike May Be More Than a Risk Management Exercise
The U.S. Federal Reserve delivered on consensus expectations by raising its policy rate by 25 basis points (bps) at its September meeting.
Commentary
One AI Trade for Now, Many Trades Later
Is the AI infrastructure buildout one big trade in credit? So far, the market seems to think so. Spread dispersion – differences in borrowing costs among issuers – across the financing chain remains limited despite sharp differences in underlying risk. This contrasts with equities, where performance has become increasingly differentiated.
Commentary
Welcome Back, Balanced Portfolio

For much of the past decade and a half, investors saw little reason to favor bonds over equities. Yields were low and returns were muted, especially in passive strategies. Equities seemed to offer a much clearer path to long-term capital appreciation. For many investors, bonds were, at best, ballast: a dull but generally stable component of a broader portfolio. Then the experience of 2022 had investors questioning even that view, as areas of high quality fixed income generated equity-like losses that eroded much of the prior decade’s real return.
Commentary
How a K-Shaped Economy Affects Opportunities in Asset Based Finance
The “K-shaped” divide endures even as it evolves. Higher-income households keep benefiting from equity gains, home price appreciation, and solid earnings, while lower-income households face mounting pressure from elevated costs and tighter credit. But recent data suggest the story is becoming more nuanced.
Commentary
If Inflation Is the Problem, Why Aren't Wages?
Kevin Warsh's Jackson Hole speech struck a decidedly hawkish tone and was arguably the clearest signal yet that the Federal Reserve is actively considering additional tightening. Markets responded by raising the probability of a September hike to roughly 60% and pricing approximately 60 basis points of cumulative tightening through the middle of next year.
Commentary
U.S. Corporate Issuers Can Digest Higher Refinancing Costs
The backup in global yields since late February has reignited the debate over the potential knock-on effects for corporate borrowers, particularly through higher refinancing costs and weaker debt-servicing capacity.
Commentary
Chairman Warsh’s Jackson Hole Speech Emphasizes Price Stability
In an ambitious and much-anticipated Jackson Hole speech, Federal Reserve Chairman Kevin Warsh made the most market-moving news when he stated clearly that unless “underlying inflation is moving to our objective, clearly and at sufficient speed … we have work to do.”
Commentary
Buybacks, Market Functioning, and Treasury Predictability
Last week, the U.S. Treasury Department surprised the bond market by announcing that it would at least double selected long-end bond buybacks.
Commentary
Narrowing the Visibility Gap in Defaults
As the credit cycle ages, defaults are likely to remain front and center. But for investors evaluating private credit alongside public markets, measuring defaults is not as straightforward as it may seem.
Commentary
What’s Pushing Long-Term Bond Yields Higher?
The 30-year U.S. Treasury yield has touched roughly 5.3% in the past week, a level not seen in nearly two decades. Global counterparts in Europe, the U.K., and Japan have climbed to similar heights.
Commentary
The Key Inflation Signal for Investors
In the early weeks of Kevin Warsh’s start as chair of the U.S. Federal Reserve, there has been renewed focus on how “underlying” inflation should be measured to guide decisions on interest rates.
Commentary
Counterintuitive Labor Market Shifts Constrain Measured U.S. Wage Gains
The headline U.S. unemployment rate has been falling for several months, but a closer look at who is leaving the workforce – and who isn’t entering or returning to it – reveals why average wages are stagnating, and why labor markets aren’t a source of inflationary pressure.
Commentary
What BDC Markets Are Signaling About Private Credit Valuations
BDC bonds have recovered most of their underperformance while equities continue to lag, suggesting investors are demanding a higher risk premium to compensate for uncertainty around portfolio valuations.
Commentary
As Older Workers Retire, Labor Costs Ease
Recent trends are sending confusing signals about the health of the U.S. labor market. Since late 2025, the employment/population ratio has moved lower even as the unemployment rate has declined.
Commentary
The AI Split Between U.S. Dollar and Euro Investment Grade
The AI capital expenditure cycle remains solidly on track to eclipse the telecom boom of the late 1990s and become the largest investment cycle since the railway buildout of the 19th century in inflation-adjusted terms. T
Commentary
Underlying Inflation Gauges: Trimming Noise or Trimming Signal?
By repeatedly describing standard inflation gauges as “imperfect measures of underlying inflation,” Federal Reserve Chair Kevin Warsh has pushed a long-running technical debate into the center of the policy conversation: What is the best way to measure underlying inflation?
Commentary
Still Buying America
Just as important, the dollar and U.S. Treasuries have continued to behave like hedges in periods of broader market unrest (driven by geopolitics or other conditions). When risk assets come under pressure, Treasury yields have generally fallen, or the dollar has tended to find support.
Commentary
Geography, Geopolitics, and Gamesmanship Leave Little Room for Error in Energy Markets
Energy markets have reached a precarious moment, with the path of prices over the remainder of the year – and potentially beyond – hinging on two key questions.
Commentary
The Fed Holds Steady, But Questions Linger
The Federal Reserve left its policy rate unchanged in July, with three participants dissenting in favor of a hike. Prior to the meeting, markets had priced roughly a one-third probability of a rate hike, so the hold was dovish relative to market pricing.
Commentary
The Return of Financial Engineering – Not 2008, But Not Nothing
Leverage, ratings arbitrage, liquidity transformation, and a growing willingness to embrace complexity and illiquidity are becoming more visible across parts of the financial system.
Commentary
When Monetary Policy Surprises Stop Translating
Inflation remains above target, especially the Federal Reserve’s preferred core Personal Consumption Expenditures (PCE) inflation measure, as choppy data have challenged the view that disinflation will proceed smoothly.
Commentary
Old-Fashioned Bond Math for a New-Fashioned Fed
In the Warsh Fed's new era of two-way risk, bonds offer something rare: potential downside risk mitigation that investors get paid to hold.
Commentary
Rich Spreads, Cheap Treasuries, and an Incomplete Explanation
The relative cheapness of Treasuries versus interest rate swaps mechanically affects how corporate bond spreads are measured, but it appears to have limited influence on how corporate bond spreads actually behave.
Commentary
Fed Policymaker Comments Raise the Stakes for Inflation Data
Our baseline outlook still sees the Fed on hold through 2026 amid gradually easing price pressures. But Waller’s comments suggest that after a string of firmer Personal Consumption Expenditures (PCE) inflation prints, the Fed now places greater emphasis on responding if inflation surprises sharply to the upside or proves more persistent than expected, regardless of which factors are driving the inflation. And this raises the stakes for incoming inflation data throughout the year.
Commentary
Real Estate: From Repricing to Relevance
Investors should consider where in the capital structure they are best compensated for risk. Equity may offer income with upside potential from active asset management, whereas debt may offer income with downside mitigation.
Commentary
A Higher Bar for Earnings Season
The first wave of upgrades came after the AI hyperscalers reported, by and large, strong earnings. But most of the improvement has stemmed from the rest of the non-financials index, with analysts quadrupling their one-year aggregate EBITDA (earnings before interest, taxes, depreciation, and amortization) growth expectations, from 5% at the end of January to more than 20% as of 30 June.
Commentary
Does AI Raise or Lower Neutral Rates?
A growing share of central bankers argue that artificial intelligence will ultimately push neutral interest rates higher. Intuitively, if AI boosts productivity and lifts long-run growth, then households have less incentive to save, pushing up the real neutral rate.
Commentary
The Credit Market Lens: What BDC Redemptions and NAV Pressures Mean for Investors
A widening confidence gap in non-traded investment vehicles is testing private credit valuations, sharpening the case for manager selection and diversification beyond direct lending.
Commentary
Global Bond Diversification: Higher Yields and New Opportunities for Alpha
In a world of high starting yields and rupturing economic alliances, investors who actively diversify across regions, sectors, and currencies can be better positioned to pursue durable returns.
Commentary
Will Greater Monetary Policy Uncertainty Lead to Tighter Financial Conditions?
Kevin Warsh’s first Federal Reserve meeting as chair mattered less for the rate decision than for what he revealed about how the Fed intends to operate. Warsh signaled a shift toward less guidance and more flexibility.
Commentary
Sharpe Is Back in Emerging Markets
Emerging market (EM) fixed income's risk-adjusted profile has meaningfully improved. Sharpe ratios across EM credit and local rates have rebounded, with EM credit delivering one of the strongest risk-adjusted performances in fixed income over the past two years.
Commentary
Hawkish-Leaning Committee, Reform-Minded Chair: Warsh’s First Fed Meeting
The Federal Reserve held the policy rate steady at 3.50%–3.75% at its June meeting – an outcome that was never really in doubt. The more interesting signals came from the Summary of Economic Projections (SEP), the policy statement, and Chair Kevin Warsh’s first press conference, which may prove to be his most substantial.
Commentary
How Large Is Private Credit’s Total Addressable Market, Really?
One of the most debated topics in private credit is the size of the investment opportunity – or, in industry parlance, the total addressable market (TAM). But the way TAM is typically framed can be misleading.
Commentary
Rupture and Resilience
For more than four decades, PIMCO’s Secular Forum has provided a disciplined framework for stepping back from short-term market noise to assess the structural forces that will shape the global economy and markets over the next five years. Yet rarely has this exercise been more consequential than it has recently.
Commentary
Energy Credit Market Returns Reflect Sector Discipline
The takeaway for both HY and EM corporates is straightforward. Once oil prices are above breakeven, further moves in oil tend to matter less for credit performance.
Commentary
The Quiet Erosion Beneath U.S. Growth
The U.S. economy appears resilient, judging from key economic measures. AI-driven capex continues to power investment, support equity markets, and sustain a wealth effect that has propped up consumption. Real GDP growth remains positive. Private sector balance sheets are in generally good condition and many higher income and wealthy households have benefited from equity markets gains.
Commentary
AI Financing Needs Do Not Override Cyclical Drivers of Yield
AI is a transformative technology with both near-term and long-term implications for the economy. For investors, while the debt-funded AI buildout has the potential to become a secular driver of risk premia, we believe any such shift would only play out through a multi-year adjustment and would not override the cyclical forces that affect markets.
Commentary
Investment Discipline Amid the AI Infrastructure Boom
Businesses are racing to build the physical infrastructure that makes AI usable at scale – data centers, the graphics processing unit (GPU) hardware stack, power, and cooling.
Commentary
Supply Shocks and AI-Related Demand Blur Inflation Signals for the Fed
Recent Federal Reserve communications have turned more hawkish, reflecting concern that persistent supply-driven price pressures could begin to feed into inflation expectations. But unlike in prior cycles, today’s environment is not defined by supply shocks alone.
Commentary
The Retirement Hack Hiding Inside Most DC Plans
Many debates in defined contribution (DC) circles focus on fees, new asset classes, and ever more complex solutions. But the biggest improvement available to plan participants may come from something far simpler: how their fixed income is managed.
Commentary
Measuring What Matters in Public and Private Fixed Income
Despite the move lower late last week, U.S. Treasury yields are still holding well above recent lows and close to highs not seen in more than a year. By contrast, risk assets are firmly bid: U.S. equities have been routinely touching new historical highs, and credit spreads over Treasuries remain tight.
Commentary
AI Credit Expansion: Assessing the Micro and Macro Risks
Since the post-COVID recovery began, U.S. nonfinancial corporations have generally managed capital conservatively. They have kept credit metrics stable and, in many cases, actively improved them. That discipline was not entirely voluntary: The sharp adjustment in funding costs triggered by the Federal Reserve’s 2022–2023 rate hiking cycle raised the bar for incremental borrowing and pushed management teams toward balance sheet restraint.
Commentary
Key Takeaways From PIMCO’s Sustainable Investing Report 2025
by PIMCO, 5/22/26
Sustainable investing in fixed income has come of age. Against a backdrop of heightened geopolitical tensions, persistent economic and trade uncertainty, sustainable fixed income continued to demonstrate its appeal in 2025.
Commentary
AI, Market Power, and Diminishing Labor Share
In the past year, new models from industry leaders have continued to boost AI’s capabilities. According to various capabilities tests, Anthropic’s Mythos model has leapfrogged other AI models – including in the ability to thwart or support cyberattacks.
Commentary
What Would The Merton Model Say About AI Capital Spending?
For shareholders, the upside justifies the gamble. For bondholders, the downside is real and the upside belongs to someone else. That wedge – the classic asset substitution problem – is what credit investors are increasingly pricing, and until the re-leveraging impulse shows signs of reaching a plateau, the divergence across the capital structure is likely here to stay.
Commentary
Daily Pricing Is Not Daily Liquidity
Within private credit, attempts to increase liquidity – the ability to buy or sell an asset quickly, in size, and at prices reflecting fundamental values – are welcome developments, in our view. Yet until these efforts address the market’s inherent structural constraints, including a lack of true price discovery, they will only increase the perception of liquidity without truly improving liquidity.
Commentary
U.S. Inflation Measures Tell Two Different Stories
Something unusual is happening with U.S. inflation data. While the core Consumer Price Index (CPI) has looked relatively cool recently, core Personal Consumption Expenditures (PCE) inflation has risen sharply.
Commentary
Making Sense of a Cross-Asset Disconnect
A persistent oil shock implies higher inflation and weaker growth, but risk assets appear unfazed, with equities and credit spread performance diverging from the caution implied by government bonds.
Commentary
Fed’s Holding Pattern Continues Amid Competing Risks
Markets and observers weren’t surprised when the Federal Reserve held its policy rate steady at the April meeting. More notable, in our view, were the three dissents by voting participants who did not support keeping the implicit easing bias in the policy statement’s forward guidance language.
Commentary
Differing Signals in BDCs, and Orderly Defaults in High Yield
Sentiment toward BDCs – funds that invest in small and midsize private U.S. businesses – has improved since early March. BDC bond spreads have stabilized and outperformed the broader investment grade (IG) index, suggesting credit investors are increasingly comfortable with downside risk.
Commentary
When Geopolitics Becomes an Economic Input
Markets have long struggled to price geopolitical risk. Part of the issue is that each flare-up tends to be viewed as a one-off volatility jolt to be weathered and then faded once there is resolution.
Commentary
Higher Energy Costs, Weaker Tax Relief Squeeze U.S. Households
Even in the event that the Middle East conflict eases and shipping resumes as usual through the Strait of Hormuz, it would likely take time for the global economy to normalize after one of the largest oil supply disruptions in decades.
Commentary
Software Stuck in a Trough
Despite compositional differences – public equities generally represent larger companies with more scale, liquidity, and financial flexibility than the typically smaller, private-equity-owned issuers that dominate the software loan market – the outcome is the same: Neither market has been able to fully retrace the year-to-date sell-off in a meaningful way.
Commentary
Why the Fed Could Shrink Its Balance Sheet Again (and Markets Might Not Notice)
Late last year, the Federal Reserve ended its latest quantitative tightening (QT) program: the process by which it shrinks its balance sheet by selling securities or letting them mature without reinvestment.
Commentary
Oil Supply Shocks Don’t Age Well
The Middle East ceasefire sparked a relief rally last week as markets dialed back the risk of a deep, drawn‑out oil supply shock. Stocks have already erased much of the post-conflict drop. Bonds haven’t gotten the memo: Yields are still elevated, keeping a bit of extra term premium on the table.
Commentary
U.S. Employment Volatility Masks Structural Shift
U.S. headline employment rebounded strongly in March, posting the largest monthly gain since late 2024. The jobs rebound, which was broad-based across industries, was a welcome sign after February’s data showed a sharp decline not usually seen outside of recessions.
Commentary
A Data-Driven Look at Public Credit Liquidity
Across corporate lending markets, some investments are easier to trade and exit than others – differences that deserve particular attention today.
Commentary
A Systematic Lens on Global Equity Opportunities Within Multi-Asset Portfolios
Systematic equity investing is a way to invest in the stock market using clear rules and data, rather than guesswork or hunches. Instead of trying to pick stocks based on trends or headlines, this approach uses research, data, and technology to systematically identify opportunities across global markets.
Commentary
The Credit Market Lens: A Market Split, but for How Long?
Amid geopolitical uncertainty, dispersion across credit markets – rather than a broad risk-off move – has become the dominant investment signal.
Commentary
Layered Uncertainty: Conflict, Credit Stress, and AI
In a world of intensified uncertainty and dispersion, investing becomes less about forecasting and more about favoring more liquid, high quality assets that can be resilient across a variety of scenarios.
Commentary
Spreads May Be Converging Across Public and Private Markets, But Liquidity Is Not
Proposals to engineer secondary trading in private assets, often championed by vocal critics of public market liquidity, have gained renewed momentum. For some, enhanced tradability is viewed as a remedy to growing unease over the absence of transparent, real‑time valuation signals in private portfolios.
Commentary
Caution Takes Center Stage at the March Fed Meeting
The Federal Reserve held the policy rate steady in March at 3.5%–3.75%, a widely expected outcome as policymakers navigated an unusually complex macro backdrop.
Commentary
Middle East Conflict Clouds the Economic Outlook
The military conflict in Iran and the Middle East is curtailing the global flow of oil and natural gas. This adds notable pressure to energy prices and the near-term inflation outlook, while also raising questions about countries’ reliance on energy imports and their economic resilience.
Commentary
Private Credit’s Other Lanes Still Offer Value
Concerns about private credit have intensified in recent months. Investors are grappling with questions about weakening credit quality, stale valuations, looser underwriting, redemption risk in certain types of funds, and the impact of AI‑driven disruption.
Commentary
Tariff Ruling Drives Near-Term Uncertainty, With Potential for Longer-Term Stability
The U.S. Supreme Court on Friday invalidated tariffs that President Donald Trump had imposed under the 1977 International Emergency Economic Powers Act (IEEPA). Most of the administration’s 2025 tariffs will therefore be rolled back, and importers should eventually receive refunds.
Commentary
The AI-Driven Productivity Tide May Not Lift All Boats
In recent editions of Macro Signposts, we’ve emphasized how U.S. policy changes coinciding with the emergence of a new general-purpose technology (AI) may be accelerating adoption and diffusion of that technology – while also driving economic adjustments.
Commentary
Pricing the Known Unknowns From Japan’s Election Landslide
The historic election victory in Japan for the ruling Liberal Democratic Party has granted Prime Minister Sanae Takaichi the strongest mandate in the country’s postwar era and raised hopes of a shift toward growth-oriented policy.
Commentary
Expect the Unexpected
Barely a month into 2026, markets have already weathered multiple bouts of rolling, event‑driven volatility. Geopolitical surprises and policy pivots have triggered sharp price moves from the U.S. to Japan to Europe, from sovereign bonds to currencies to mortgages.
Commentary
Under a Warsh Fed, Expect a Thoughtful Policy Approach
President Trump has announced his intention to nominate Kevin Warsh to become the next chair of the Federal Reserve Board of Governors. We believe Warsh will be confirmed by the Senate and serve as an effective, thoughtful Fed chair. He brings intriguing ideas on ways to change and ideally improve how the Fed operates.
Commentary
Why U.S. Productivity Gains No Longer Reach Workers
Last week in our latest Cyclical Outlook, “Compounding Opportunity,” we argued that beneath the economy’s broad resilience lies a stark divergence. U.S. policy pivots combined with the surge in adoption of AI technology have created winners and losers.
Commentary
Compounding Opportunity
Following strong 2025 returns, high quality fixed income continues to offer attractive yields and global diversification at a time of stretched equity valuations and tight credit spreads.
Commentary
Technology-Related Surge Helps Offset Tariff-Driven Drain in Global Industrial Production
Macro Signposts highlights takeaways from the data analysis conducted by our team of economists and other experts.
Commentary
Mohit Mittal Explores Why Core Bonds Are Compelling Investments Today
Elevated yields, steeper yield curves, and ongoing volatility make core bonds a compelling choice for total return, income, diversification, and downside risk mitigation in today’s markets. Active management is key: Historically, it has helped core bond portfolios outperform passive strategies through a rigorous, diversified approach.
Commentary
Moving From Cuts to Caution: Fed Enters 2026 in Wait-and-See Mode
The Federal Reserve delivered a widely expected 25-basis-point (bp) rate cut in December, then signaled a more data-dependent path ahead. Barring an economic shock, we probably won’t see another rate cut until the second half of next year.
Commentary
Charting the Year Ahead: Investment Ideas for 2026
Marc Seidner, CIO of Non-traditional Strategies, explores opportunities across equities, bonds, credit, and commodities that have the potential to offer investors resilience and diversification.
Commentary
Tariffs Are Here to Stay
Macro Signposts highlights takeaways from the data analysis conducted by our team of economists and other experts.
Commentary
The Economics of AI Scale
This technology is moving quickly, with most businesses only in the early stages of understanding its capabilities. Whether and how fast AI can unlock new, transformative, lucrative idea generation or unleash a force in the U.S. economy similar to the “China shock” – the period in the early 2000s when outsourcing shrunk the U.S. manufacturing base and structurally changed the U.S. labor market – is yet to be seen.
Commentary
The Strategic Role of Commodities in Portfolios
Investors have poured into gold – but they may also see compelling benefits from a broad-based commodity allocation.
Commentary
Fed Policy in the Fog of Missing Data
The ongoing U.S. government shutdown has policymakers – and investors – operating without much of the timely official data that usually inform their decisions. This could have a tangible impact on Federal Reserve policy in particular.
Commentary
China’s Growth Engine Faces Fresh Challenges
China’s ability to sustain fairly robust economic growth despite a massive property sector downturn is now facing new tests as global trade barriers rise, and domestic demand shows fresh signs of weakness.
Commentary
Fed Delivers Despite Data Drought
The Federal Reserve on Wednesday announced a widely anticipated 25-basis-point (bp) rate cut, bringing the federal funds target range to 3.75%–4.00%. With markets priced for this move and the Fed operating in a data vacuum due to the U.S. government shutdown, the rate cut and modest statement changes were largely uneventful.
Commentary
Cracks Emerge Beneath Market Resilience, Challenging Areas of the U.S. Economy
The recent high-profile bankruptcies and the timing of their collapse are consistent with this changing macro backdrop, although these cases were also allegedly exacerbated by inconsistencies in collateral accounting and pledges.
Commentary
Fed Delivers Dovish Shift, Restarts Rate-Cutting Cycle
The Federal Reserve resumed its rate-cutting cycle at the September meeting, lowering its policy rate by 25 basis points (bps) to a range of 4%–4.25%, after being on hold since its previous cut in December. The Fed also signaled a less restrictive stance to come amid mounting labor m
Commentary
A Fed Housing Fix That’s Hiding in Plain Sight
Mortgage bond reinvestment could be the Federal Reserve’s most effective and immediate tool to unlock the housing market – without even touching interest rates.
Commentary
An Active Manager’s Lens Into Private Investment Grade Credit
The rise of private markets has brought new attention to private investment grade (IG) credit, which can offer investors a premium over public IG for giving borrowers customized terms – though that premium comes with certain risks.
Commentary
In Jackson Hole, Chair Powell Hints at Near-Term Rate Cuts and Reiterates Long-Term Approach
The Federal Reserve notes the balance of risks to the U.S. economy may warrant a shift in policy stance – in other words, a rate cut.
Commentary
Seeking Stability With High Quality Fixed Income
Uncertainty remains high, but so are bond yields, leading to attractive opportunities for active investors, in our view.
Commentary
EU–U.S. Trade Deal: Reduced Risks, but Still a Headwind for Europe
The degree to which growth in Europe slows, along with inflation developments, will be key in determining the path ahead for the European Central Bank.
Commentary
Holding Steady Amid Whipsawing Markets
Investors enjoyed broad gains across major asset classes in the first half of this year, but they endured considerable market swings to earn those returns.
Commentary
Charting Commodity Markets
In the weeks leading up to last month’s Israeli and U.S. strikes on Iran, oil prices climbed – not due to actual supply disruptions, but in response to a geopolitical risk premium.
Commentary
Balancing Act: Building Resilient Portfolios in a Changing Landscape
In recent months, markets have whipsawed amid changes in trade policy, geopolitical shocks, concerns about fiscal sustainability, challenges to central bank independence, technological advancements, and earnings surprises in both directions. Despite this, stocks and bonds in much of the world are close to where they began the year.
Commentary
Active Management Comes for Private Credit
by PIMCO, 7/2/25
As direct lending matures and other private credit areas expand, active investors can apply relative value strategies across sectors – and even entire markets – to pursue enhanced outcomes.
Commentary
Bend, Not Break: Investing in Real Estate Amid Economic Uncertainty
by PIMCO, 6/30/25
Until recently, commercial real estate appeared poised for a long-awaited rebound. However, 2025 has revealed a new reality: Uncertainty has become structural.
Commentary
Charting the Neutral Rate
Former Federal Reserve Vice Chair Richard Clarida explains where yields may be headed, as well as positioning considerations for the long-run by charting the relationship between r* and term premium.
Commentary
Fed Policymakers: Split Decision
The U.S. Federal Reserve left interest rates unchanged in June, as widely expected, but revisions to its economic projections indicate a more uncertain outlook.
Commentary
Charting the U.S. Consumer with Kristofer Kraus
Kristofer Kraus, portfolio manager and co-lead of PIMCO’s asset-based finance business, charts the nuances behind the overall resilience of U.S. consumers – and explains how these insights shape lending and investment strategies.
Commentary
The Future of the GSEs: Do No Harm
by PIMCO, 5/17/25
A rushed exit from conservatorship could increase mortgage rates and worsen home affordability.
Commentary
Income Fund Update: Focus on Stability Amid Turbulence
We maintain a focus on resiliency as elevated yields within high quality fixed income continue to offer attractive opportunities.
Commentary
The Fed Is in a ‘Good Place’: But for How Long?
Fed officials remain patient, likely awaiting hard evidence of a weaker U.S. labor market before considering rate cuts.
Commentary
The Real Lessons From the Plaza and Louvre Accords
Sustainable adjustments to trade imbalances require supportive monetary and fiscal policies – not just currency intervention.
Commentary
Challenges to Fed Independence
Although President Trump has said he has no intention of firing Fed Chair Powell, the Trump administration may be testing the laws underpinning Fed independence.
Commentary
Charting the Business Cycle
Former Federal Reserve Vice Chair Richard Clarida shares three charts highlighting possible macro inflection points in the business cycle: from growth and inflation to debt and labor.
Commentary
Outlook on Municipal Bonds: Seeking Opportunity Amid Volatility
A historic sell-off enhances value, with high yields, strong fundamentals, and ample reserves mitigating policy risks.
Commentary
How Effectively Can the U.S. Economy Untether From China?
U.S. trade policy has evolved significantly in a matter of weeks.
Commentary
Trade Wars and the U.S. Dollar
Rapid U.S. policy changes pose challenges for investors accustomed to a global financial system anchored in U.S. markets and assets.
Commentary
Overall U.S. Tariff Level Still High Despite Exemptions
With Congress out for the next two weeks for Easter recess and a short trading week in New York, it should be a quieter week – though tariff-related news continues to capture headlines.
Commentary
President Trump Blinks for Now, But Tariffs Remain High
On 9 April, President Donald Trump announced a 90-day pause on the higher “add-on” reciprocal tariffs on 50-plus countries that had been announced the previous week, precipitating a historic equity market rally and showing that there was seemingly a limit to how far he would go to move forward with his trade agenda.
Commentary
The U.S. Economy’s Trajectory Amid Higher Tariffs
On 2 April, the Trump administration announced sweeping tariffs that were more aggressive than many had expected. Then on 9 April, the administration announced a 90-day pause on most of the new country-specific “reciprocal tariffs.”
Commentary
Opposing Forces Complicate the Fed’s Dual Mandate
At their March meeting, Federal Reserve officials left the policy rate unchanged at 4.25%–4.5% and signaled further patience on rate cuts as they navigate greater uncertainty about the economic outlook.
Commentary
ECB: It Will Get Harder From Here
The European Central Bank will likely continue to cut interest rates, but future decisions could be more contentious.
Commentary
Income Fund Update: Navigating Uncertainty in 2025
Attractive yields and a broad opportunity set bolster active bond investments amid today’s uncertain macroeconomic and market outlook.
Commentary
Where to Look When Equities Are Priced for Exceptionalism
Lofty U.S. stock valuations call for a renewed focus on risk assessment and portfolio diversification.
Commentary
Watching the Fed Watching Tariffs and Inflation
It is not just tariffs that might affect inflation and growth but also trade uncertainty and the effects of the ambitious Trump policy agenda.
Commentary
The Tariff Tug-of-War: Balancing Economic Growth and Trade Relations
by PIMCO, 2/11/25
Exploring the delicate balance between protectionism and global cooperation
Commentary
ECB: Heading Towards Neutral
Despite still elevated domestic inflation, weak growth and inflation projected at target this year strengthen the case for further rate cuts.
Commentary
Fed Sees No Need to Hurry
Facing an uncertain outlook, the Federal Reserve holds rates steady and signals a watch-and-wait approach.
Commentary
Uncertainty Is Certain
Amid an unsettled global economic outlook and elevated equity valuations, bond markets present attractive yields and important diversification benefits.
Commentary
December Fed Takeaway: A Foggier Outlook and a More Cautious Path
Macroeconomic uncertainties prompted the Federal Reserve to signal a slower pace of policy rate cuts in 2025 and beyond.
Commentary
From Cash to Bonds: A Strategic Shift in Post-Pandemic Investing
As cash yields dwindle, the case for fixed income becomes increasingly compelling.
Commentary
ECB: Managing Risks to Growth
We continue to agree with market pricing following the ECB’s latest rate cut, but see additional downside risks to growth post-U.S. election.
Commentary
Private Credit: Asset-Based Finance Shines as Lending Landscape Evolves
by PIMCO, 12/13/24
The transition from bank-dominated lending to a diversified financing ecosystem offers unprecedented opportunities for private credit investors.
Commentary
Negative Correlations, Positive Allocations
The inverse correlation between bonds and stocks has returned, broadening potential for risk-adjusted returns in multi-asset portfolios.
Commentary
Income Fund Update: Navigating Rate Cuts With Flexibility and a High Quality Focus
We seek to capitalize on today’s attractive yields while staying mindful of economic and market uncertainties.
Commentary
Trump’s Second Act: What to Expect in 2025 and Beyond
Even with Republicans poised to control the White House, the Senate, and the House of Representatives, slim congressional majorities could hinder the president’s efforts to enact his agenda.
Commentary
Amid Uncertainty, Fed Embraces Data Dependence
In a week with a U.S. presidential election and market volatility, the Federal Reserve cut its policy rate 25 basis points (bps) as expected. Amid this noise and the generally positive messages from recent macro data, Fed Chair Jerome Powell emphasized that downside economic risks had decreased, but the policy rate remains above neutral, suggesting that gradual cuts are still likely to come over time.
Commentary
Emerging Markets: The Biggest, Fastest Growing, and Arguably Least Understood Pool of Credit in the World
Many investors today use EM debt for the wrong reasons, manage it imprudently, or overlook the best parts.
Commentary
ECB: Growth Concerns
Even without new staff projections, the European Central Bank makes policy less restrictive and lowers its relevant rate to 3.25%.
Commentary
Securing the Soft Landing
In the wake of pandemic shocks, economies appear more “normal” than at any time since 2019. Yet policy rates remain elevated.
Commentary
The Alpha Equation: Myths and Realities
Alpha (α) is a fundamental yet poorly understood concept in finance. Simply put, it is the difference between the return of an investment and that of a risk-adjusted benchmark. In a more advanced definition, alpha is the residual in an asset pricing equation (see Appendix A). Alpha is what active managers strive to achieve and passive managers do not pursue.
Commentary
Starting With a Bang: Fed Cuts Policy Rate
We believe the Fed is on a path to continue to cut rates over the next several meetings to realign monetary policy with a now more “normal” U.S. economy.
Commentary
Cuts and Consequences
Balanced risks to inflation and employment indicate it’s time for the Fed to normalize interest rates, enhancing a positive backdrop for bonds.
Commentary
China's Growth Evolution: Opportunities and Challenges for the Global Economy
China's economic transformation presents both challenges and opportunities for global markets.
Commentary
Powell on Fed Policy Moves: The Time Has Come
In his annual Jackson Hole speech, Fed Chair Powell assessed the post-pandemic U.S. economy and suggested rate cuts are coming soon.
Commentary
Summer of Dispersion
In this PIMCO Perspectives, we explore the dispersion playing out across monetary policy and financial markets.
Commentary
Developed Market Public Debt: Risks and Realities
In the post-pandemic fiscal landscape, government debt trajectories may be volatile, but appear broadly sustainable.
Commentary
June CPI Marks Progress Along the Last Mile to Inflation Target
A second straight month of encouraging U.S. core CPI data supports an initial Federal Reserve rate cut as early as September.
Commentary
Navigating Public and Private Credit Markets: Liquidity, Risk, and Return Potential
Comparing public fixed income and private credit markets involves weighing factors related to liquidity, transparency, credit quality, risk premium, and opportunity costs.
Commentary
Fed Policy: One Month of Good Data Is Not Enough
Good news on U.S. inflation in May did not sway the Federal Reserve to signal interest rate cuts could come sooner.
Commentary
ECB: Lower Cruising Altitude
While the European Central Bank cut policy rates by 25 basis points to 3.75% on its deposit facility, the trajectory beyond June remains unclear.
Commentary
Yield Advantage
The global economy continues to recover from pandemic aftershocks, including trade dislocations, outsize monetary and fiscal interventions, a prolonged inflation surge, and bouts of severe financial market volatility. At PIMCO’s 2024 Secular Forum, we explored how the aftereffects of those disruptions are producing some unexpectedly positive developments while introducing longer-term risks.
Commentary
April Inflation Report Unlikely to Alter Fed’s Path
April’s U.S. inflation report likely offers some comfort to Federal Reserve officials, but rate cuts are unlikely until we see a more substantial deceleration in inflation.
Commentary
Income Fund Update: Capitalizing on the Global Opportunities in Fixed Income
With the potential for higher-for-longer yields across countries, we see the global fixed income opportunity set as the most attractive in years.
Commentary
The Cost of Cash: A $6 Trillion Question
In this PIMCO Perspectives, we examine how the return of elevated bond yields comes at an opportune time to consider shifting out of cash.
Commentary
When Markets Diverge, Opportunities Emerge
Shifting dynamics among global economies and markets present a range of opportunities for multi-asset portfolios.
Commentary
The Fed: Stuck On Hold for Now
Despite the reacceleration of inflation and enduring labor market strength, the Fed remains focused on downside risks.
Commentary
Will the True Treasury Term Premium Please Stand Up?
Various methods to estimate this key bond market gauge differ on details but appear to signal rising investor compensation.
Commentary
ECB: Eyeing a June Rate Cut
While the European Central Bank refrained from declaring victory at its April meeting, a June rate cut seems increasingly likely.
Commentary
Shocking Bonds: Evaluating Advisor Fixed Income Portfolios as the Fed Enters Its Next Phase
After two volatile years, we believe conditions are especially compelling for fixed income.
Commentary
One Hike, Three Hints, and a Surprise Rate Cut
Recent signals from major central banks suggest challenges ahead with easing monetary policy amid above-target inflation.
Commentary
Bank of Japan’s Policy Shift Ushers in a New Era for Investors
The Bank of Japan (BOJ) has bid farewell to its negative interest rate policy (NIRP), yield-curve control (YCC) and quantitative and qualitative easing (QQE), marking the end of an era of extraordinary monetary easing.
Commentary
Fed Readies for Rate Cuts: Back Toward Neutral, or Mid‑Cycle Adjustment?
Federal Reserve officials appear locked in for multiple rate cuts this year, despite inflation reaccelerating – raising questions about the speed and timing of this easing cycle.
Commentary
ECB: Next Stop, June
While market pricing looks more reasonable, European Central Bank rate cuts, which could commence in June, are unlikely to be delivered as aggressively as the market expects in 2024.
Commentary
Back to the Future: Term Premium Poised to Rise Again, With Widespread Asset Price Implications
This PIMCO Perspectives assesses how the term premium’s 40-year downturn could start to reverse.
Commentary
The Crude Calculus: Predicting Oil’s Next Moves Amid Global Uncertainties
OPEC+ strategies and geopolitical tensions could roil markets.
Commentary
Real Assets: Bolstering Portfolios as Inflation Lingers
Adding real assets to a stock and bond portfolio can help boost returns and smooth volatility when inflation runs above 2%.
Commentary
Bond Markets Overlook U.S. Debt Trajectory, For Now
Debt levels will likely continue to rise absent policy changes, and the yield curve is likely to steepen.
Commentary
Income Fund Update: Compelling Yields Today, Potential Price Appreciation Tomorrow
Many investors remain in cash, but we think it’s time to shift exposure to bonds.
Commentary
Fed Slowly Building the Confidence to Cut
The Federal Reserve sees progress on inflation, but wants more certainty before it’s prepared to lower the policy rate.
Commentary
ECB Firmly on Hold
While interest rates have presumably peaked, we remain skeptical that rate cuts will be delivered as forcefully as the market expects.
Commentary
Munis Cap 2023 With Big Rally; Fundamentals Remain Strong
Municipals experienced their strongest two-month performance since 1986 during the final two months of 2023.
Commentary
Rethinking Retirement Spending Rules: A Market‑Based Approach

Starting portfolio yields may be a better guide to optimal spending than knowledge of future market returns.
Commentary
Fed’s Dovish Pivot Reflects Lessons From History

The market anticipates a swift shift in the Fed cycle.
Commentary
ECB Remains Attentive and Focused
While the ECB is unlikely to raise rates further, we remain skeptical that it will deliver rate cuts as early as the market expects.
Commentary
Mind the Supply: The Counterintuitive Impact of Higher Rates on U.S. Housing
The dearth of homes for sale has underpinned the housing market’s surprising resilience and may further lift home prices despite reduced affordability.
Commentary
Opportunities in Private Credit: Stepping in as Banks Step Out
As banks pull back from many types of lending, demand for capital is outpacing supply, providing the best potential opportunities in private credit since the GFC.
Commentary
October CPI: Small Surprise, Large Market Reaction
U.S. inflation cooled more than expected, and bond markets rallied, but the Fed is likely to remain in a long pause.
Commentary
Prime Time for Bonds
In our 2024 outlook, bonds emerge as a standout asset class, offering strong prospects, resilience, diversification, and attractive valuations compared with equities.
Commentary
Despite Resilient Data, Fed Signals Prolonged Pause
Tighter financial conditions prompted Federal Reserve officials to take a step back from data dependence, and suggest a higher bar for future hikes.
Commentary
Inflation Headache Remains for the Fed
The latest inflation report raises the odds of further Federal Reserve action.
Commentary
Post Peak
Our September Cyclical Forum was the first to be held in London, where the economic situation today reflects what’s happening around the world.
Commentary
Major Central Banks Maintain Hard‑Line Stance on Inflation
“Restrictive for longer” is now the mantra as monetary policymakers seek to bring inflation reliably to target.
Commentary
Understanding the Rise in Bond Yields: Implications and Opportunities for Investors
The spike in bond yields presents an opportunity for fixed income investors to earn capital gains and diversify portfolios.
Commentary
Specialty Finance: The $20 Trillion Next Frontier of Private Credit
A liquidity gap is growing as banks curtail specialty lending, providing specialty finance investors opportunities for potential better risk-adjusted returns than we’ve seen since the GFC.
Commentary
ECB Prioritizes Fighting Inflation Above Avoiding Recession
The European Central Bank is likely at or very near its peak policy rate, but we don’t expect rate cuts in the near term.
Commentary
Shifting Macro Trends in the Aftershock Economy
PIMCO’s Global Advisory Board discusses economic and geopolitical factors shaping the long-term global outlook.
Commentary
Local Government Financing Vehicles: A Growing Risk for China’s Economy?
We believe idiosyncratic credit events may occur over the next 12 months, but systemic bank risk is remote.
Commentary
Local Government Financing Vehicles: A Growing Risk for China’s Economy?
We believe idiosyncratic credit events may occur over the next 12 months, but systemic bank risk is remote.
Commentary
At Jackson Hole, Fed Reinforces Policy Stance
The Fed chair’s high-profile speech emphasized the central bank’s focus on taming inflation.
Commentary
Why Now Is a Good Time to Invest in Commodities
Commodities stand to benefit from underinvestment and the clean energy transition.
Commentary
Income Fund Update: Attractive Yields, Resilient Returns
We see compelling value in high-quality, liquid fixed income assets that may offer potential resiliency if the economy weakens.
Commentary
U.S. Downgrade a Reminder That Rising Deficits Can Have a Cost
The sovereign credit rating cut is unlikely to significantly change views toward U.S. Treasuries, but questions about debt sustainability may grow louder over time.
Commentary
BOJ Moves Toward Phasing Out Yield Curve Control
The Bank of Japan announced changes that could allow its yield curve control program to expire gradually if economic conditions are favorable.
Commentary
Fed Cycle Enters Data‑Dependence Phase
Amid an outlook for slower growth and more moderate inflation, the Fed shifts to data dependence.
Commentary
Bond Market Outlook: Valuations Suggest Potential for Equity‑Like Returns With Less Risk
High-quality fixed-income assets may offer the best return potential in more than a decade along with diversification benefits as a likely recession approaches.
Commentary
U.S. Inflation Outlook: A Meaningful Shift in the Second Half of 2023
After stubborn U.S. inflation in the first half of 2023 kept the Federal Reserve raising rates, June’s softer inflation report suggests July may mark the end of the hiking cycle.
Commentary
Fiscal Arithmetic and the Global Inflation Outlook
Debt-financed fiscal policy is driving much of today’s high inflation, but as pandemic-era measures fade, central banks will likely return to their key role in managing price levels.
Commentary
Rising Macro Risks May Limit Fed From Reaching Its Projected Peak
The Federal Reserve paused in June but raised its estimates for the policy rate later this year. We expect a July increase but remain skeptical about subsequent hikes.
Commentary
ECB Policy Rates Not Peaking Yet
The European Central Bank (ECB) hikes rates and signals more tightening ahead.
Commentary
Rising Macro Risks May Limit Fed From Reaching Its Projected Peak
The Federal Reserve paused in June but raised its estimates for the policy rate later this year. We expect a July increase but remain skeptical about subsequent hikes.
Commentary
Municipal Credit Conditions Have Peaked, but Fundamentals Remain Strong
State and local tax revenues sank in April, yet we believe most governments have strong fiscal positions, with ample reserves and budget flexibility to manage the decline.
Commentary
The Strategic Case for Commodities
With their ability to act as an inflation hedge, diversified, and return enhancer, commodities should be considered an important portfolio allocation over the long term.
Commentary
The Aftershock Economy
The first few years of the 2020s have seen a number of acute economic, financial, and geopolitical disruptions on a worldwide scale, and it will take time for the ultimate consequences of these shocks to be fully felt.
Commentary
When High Alpha Met Low Beta
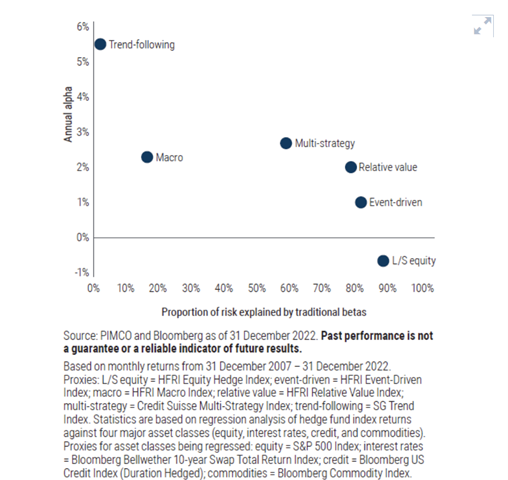
An in-depth analysis of hedge fund performance demonstrates that, over the past 15 years, lower-beta hedge fund styles have generally achieved higher alpha, aligning with investors' objectives of maximizing returns and diversification.
Commentary
Income Fund Update: Building Resilience and Harnessing Yield in High Quality Assets
Despite economic uncertainty, we see compelling value in high-quality, liquid assets that we view as more resilient in the face of a potential recession.
Commentary
Spring Brings Cautious Optimism to U.S. Housing Market
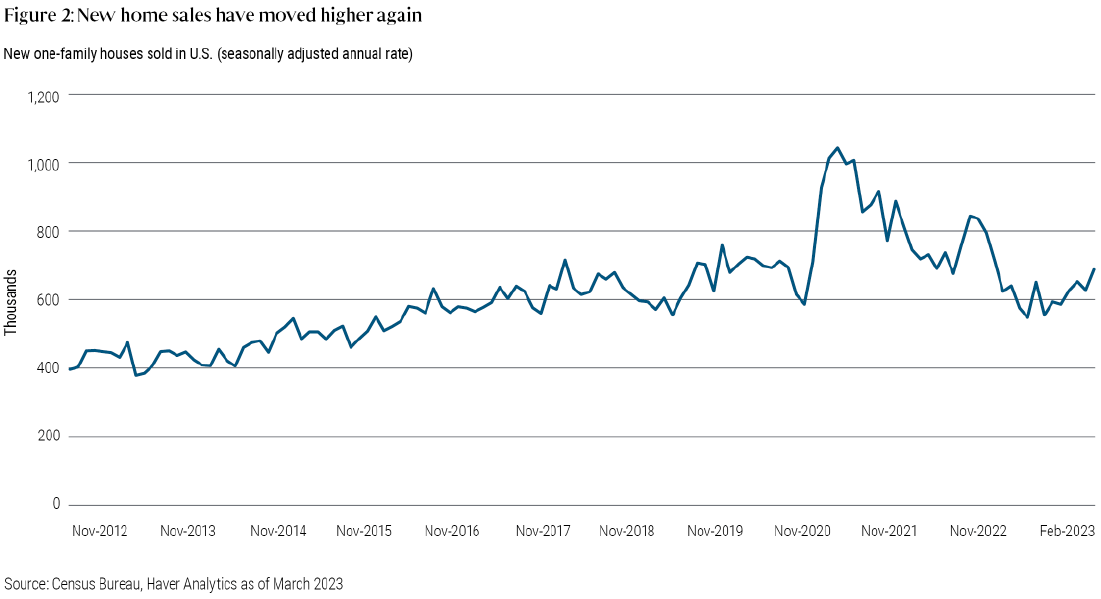
Although affordability remains an obstacle, recent data offer reasons to be more constructive as broader conditions still appear supportive of home prices.
Commentary
Whether Pause or Pivot, Look to Bonds
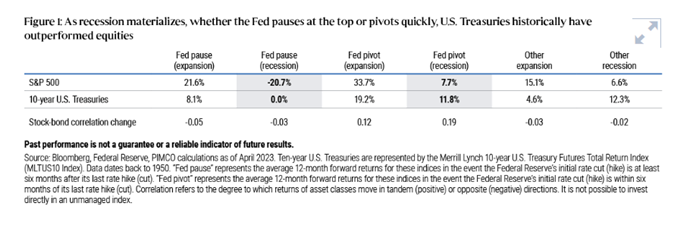
An allocation to fixed income may help investors navigate a potential recession as well as uncertainty around the Federal Reserve’s policy trajectory.
Commentary
Preparing for the Pivot: Key Takeaways From Our 2022 Advisor Fixed Income Portfolio Review
Higher bond yields and improved total return potential may offer advisors a compelling opportunity to move cash off the sidelines.
Commentary
Data Underpinning CPI Report Suggest U.S. Inflation Moderated Materially in March
March inflation data may put the Federal Reserve close to its terminal policy rate this cycle, if it hasn’t already reached it.
Commentary
Fractured Markets, Strong Bonds
History suggests the lagged economic effects of tighter central bank policy are arriving on schedule, but any eventual normalizing or even easing of policy will still likely require inflation to decline further.
Commentary
Bank Failures and the Fed
The failure of Silicon Valley Bank raises questions for Fed policy and economic growth.
Commentary
Data Alters Market's Expectations for Peak Policy Rate But Not Outlook for Fed Cuts
Strength in employment and inflation has caused markets to raise the implied terminal rate while still expecting the Fed to normalize policy – which is different from easing – in 2024.
Commentary
Markets Are Finally Listening to Fed’s ‘Ongoing Increases’ Message
Bond markets are pricing in additional Federal Reserve interest rate hikes, acknowledging the central bank’s emphatic resolve to tame inflation despite the likely trade-offs.
Commentary
Disappointing Details in January CPI Report May Give the Fed Room to Maneuver
U.S. inflation may not be moderating as quickly as many were expecting.
Commentary
The Worst is Likely Behind for Emerging Markets
After withstanding a multitude of global challenges last year, emerging markets look poised for improvement as inflation recedes and the path of monetary policy comes into view.
Commentary
The ECB is Not Done Yet
The European Central Bank raised its policy rate, and more hikes are coming.
Commentary
Fed Seeks to Balance Competing Risks
Investors face mixed signals between the Federal Reserve’s policy guidance and recent economic developments.
Commentary
Trying to Make Apple Juice from Oranges: The Problem with Comparing Market Pricing and Fed Projections
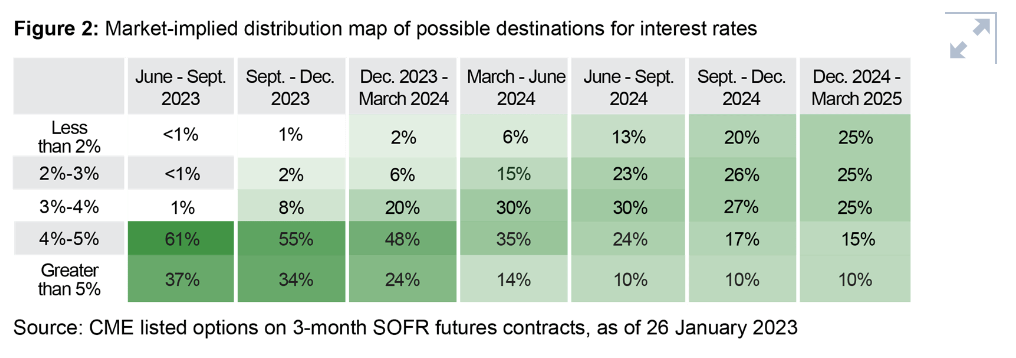
As investors seek to pinpoint market expectations for Federal Reserve policy, it’s critical to consider not just rate projections and derivatives pricing, but the degree of uncertainty and distribution of outcomes.
Commentary
European Outlook: Less Downside Now, But Caution Still Warranted
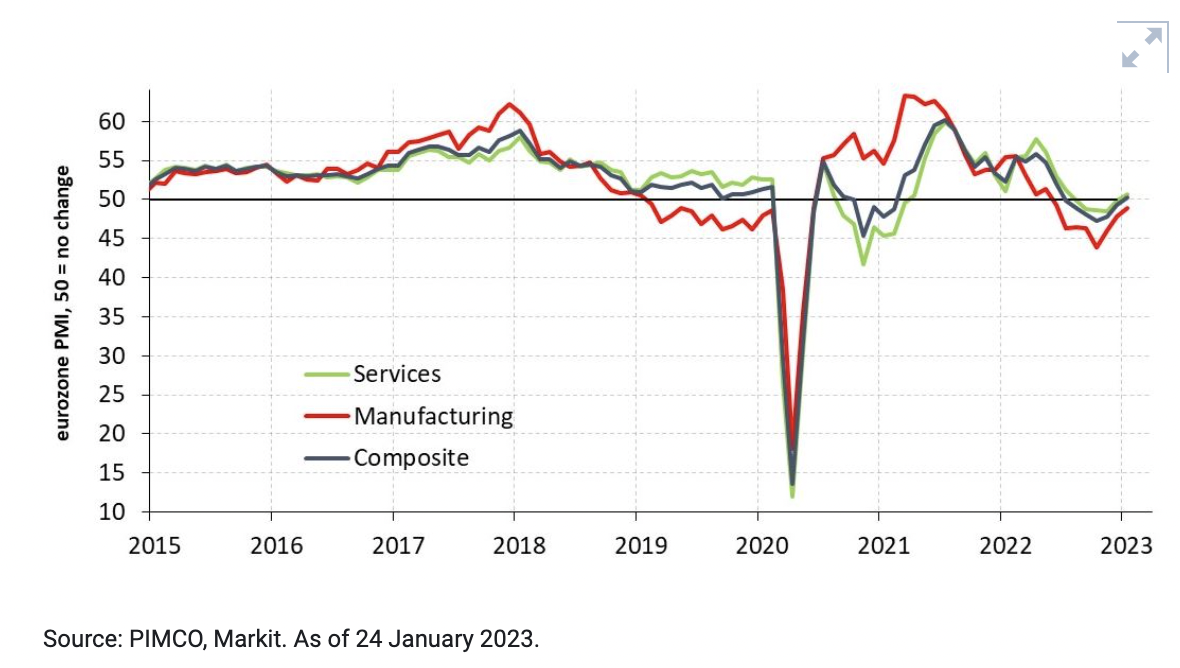
Focusing on high quality and liquidity when taking risk in portfolios will be key in 2023, as pressure on monetary policy remains intense.
Commentary
Cyclical Outlook Key Takeaways: Strained Markets, Strong Bonds
After enduring one of the worst years on record across asset classes, investors should find more cause for optimism in 2023, even as the global economy faces challenges.
Commentary
ECB Hikes, and Indicates Higher Rates Coming
The European Central Bank is likely to continue hiking rates next year, but the end point remains uncertain.
Commentary
U.S. Inflation Eased More Than Expected in November as Fed Eyes Pause in Rate‑Hike Cycle Next Year
Falling prices for cars and holiday discounting contributed to softer U.S. inflation, creating more room for the Fed to potentially dial back its hawkish stance.
Commentary
Plan Design in an Inflation‑Sensitive World
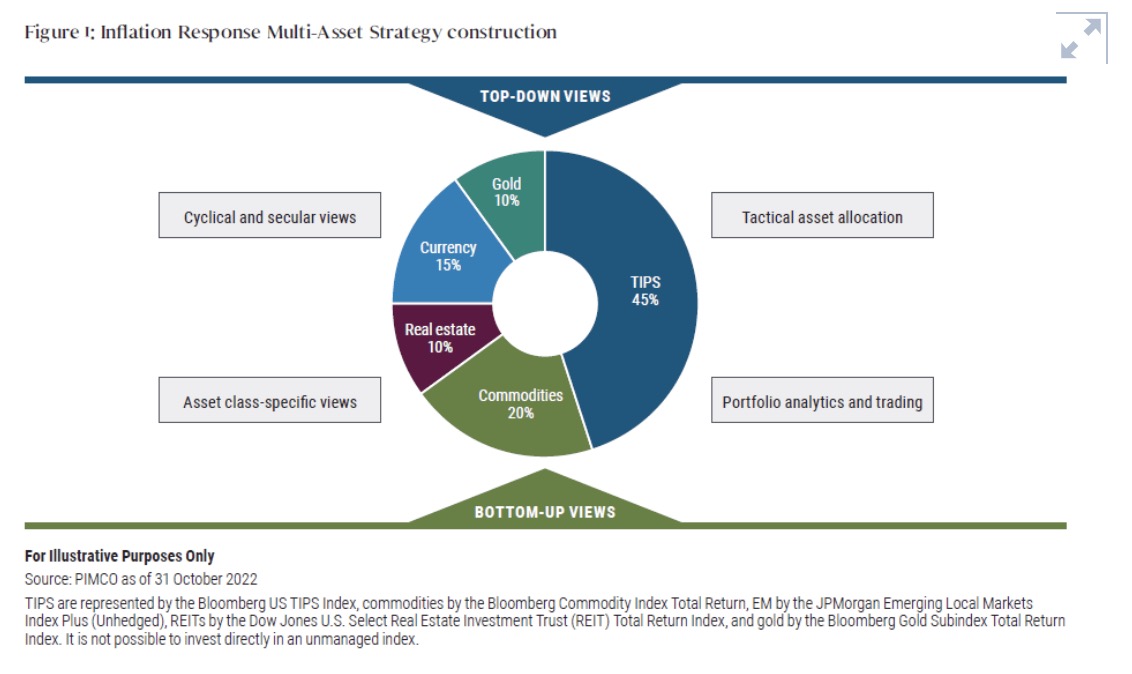
A multi-real-asset strategy may help plan participants preserve and grow purchasing power, enhance portfolio diversification, and mitigate inflation risks.
Commentary
Risk‑Off, Yield‑On
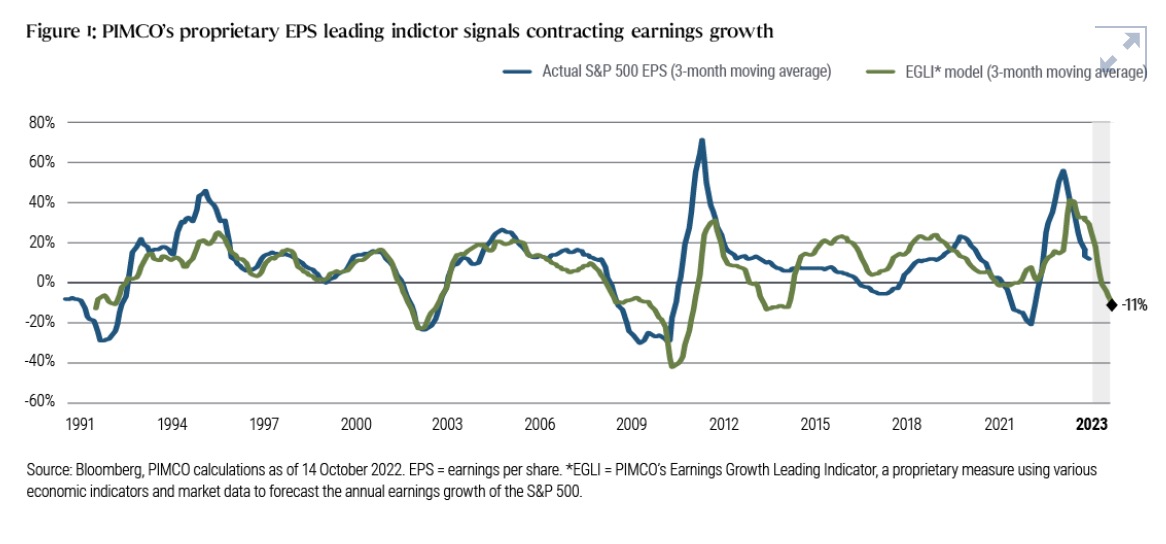
With interest rates higher amid a challenging macro environment, we see a compelling case for bond allocations and are cautious about higher-risk investments.
Commentary
What’s Behind the Slowdown in U.S. Inflation
Core inflation came in below expectations for October and should moderate in 2023, but likely with bumps in the road ahead.
Commentary
Peak Inflation May Hint at Peak Rates in Emerging Markets
Inflation is receding and real interest rates are climbing in EM after a year of tightening monetary policy.
Commentary
Fed Sets Up a Pause, Not a Pivot
The Federal Reserve’s November statement included dovish language, but Fed Chair Powell warned investors not to expect the Fed to stray from its full focus on fighting inflation.
Commentary
ECB Promises More Rate Hikes, But the Language Softens
The central bank noted that substantial progress has been made in withdrawing monetary policy accommodation, and expressed concerns around growth and policy transmission lags.
Commentary
Surging September CPI Bolsters Case for Further Outsize Fed Hikes
Core inflation in the U.S. outpaced expectations for September and may fortify the Federal Reserve’s hawkish resolve.
Commentary
OPEC+ Production Cuts Show Energy Security Has a Price
The OPEC+ plan to curb oil production complicates the global economic, inflation, and geopolitical outlook and will likely lead to higher prices for key commodities.
Commentary
U.K. Market: Growth, But at What Price?
U.K. financial market volatility is likely to remain high, and the longer-term outlook likely depends on future monetary and fiscal policy.
Commentary
With Aggressive Rate Forecasts, Fed Seeks to Reinforce Commitment to Taming Inflation
The Federal Reserve released new economic projections suggesting interest rate hikes will be faster and larger than previously forecast.
Commentary
Proceed With Caution: Opportunities for Cash and Defensive Income Amid Uncertainty
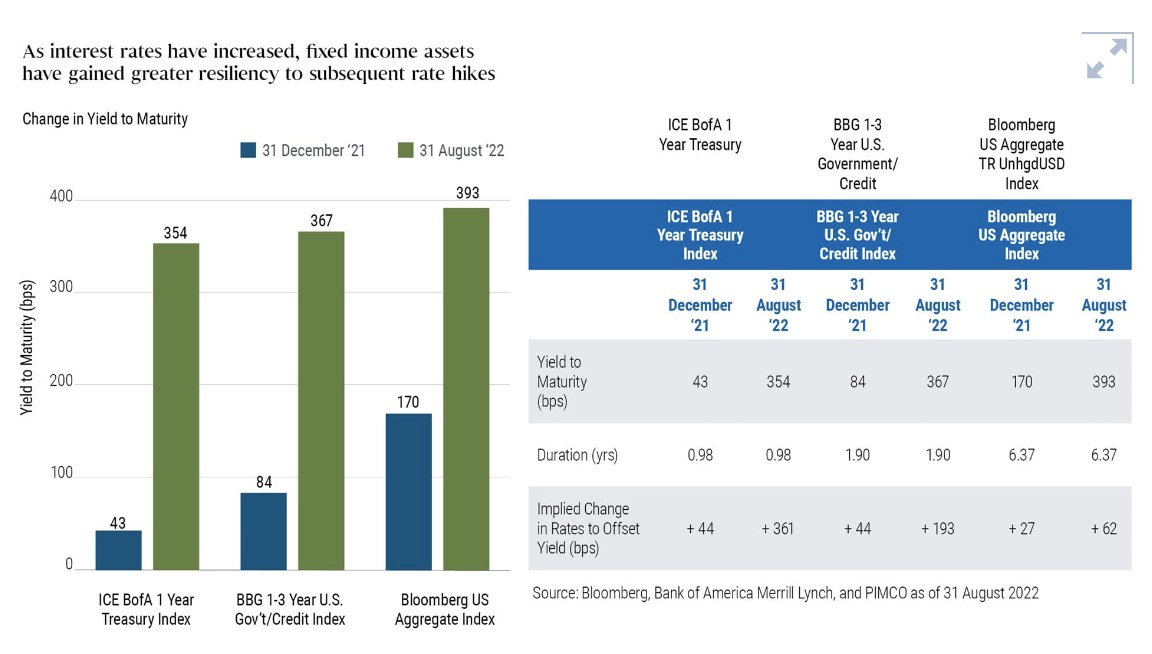
We believe short-dated bonds can offer attractive yields, flexibility, and a means to proceed cautiously as central banks continue to raise interest rates.
Commentary
Hot August Inflation May Shift Fed’s Interest Rate Trajectory Higher
The Federal Reserve may be pressured to target a higher terminal fed funds rate as it seeks to tame U.S. inflation expectations following strong price rises in August.
Commentary
How Can Policymakers Improve the Functioning of the U.S. Treasury Market?
Widening participation in the Fed’s standing repo facility and bond buying programs could mitigate another liquidity crisis in the Treasury market.
Commentary
Understanding the Completion Mandate Value Proposition
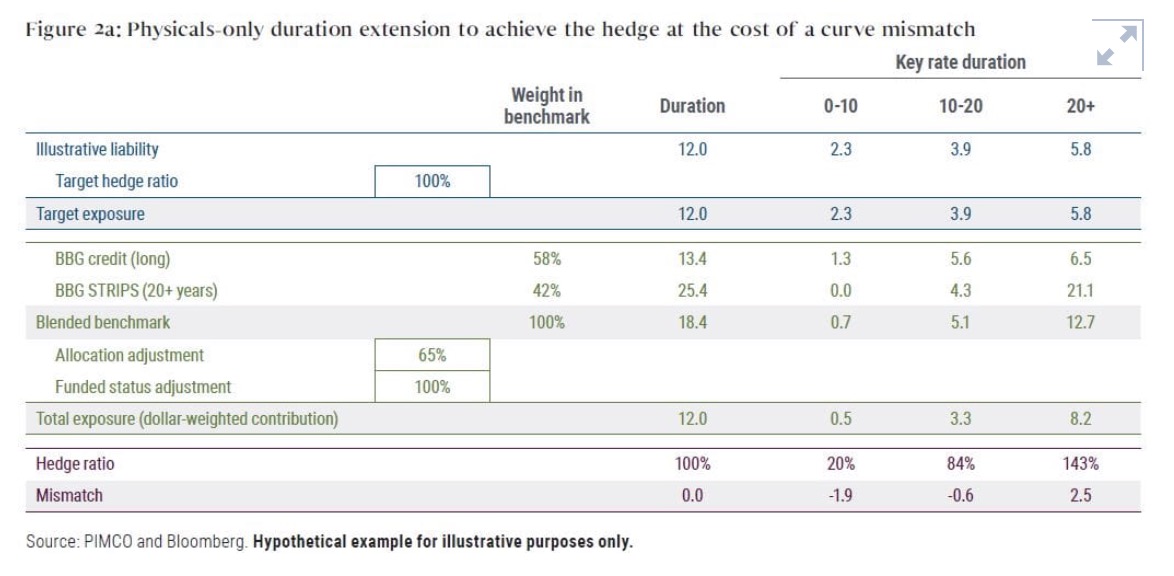
The value of completion mandates for defined benefit plans depends on the stage of the de-risking journey.
Commentary
Income Fund Update: Higher Yields, Wider Spreads, Greater Opportunities
The market contraction presents better opportunities than we’ve seen in years to generate income, which we balance against the need for resilience in the face of a potential recession.
Commentary
European Front‑End Markets: Valuation Strikes Back
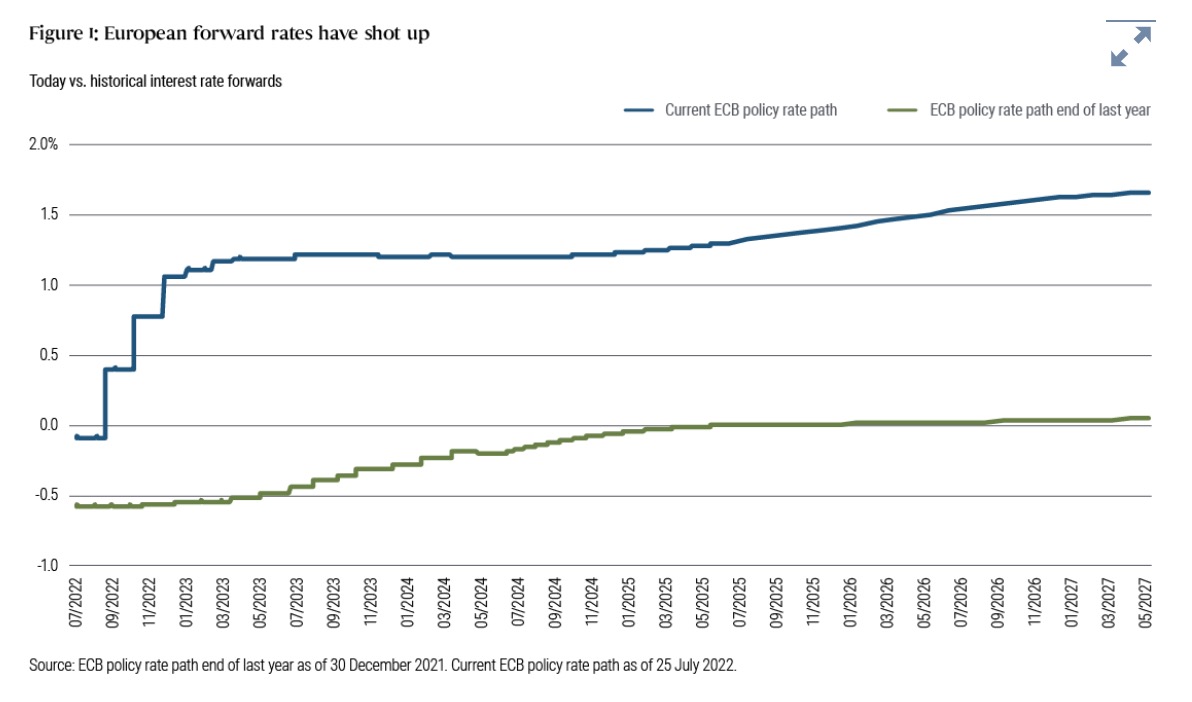
As the European Central Bank leaves negative policy rates behind, attractive valuations herald a much-improved total return potential.
Commentary
Building Resilience Amid Global Risks
PIMCO’s Global Advisory Board discusses the longer-term outlook for geopolitics, inflation, and other macro themes.
Commentary
July U.S. CPI Offers Some Relief, But Fed Also Watches Other Inflation Indicators
Despite price declines in many sectors, the Federal Reserve may continue its hawkish approach.
Commentary
Fed Aims for ‘Modestly Restrictive’ Policy to Counter Inflation
The Federal Reserve affirmed its commitment to price stability, hiking its policy rate 75 basis points again and signaling more tightening to come.
Commentary
What China’s Recovering Supply Chain Means for Global Inflation
Renewed growth in China’s manufacturing activity, coupled with softening developed market demand, should ease some supply-side pressures – but several other inflation risks remain prevalent.
Commentary
Core Inflation Data Could Prompt Dramatic Action at the Fed
June’s U.S. CPI (Consumer Price Index) inflation data likely set alarms blaring in the minds of Federal Reserve officials.
Commentary
Core Inflation Data Could Prompt Dramatic Action at the Fed
June’s U.S. inflation data will likely force central bankers into more restrictive territory – raising the odds of recession.
Commentary
Shelter From the Storm
Amid stormy markets, senior securitized credits hold potential for resilient returns.
Commentary
Key Takeaways From Our 2021 Advisor Fixed Income Portfolio Review
We examine key themes from our review of advisor fixed income portfolios over the past year.
Commentary
Power of Representation: the 'Us'es'
To celebrate Pride Month, four PIMCO executives share their perspectives on inclusion and diversity in the workplace and the importance of visible representation.
Commentary
Assessing Inflation’s Effects Across Emerging Markets
The varied responses of individual countries to global inflationary pressures have contributed to elevated real-rate differentials between developed and emerging markets.
Commentary
All Asset All Access: Managing Portfolios Amid Evolving Market Narratives
Research Affiliates discusses the intriguing long-term outlook for value stocks, and provides insights on the models that underpin its asset class forecasts.
Commentary
Income Strategy Update: Opportunities Ahead
Rising yields, wider spreads, and heightened market volatility are providing an attractive environment, but caution in credit selection is warranted.
Commentary
Credit Where Credit Is Due: Four Common Misconceptions in Public and Private Credit Markets
Heightened market volatility has led to misconceptions about credit, in our view. We dispel four of them here.
Commentary
Outflows Can Create Potential Opportunities in Municipal Marketplace
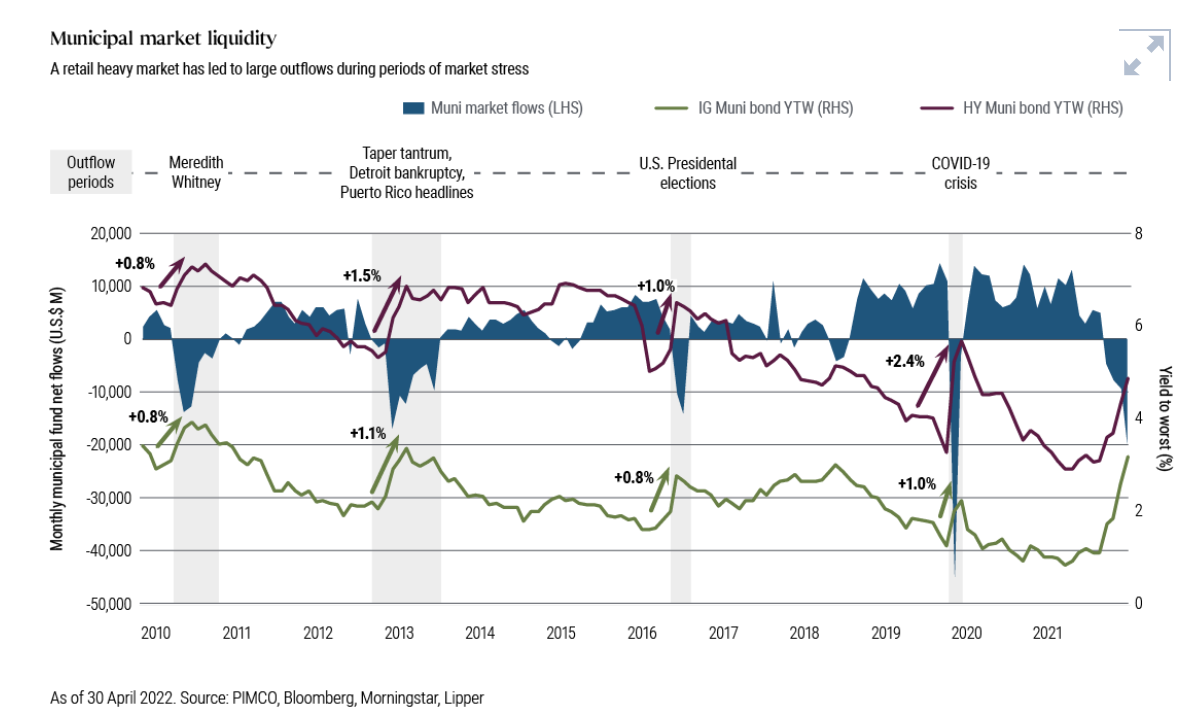
Higher yields, wider credit spreads, and other common market reference metrics suggest relative valuations for muni bonds have become attractive.
Commentary
Late‑Cycle Strategies
We assess risks and potential opportunities for multi-asset portfolios amid late-cycle dynamics, higher inflation, rising interest rates, and geopolitical uncertainty.
Commentary
Bank of Canada: Hike More Now, Less Later
The Bank of Canada embarked on a swift tightening path, but secular forces still weigh on the longer-run interest rate outlook.
Commentary
The Big Freeze: Sanctioning Russia Raises Questions on Other Currencies
Sanctions on Russia’s foreign currency reserves will likely stymie the rise of the Chinese renminbi as a competitor to the U.S. dollar.
Commentary
Real Estate Investing in an Uncertain Environment
Five commercial real estate sectors in markets across the globe have the potential to thrive in this environment.
Commentary
Russia‑Ukraine Ramifications: Not All Trade Is Created Equal
The countries’ weight in global trade is relatively small, but outsize exports of raw and semi-finished goods may portend price hikes across a variety of industries.
Commentary
China Growth Outlook: Counting the Cost of Lockdowns
While Beijing has set an ambitious growth target this year with a generous fiscal stimulus plan, new COVID-19 waves are adding to mounting headwinds amid a slowing global economy.
Commentary
Cash for Calls: Managing Liquidity for Illiquid Investments
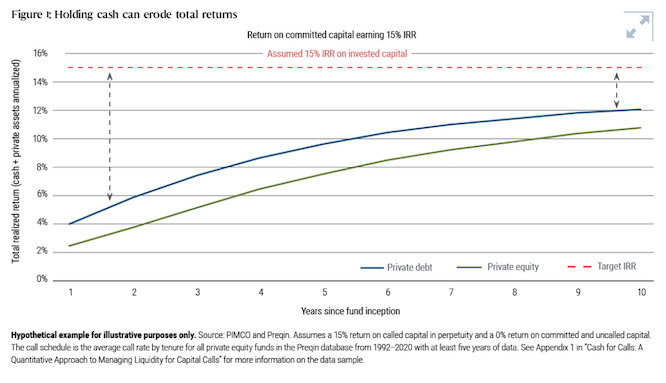
A framework for optimizing liquidity in alternative investments.
Commentary
Supply Chain Crisis: Disruption Should Lead to Greater Diversification
Supply chains set to become less dependent on China over time.
Commentary
U.S. Housing Outlook: No Bust After the Boom
Home price fundamentals suggest appreciation will slow but remain resilient.
Commentary
Munis in Focus: 2022 Municipal Market Update
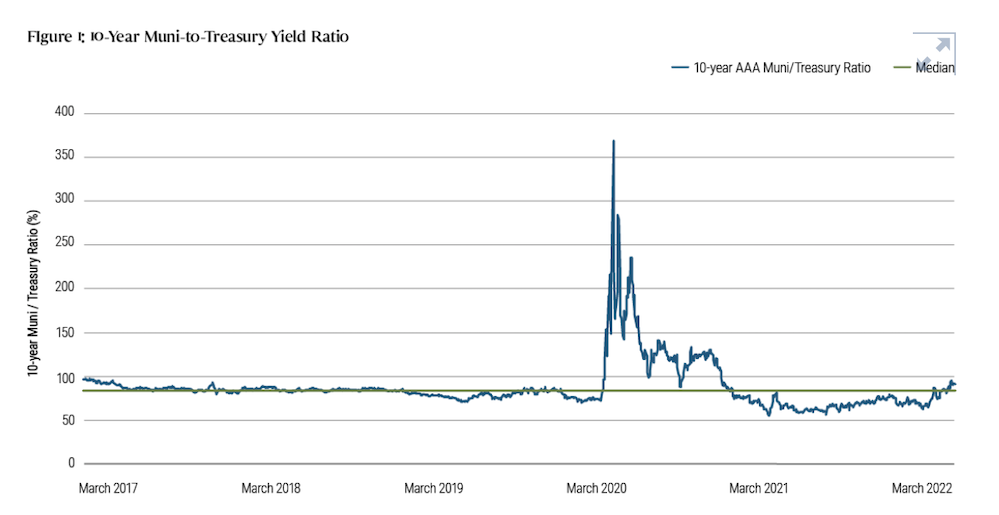
Their track record in periods of rising interest rates suggests municipal bonds could be well-positioned for this year’s market environment.
Commentary
Anti‑Goldilocks: Key Takeaways From the Cyclical Outlook
Russia’s invasion of Ukraine, the sanctions response, and the gyrations in commodity markets cast an even thicker layer of uncertainty on what already was an uncertain economic and financial market outlook before the onset of this horrific war.
Commentary
The New Defined Contribution Landscape
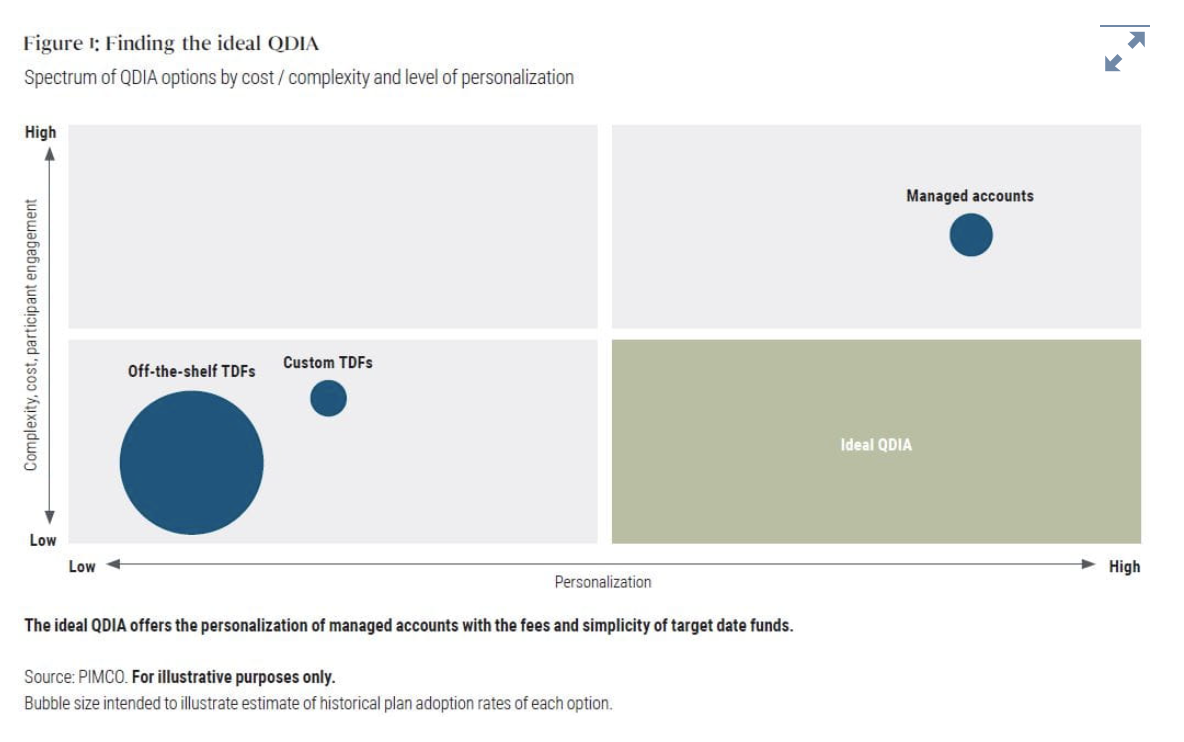
The pandemic hastens the evolution of the DC plan landscape and challenges plan sponsors to evolve.
Commentary
Tug of War: The Fed Begins a Rate‑Hiking Cycle as Inflation Trumps Uncertainty
The U.S. Federal Reserve raised the policy rate at the March meeting and signaled more hikes to come given the risks from high inflation.
Commentary
Income Strategy Update: Investing in Volatile Times
Russia’s invasion of Ukraine and the world’s subsequent sanctions and actions to curtail Russia’s access to the global financial system have thrown financial markets into turmoil.
Commentary
PIMCO Updates Its 2022 Glide Path for Target Date Funds
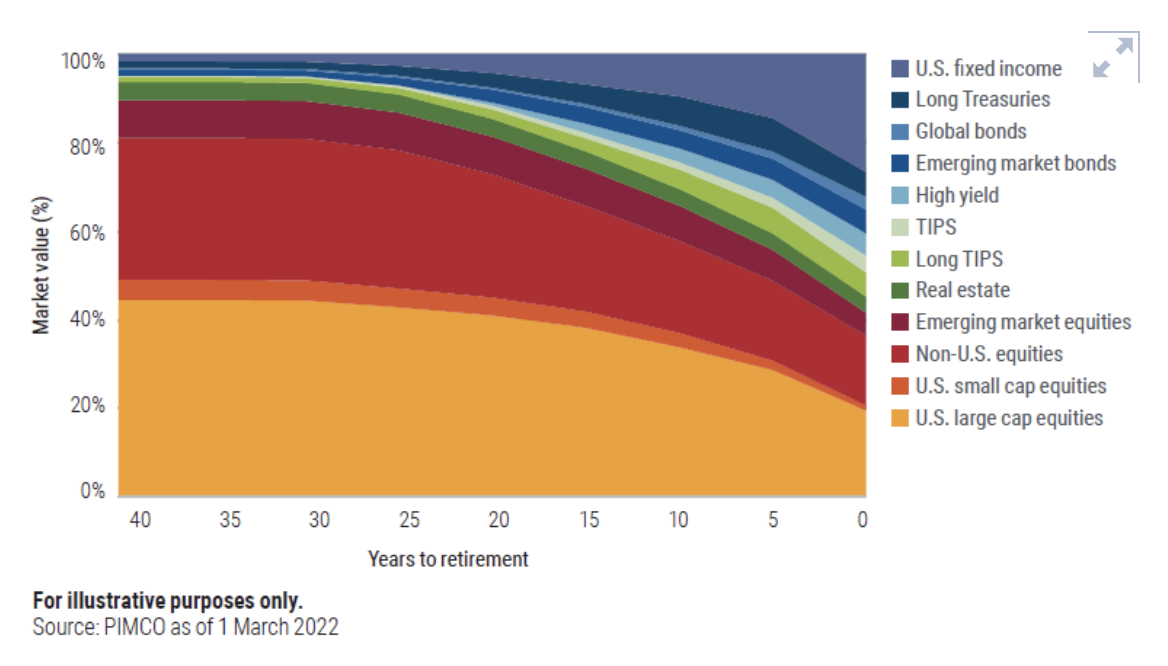
PIMCO’s glide path for target date funds expresses the firm’s collective view on age-appropriate asset allocation that can help prepare defined contribution (DC) plan participants for successful retirements.
Commentary
Muni Market Set to Welcome Puerto Rico’s Return After Bankruptcy
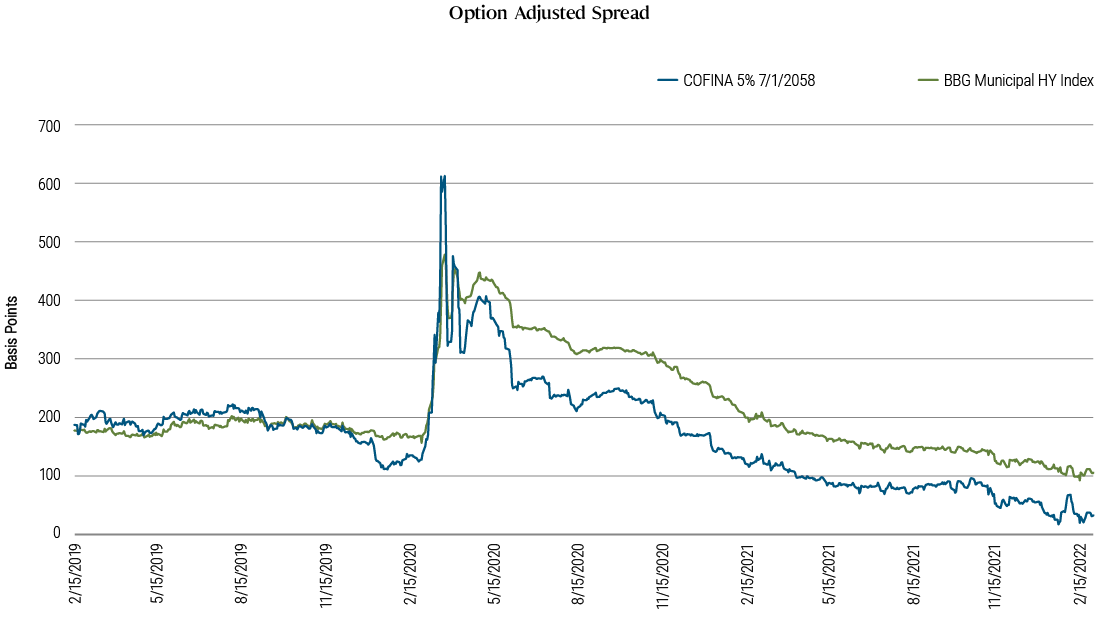
Restructured debt has often outperformed the broader municipal bond market as issuers emerge from bankruptcy with higher debt-servicing capacity.
Commentary
All Asset All Access: Engaging Opportunities Amid Volatile Markets
Research Affiliates discusses their approach to managing risks and targeting opportunities in uncertain environments.
Commentary
Commodities: Time to Shine
Commodities appear attractive amid elevated inflation, lingering supply-demand imbalances and high roll yields.
Commentary
Income Strategy Update: Positioning for Volatility and Interest Rate Uncertainty in 2022
As uncertainty pervades the markets, we are positioning defensively, increasing liquidity and remaining nimble in an effort to generate income amid bouts of heightened volatility.
Commentary
Price Hikes in Retail Goods Spur U.S. Inflation – and the Fed Is Watching
The January U.S. CPI (Consumer Price Index) report indicated a higher pace of inflation than many observers expected.
Commentary
Cash for Calls: A Quantitative Approach to Managing Liquidity for Capital Calls
Studies of private market investments tend to focus on the return premium associated with illiquid assets and their appeal relative to traditional public market assets.
Commentary
Regional Cyclical Outlook for 2022: Post‑Peak Growth and Shifting Policy
by Tiffany Wilding, Allison Boxer, Nicola Mai, Peder Beck-Friis, Vinayak Seshasayee, Carol Liao, Jun Yamamoto, Lupin Rahman of PIMCO, 1/31/22
Much of the global economy has transitioned quickly from an early-cycle recovery to a mid-cycle expansion that now appears to be rapidly progressing toward late-cycle dynamics.
Commentary
The Fed’s Road to Full Normalization
At the January 2022 meeting, the U.S. Federal Reserve signaled an accelerated timetable to normalize policy, but it will be a long process amid an uncertain environment.
Commentary
December CPI Data Suggests U.S. Inflation May Be Stabilizing, But Hasn’t Peaked Yet
The strong inflation report combined with employment data will likely prompt the U.S. Federal Reserve to begin hiking its policy rate in March.
Commentary
Fed Focused on Getting Back Toward Neutral
The Federal Reserve pulls forward rate hike expectations and doubles the pace of tapering in an effort to provide more flexibility to react in 2022.
Commentary
Trends and Transformations in the Global Economy
PIMCO’s Global Advisory Board discusses the longer-term outlook for macro trends and major economies.
Commentary
All Asset All Access: Investment Implications of Inflation Expectations
Research Affiliates discusses the outlook for U.S. inflation expectations, and explains their business cycle model and how it informs portfolio positions.
Commentary
U.S. Inflation Data Appears Consistent With Faster Fed Tapering and Interest Rate Hikes
The risks of continued elevated inflation likely have the U.S. Federal Reserve considering material changes to its policy path.
Commentary
Hazy Outlooks for Monetary Policy, Virus Roil Yield Curves and Boost Bonds
Uncertainties that caused U.S. Treasuries to rally and yield curves to undulate in November may persist and could contribute to volatility into year-end.
Commentary
Asset Allocation Views: Opportunity Amid Transformation
Disruptive trends and fatter tail risks highlight the importance of selection within asset classes and regions.
Commentary
European Secular Outlook: The Prospect of More Stability
The COVID-19 crisis spurs cohesion, but fresh challenges await.
Commentary
Amid Inflation Uptick, Valuations Signal Opportunities in Inflation‑Linked Assets
With major central banks likely to exercise patience in the face of price pressures, inflation-linked assets may be attractive allocations.
Commentary
Climate and COP26: Takeaways From Two Delegates
We offer our view of the most significant outcomes from the UN Climate Change Conference.
Commentary
Income Strategy Update: Flexibility to Withstand Pressure
As policymakers withdraw fiscal and monetary support, we believe market volatility will rise, presenting investment opportunities.
Commentary
Energy Volatility Shows Power of Commodities to Influence Inflation
The recent surge in oil and natural gas prices highlights the interconnected nature of energy markets, as well as the complexities of transitioning away from fossil fuels.
Commentary
October U.S. CPI Adds Pressure to Fed Policymaking
Stronger-than-expected U.S. inflation data in October may prompt the Federal Reserve to consider tapering faster and hiking sooner.
Commentary
Down, Not Out: 5 Things to Know About China's Power Crunch
While the recent energy crisis has disrupted China’s economy, we do not expect a significant drag on growth.
Commentary
Rising Valuations May Reflect Improved Credit Conditions
We believe the municipal markets should remain strong into 2022, although the good news may already be baked into high quality bond valuations.
Commentary
Focusing on Sustainability and Providing Attractive Income
Combining PIMCO’s innovative ESG (environmental, social, governance) investing approach with its expertise in income investing, this flexible strategy targets a multi-sector, global opportunity set.
Commentary
Age of Transformation
Three transformative trends will lead the world into a radically different macro environment over the secular horizon. Read our long-term outlook and implications to consider when investing.
Commentary
Monthly Municipal Market Update, September 2021
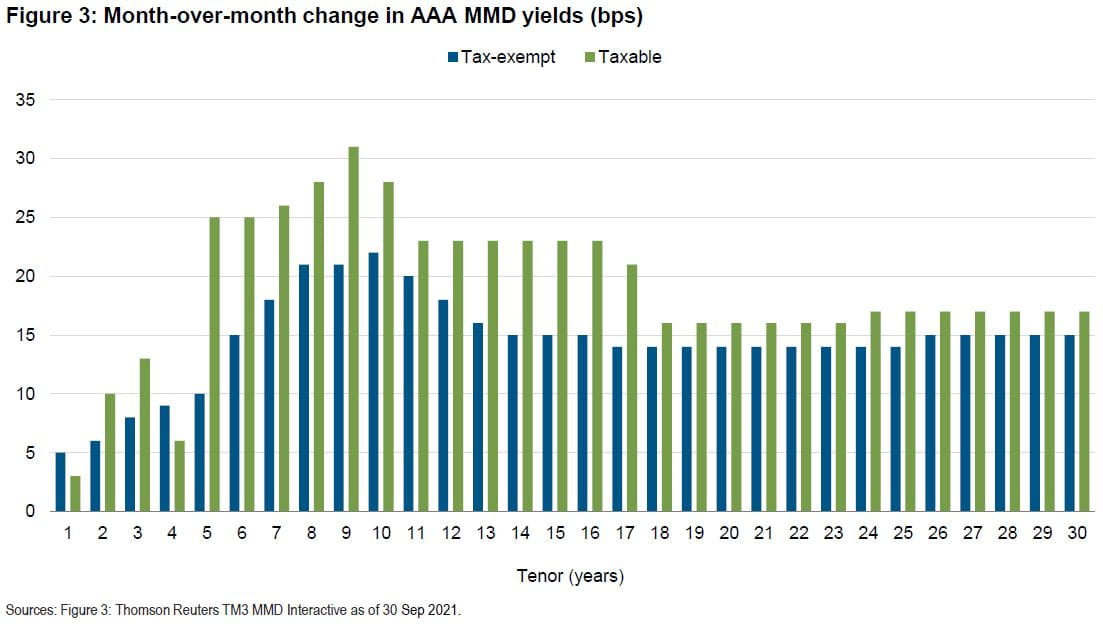
The Fed's more hawkish stance at September’s FOMC meeting, rising upside inflation pressures, and near-term volatility drove Treasury yields higher at the end of the month.
Commentary
Idiosyncratic Risk in China Real Estate: What Does it Mean for the Property Market and Banks?
We do not expect widespread contagion across China’s real estate or banking sectors despite the challenging outlook.
Commentary
Fed Policy Amid Elevated Inflation Concerns
Elevated risks to inflation expectations appear to have prompted Federal Reserve officials to revise their policy rate hike projections higher.
Commentary
Fed Policy Amid Elevated Inflation Concerns
Elevated risks to inflation expectations appear to have prompted Federal Reserve officials to revise their policy rate hike projections higher.
Commentary
Municipal Bonds: The Advantages of Active Management
The active/passive debate frequently focuses on equities, where active approaches have historically underperformed passive strategies. The story is decidedly different in the world of fixed income, where active managers can more easily exploit mispricing and other inefficiencies.
Commentary
Fundamentals of RAE: Deep Value, Bubble Stocks, and Market Inefficiency
Value has its day in the sun. But are investors learning the right lessons from it?
Commentary
Flexible Fixed Income: How to Navigate the Challenges of 2021 and Beyond
Uncertainty always exists in financial markets.
Commentary
A Dizzying Summer in D.C. as U.S. Debt Ceiling Looms Again
A busy summer on the fiscal front in Washington that’s seen progress on budget and infrastructure legislation could soon give way to another showdown over the U.S. statutory debt ceiling, potentially signaling volatility for investors in the months ahead.
Commentary
All Asset All Access: Evaluating and Managing Long‑Term Inflation Risks
In this edition, Chris Brightman, chief executive officer and chief investment officer of Research Affiliates, explains their outlook on long-term inflation and discusses how investors can prepare for this risk.
Commentary
How SMAs and Interval Funds Can Help Meet Municipal Investor Needs
There are many potential advantages to investing in tax-exempt municipal bonds, but not all advisors are aware of additional strategies and investment vehicles that can help them meet muni-focused client needs.
Commentary
Why Yields Fell, and What Happens Next
In our baseline forecast, the recent decline in U.S. Treasury yields will reverse somewhat, as some of the near-term factors pressuring yields lower ebb.
Commentary
Income Strategy Update: Investing Amid Inflation Concerns and Lower Yields
With global growth rebounding amid uncertainties over inflation and COVID-19 variants, investors may want to consider a somewhat more cautious and flexible approach when seeking a consistent yield.
Commentary
Substantial Further Progress? Not Yet, Says the Fed
The Fed stopped short of providing “advance notice,” but a December tapering announcement remains likely.
Commentary
Three Disruptive Trends Set to Transform the Auto Industry
Over the next 10 years, the global automotive industry is expected to face one of the most significant changes in its history – the replacement of internal combustion engine (ICE) vehicles with electric vehicles (EVs).
Commentary
Mid‑Cycle Investing: Time to Get Selective
The global economy is in a mid-cycle expansion, following peaks in policy support and growth, and what is likely a transitory spike in inflation. We expect global growth to moderate to a still above-trend pace in 2022.
Commentary
Supply Bottlenecks Likely to Ease by the End of the Year
Global demand for consumer goods has rebounded since the second half of 2020, driven initially by large government stimulus packages and, more recently, by resilient capital expenditures and swift vaccination rollouts in most developed markets.
Commentary
We Have a Deal: U.S. Infrastructure Spending Soon, Tax Increases Likely Later
A bipartisan deal on infrastructure spending would likely be followed by a separate partisan deal funded by tax increases.
Commentary
U.S. Regulators to Leveraged Loan Issuers: Just Do It (Transition to SOFR)
Leveraged loan issuers have lagged other fixed income market issuers in moving to SOFR as a reference rate, posing potential risks to investors as the year-end deadline approaches.
Commentary
Inflation Inflection
Over the past few months, economic recoveries have been uneven across regions and sectors.
Commentary
PIMCO Trends: Managed Futures: Seeking Diversification and Returns
Managed futures strategies have historically delivered attractive returns over the long run with low equity correlations.
Commentary
Monthly Municipal Market Update, May 2021
A brief monthly update on what's happening in the municipal bond market.
Commentary
Top Five Insights from PIMCO’s 2021 ESG Investment Summit: Financing a More Sustainable Future
PIMCO’s annual ESG Summit – hosted virtually this year – aimed to help participants keep pace with the rapidly evolving landscape of environmental, social and governance issues within the world of investing, with a particular focus on the transition to net-zero emissions.
Commentary
Top Five Insights from PIMCO’s 2021 ESG Investment Summit: Financing a More Sustainable Future
Expectations for COP26, the importance of issuer engagement, and growth in sustainability-linked bonds were among the many topics covered.
Commentary
A Swift Price‑Level Adjustment, Not an Inflation Spike: April U.S. CPI
We believe the U.S. is undergoing a large price-level adjustment, not shifting to a persistently higher inflation regime.
Commentary
China Property Sector Remains Robust Despite Policy Headwind
Momentum in China’s property market remains strong so far in 2021, driven by healthy demand for housing.
Commentary
Treasury Issuance Could Aid Adoption of SOFR Benchmark
As regulators push to transition away from Libor, sales of Treasuries linked to the successor rate could boost the new benchmark’s credibility and expand nascent markets for related debt and derivatives.
Commentary
Realigning Inflation Expectations
As expected, the Federal Open Market Committee (FOMC) announced no changes to its administered rates following its April meeting, and Federal Reserve Chair Jerome Powell did not provide new information about the Fed’s bond-buying programs.
Commentary
Nuclear Decommissioning Trusts: Broadening the Fixed Income Opportunity Set
Nuclear decommissioning trusts (NDTs), the pools of money accumulated over decades used to dismantle nuclear power plants and safely dispose of radioactive materials, allocate about 40% of their assets to fixed income securities.
Commentary
Rethinking Cash Holdings to Avoid Near‑Zero Yields
Since the disruptions that roiled financial markets in March 2020, investors have turned more to cash and other short-term instruments typically associated with risk aversion and preservation of capital and liquidity.
Commentary
Bank of Canada: Walking a Tightrope
On April 21 the Governing Council of the Bank of Canada (BoC) will meet to discuss monetary policy.
Commentary
Global Chip Shortage: The Winners and Losers
Computer chips, or semiconductors, power everything from cars to consumer electronics, such as PCs, gaming consoles and smartphones.
Commentary
Dealing With an Inflation Head Fake
We forecast a strong global recovery in 2021 amid significant fiscal support, accommodative monetary policy, diminishing lockdowns, and accelerating vaccinations.
Commentary
Will Taxes Rise in the U.S.?
Democrats could begin working on a tax bill later this year, but resulting tax hikes may be weaker and less of a headwind to growth than some fear.
Commentary
U.S. Equity Values: The Three Dogs That Have Not Barked
Stock market bulls can find reassurance in the equity risk premium, which suggests stocks are valued fairly or slightly expensive.
Commentary
SLR Expiration: Treasury Markets Likely to Shoulder the Costs
The Federal Reserve on 19 March announced that the temporary changes to its supplemental leverage ratio, or SLR, will expire as scheduled on 31 March.
Commentary
Fed Policy: Patience Is a Virtue
Following its March meeting, the Federal Open Market Committee (FOMC) released a statement and summary of economic projections (SEP).
Commentary
Focusing on Inflation May Miss the Bigger Risk
As the latest COVID-19 relief bill winds through the U.S. Congress, some economists have been warning that too much stimulus could lead to the economy overheating
Commentary
Surge in Rates May Be Overstating the Case for Inflation
Longer-dated Treasury yields have climbed as markets consider whether economic growth and inflation expectations might accelerate more rapidly. We believe inflation pressures will remain in check and bond yields will be range-bound.
Commentary
Implications of China’s Credit Curtail
China’s economy should see a soft landing as stimulus is reduced, but the drag on global growth may place a burden on developed economies to keep stimulus taps open for longer.
Commentary
An Employment Priority: Women Reentering the Workforce Are Pivotal to U.S. Economic Recovery
One year since the inception of one of the most severe recessions in modern history, women’s engagement in the labor force is crucial to the economic recovery.
Commentary
Valuing Diverse Perspectives
As International Women’s Day approaches, three PIMCO executives share their perspectives on diversity in the workplace.
Commentary
What the Pandemic Taught Us About Target Date Funds
Target date funds should be designed to reduce the risk of rash selling.
Commentary
Fiscal Spending Could Cause a U.S. Growth Spike – Compounding Investors’ Concerns on Inflation
A large fiscal package geared toward pandemic relief will likely boost U.S. growth even further in 2021, but long-term inflationary risks are still balanced.
Commentary
Municipal Bond Outlook: Recovering at Different Speeds
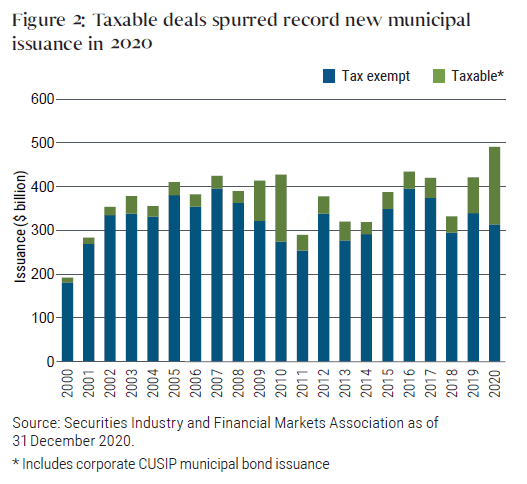
Political change, continued fiscal support will drive municipal markets in 2021, although outcomes are likely to vary.
Commentary
Fixed Income: Low Yields Don’t Tell the Whole Story
It’s tempting these days for some investors to question the role of fixed income in portfolios. After all, real yields have plunged, potentially leading to less income today and smaller capital gains tomorrow.
Commentary
Monthly Municipal Market Update, January 2021
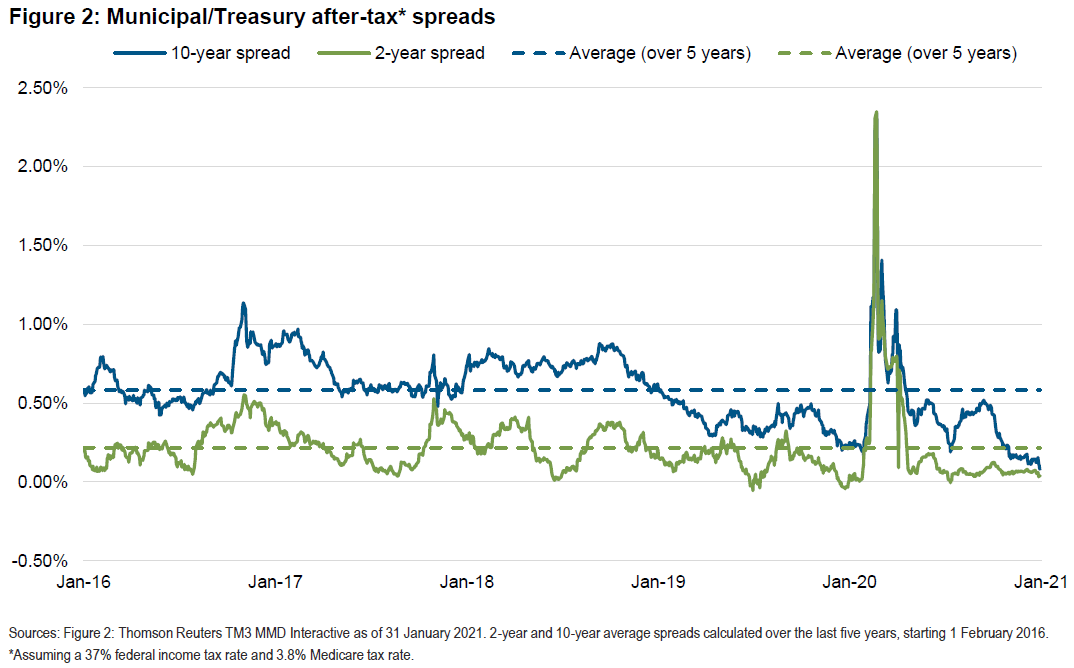
A brief monthly update on what's happening in the municipal bond market.
- Tax-exempt municipal bonds generated solid performance in January, with high yield munis gaining more than 2% on the month.
- Municipal yields rose early in the month on expectations for higher rates and additional fiscal stimulus.
- Although issuance was relatively light in January, the municipal market experienced strong demand, with four consecutive weeks of fund inflows.
Commentary
Avoiding Turbulence: Fed Policy and Communication in 2021
A clear communication strategy is crucial to managing market expectations around changes in Federal Reserve asset purchases and interest rate policy.
Commentary
LDI Programs: Finding a Better Replacement for Treasury STRIPS
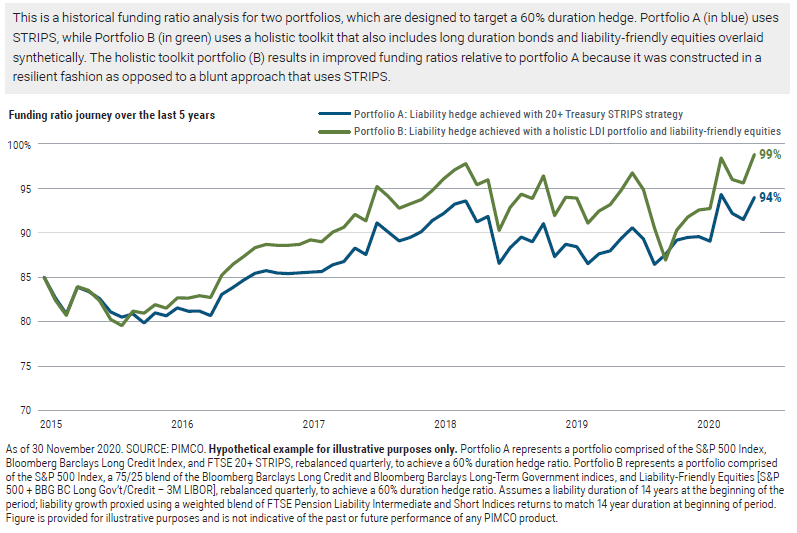
A holistic LDI portfolio may provide a superior liability hedge.
Commentary
Beyond Brexit: Outlook and Risks for the U.K. Economy
Despite seeing major market swings following the 2016 Brexit referendum, we don’t expect Britain’s departure from the European Union (EU) to have any major economic effects in our baseline outlook for 2021 and beyond. Far more important are COVID-19, fiscal policy, and bigger questions around future productivity growth.
Commentary
Tail Winds Provide Lift for Emerging Markets Investments
A confluence of dynamics are set to accelerate global capital flows to emerging markets amid attractive valuations.
Commentary
Monthly Municipal Market Update, December 2020
A brief monthly update on what's happening in the municipal bond market.
Commentary
A Narrowly Democratic Congress Could Boost Spending and Growth
With a narrowly Democratic Congress, U.S. fiscal spending is likely to increase on economic relief from the pandemic, infrastructure, and healthcare, boosting the economic rebound.
Commentary
Asset Allocation Views: Early Cycle Investing
In this abridged version of our latest Asset Allocation Outlook, we discuss the opportunities and risks of investing in an early cycle recovery.
Commentary
Today's Credit Opportunities in 5 Charts
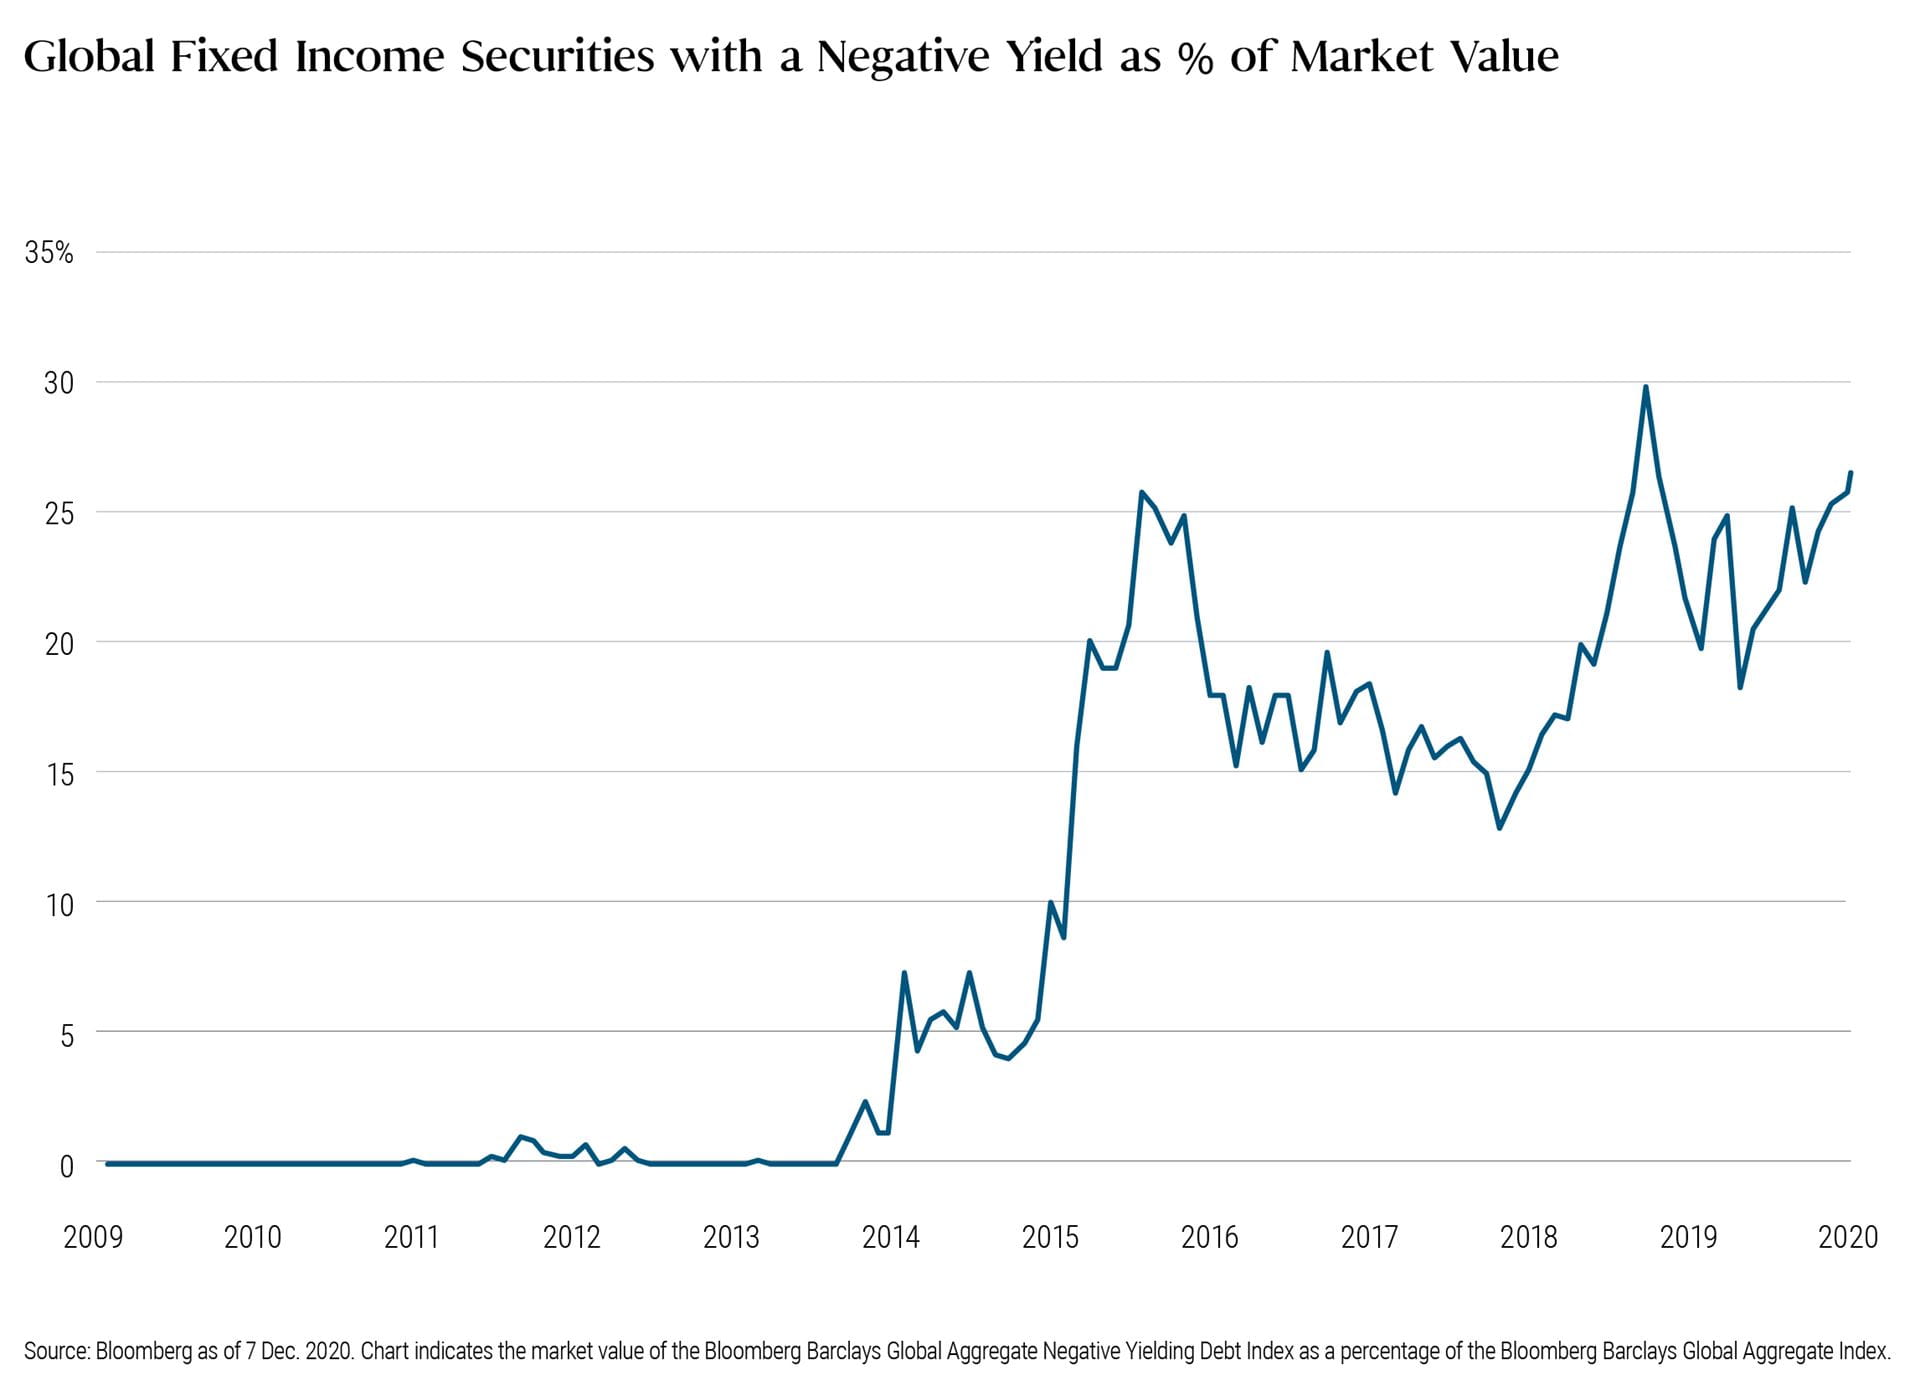
How can credit markets help active investors achieve their goals in the present low yield environment? Here are 5 ideas.
Commentary
The 60/40 Portfolio Is Alive and Well
Is the 60/40 stock-bond portfolio dead? We don’t think so.
Commentary
The Fed’s Latest Balance Sheet Guidance: A Compass, Not a Map
The Federal Reserve signals that monetary policy accommodation will remain firmly in place.
Commentary
Monthly Municipal Market Update, November 2020
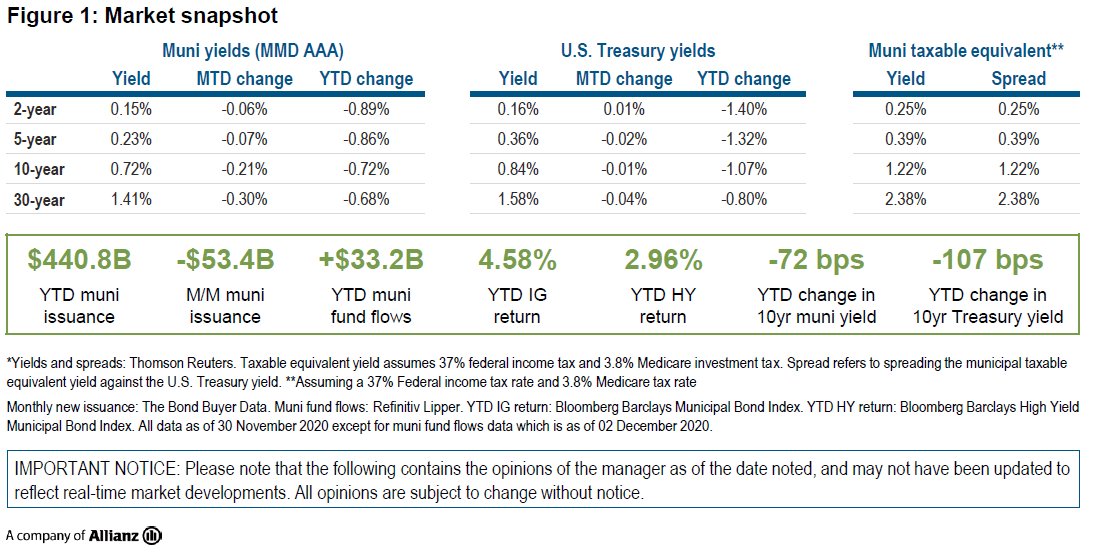
The U.S. stock market surged in November, erasing October’s losses even amid a rising number of coronavirus infections. Propelled by progress toward potential coronavirus vaccines and hopes for a relatively smooth transition to power for president-elect Joe Biden, major U.S. equity indices closed the month with double-digit gains.
Commentary
Early Cycle Investing: Navigating the Growth Rebound
We believe traditional fixed income should continue to provide a reliable source of diversification against a growth shock, but low rates and the risk of an inflation shock necessitate broadening the menu of diversifiers.
Commentary
Green Light to a Greener Economy: Three Investment Trends
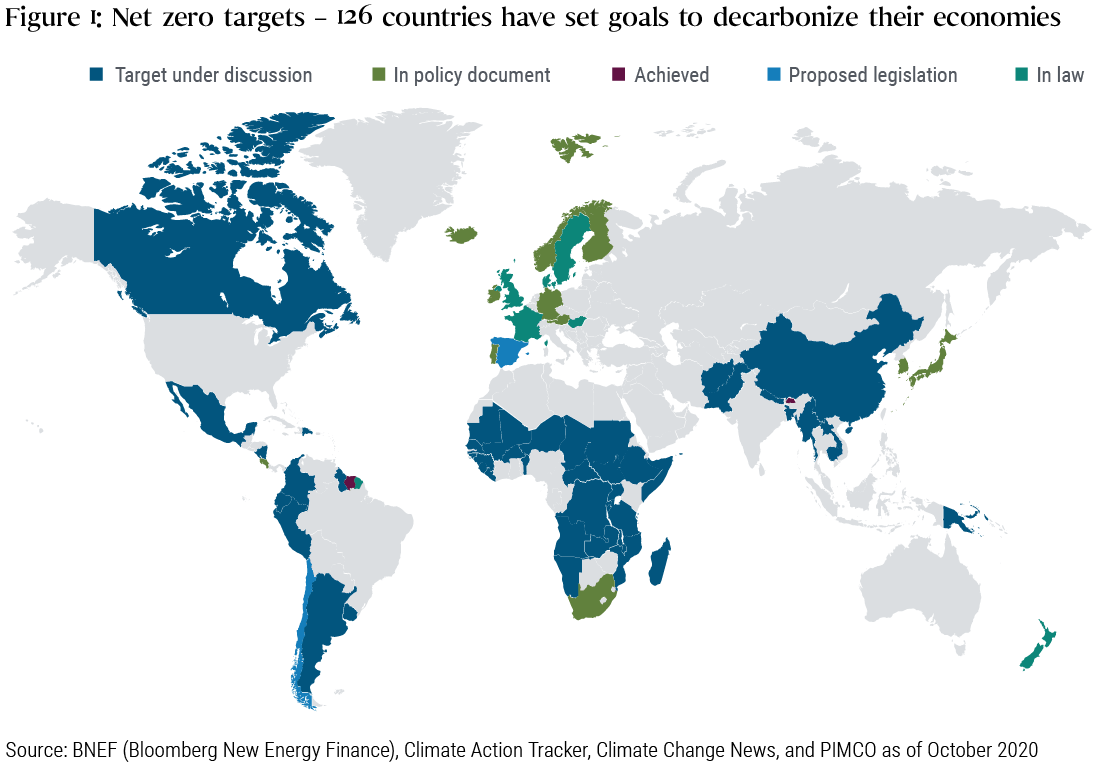
Some of the world’s leading countries have recently announced major sustainability targets. These moves, aimed at making economic recovery faster and more sustainable, will create investment opportunities as well.
Commentary
Harvesting Yield in Emerging Markets
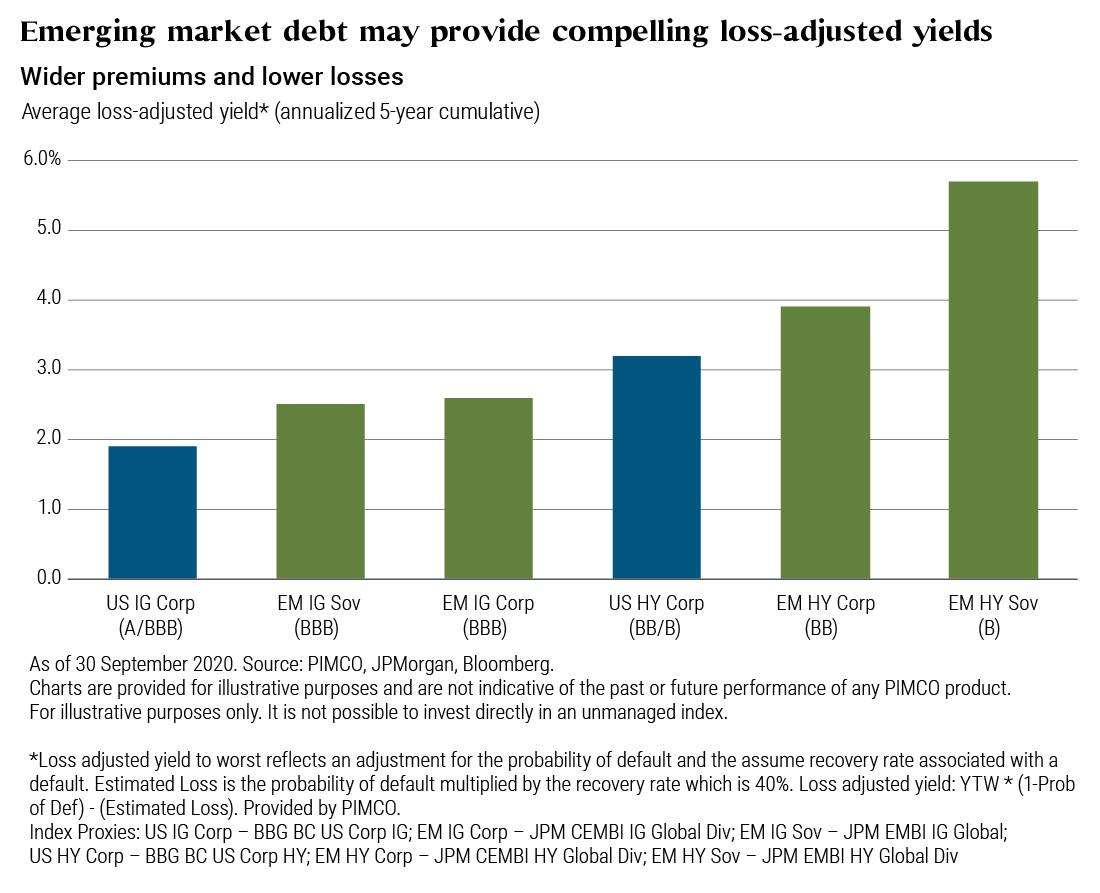
Debt of many emerging market countries can offer robust yields and enhance portfolio diversification, provided the asset manager has the resources and sophistication to avoid potential pitfalls.
Commentary
Implementation Matters: A Review of the Performance of Alternative Risk Premia Strategies in 2020
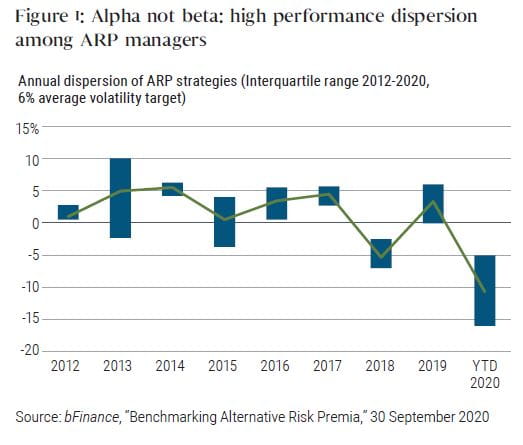
Wide performance dispersion underscores the importance of portfolio construction.
Commentary
What China’s 14th Five-Year Plan Means for Investors
It will continue to be important to be an active investor during this period of transition and to carefully monitor the impact of policy on credit sectors.
Commentary
Distressed Credit Opportunities on Rise Amid Uncertainties in Middle Markets
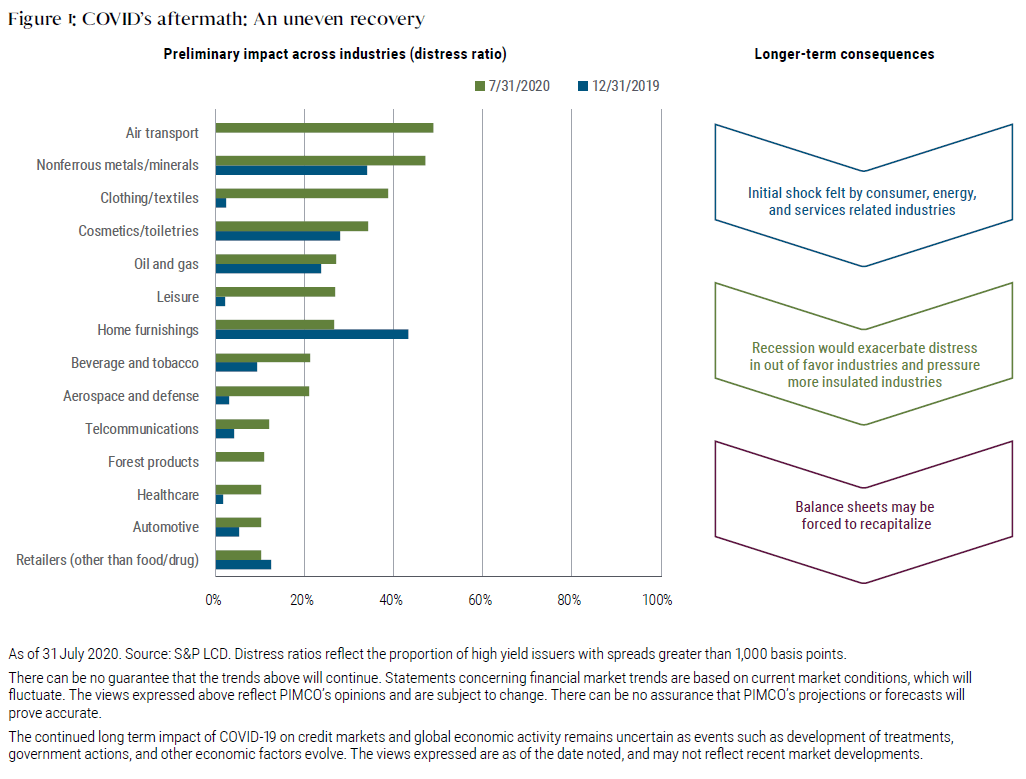
Liquidity issues and other business risks could prompt a wave of defaults and restructurings, in turn creating fertile ground for opportunistic investing in distressed credit.
Commentary
Income Fund Update: Navigating an Uneven Recovery
We are cautiously optimistic about economic growth over the next year, but over the longer term, disruptive factors will likely contribute to heightened volatility and lower returns across both fixed income and equity markets.
Commentary
How Active Short‑Term Strategies Can Fill the Void Left by the Diminished Money Market Landscape
Amid an environment of near-zero benchmark and T-bill yields, for a modest increase in risk, PIMCO's short-term strategies may offer higher levels of total return and income for stepping beyond the confines of money market fund strategies.
Commentary
Monthly Municipal Market Update, October 2020
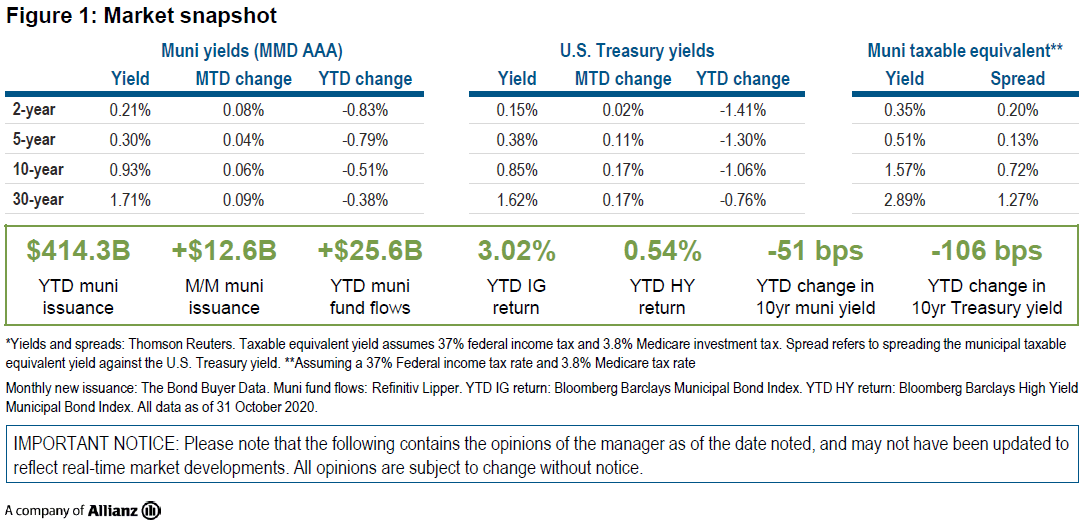
A brief monthly update on what's happening in the municipal bond market.
Commentary
First the Election, Now the Governing: Fiscal Policy Priorities, Challenges, and Implications
Washington will likely focus on fiscal stimulus immediately – but given the realities of governing and the pandemic, economic recovery will take time.
Commentary
Bundled LDI Portfolios: An Antidote to Historically Low Treasury Yields?
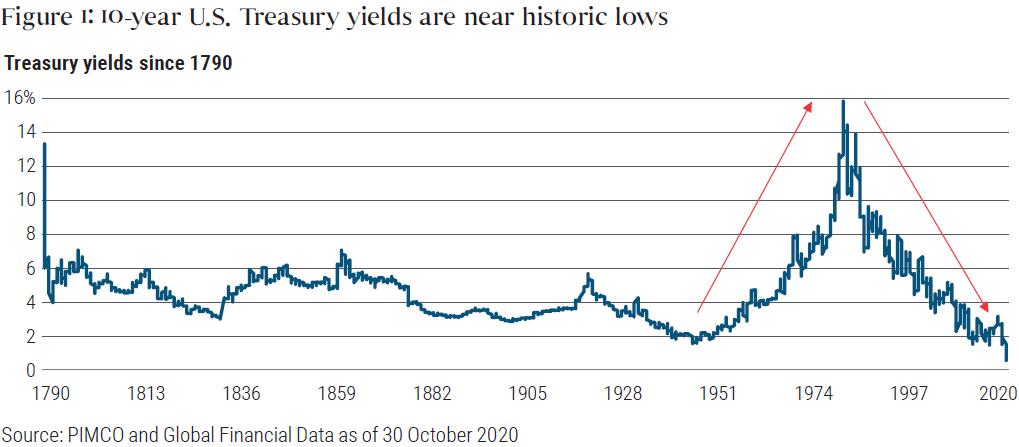
Bundling may help plan sponsors unlock alpha potential and supplement low returns from long Treasury bonds.
Commentary
The Tax Man and Urban Flight: Fact and Fiction of Outmigration Trends
Conventional wisdom says urban residents will flee cities in droves in response to higher taxes and the COVID-19 pandemic. But will that really come to pass?
Commentary
Examining the Global Outlook and Long-Term Disruptors
PIMCO’s Global Advisory Board discusses the longer-term outlook for major economies and geopolitical developments.
Commentary
Will the Bank of Canada Follow the Fed Into a New Inflation Targeting Regime?
Canada’s central bank looks to evolve its policy framework amid concern over disinflationary trends.
Commentary
Escalating Disruption
The pandemic has amplified four long-term macroeconomic disruptors, and fiscal policy – a key swing factor – may hold the key to upside or downside surprises. Read our long-term outlook and learn implications to consider when investing.
Commentary
Assessing China’s “Structural” Monetary Policy
Policy will continue to be carefully calibrated as China walks a tightrope between supporting growth and maintaining financial stability.
Commentary
Emerging Market Bonds: Part of a Resilient Portfolio?

A basket of emerging market bonds may offer the same appeal investors have long sought from U.S. Treasuries.
Commentary
The New Sustainable Finance Principles
Launched in September 2020, the CFO Principles for Integrated SDG Investments and Finance are designed to help create a market for corporate SDG (Sustainable Development Goal) investments.
Commentary
Should the Fed Buy Treasuries or Agency MBS During QE? Yes
We believe the Fed’s mortgage purchase program is helping to bolster economic activity, and accomplishing more than Treasury purchases alone.
Commentary
The Fed's New Guidance: Surprising Is Not Convincing
The lack of market reaction suggests that many investors are not convinced that the Fed’s new guidance represents any material shift in policy.
Commentary
Monthly Municipal Market Update, August 2020
A brief monthly update on what's happening in the municipal bond market.
Commentary
Back‑to‑School Challenges Are Serious, But They Shouldn’t Scare Municipal Investors
Although the pandemic could make for a chaotic return to school, it is unlikely to create significant municipal credit stress.
Commentary
Back-to-School Challenges Are Serious, But They Shouldn’t Scare Municipal Investors
Although the pandemic could make for a chaotic return to school, it is unlikely to create significant municipal credit stress.
Commentary
Monetary Policy Framework: The Fed Says What, But Needs Help on How
The Federal Reserve released the results of its multiyear framework review alongside a speech by Fed Chair Jerome Powell at the Kansas City Fed’s Economic Policy Forum on 27-28 August. While the announcement came earlier than anticipated, the conclusions were in line with the evolutionary, not revolutionary, changes to the Fed’s framework we have long been expecting.
Commentary
Gold Still Shines Bright
Despite reaching record highs earlier this month, gold remains attractively valued, according to our framework.
Commentary
All Asset All Access: Tactical Repositioning in a Changing Global Market

Research Affiliates discusses the increase in portfolio tactical shifts and recent research efforts supporting the All Asset strategies in today’s evolving investment environment.
Commentary
Monthly Municipal Market Update, July 2020

A brief monthly update on what's happening in the municipal bond market.
Commentary
A Slow and Uneven Recovery Still Likely Despite July’s U.S. Price Bounce
Rising prices in July have led PIMCO to raise its core inflation forecast for 2020, but not 2021.
Commentary
Income Fund Update: Focused on Finding Opportunities in Today’s Markets
Looking across the global opportunity set, we see potential for attractive yield, though uncertainties surrounding the global recovery suggest this is a time to be cautious.
Commentary
Fed Reinforces Commitment to Ongoing Monetary Policy Support
The Federal Reserve wants financial conditions to remain accommodative as it looks to support the U.S. recovery.
Commentary
Worried About Retirement? PIMCO’s Plan to Help Retirement Savings Last a Lifetime
PIMCO’s CEO and its head of retirement outline the firm’s approach to generating retirement income.
Commentary
Europe’s Labor Measures: Short-term Gain, Long-term Pain?
European measures applied to mitigate the effects of the pandemic have contained the unemployment rate in Europe more than in the U.S. While recognizing economic risks from the rising number of COVID-19 cases in the U.S., our forecast sees this success ratio reversing before the end of the year.
Commentary
The Imprint of Monetary Policy on Munis
Municipal bond investors will need to contend with the impact of monetary policy on market prices.
Commentary
June CPI Report Underscores Economic Fragilities
We expect more stimulus, both monetary and fiscal, will be necessary to support the recovery amid the renewed COVID-19 outbreak.
Commentary
Building Resiliency Amid Uncertainty
After a decade of steady growth and rising asset prices, economies and financial markets were rocked by the COVID-19 pandemic. The global health crisis forced most governments to lock down their communities, halting economic activity almost overnight and causing financial markets to reprice lower at an unprecedented speed.
Commentary
Public-Private Solutions to Safeguard Economies Everywhere
The health crisis creates opportunities to unite historically disparate investor groups to help build economic and market sustainability and resiliency.
Commentary
Cyclicals 2.0: Green and Digital
The text book rules about where to invest following a recession may not apply in a post-pandemic world; more than bricks and mortar, stimulus efforts are green and digital now.
Commentary
Monthly Municipal Market Update, May 2020
A brief monthly update on what's happening in the municipal bond market.
Commentary
The Long Climb
While a near-term mechanical bounce in economic activity in response to the lifting or easing of lockdown measures looks likely, we expect the subsequent climb up to be long and arduous.
Commentary
Fed Shifting Focus From Crisis Management to Easy Financial Conditions
We expect the Federal Reserve will continue to conduct asset purchases at its current pace through year-end, and eventually commit to keeping interest rates on hold through 2022. This should help ensure easy financial conditions and support the economic recovery.
Commentary
Manager Diversification in LDI Portfolios: Consume in Moderation
Over diversifying an LDI manager roster may have important hidden costs.
Commentary
Seeking Long‑term Value in a Gradually Healing Economy
This strategy aims to help investors participate in the ongoing recovery of the global economy, offering potential for attractive yield while managing downside risks.
Commentary
Monthly Municipal Market Update, April 2020
A brief monthly update on what's happening in the municipal bond market....
Commentary
Post‑COVID Economy: Not the Way We Were
The COVID-19 crisis is likely to accelerate many underlying, secular disruptive forces already affecting economies and financial markets. This may only increase the difference between those companies, sectors, and countries that are being disrupted, and those that are acting more like disruptors. Distinguishing between the two is becoming crucial.
Commentary
Six Key Questions on U.S. Policy and the Economic Outlook
The U.S. political focus has shifted to the reopening of the economy.
Commentary
All Asset All Access: Positioning Portfolios for Opportunity in Stormy Markets
Research Affiliates discusses how the All Asset portfolios seek to capitalize on opportunities amid pandemic-related market volatility and a strengthening U.S. dollar.
Commentary
Municipal Yields Rising
Weak technicals are creating an opportunity in long-duration municipal bonds.
Commentary
Monthly Municipal Market Update, March 2020
A brief monthly update on what's happening in the municipal bond market.
Commentary
Looking Beyond the Many Recessions
Major economies are contracting, but extraordinary policy responses could limit severe recessions to this year.
Commentary
Post‑Pandemic Interest Rates: Lower for Longer
Evidence from decades and even centuries ago, plus the unique circumstances of the current global health crisis and its economic impact, suggests we can expect a “New Neutral 2.0” of lower interest rates for longer.
Commentary
The U.S. Likely Faces a Deep, Hopefully Short Recession
The U.S. labor market disruption is the worst the country has experienced in recent memory, suggesting that the decline in overall activity could also be much more severe.
Commentary
Finding the Right Level of Support for Capital Markets and Mortgage Rates
The Fed has moved aggressively to stabilize core assets, including mortgages. Yet several market indicators are still concerning.
Commentary
From Hurting to Healing
Our baseline economic forecast is a U-shaped global recovery, but substantial unknowns remain.
Commentary
Economic Fallout: Here Comes Congress!
The $2.2 trillion stimulus is the biggest ever, but Congress will likely be forced to do even more.
Commentary
Making Sense of the Move in Munis
Liquidity could remain challenged, but valuations may be attractive for long-term investors.
Commentary
In Europe the Crisis Policy Response Is Substantial, But More Is Likely Needed
The conditions for a relatively quick and robust rebound rest on the success in containing the virus within a reasonable horizon, and a well-calibrated economic policy response.
Commentary
The Fed: Avoiding a Depression
The Fed’s aggressive support may help keep markets functioning, hasten recovery and avoid longer-term damage.
Commentary
All Asset All Access, March 2020
Research Affiliates assesses the potential impact of COVID-19 on economies and investments, and what it means for the All Asset strategies.
Commentary
Economic Fallout: Here Comes Congress?
A bolder fiscal response to the rapidly spreading coronavirus has become an economic and political imperative.
Commentary
Policymakers: Pulling Out All The Stops
Governments and central banks have started to respond more forcefully to the health crisis, enacting policy in an effort to limit long-term damage to the global economy.
Commentary
Oil Prices: Lower for Longer
As the oil surplus builds, we expect U.S. crude oil to linger at $30-$40 per barrel for the next several months.
Commentary
Fiscal and Monetary Together
The Bank of England and the British government both announced easing measures to counter the effects of the coronavirus on the economy – how effective can we expect these measures to be?
Commentary
When Rate Cuts and Quantitative Easing Fall Flat
Fed rate cuts may be less effective at boosting the economy or markets as societies grapple with the spread of COVID-19, but other policy measures may help.
Commentary
Economic Outlook Update: ILU Trajectories
Global growth could follow a U-shaped path over the next few quarters, though substantial uncertainty remains as policymakers grapple with the impact of the coronavirus.
Commentary
Momentum Favors Biden for Democratic Nomination, But the Race Isn’t Over
Senator Joe Biden is the current front-runner in a two-person race for the Democratic nomination, but upcoming state contests are crucial.
Commentary
Gender Equality: Celebrating Progress and Looking Ahead
In recognition of International Women’s Day on 8 March, Cady Johnson shares her perspective on gender equality in the financial services industry.
Commentary
Fed Moves First to Counter COVID-19 Market Fears
The Federal Reserve wants to avoid a crisis of confidence.
Commentary
The Fed Has Another Lever to Pull
The Fed could give the economy a powerful boost by maintaining the mix of assets on its balance sheet.
Commentary
Investing in a Diverse Future
In recognition of International Women’s Day on 8 March, Candice Stack and David Forgash discuss the internship program PIMCO hosts in partnership with Girls Who Invest.
Commentary
What Does the Puerto Rico HTA Ruling Mean for Special Revenue Bonds? Likely Not as Much as Feared
Municipal bond investors worried by the 1st U.S. Circuit Court of Appeals’ affirmation of a lower court’s decision regarding the Puerto Rico Highway Transportation Authority should rest a bit easier: The ramifications will likely be limited.
Commentary
Asset Allocation Views: Prolonging the Expansion
Read our key takeaways from our 2020 Asset Allocation Outlook, including how we are positioning multi-asset portfolios in light of our outlooks for the global economy and markets.
Commentary
Growth, Inflation, and the Potential for Disruption
Three key themes from our latest Cyclical Outlook will likely drive the global economy and central bank policy in the year ahead.
Commentary
New Year, New Risks
A review of last month’s market-moving events across countries and asset classes.
Commentary
March May Matter More for Investors Watching U.S. Primaries
We think investors should not extrapolate too much from who wins the early contests, including Iowa.
Commentary
Dispatch From Davos: Sustainability in Sharp Focus
How can leaders in finance embrace the Davos 2020 theme of “Stakeholders for a Cohesive and Sustainable World”? Here are our key observations.
Commentary
Fed Balance Sheet in Focus
As the Fed winds down its T-bill and repo programs, we don’t anticipate market volatility to emerge – at least not as a result of the Fed’s actions.
Commentary
Oil Prices and the Ripple Effects of ESG
Questions about environmental, social, and governance (ESG) issues are becoming central to commodity markets and capital allocation discussions.
Commentary
China: Buying Time Is Not Cheap
In prioritizing stability over all other objectives, China is borrowing from future growth while reducing policy ammunition to counter future shocks.
Commentary
Rating Events: One Theme to Follow in Global Credit Markets in 2020
Alongside pockets of weakness in credit markets come pockets of opportunity for active managers who focus on rigorous bottom-up research and careful credit selection.
Commentary
Key Geopolitical Risks to Oil in 2020
Tensions in the Middle East and North Africa have once again brought geopolitical risks to the forefront of oil markets.
Commentary
Monthly Municipal Market Update, December 2019
A brief monthly update on what's happening in the municipal bond market.
Commentary
All Asset All Access, January 2020
Research Affiliates provides its outlook for 2020 and discusses where it sees attractive return opportunities across the globe.
Commentary
Seven Macro Themes for 2020
The outlook for the global economy has improved over the past three months, but there may be less capacity to combat a recession when it comes. We discuss seven key macroeconomic themes we expect in 2020 and implications for investors.
Commentary
Target Date Funds: Blend Is the Trend
DC plan sponsors are increasingly using TDFs that blend active and passive strategies to seek lower fees and enhanced alpha potential.
Commentary
Investors May Benefit as Muni Issuers Turn to Taxable Markets
Muni issuers are increasingly refinancing tax-exempt munis in the taxable market, but both areas offer potential benefits.
Commentary
Year‑End Tailwind: De‑Escalating Policy
The U.S.-China trade deal is one of three diminishing policy risks, but investors shouldn’t assume that all policy uncertainty has been eliminated.
Commentary
The End of the Beginning
While the election result reduces Brexit uncertainty significantly, it doesn’t eliminate it. Will there be an extension of the transition period? How will any deal affect the economy? In the meantime, UK banks and sterling, especially wounded since the 2016 referendum, still offer value, while low-yielding gilts look unattractive relative to other government debt, such as U.S. Treasuries.
Commentary
Federal Reserve Appears Confident in U.S. Economy's Soft Landing
In its December forecasts, the Federal Reserve estimates that the policy rate will hold steady through 2020. Will economic and trade developments change that view?
Commentary
Changing Speeds?
A review of last month’s market-moving events across countries and asset classes.
Commentary
All Asset All Access, December 2019
Research Affiliates discusses why they believe value investing is still alive and well and explains how changes to the display of expense ratios seek to enhance clarity for investors.
Commentary
Salve for a Constrained Repo Market, or Potential Funding Destabilizer?
The recent repo squall shined a spotlight on “sponsored repo” transactions, a growing segment of the U.S. overnight funding market.
Commentary
Treading Carefully: Risk and Opportunity in CLOs and Bank Loans
While many risk assets have rallied in 2019, the lower-rated tranches of collateralized loan obligations (CLOs) have weakened. Is this a sign that the credit cycle is turning?
Commentary
Navigating U.S. Wealth Management: Seven Ideas for Financial Advisors and Individual Investors in 20
We aim to support wealth management firms, advisors, and investors as they assess portfolio strategy and navigate the shifting trends we face in the new year.
Commentary
Third‑Quarter Earnings Eased Market Fears, But Will the Reprieve Last?
Equity and credit markets have thus far taken lackluster earnings results and lower expectations in stride, but we think this could change if confidence readings drop further.
Commentary
Making the Most of Model Portfolios
Models can help advisors streamline portfolio management while retaining the level of discretion appropriate for their practice.
Commentary
Resilient Private Income in Late-Cycle Markets
Private markets remain a key source of income for institutional portfolios, but late-cycle concerns demand a thoughtful approach to opportunities and risks.
Commentary
Monthly Municipal Market Update, October 2019
A brief monthly update on what's happening in the municipal bond market.
Commentary
Beneath the Surface
A review of last month’s market-moving events across countries and asset classes.
Commentary
All Asset All Access, November 2019
Research Affiliates discusses how its research partnerships with academic thought leaders inform its process and examines the All Asset strategies’ returns per unit of equity beta.
Commentary
Income Fund Update: Taking a Patient Approach as Growth Slows
With global growth slowing and significant uncertainty around trade and politics, PIMCO’s Income Fund is taking the long-term view and positioning defensively.
Commentary
After Three Cuts in a Row, Is the Fed Done Easing?
Fed Chair Powell signaled that another “insurance” rate cut is unlikely. Instead, further rate cuts are contingent on a more material deterioration in the economic outlook.
Commentary
U.K. Elections: What’s Next for Economy and Markets?
The U.K. is set to head to the polls on December 12. Here are our key takeaways for the economy and markets.
Commentary
Financial Advisors and Retirement: The Decumulation Dilemma
Our Income to Outcome framework seeks to deliver a simpler, more intuitive approach to investing for retirement.
Commentary
A Shift in Approach Could Help Keep Short-Term Markets Liquid
We think there are policy tools in the Fed arsenal that wouldn’t materially alter the soundness of the banking system but could allow cash to move more freely.
Commentary
10 Key Investor Takeaways From the 2019 Annual Meetings of the IMF and World Bank
Trade, geopolitics, and emerging markets were top of mind at the recent annual meetings
Commentary
Are Investors Being ‘Aggressively Passive’ in Bond ETFs?
For bond allocations, think twice before reflexively allocating to index ETFs.
Commentary
China CPI Breaks 3% PBOC Target: What Does It Mean for Policy?
Headline inflation resulting from a food price shock can never be ignored fully.
Commentary
Germany: Back to “Sick Man of Europe”?
Germany’s economy is on the brink of recession. We expect a gradual recovery through the next year, but this is dependent on easing trade tensions.
Commentary
Could the Fed Pivot on Balance Sheet Policy for Mortgage Securities?
The Fed has another lever to pull to ease monetary policy, one that could increase savings rates and create more disposable income.
Commentary
U.S.−China Trade Deal: A Temporary Reprieve
Without pouring water on the “love fest,” we contend that the deal struck between China and the U.S. leaves much to be desired.
Commentary
Monthly Municipal Market Update, September 2019
A brief monthly update on what's happening in the municipal bond market.
Commentary
A Tale of Two Halves
A review of last month’s market-moving events across countries and asset classes.
Commentary
All Asset All Access, October 2019
In this issue, Research Affiliates discusses why its contrarian philosophy may add value over the long term and how the growing likelihood of a global economic slowdown is affecting positioning.
Commentary
UN Climate Summit: Business and Investors Lead on Action
Businesses and investors are moving ahead with progressive actions despite policy vacuums.
Commentary
Steering Away From Volatile Markets: Short-Term Bonds May Offer Value As Fed Eases
Short-term bonds could rise in price and potentially maintain a high degree of liquidity in response to Federal Reserve rate cuts.
Commentary
Window of Weakness
In a nutshell, we concluded that the global economy is about to enter a low-growth “window of weakness,” which we expect to persist going into 2020 with heightened uncertainty about whether it is a window to recovery or recession.
Commentary
Model Portfolios May Help Advisors Avoid Costly Fixed Income Timing Traps
We believe a disciplined approach to bond investing is critical to achieving desired return and risk objectives. Model portfolios may help.
Commentary
Three ESG Takeaways from PRI in Person 2019
This year, in Paris, we were excited to participate as an industry expert and to engage with attendees on ESG (environmental, social, and governance) investing in fixed income.
Commentary
September Fed Meeting: Divisions Over the Path of Policy
Weakness in the U.S. economy leaves it vulnerable to shocks. We think the Fed will respond with additional easing this year.
Commentary
Repo Rate Spike: A ‘Tail’ Of Low Liquidity
Markets can prove interesting when the price of liquidity abruptly increases and high yield is no longer the highest-yielding investment.
Commentary
Three ESG Takeaways from PRI in Person 2019
This year, in Paris, we were excited to participate as an industry expert and to engage with attendees on ESG (environmental, social, and governance) investing in fixed income.
Commentary
Saudi Oil Site Attacks Exacerbate Tightening Supply, Add to Price Risk Premium
Attacks and outages could add to the longer-term geopolitical risk premium in oil prices.
Commentary
European Central Bank Policy: QE Infinity
That fiscal policy is becoming the new monetary policy when it comes to fighting recession was a key conclusion of PIMCO’s Secular Forum, and this was the message ECB President Mario Draghi underlined through both actions and words.
Commentary
Oil Supply Outlook: Is Your Barrel Half Full or Half Empty?
Continued tight crude balances could be the bigger surprise to the market.
Commentary
Maximizing U.S. Treasury Allocations to Hedge Equity Risk
Equity-risk mitigation may be improved by combining positive expected return strategies that are negatively correlated with equities.
Commentary
Disruption in the Eurozone: Challenges of an Arranged Marriage
Two decades after inception, the eurozone countries’ arranged marriage-type of union looks shaky at best, and now it is even more challenged by ongoing, global disruptive forces.
Commentary
Asset Allocation Views: Easing Into Slowing Growth
Read our key takeaways from our 2019 Asset Allocation Midyear Update, including how we are positioning multi-asset portfolios in light of our outlooks for the global economy and markets.
Commentary
Global Fetters: Insights From Jackson Hole
The institutional “golden fetters” of the interwar period have been replaced by fundamental “global fetters” that severely constrain monetary policy.
Commentary
Muni Midyear Outlook 2019: Three Key Takeaways
We see several areas of opportunity for muni investors in the second half of 2019.
Commentary
Yield Curve Inversion: Markets Are Correct to Price In Higher Recession Risk
The risk of recession has risen, but it’s not a foregone conclusion.
Commentary
Strong Core CPI Inflation Won’t Sway the Fed From Rate Cuts
We think the Federal Reserve will look past stronger-than-expected consumer price increases in June and July.
Commentary
ECB Signals Easing, But What’s Left in the Policy Arsenal?
Come the fall, the ECB will likely deliver yet another easing package that could effectively deplete its monetary policy toolbox.
Commentary
Summer of Discontent: Market Volatility Underscores Fragility of Aging Expansion
The last few days have highlighted the inherent fragility in markets – and the growth outlook globally.
Commentary
Interest Rates: Naturally Negative?
It is no longer absurd to think that the nominal yield on U.S. Treasury securities could go negative.
Commentary
Trade Tension Flare‑Up: Not So Surprising
We think investors should take President Donald Trump at his word that he will move forward with the next round of tariffs on China come September.
Commentary
The Fed’s Rate Cut: Growth ‘Insurance’
We find the Fed’s statement clear, and we expect another rate cut as soon as September with possible additional cuts thereafter.
Commentary
U.S. Dollar Policy: Through the Looking Glass of U.S. Currency Intervention
The market consequences of direct intervention by the U.S. could be substantial and thus bear consideration.
Commentary
Signs of Stress in U.S. Economy Bolster Expectations for Fed Rate Cut
The Federal Reserve is poised to cut interest rates at its July meeting. But how much will it cut?
Commentary
Core CPI Inflation Beats Expectations, in Awkward Timing for the Fed
June inflation may have been boosted by the recent increase in import tariffs, while inflationary pressures from rising wages and tight labor markets remain notably subdued.
Commentary
Oil Sell‑Off Sparks Investment Opportunities
Demand concerns, trade tensions, and strongly implied U.S. production are driving an oil sell-off, much like in fourth-quarter 2018, but the complicated backdrop may create investment opportunities.
Commentary
Interest Rate Outlook: Fed Evaluating Risks to U.S. Economy
We don’t expect a Fed rate cut in June, but if downside risks to the economy escalate, a 50 basis point cut in July is possible, in our view.
Commentary
New U.S. – Mexico Tariffs Would Add to Economic Costs
New U.S. tariffs on Mexico would add to the direct economic costs of the string of tariff hikes enacted during this administration.
Commentary
The Pivot in U.S.-China Trade Policy May Herald Long‑Term Tension
With the U.S. and China raising tariffs on each other’s goods, we may be entering a prolonged period of trade tension.
Commentary
Fed Evaluates Policy and Portfolio Strategy
A quiet and unsurprising FOMC statement belies the important policy discussions and decisions ongoing at the Fed.
Commentary
Falling Angels? Credit Market Risks and Opportunities
We believe the spotlight on the burgeoning BBB credit market has diverted attention from the risks in the smaller single-A market.
Commentary
Falling Angels? Credit Market Risks and Opportunities
We believe the spotlight on the burgeoning BBB credit market has diverted attention from the risks in the smaller single-A market.
Commentary
Rationality and Retirement: Mutually Exclusive?
Behavioral finance may help to overcome cognitive biases.
Commentary
U.S. Housing: Potential Opportunity Amid Cautious Economic Outlook
Even as the probability of a recession in the near-term remains low, we believe investors should look to sectors that are likely to be resilient in periods of higher volatility.
Commentary
Three Key Takeaways From PIMCO’s Cyclical Outlook: Flatlining at The New Neutral
Following the Federal Reserve’s pivot to patience, we believe U.S. short-term interest rates are now anchored in The New Neutral. Global growth keeps synching lower, but may experience a soft landing later this year if China’s economy stabilizes and trade tensions ease.
Commentary
Emerging Markets Outlook: The Wealth of Nations
While we are constructive on the prospects for emerging markets in the year ahead, we think the real potential lies in individual country and thematic opportunities.
Commentary
Navigating Uncertainty in Inflation Markets: The UK Case
Investors in UK inflation-linked bonds are facing two critical sources of structural uncertainty: Brexit-induced volatility and questions about the deeply entrenched (yet problematic) Retail Price Index (RPI
Commentary
Flatlining at The New Neutral
We believe short-term interest rates in the U.S. are now anchored in The New Neutral, as global growth keeps synching lower.
Commentary
Navigating Uncertainty in Inflation Markets: The UK Case
Investors in UK inflation-linked bonds are facing two critical sources of structural uncertainty: volatility arising from the Brexit process, and questions about the deeply entrenched (yet problematic) Retail Price Index (RPI), to which UK “linkers” are tied.
Commentary
The Style Cycle: Equity Factors and Macro Data Diverge
The divergence between recent bullish factor performance and weaker economic fundamenta...
Commentary
Balancing Act: Maintaining Liquidity and Purchasing Power with Short‑Term Bonds
Investors globally are walking a tightrope today, balancing risk-taking and risk management. As growth appears poised to slow, the outlook for financial markets remains uncertain − a situation compounded by increased cost of capital, tighter financial conditions and heightened market volatility.
Commentary
Asian Credit: High Yield Anticipated to Offer Attractive Opportunities in 2019
We favor Asian high yield over investment grade credits in spite of historical higher volatility since we view valuations as more attractive, particularly compared with U.S. high yield and emerging market peers.
Commentary
Multi-Sector Credit: Flexibility Amid Shifting Markets
We believe an active, flexible, multi-sector approach may offer investors better long-term results by focusing on structural opportunities to generate alpha.
Commentary
All Asset All Access, March 2019
In this issue, Research Affiliates assesses risks facing the All Asset strategies and shares insights from its CEO on fostering a winning corporate culture.
Commentary
Emerging Market Equities: Looking Beyond Near‑Term Fear
Over the past year, emerging market (EM) equities have been one of the most volatile segments of the global market. With news headlines dominated by the International Monetary Fund’s bailout of Argentina and Turkey’s sudden interest rate increase and currency depreciation, EM equities dramatically sold off in 2018 – down 14.6% for the year.
Commentary
International Women’s Day 2019: Global Perspectives on Women in Finance
In recognition of International Women’s Day on 8 March, PIMCO leaders in three regions discuss their career experiences and the progress they see for women in finance and their own career experiences.
Commentary
International Women’s Day 2019: What It Means for Investment Management
The landscape for women in finance has changed notably over the past two decades. Today, women represent 46% of financial services employees, according to a study by Mercer. This growth, however, has been predominantly at the junior level; women represent only 15% of the top ranks in finance, and the number falls even further at the CEO level...
Commentary
Equities vs. Bonds? Look to China for Clues
Chinese stimulus could be instrumental in deciding which investors are proved right.
Commentary
Defensive Versus Cyclical: The Blurring Lines
Bond investors will need to be very selective due to recent changes in sector credit quality.
Commentary
Equities vs. Bonds? Look to China for Clues
Chinese stimulus could be instrumental in deciding which investors are proved right....
Commentary
Impact Investing: Imagining the Next Evolution in Economies and Finance
Impact investing is anchored in a fundamental belief that over the long term, healthy societies and healthy markets go hand-in-hand.
Commentary
Munis and the Markets, January 2019
A brief monthly update on what's happening in the municipal bond market.
Commentary
Core CPI May Tick Up Before Moderating in the Second Half
The decline in oil prices continues to weigh on headline Consumer Price Index (CPI) inflation, which fell 0.3 percentage point to 1.6% year-over-year in January. However, core CPI (which excludes energy and food prices) held steady at 2.2% year-over-year, with support from normalization in retail prices after holiday discounting late last year.
Commentary
EU Elections: Populism’s Threat May Be Overstated
The European parliamentary elections may cause near-term market jitters, but we do not think the outcome will be a game-changer.
Commentary
Good Things Come to Those Who Are Patient
A review of last month’s market-moving events across countries and asset classes.
Commentary
All Asset All Access, February 2019
In this issue, Research Affiliates assesses the potential impact of a bear market in U.S. stocks on emerging markets and discusses regulatory reporting requirements.
Commentary
How Durable Is the Fed’s Dovish Turn?
The Federal Reserve’s recently communicated change in its outlook for monetary policy has led to concerns that the Fed is overreacting to market volatility, or worse, succumbing to political pressures. However, we believe there is a more compelling reason for the dovish shift.
Commentary
Asset Allocation Views: Late Cycle vs. End Cycle Investing
Here are key takeaways from our 2019 Asset Allocation Outlook on how we are positioning asset allocation portfolios in light of our outlook for the global economy and markets.
Commentary
Multi‑Strategy Alternative Funds: Not All Are Created Equal
Today’s late-cycle environment gives investors an opportunity to re-evaluate the risk and return potential of their portfolios. Since the depth of the financial crisis, core stock and bond allocations have delivered exceptional returns with modest volatility. But future returns will likely be muted even as risk increases.
Commentary
Dispatch from Davos: Retooling Globalization
Discussions and debates at this year’s World Economic Forum took a soul-searching turn with Davos organizers and delegates agonizing over the future of globalization in a world marked by nationalism, protectionism and social tensions based on economic imbalances.
Commentary
What Can Marshmallows Teach Us About Social Security Deferral?
Akin to the famed Stanford Marshmallow study on delayed gratification, deferral of Social Security income often maximizes lifetime benefits, particularly for those with above-average life expectancy.
Commentary
With Canada’s Economy in Transition, the Neutral Rate is Key in 2019
We are skeptical Canada can shift its growth model, and our investment outlook for Canada is cautious as a result.
Commentary
The Fed: Patient Amid Rising Uncertainty
Following this week’s meeting of the Federal Open Market Committee (FOMC), the Fed issued a statement that more forcefully signaled its intention to be cautious in the face of a more uncertain outlook. Policymakers also signaled that they view the current stance of monetary policy as more or less neutral. Therefore, investors should expect the Fed to keep rates steady, for now.
Commentary
China’s Growth Playbook: How to Get Out of a Fix
In recent months China has rolled out tax cuts and incentives to boost consumption over investment while taking steps to further open its capital markets – a shift in approach that seems to accept a natural slowing in growth over time and to acknowledge the costs of an overreliance on credit growth.
Commentary
Income Fund Update: Building Resiliency in Volatile Markets
We expect market volatility to continue in 2019, creating opportunities for the Income Fund.
Commentary
Delaying the ECB’s Liftoff
In his first press conference of 2019, European Central Bank (ECB) President Mario Draghi said risks surrounding the eurozone growth outlook have shifted to the “downside,” versus the “broadly balanced” risks he discussed just one month ago when the bank ended net asset purchases.
Commentary
Agency MBS: Time to Rethink Prepayments
In our view, a combination of positive macroeconomic factors is likely to keep prepayment speeds higher than the market projects.
Commentary
U.S. Policy Outlook for 2019: Trade Risks Continue, But Might Not Escalate
In our outlook for 2019, we believe politics and policy out of Washington will continue to drive – and in some cases, weigh on – markets, much like they did in 2018. Investigations and manufactured crisis are likely to contribute to uncertainty. Trade tensions persist, though on a more positive note, relations between the U.S. and China seem to be improving.
Commentary
The Fed: Poised to Pause in March
With the effective fed funds rate now only slightly below the range of estimates for neutral monetary policy and few signs of economic or financial market overheating, we believe that the Federal Reserve is likely to hold rates steady in March, interrupting its pattern of quarterly interest rate hikes.
Commentary
Investing in Decisions
Richard Thaler and Emmanuel Roman discuss behavioral science and investing.
Commentary
Another Hike: When Will the Fed Pause – or Stop?
Tighter financial conditions and slower global growth have weakened arguments that U.S. monetary policy will be restrictive in the coming years to alleviate the risk of economic overheating or growing financial imbalances.
Commentary
Five Key Takeaways from PIMCO’s Cyclical Outlook: Synching Lower
Five key macro debates are likely to shape the economic and market outlook for 2019.
Commentary
Truce Be Told
-Global market performance remained challenged amid lingering volatility. -Concerns about softer growth, coupled with comments from the Fed, tempered market expectations for the path of future rate hikes. -An assortment of geopolitical developments continued to capture attention in November.
Commentary
Munis and the Markets, November 2018
A brief monthly update on what's happening in the municipal bond market.
Commentary
Brexit: In All the Noise, Has That Much Changed?
We believe markets are now broadly priced for an extended period of the status quo – where the current impasse remains, but the UK remains in the EU.
Commentary
High Yield and Bank Loans: A Tale of Two Markets
Recent fundamental changes in the leveraged finance markets mean that actively managing credit exposure is more important than ever.
Commentary
Longer‑Term Risks Complicate ECB's Policy Path: Beware the Pillars of Hercules
Will the ECB have sufficient firepower – and support from the population – to spur the economy when the next recession arrives?
Commentary
Synching Lower
We see a synchronized global slowdown in 2019. We position cautiously but anticipate opportunities ahead.
Commentary
Corporate Reporting on the SDGs: Mapping a Sustainable Future
PIMCO has mapped the SDG sustainability reporting of 246 companies globally with the goal of encouraging enhanced disclosure.
Commentary
What OPEC’s ‘Third Way’ Means for Investors
OPEC and key partners opted for a middle path coming out of the 175th meeting of the OPEC Conference, agreeing to cut oil production by 1.2 million barrels per day (bbl/d) from October levels (an even steeper cut than versus November levels). We expect the move to support prices in the low $60s/bbl for Brent crude and in the mid-$50s for WTI.
Commentary
Emerging Markets: Vulnerable to External Factors?
The combination of trade tensions, U.S. rate hikes and weaker global trade growth has weighed on emerging markets (EM) this year.
Commentary
Engineering Inflation: For the Fed, the Time Is Now
As the Federal Reserve embarks on a review of its long-run monetary framework, questions about its inflation target are resurfacing. We believe now is the time for change.
Commentary
Powell’s Speech Lifted Markets, But We Expect Gradual Rate Hikes to Continue
Federal Reserve Chairman Jerome Powell’s speech on 28 November helped stir a market rally as investors interpreted his comments as more dovish and favorable to risk assets.
Commentary
Preparing Portfolios for Resilience Against Inflation Surprises
Many investment portfolios that rely heavily on stock-bond diversification to manage risks may not be protected against inflation surprises. Real assets offer a solution.
Commentary
Munis and the Markets, October 2018
A brief monthly update on what's happening in the municipal bond market.
Commentary
Mexico: ‘Tequila’ Sunrise?
The incoming Mexican government’s costly plan to cancel the new Mexico City airport has fueled concerns that President-elect Andrés Manuel López Obrador will enact a populist agenda and squander the country’s sound financial position.
Commentary
Asset Allocation: Following the Cash to Find Quality in Equities
Asset allocation decisions can be challenging for investors during the later stage of the business cycle. Focusing on quality is likely the best way to manage the transition from late expansion to a potential recession.
Commentary
Packing for the Holidays: Reducing Risk with Short‑Term Bonds
As we approach the holiday season, most investors are beginning to think about escaping to somewhere far and exotic or spending time with family and friends. Unfortunately, while our social calendars are working overtime, markets don’t always take a break during the festive season.
Commentary
Core CPI Rebounds on Used Car Bump, While Tariffs’ Impact Is Mixed
Core U.S. Consumer Price Index (CPI) inflation rebounded in October, though not as much as expected, driven largely by a bounce in used car prices. The year-over-year rate ticked down to 2.1%, and evidence of tariff-related price increases was mixed.
Commentary
Into the Red Zone
Volatility returned and pulled markets across the globe into the red. Slowing growth momentum outside the U.S. further weighed on sentiment. Political developments from Latin America to Europe were a source of both uncertainty and assurance for markets.
Commentary
Credit Markets: To BBB or Not to BBB?
Financial media and investors have been focusing on the BBB segment of the U.S. investment grade (IG) corporate bond market this year.
Commentary
How Markets May React to a Brexit Deal
We expect volatility as the process moves forward, along with a potential rise in UK sovereign yields and strengthening of the pound, though some Brexit-related risk premium is likely to remain.
Commentary
An Innovative Approach to Enhancing Small Cap Allocations
Index returns and traditional active management may fall short, so PIMCO StocksPLUS Small takes a different path to seek small cap alpha.
Commentary
China: Current Account Deficit Will Pressure the Yuan and Refashion Global Portfolio Flows
For investors focused on Sino-U.S. trade tensions, it may come as a surprise that China ran a current account deficit in the nine months of 2018, its first since 1993. The $12.8 billion deficit is only about 0.1% of GDP on an annualized basis.
Commentary
Key Takeaways From the U.S. Midterms: What a Split Congress Means for Markets
The U.S. midterm elections played out much as expected, with Democrats picking up the 23 seats (and more) needed to retake the majority in the House of Representatives and Republicans easily defending their majority in the Senate.
Commentary
Emerging Markets: Diversification and Yield Potential for Insurance Companies
This may be an opportune time for insurance companies to consider high-grade emerging markets.
Commentary
Slower Eurozone Growth in Q3 Not a Major Concern, But Watch Italy
Eurozone GDP growth was very soft in the third quarter, coming in at 0.6% for the three months to September on a seasonally adjusted annualized basis, against consensus expectations of around 1.5%. While the release is disappointing, we caution against extrapolating this weakness in quarters ahead.
Commentary
Volatility Brings Opportunity in Bank Capital Securities
European bank capital securities, the term used to refer to subordinated debt instruments issued by financial institutions, have had a challenging 2018. Spreads on Additional Tier 1 (AT1) bonds are over 150 bps wider than in January, driven by uncertainty over Italy and Brexit negotiations, combined with heavy issuance, particularly in the U.S.-dollar-denominated market.
Commentary
U.S. Midterm Election Preview: Policy Gridlock Ahead
If you live in the United States, it is hard to escape news of the upcoming midterm elections on 6 November. But for investors, are these midterms really significant?
Commentary
A New Dawn for Brazil?
Anti-establishment candidate Jair Bolsonaro prevailed as expected in Brazil’s presidential election on 28 October, having run on a socially conservative “more Brazil, less Brasilia” platform. This included promises to reduce corruption, increase security, allow gun ownership and oppose the legalization of abortion. It was the first time since 2002 that Brazil’s Workers’ Party (PT) did not win the presidency.
Commentary
Investing Ideas for an Aging Expansion: Three Reasons to Look at Munis
The current U.S. economic expansion is now the second-longest in the postwar era, and while it may have more room to run, we believe a recession is likely over the three- to five-year horizon. As U.S. taxpayers think about positioning their portfolios, we see three key reasons why the tax-exempt municipal market may be attractive late in the cycle.
Commentary
An Improving Environment for Capital‑Efficient Equity Investing
Equity index futures are among the most liquid and cost-effective ways for investment managers to capture the returns of major stock market indexes such as the S&P 500 and Russell 2000 – especially now that financing costs have cheapened.
Commentary
Key Takeaways From PIMCO’s Cyclical Outlook: Growing, But Slowing
Global growth has not only plateaued in 2018, it has also become more uneven across regions this year. We’re seeing increasing economic divergence and differentiation between and within asset classes, both of which are typical of an aging expansion.
Commentary
Navigating U.S. Wealth Management: How Advisors Are Using Alternatives in Client Portfolios
Alternatives allocations are becoming more mainstream in wealth management portfolios, though implementation varies greatly among financial advisors.
Commentary
Collapsing Oil Prices, Not Trade, Pose Biggest Exogenous Risk to Canada’s Economy
While trade policy has dominated headlines, we believe investors should focus on the collapse of Western Canadian Select (WCS) oil prices relative to global benchmarks, which represents the biggest exogenous risk to the Canadian economy.
Commentary
PIMCO’s Rigorous Approach to Managing Portfolio Liquidity Risk
By managing liquidity risk, we help ensure that portfolios are well-positioned both to withstand stress scenarios and to potentially take advantage of market dislocations.
Commentary
Health Check for Your Asset Allocation: Focus on Quality and Flexibility
In PIMCO’s recent Cyclical Outlook, our colleagues Joachim Fels and Andrew Balls outlined a “growing but slowing” backdrop, with the global economy in the final stages of an economic cycle. This late-cycle phase poses significant challenges to asset allocators.
Commentary
Ten Investor Takeaways From the 2018 Annual IMF/World Bank Meetings
Global central bankers, finance ministers and representatives from the private sector and civic groups gathered in Bali recently for the annual meetings of the IMF (International Monetary Fund)/World Bank Group. Below are 10 key takeaways from the discussions.
Commentary
Rising Rates: Not So Fast
Worries about rising U.S. interest rates have gripped global financial markets in recent weeks, with investors questioning whether the era of historically low global interest rates will persist.
Commentary
Argentina and the IMF: Second Time's a Charm
Like shock therapy, Argentina’s new lending agreement with the IMF delivers immediate benefits: increased funding and front-loaded disbursements to meet the country’s budget through next year. It also comes with serious side effects, including a likely deep recession in Argentina and the risk of political resistance leading up to the country’s elections in 2019.
Commentary
Oil Hits Multiyear Highs on Renewed Iran Sanctions: What Investors Should Watch
While we believe investors can expect a hawkish policy stance to keep supporting prices...
Commentary
What Investors Should Watch as Brexit Talks Heat Up
As we enter another period of accelerated Brexit negotiations, how can investors best navigate the next few weeks and months? Our assessment is that a number of U.K. assets have already priced in a significant chance of a disruptive Brexit, but there is scope for further moves in either direction, depending on the path the negotiations take.
Commentary
Fearing the Next Recession? Investing at the Front End of the Bond Market
Now in its 10th year, the U.S. economic expansion could become the longest on record: Our forecast calls for the current “late-cycle” phase of the expansion to last at least another year, barring any policy mistakes.
Commentary
Commodities: Expectations for Chinese Stimulus May Provide Support
Investors expecting that trade tensions with Washington will soon prompt additional stimulus by Beijing may be disappointed. Concerns over government debt, we believe, will limit additional stimulus – unless trade tensions weaken growth dramatically.
Commentary
No September Surprise: U.S. Economic Strength Prompts Fed to Raise Policy Rate
The Federal Reserve’s September statement, projections and press conference were in line with our expectations and support our view that the Fed will continue on a gradual trajectory of interest rate hikes.
Commentary
Growing, But Slowing
We see growth slowing, but not an imminent recession. We invest accordingly.
Commentary
The Fed: Look Forward or Risk a Hawkish Mistake
Will the Federal Reserve take a hawkish turn at its next meeting ending on 26 September? There are signs it may. Although we expect the Fed to hike rates by 25 basis points, to 2.0% to 2.25%, that’s not our concern.
Commentary
All Asset All Access, September 2018
In this issue, Research Affiliates discusses the funds’ long-term outcomes relative to peers, views on emerging market currencies and recent research centered on momentum.
Commentary
Love ’EM or Leave ’EM?
A review of last month’s market-moving events across countries and asset classes.
Commentary
Next Recession Ahead? Fixed Income Investing Ideas in an Aging Expansion
We look at ways to de-risk, diversify and differentiate ahead of a turn in the economic cycle.
Commentary
Retail Dip Weighs on U.S. Core CPI Inflation
U.S. core Consumer Price Index (CPI) inflation lagged expectations in August, breaking from the recent trend of generally upward surprises from various wage and price reports.
Commentary
SDG Bonds: Creating a World of Opportunity for Issuers and Investors
The UN Sustainable Development Goals provide the investment community, including bond issuers, with a framework for tackling long-term global challenges.
Commentary
Asset Allocation Views: Late-Cycle Investing
Risk is rising late in the cycle. How should investors respond?
Commentary
Shifting Realities and Opportunities in Emerging Markets
One truism spanning the last three decades has been that emerging markets are a leveraged play on global growth – often outperforming when developed markets (DM) are growing but susceptible to sharp downturns when DM conditions are less favorable.
Commentary
Women’s Economic Power Is Expanding – Is Investment Management Keeping Pace?
Women are transforming the global economy. The financial services industry must evolve both to better serve women investors, and to assess the impact that women’s decisions have on markets worldwide – now and in the decades to come.
Commentary
So Long, Libor: Transition Is Underway to SOFR and Other Alternative Reference Rates
It won’t be easy and key risks remain, but we believe the players and strategies are now in place to transition markets beyond Libor.
Commentary
Powell and the Fed Face ‘Dollar Doom Loop’ Dilemma
The U.S. central bank is damned either way as it faces a choice on a September rate rise.
Commentary
Investing in China: Evolving Opportunities
We expect an acceleration of strategic investments into onshore China bonds as these securities join emerging market and global bond indexes.
Commentary
The Uncertainty Principle: Fed Weighing Policy Risks
Federal Reserve Chairman Jerome Powell’s remarks at the annual Jackson Hole Symposium emphasized several important uncertainties about the structural aspects in the U.S. economy that greatly complicate the central bankers’ medium-term job of setting monetary policy.
Commentary
Why Commodity Carry May Be Higher Than You Think
In commodity investing, roll yield and carry are not the same thing.
Commentary
Updating Cash and Short‑Term Portfolios: Why Replay That CD?
Looking through your old compact disc collection can be nostalgic. The cover photo on your favorite CD or a few bars of a summer song can transport you back in time to what seems like a better, simpler place.
Commentary
Income Fund Portfolio Managers Discuss Rising Rates and the Impact on Bond Investors
We believe the Income Fund has the tools to be resilient in the face of rising interest rates.
Commentary
REITs Revisited: A Closer Look at Tax Efficiency and Returns
A fresh look at after-tax returns and valuations may cast REITs in a new light.
Commentary
Productivity Awakening: It Takes Two to Tango
For microeconomic advances to unleash a productivity rebound economywide, the macroeconomics must cooperate.
Commentary
United Nations: Creating a New Hub for Sustainable Investment Deals
The UN recently wrapped up its annual High-Level Political Forum on Sustainable Development, which brings together the 193 Member States to explore how they plan to reach the UN’s Sustainable Development Goals (SDGs).
Commentary
Munis in Focus: Preparing for Late-Cycle Certainties
Munis may offer U.S. taxpayers key benefits as they contemplate the end of the economic expansion.
Commentary
De-FANGed Trade?
A review of last month’s market-moving events across countries and asset classes.
Commentary
The Global Bond Paradox: How Hedging Can Enhance Low Local Yields
Japanese government bonds yield virtually zero. Yields on German bunds remain stuck below 50 basis points (bps). U.K. gilts yield only about 125 bps. Do non-U.S. bonds such as these hold any value to dollar-based investors?
Commentary
ESG Integration and Engagement: South Africa Sovereign Credit
Environmental, social and governance (ESG) indicators are integral to PIMCO’s sovereign credit assessments, which inform our investment decisions. But how exactly do we incorporate ESG considerations into our decisions?
Commentary
Income Strategy Update: Sifting Global Change for Investment Opportunities
Portfolio managers Dan Ivascyn and Alfred Murata discuss the impact of higher market volatility and how they are positioning the Income Strategy for change ahead.
Commentary
All Asset All Access, August 2018
In this issue, Research Affiliates discusses positioning in emerging markets and why investors should care about the distinction between real and nominal returns.
Commentary
Could Trade Turmoil Be an Economic Spoiler for the U.S.?
Even before President Trump’s inauguration, we at PIMCO had identified trade policy as a potential spoiler to the otherwise pro-growth nature of the president’s economic agenda. And the unfolding of this “summer of discontent” has only affirmed our view heading into 2018 that trade policy remains one of the biggest policy risks for markets and the economy this year.
Commentary
Attractive Valuations in Short‑Dated Investment Grade Credit
Amid overall caution on credit, we believe short-dated investment grade corporate bonds offer a compelling risk/reward profile today.
Commentary
Fed Meeting: Important Details to Come?
The Federal Reserve held interest rates steady and released a statement on 1 August that made only minor changes to reflect the more upbeat U.S. economy since the Fed’s June meeting. Despite the lack of surprises, however, we don’t think investors should write off the meeting just yet: The more interesting aspect may well come later ‒ when the meeting minutes are revealed in a few weeks.
Commentary
Gold Outlook Brightens
Ultimately, we think the sell-off will prove transient and that the relationship of real yields to gold observed over the past decade will prevail.
Commentary
Fed Up With the Fed: What It Means for the U.S. Dollar
President Donald Trump has opened a new front in the cold currency war: He recently complained in an interview and on Twitter that the strong U.S. dollar puts the U.S. at a disadvantage and that China and the European Union have been manipulating their currencies and interest rates lower.
Commentary
U.K. Outlook: It’s Not Just Brexit
We see key factors beyond Brexit affecting the medium-term economic outlook for the U.K.
Commentary
FERC Change in Stance Is Positive for Oil and Gas MLPs
Master limited partnership (MLP) investors received some good news last week. The Federal Energy Regulatory Commission (FERC) issued a final ruling that clarifies and softens a previous order issued in March, which would have disallowed a long-standing policy enabling MLPs to earn an income tax allowance in their pipeline rates.
Commentary
Will the Fed Yield to the Yield Curve?
Will they or won’t they? With the U.S. yield curve flattening to new cycle lows, whether or not the Federal Reserve will stick to its planned rate-hike path is a key question – and could soon become the key question – for financial markets.
Commentary
Yuan Decline: Concerning But Not Systemic
Amid fears of escalating trade tensions, the yuan’s sharp depreciation against the dollar last month has spooked some investors who see similarities with China’s currency devaluation in 2015, an episode that prompted capital outflows and roiled markets worldwide.
Commentary
When Push Comes to Shove
A review of last month’s market-moving events across countries and asset classes.
Commentary
Munis and the Markets, June 2018
A brief monthly update on what's happening in the municipal bond market.
Commentary
Eurozone Outlook: When Secular Turns Cyclical
Over the next few years, financial markets could be set for a series of “Rude Awakenings,” as we forecasted in our latest Secular Outlook. The global economy is transitioning out of a post-crisis period characterized by remarkable stability, and the changes ahead could be jarring for investors.
Commentary
U.S. Trade Tariffs: Impact on Asian Technology and Consumer Credit
U.S. tariffs and trade tensions have dominated headlines over the past few months. With certain tariffs aimed squarely at China, Beijing quickly responded with tariffs of its own on U.S. goods in early July. What do the tariffs mean for investors in Chinese and other Asian technology and consumer credits?
Commentary
All Asset All Access, July 2018
In this issue, Research Affiliates discusses positioning for a potential inflation shock and offers insight into its collaboration with PIMCO to bring forth innovative solutions for investors.
Commentary
Why Long-Term Investors Shouldn’t Necessarily Fear Rising Rates
Investors may be concerned that Fed rate hikes may be bad for bondholders but it’s important to remember the fundamental benefits that bonds may bring to a portfolio no matter which way rates move – capital preservation and appreciation, income, and diversification.
Commentary
ESG Investing and Fixed Income: The Next New Normal?
We believe the bond market is uniquely suited to both benefit from and provide finance for ESG-related (environmental, social and governance) efforts.
Commentary
After OPEC Meetings, We See a Constructive Backdrop for Oil
The recent OPEC meetings and press conference have given oil investors greater clarity about the cartel’s intentions and reaction function: OPEC, along with Russia and other partners, agreed to boost aggregate output by 700,000–1 million barrels per day.
Commentary
Canada’s ‘Rudest Awakening’ May Come From Debt‑Saddled Consumers
External pressures are mounting, but Canada’s biggest wake-up call may come from within.
Commentary
High Yield Bonds: A Fresh Look at BB Rated Credit
With the economy in the later stages of its post-crisis recovery, we believe investors should be cautious and selective on corporate credit. Within the high yield sector, this caution may warrant a move up in quality toward the higher end of the spectrum: BB rated bonds.
Commentary
The Currency Sweepstakes: Will the U.S. Dollar Win?
Forecasting currency performance is like predicting the outcome of a horse race. Currencies move up the field and then fall back depending on their respective country conditions. And once in a great while, a very strong contender dominates the field – much like the winner of the Triple Crown.
Commentary
Charting Unusual Late-Cycle Fiscal Stimulus in the U.S.
How can investors navigate volatility arising from late-cycle fiscal stimulus?
Commentary
Evolutions in Growth, Trade and Geopolitics
PIMCO’s Global Advisory Board discusses the outlook for major economies and geopolitical developments.
Commentary
The Fed Raises Rates as Expected but the Path of Future Hikes Grows More Uncertain
The Federal Reserve’s decision today to hike its policy rate by 25 basis points (bps) to a range of 1.75% to 2.0% was widely expected. The Federal Open Market Committee (FOMC) also signaled growing consensus that the robust pace of economic activity warrants two more rate hikes this year, for a total of four in 2018.
Commentary
Productivity Awakening?
One of the potential rude awakenings that we advised investors to prepare for in our recent Secular Outlook is a surprising surge of productivity growth over the next several years.
Commentary
China’s Property Market: Bubble or Balloon?
Despite long-running international concerns about China’s property “bubble,” the market has proven quite resilient. The Chinese government has instituted various austerity measures to cool the market, but buoyant demand for property has helped avoid any serious downturn.
Commentary
The Summer of Discontent on Trade? Deadlines, Headlines and Escalation Catalysts
Consistent with our thinking back in January 2018, trade has dominated the policy agenda in Washington and cast a pall over certain segments of the market. We continue to maintain that President Trump should be taken at his word regarding trade policy...
Commentary
International Equities and the U.S. Dollar: Is It Time to Hedge?
In a reversal from last year, the U.S. dollar has strengthened against other major currencies in 2018, reflecting rising U.S. rates, expectations of more Federal Reserve rate hikes and recent sluggish economic data outside the U.S.
Commentary
Preferred and Capital Securities Fund: Bank Fundamentals Haven’t Been This Strong in Decades
A segment of the credit market many investors may overlook, preferred securities are one of PIMCO’s highest-conviction credit views today.
Commentary
Rude Awakenings
We expect a more difficult market environment will surprise many investors as the post-crisis era ends. It’s time to position for the opportunities ahead.
Commentary
Income Strategy Update: Investing Into Higher Bond Yields
For income investors, rising interest rates have created both a challenging market environment and a better outlook for yield.
Commentary
‘Simplification Day’ for Oil & Gas MLPs: What Investors Need to Know
We believe the news is evidence of a broader shift toward simpler corporate structures in the midstream energy sector – a trend that supports our investment approach and our constructive view of the sector.
Commentary
The Fundamentals of RAE: Seeking Value Beyond Borders
It may be time for U.S. investors to challenge their home-country equity biases.
Commentary
Value in Short Bonds: ‘We’re Not in Kansas Anymore’
For years after the financial crisis, many investors were resigned to earning next to nothing on their cash and short duration investments. Rising interest rates, however, have brought a new reality: The front end of the fixed income market looks attractive for the first time in almost a decade.
Commentary
A Strong Defense Can Win Championships: Actively Managing Your Cash and Short‑Term Investments
We are positioning our ultra-short and short-term bond portfolios with the goal of not only navigating rising rates but also ultimately benefiting from them.
Commentary
UN Sustainable Development Goals: Measuring Performance Through Impact
We believe that active engagement with issuers can help reduce credit risk, unlock value for investors, and influence positive impact on economies, societies and the environment.
Commentary
Market Relieved by Inflation Reading, for Now
U.S. core Consumer Price Index (CPI) inflation was softer than consensus expectations in April, and the year-over-year rate remained stable at 2.1%. We see a couple of reasons for that, and continue to expect core CPI inflation to accelerate further (to 2.3%–2.4%) before settling back to 2.2% by year-end.
Commentary
Oil Prices Likely to Rise With U.S. Withdrawal From Iran Nuclear Deal
The U.S. decision to pull out of the Iran nuclear deal has potentially profound implications for the oil market. While withdrawal from the Joint Comprehensive Plan of Action (JCPOA) creates many known unknowns, any reduction in Iranian supply will likely exacerbate market deficits, suggesting upward pressure on pricing.
Commentary
Across the Line
A review of last month’s market-moving events across countries and asset classes.
Commentary
Why We Favor Active Management in Emerging Market Bonds
We believe the myriad inefficiencies in emerging market fixed income play to the strengths of active management.
Commentary
The U.S. Economy Isn’t Immune to Rising Oil Prices
How sensitive is the U.S. economy to rising oil prices? A popular view is that growing U.S. energy output has largely immunized the economy against the adverse effects of pricier oil.
Commentary
Fed Poised to Let Inflation Accelerate, a Little
With little in the recent economic data to warrant a change in the U.S. outlook and bond markets that were largely aligned with the Federal Reserve’s 2018 rate hike projections, today’s statement from the FOMC (Federal Open Market Committee) needed only to reaffirm the messages conveyed at the March meeting.
Commentary
Ten Investor Takeaways From the IMF/World Bank Spring Meetings
Global central bankers, finance ministers and representatives from the private sector and civic groups gathered in Washington recently for the spring meetings of the IMF (International Monetary Fund)/World Bank Group. With trade policy, geopolitics and emerging markets currently top-of-mind for many investors, the meetings were especially relevant this year.
Commentary
Global Debt and The New Neutral
We believe The New Neutral of lower-for-longer equilibrium policy rates remains a valid anchor over the medium term. The key drivers of low equilibrium rates – including demographic trends and the high level of leverage in the global economy – have not substantially changed since the financial crisis.
Commentary
China’s Surprise Reserve Requirement Cut: Liquidity Fine‑Tuning or Policy Shift?
When the People’s Bank of China (PBOC) cut its reserve requirement rate (RRR) by 1% for China’s banks recently, the central bank said its “prudent and neutral policy stance” remained in place, since the overall quantity of excess reserves would not change much. Indeed, the PBOC will maintain a relatively high reserve requirement for China’s banks.
Commentary
Bank of England: Is History Repeating Itself?
The Bank of England has had to navigate a difficult set of circumstances in its attempts to raise interest rates. As far back as 2014, Governor Mark Carney suggested that rate rises could come “sooner than markets currently expect,” only for those aspirations to be dashed. Indeed, the next move in interest rates turned out to be a rate cut, in the aftermath of the June 2016 Brexit vote.
Commentary
China’s Growth Rebalancing Provides Opportunities for Bond Investors
After a decade of relying on investment and exports for growth, China’s effort to rebalance its economy toward consumer-led growth is well underway and should continue to build steam in 2018.
Commentary
Managing Volatility in Short‑term Markets: The Global Liquidity Ladder
In a storm, you want to be able to reach higher ground. Recent market volatility – sparked by concerns over interest rates, inflation, global trade, the tech sector and more – has many investors shifting toward more defensive portfolio positions.
Commentary
Time for Investors to Prepare for the Next Cycle
The global economic expansion has already entered its 10th year. With bumpy and brittle growth having given way to a robust and globally synchronized conjuncture, an aging cycle has suddenly become much more cyclical.
Commentary
With Inflation Rising, Commodities May Shine
Many investors who thought worrying about inflation was “so 20th century” may now be seeing reasons to reconsider: The business cycle in the U.S. is mature, output gaps have closed, trade frictions are mounting and populism is on the rise.
Commentary
U.S. CPI Inflation: Two Trends to Watch
The acceleration in U.S. core Consumer Price Index (CPI) inflation in March was in line with expectations, and likely a welcome development for Federal Reserve officials after a surprising string of soft inflation prints last year.
Commentary
Fed Minutes: Policymakers Shrug at Market Volatility, Stay Focused on Gradual Path
The minutes of the March 2018 Federal Open Market Committee (FOMC) meeting affirmed our outlook that the Fed will likely continue to gradually and methodically increase interest rates and that the bar is relatively high for policymakers to change the current plan for two or three more hikes in 2018.
Commentary
Trade Outlook: Stormy
A review of last month’s market-moving events across countries and asset classes.
Commentary
Trade Tensions Mount: What It Means for Growth
Consistent with our view last month that the Trump administration’s more significant (and market-moving) trade actions had yet to come, the recent announcement of tariffs on Chinese products related to the Section 301 intellectual property investigation has roiled markets and increased uncertainty over the possibility of a trade war.
Commentary
State‑Specific Municipal Portfolios: When Do the Benefits Outweigh the Costs?
Recent tax reform has increased the dialogue around state preference municipal portfolios, and some municipal investors are inquiring whether state-specific or state preference portfolios are a good fit in the current environment.
Commentary
Uniform Mortgage‑Backed Security Initiative (‘Single Security’)
Many of us who grew up as children of children of the Great Depression may recall our parents imploring us to “Stop throwing good money after bad!” in any number of situations, even if we didn’t always heed their wisdom.
Commentary
Issuer Engagement Is Crucial to the Future of Sustainable Investing
We believe that ESG investing is not only about partnering with issuers who already demonstrate a deeply integrated approach to ESG, but also about engaging with those who wish to move forward with their ESG initiatives. We believe that successful engagement can reduce credit risk, unlock value and influence positive impact.
Commentary
U.S. Commercial Real Estate: Selectivity in a Range‑bound Environment
We maintain a neutral outlook for U.S. commercial real estate prices overall this year, following a 3% to 5% decline from their 2015 peak.
Commentary
Issuer Engagement Is Crucial to the Future of Sustainable Investing
We believe that ESG investing is not only about partnering with issuers who already demonstrate a deeply integrated approach to ESG, but also about engaging with those who wish to move forward with their ESG initiatives.
Commentary
The Beginning of the End? Key Takeaways From PIMCO’s Cyclical Outlook
Stormy weather was abundant in March: spring snowstorms in the Northeast of the U.S., a trade tussle with China that could escalate into a trade war, hawkish personnel changes in the White House, a Powell-led Federal Reserve that expects to overshoot the neutral policy rate, and the worst week for U.S. equities since January 2016.
Commentary
The Beginning of the End?
The global expansion is either nearing its demand-driven peak or in the early stages of a supply-driven renaissance. We share our assessment and portfolio positioning.
Commentary
Fed Outlook: Headwinds Shift to Tailwinds, But Pace of Hikes Still Gradual
The U.S. Federal Reserve’s announcement of another 25 basis point hike in the fed funds rate range to 1.5% to 1.75% was widely expected by us and by markets. The more interesting aspect of the March FOMC (Federal Open Market Committee) meeting is the change to central bank officials’ forecasts.
Commentary
Inflation Rebound Signals China Is No Longer a Source of Global Disinflation
Strong Chinese Consumer Price Index (CPI) data for February suggest the world’s second-biggest economy will no longer be a source of global disinflation.
Commentary
What the MSRB’s Markup Disclosure Rule Means for Muni Investors and Advisors
The Municipal Securities Rulemaking Board (MSRB)’s new “markup disclosure rule” is on track to go into effect in the U.S. in May 2018, as part of a broader move toward greater transparency in the municipal bond market.
Commentary
PIMCO Income Update: Finding Value in Volatile Markets
We believe that balancing higher-yielding assets with higher-quality assets is the best way to achieve the strategy’s objectives across different market environments.
Commentary
Trump, Tariffs and Trade: Three Takeaways for Investors
We believe the trade actions with the most significant potential economic and market impact have yet to unfold.
Commentary
U.S. Core CPI Moderates in February, With Few Surprises in the Readings
We saw little to surprise in February’s U.S. Consumer Price Index (CPI) inflation print: Core CPI (excluding food and energy prices) gained 0.18% month-over-month, a moderation from January’s 0.34% gain, and held steady at 1.8% year-over-year.
Commentary
All Asset All Access, March 2018
In this issue, Research Affiliates discusses positioning for potentially volatile markets and the link between equity valuations and macroeconomic conditions.
Commentary
Diversifying Risk, and Risk‑Takers, in Investment Management
PIMCO’s new partnership with the organization Girls Who Invest is one more step toward a more inclusive financial services industry. It is also an act of conviction.
Commentary
Demystifying the Weak Dollar Puzzle
Market participants have been puzzled by the decline in the U.S. dollar since the November 2016 election. Expectations over future central bank moves and short-term interest rates offer one explanation – and potentially a signal about the dollar’s future.
Commentary
Oil and the Uphill Road to Fiscal Balance in the Middle East
A recent visit to the United Arab Emirates (UAE), Oman and Bahrain showed just how much the region’s fortunes are still levered to oil prices, despite the efforts of several countries to diversify.
Commentary
The Next Correction?
Last March, we wrote a piece entitled “Equity Repricing Under a New Administration: A Tail Risk Scenario.” We posited that the proposed pro-growth tax and spending policies of the Trump administration, thrust onto an economy nearing full capacity, could lead to a general rise in the inflation rate and ultimately the real rate of interest.
Commentary
Alternative Investments for Wealth Management Portfolios
Many investors are now willing to sacrifice liquidity in the search for higher yields, more attractive risk-adjusted returns and the flexibility to hedge against downside risk.
Commentary
Defined Contribution: Four Themes for 2018 and Beyond
In our view, the prospective low-return environment calls for a capital-efficient approach that pairs actively managed bonds with passive or enhanced equities in target-date, core and retirement-income allocations.
Commentary
Emerging Markets: Standing Up to Higher Volatility
During the second most significant repricing in U.S. Treasury bond yields since 2013, emerging market debt has so far significantly outperformed equity, oil and U.S. Treasury beta.
Commentary
What’s Next for Investors in the Bond Market
Recent market volatility suggests that investors are questioning whether the post-crisis subpar pace of economic growth, which we dubbed The New Normal, is subsiding, to be replaced by more traditional late-cycle outcomes – in particular faster inflation and tighter monetary policy.
Commentary
U.S. Core CPI Accelerates in January on Post‑Holiday Retail Bounce
U.S. inflation continued to accelerate in January, with a 0.349% month-over-month advance in core Consumer Price Index (CPI) inflation (which excludes food and energy prices) – the strongest gain since 2001.
Commentary
Unconstrained: How Bond Investors Can Embrace Volatility
Untethered to traditional bond benchmarks, unconstrained bond strategies can respond to current changing market conditions in various ways.
Commentary
Regime Change in Bond Markets?
With a steady repricing of global bond markets having contributed to a sharp plunge in global stock markets, there could be a whiff of a new era in the air.
Commentary
U.S. Housing Finance Reform: Why Fix What Isn’t Broken?
The topic of housing finance reform has come in and out of focus on Capitol Hill since Fannie Mae and Freddie Mac (the government-sponsored enterprises, or GSEs) were taken into conservatorship back in 2008.
Commentary
Looking Past Volatility
PIMCO takes a long-term view of markets and economies, one that anchors investment decisions during shorter-term periods of market volatility. Nonetheless, the dramatic return of market volatility has understandably unnerved many investors.
Commentary
Hot Out of the Gate
A monthly review of market-moving events across countries and asset classes, and what investors can expect going forward.
Commentary
Are Equity Markets Anticipating a Macroeconomic Regime Change?
The U.S. economic numbers released last week preceded a slide in equities, prompting keen interest in what the data may have been signaling to markets.
Commentary
2018 Outlook: Looking Beyond Market Volatility
With the dramatic spike in market volatility over the past week, many investors are asking what comes next.
Commentary
Munis in Focus: 2018 Municipal Market Outlook
We expect policy will continue to drive municipal bond markets in 2018, if more constructively than in 2017. Municipal investors may remember 2017 as the year of unrealized policy fear. While the threat of tax reform and its potential to reduce the value of the muni exemption for retail investors loomed large, ultimately it had little impact on individual municipal bonds.
Commentary
The Fed: More Confident on Outlook and Inflation Target
Going into Federal Reserve Chair Janet Yellen’s 32nd and final meeting, neither we nor the markets expected the Fed to make much news. Of note, however, in its statement after the meeting on 31 January, the Fed acknowledged recent firmer economic data and expressed confidence in inflation moving toward the 2% target later this year.
Commentary
Winning the Cold Currency War
Investors in Europe are more optimistic than they have been in years, but there is growing concern that U.S. dollar weakness could make the euro too strong.
Commentary
Eurozone Outlook: Economic Growth Masks Underlying Fragility
Economic recovery is in full swing but investors should remain vigilant of the long-term risks.
Commentary
Asia Market Outlook: What Is in Store for 2018?
Nominal growth is likely to pick up, reflecting some recovery in real GDP and a gradual rise in inflation.
Commentary
Applying ESG Analysis to Sovereign Bonds
Integrating ESG into sovereign risk analysis adds a holistic and long-term perspective that is aligned with investing in sovereign fixed income.
Commentary
BOND: Going Active in Core Bond ETFs
Fixed income exchange-traded funds (ETFs) saw a record $126 billion of inflows in 2017, bringing the overall market to nearly $600 billion. The majority of these flows, as well as existing assets under management, are in passive bond ETFs. But are passive, index-tracking approaches the best way to harness the fixed income opportunity set?
Commentary
Oil and Gas MLPs: Poised for a Rebound in 2018
After a four-year downturn in the oil and gas master limited partnership (MLP) sector, marked by a roughly 47% decline in market value, we believe sentiment toward the sector may be turning. With dividend yields approaching 8% – along with increasing free cash flow and a robust U.S. production outlook...
Commentary
U.S. Policy Outlook for 2018: Expect Action on Trade and Government Spending
Although much of 2017 represented a series of fits and starts in Washington, the Trump administration and the Republican-led Congress ultimately – and against long odds – delivered on one of their biggest campaign promises: a relatively sweeping rewrite of the tax code, representing a likely boost to 2018 U.S. real GDP of 0.2%–0.3%.
Commentary
To Be (20)17 Again
Like much of 2017, politics remained keenly in focus at the end of the year. Tax reform took center stage in the U.S., and President Trump wrapped up this major legislative victory just in time for the holidays. The sweeping tax overhaul moved quickly through both chambers of Congress after the House and Senate drafted amended versions from the separate ones each had previously passed.
Commentary
Investment Grade Credit: Be Actively Aware of BBB Bonds
Years of significant growth in the U.S. corporate bond market have been accompanied by a steady decrease in overall credit quality and a trend toward higher leverage. Close to $80 billion in U.S. corporate bonds currently rated BBB potentially could be downgraded below investment grade in 2018, according to our estimates.
Investors may want to consider taking a more cautious and selective approach to BBB nonfinancial corporate bonds, particularly those in the low BBB rated segment, where the risk of downgrades is higher and the room for error is lower.
That said, we find many compelling BBB bonds in the U.S. marketplace today. As a large active fixed income manager, PIMCO is in our view ideally positioned to manage the risks in the complicated universe of BBB bonds.
Commentary
All Asset All Access, January 2018
In this issue, Research Affiliates provides its outlook for 2018 and discusses where it sees attractive return opportunities across the globe.
Commentary
Equity Factor Investing: Three Key Considerations
Equity investors in search of higher returns are increasingly turning to factor investing. Driving this trend is frustration with the underperformance and higher fees of traditional active equity approaches, along with a growing realization that many stock-picking strategies owe their results largely to the manager’s factor tilts rather than stock-specific risk.
Commentary
Peak Growth: Three Reasons the Global Economy Could Top Out in 2018
The conclusion from PIMCO’s latest Cyclical Forum is that 2017–2018 could well mark the peak for economic growth in this cycle and that investors should start preparing for several key risks that lie ahead in 2018 and beyond.
Commentary
Are Emerging Markets Still on High Ground?
After a strong run in emerging markets through the first nine months of 2017, a recent performance setback in local bond markets has led some investors to fear that the recovery cycle may be short-circuiting. Is the two-month run of underperformance in EM local markets an opportunity or a canary in a coal mine?
Commentary
Political Noise, Market Poise
A review of last month’s market-moving events across countries and asset classes.
Commentary
Tax Reform: There’s Will, But Is There a Way?
Congressional Republicans’ efforts to reduce taxes and reform certain elements of the U.S. tax code have been impressive thus far. In a matter of weeks, the House has passed its version of a bill, and the Senate is hoping to take up its own bill later this week.
Commentary
Geopolitical Uncertainty and the Global Economy
Ben Bernanke and our panel of world-renowned advisors examine the outlook for global economic growth amid geopolitical shifts.
Commentary
Chinese Corporate Credit: Five Themes for 2018
Growth in China’s offshore corporate bond market seems likely to continue in 2018, driven by the financing needs of investment grade state-owned enterprises (SOEs) and private sector...
Commentary
Firming U.S. CPI Supports Forecast for 2% Inflation in 2018
Core U.S. Consumer Price Index (CPI) inflation rose 0.22% month-over-month in October, broadly in line with expectations for firming price trends but notably stronger than the 0.14% average monthly pace this year.
Commentary
Benefiting From Flexibility: Opportunities in Multi‑Sector Credit
As many traditional credit sectors begin to approach full valuations, credit investors may want to look in new directions for attractive returns with manageable downside risk. In diversified credit portfolios today, de-risking and building liquidity are important, but we also see attractive relative value opportunities in a couple of (sometimes overlooked) sectors.
Commentary
Extra Innings
A review of last month’s market-moving events across countries and asset classes
Commentary
The Thorny Transition from Libor to SOFR
The transition from Libor to SOFR as a benchmark short-term rate needs to be undertaken with tremendous care, and PIMCO would like to help by outlining clear steps for stakeholders...
Commentary
Munis in Focus: Adjusting the Sails
How we’re positioning muni portfolios for turbulence – and the opportunities it may create.
Commentary
Addressing the Non‑Performing Loan Problem in Europe
Creative solutions may be needed to address remaining asset quality issues in Europe’s banks.
Commentary
Hedging for Profit: A Novel Approach to Diversification
With stocks hitting record highs, many investors want to mitigate the largest source of risk in their portfolios – equities. In recent decades, fixed income has served this purpose well. The asset class has generally delivered both positive returns and negative correlations with equities.
Commentary
The Powell Fed: Continuity in Monetary Policy
President Trump has announced Fed Governor Jerome Powell as his nominee for Chair of the Federal Reserve Board. A Fed governor since 2012, Powell has been confirmed twice by the U.S. Senate and likely will be confirmed as chair without controversy in time to take over when current Chair Janet Yellen’s term expires in February 2018.
Commentary
ECB Preview: Expect Emphasis on Forward Guidance, Continued Tapering
Our central expectation for the European Central Bank (ECB) meeting on 26 October is for the Governing Council to extend asset purchases by nine months at €30 billion per month to September 2018, without yet committing to a specific end date, while strengthening its commitment to keep policy rates and the balance sheet unchanged when asset purchases end next year.
Commentary
Active Short‑Term Strategies: Swimming Clear of Rate Hike Riptides
Actively managed front-end strategies may be able to mitigate the erosion of real capital experienced in passive benchmarks as rates rise.
Commentary
The Global Factor in Neutral Policy Rates
A global factor helps explain why central bank policies often tend to be correlated across countries.
Commentary
Navigating U.S. Wealth Management: Five Key Themes for Financial Advisors and Individual Investors
Unprecedented changes are reshaping the financial advice industry and affecting portfolio construction for individual investors. New regulation, technological innovation, capital market trends and the prospect of lower future returns are all exerting profound effects.
Commentary
Japan’s Election: ‘TINA’ to Abe
The governing coalition of Abe’s Liberal Democratic Party (LDP) and the smaller Komeito Party staged a big win in the snap election. Although recent public polls indicated a victory, the final tally was on the higher side of consensus expectations, including ours.
Commentary
Australian Interest Rates: Like Watching Grass Grow
If the pace of monetary tightening in the U.S. is any sort of leading indicator for policy tightening in the rest of the world, including Australia, then in Australian parlance, it will be “like watching grass grow.”
Commentary
5 Things to Know About Emerging Markets
Emerging markets debt and equity have many overlapping traits, but also differ in their exposure to countries and risks. The MSCI Emerging Markets Index contains 27 countries, with the five largest accounting for 70% of market value. Three countries in Asia - China, South Korea and Taiwan - comprise more than 50% of the index.
Commentary
Ten Investor Takeaways From the IMF/World Bank Meetings
Global central bankers, ministers of finance and representatives from the private sector and civic groups gathered in Washington, D.C., last week for the Annual Meetings of the IMF (International Monetary Fund) and the World Bank Group.
Commentary
Another Weak Inflation Report Won’t Help the Fed’s Dilemma
Despite a hurricane-related surge in headline inflation, core inflation continued to run softer than expected in September, a trend that could make the Federal Reserve more cautious about hiking interest rates in December.
Commentary
Drying Paint or Boiling Frog?
Last Month in Perspective: The convoy of developed world central banks reducing policy accommodation appeared to gather steam. Global political developments continued to capture headlines. Interest rates moved higher on the hawkish tilt in central bank rhetoric, and equities gained on generally positive economic data.
Commentary
Will Fannie and Freddie Draw From the Treasury? Much Ado About Nothing …
Policymakers in Washington have recently expressed growing concerns about the (planned) dwindling of capital levels at Fannie Mae and Freddie Mac – the two government-sponsored enterprises (GSEs) that help finance the vast majority of U.S. mortgages.
Commentary
Emerging Markets Outlook: Constructive, But for Investors the Work Begins
While PIMCO’s cyclical outlook is cautious overall, our outlook for emerging markets ex-China (EM) is more constructive. We expect further improvement in the EM macro picture as most emerging economies are at a different stage of the economic cycle than developed economies and they are still benefiting from relatively easy global policy conditions.
Commentary
Corporate Crossover Bonds in the Sweet Spot
The unique attributes of corporate crossover bonds may offer solutions for investors assessing a range of objectives and risks.
Commentary
Oil Market Shifts From Contango to Backwardation: Implications for Investors
In recent weeks Brent crude oil, the global oil benchmark, has shifted into backwardation – a state when spot prices are higher than prices for futures contracts, creating a downward-sloping curve for futures prices.
Commentary
When a Fact May Not Be a Fact and So What
An analysis of default rates and government intervention since the financial crisis.
Commentary
Russia: Growth Up, Inflation Down
Russia has been front-and-center of the news this summer. Yet Western sanctions over Crimea, fallout from the investigation into meddling in the U.S. presidential election and last month’s bailout of the nation’s largest privately held bank have failed to thwart Russia’s emergence from stagflation.
Commentary
Tax Reform: Challenges Ahead
With great fanfare, the White House and Republican congressional leadership released their long-awaited framework for tax reform, but many politically thorny issues need to be resolved – and quickly – before investors can feel confident that tax reform will materialize in the coming months.
Commentary
As Good as It Gets
We see three risks to the outlook for steady economic growth. Yet we also see opportunities for investors to target above-benchmark returns while emphasizing defense at a time of low volatility and full valuations.
Commentary
Protecting Portfolio Value: Constant Proportion Portfolio Insurance Versus Tail Risk Hedging
Tail risk hedging seeks to protect gains without loss of upside equity potential.
Commentary
German Elections: Not So Steady As She Goes
Broad-based support for Europe among Germany’s key political parties vying for seats in the Bundestag’s 19th legislative period meant Sunday’s election was unlikely to be disruptive for financial markets. And the muted reaction in financial markets Monday morning confirmed this was the case.
Commentary
Oil and Gas MLPs: Time to Take a Fresh Look?
Master limited partnerships, once considered utility-like yield instruments, have come to be viewed largely as leveraged commodity investments – but is the pendulum about to swing back?
Commentary
Fed Balance Sheet Normalization: Signed, Sealed, Delevered
Going into today’s important Federal Reserve meeting (with a press conference and an update to the economic projections, aka the “dot plot,” along with the usual statement), we at PIMCO along with most market participants expected the Fed to announce formally the start of balance sheet reduction this fall, perhaps in October. And that’s exactly what the Federal Open Market Committee (FOMC) did.
Commentary
Are Diversifying Assets Up Next in the Return-Seeking Cycle?
After a sustained period of return leadership by U.S. stocks, a number of diversifying assets now appear poised for outperformance.
Commentary
CPI Finally Accelerates – A Small Sigh of Relief for the Fed
As many observers expected, after five months of surprisingly soft inflation prints, prices firmed in August. U.S. core CPI inflation (which excludes the volatile food and energy categories) was up 0.25%, boosted by the largest-ever one-month increase in hotel prices and surprising firmness in rents and owners’ equivalent rents (OER).
Commentary
Rolling with the Punches
A review of last month’s market-moving events across countries and asset classes.
Commentary
Opportunities in U.S. Commercial Real Estate Debt Investing
Unmet borrower needs continue to grow in the U.S. commercial real estate lending market.
Commentary
ESG in Action: Evaluating Global Financials
Analysis of environmental, social and governance factors (ESG) is particularly important for bank investments because the confidence of their depositors and borrowers largely drives banks’ valuations.
Commentary
Managed Futures Strategies: Inside the “Black Box”
Momentum, trend-following, managed futures - are terms that can seem intimidating and opaque for many investors. But, while these types of investment strategies may be less familiar than traditional strategies, they can be quite intuitive and offer attractive diversification and return potential that is worth getting to know.
Commentary
Getting More From Your LDI Portfolio
Our approach to investing in long duration and long credit portfolios has delivered meaningful alpha over most market cycles.
Commentary
Congress’ Must‑Do List Is Looking More Doable, but After That …
After an uncharacteristically eventful August in Washington, Congress returns to D.C. for an even busier fall: In September, it has a mere 12 legislative days to fund the government for fiscal 2018 (and thus avoid a shutdown), raise the debt ceiling and address a smattering of other must-pass bills...
Commentary
Retirement Savings: Why Hedging Inflation Is Important
Although inflation may seem a distant threat, even modest inflation can prove devastating to retirees who depend on income that does not adjust with inflation.
Commentary
BOJ: Rethinking the Mandate
Who will be the next governor of the Bank of Japan (BOJ)? This is an important question to be answered in the next several months, as Governor Haruhiko Kuroda’s current term will expire in April of next year.
Commentary
Yellen at Jackson Hole: Long on History, Short on Hints About Future Fed Policy
Federal Reserve Chair Janet Yellen’s remarks at the annual Jackson Hole Economic Policy Symposium delved into history but offered few clues about the future course of Fed policy.
Commentary
Asset Allocation Views: Preparing for Pivot Points
With critical policy pivots on the horizon, investors should approach asset allocation with full appreciation for downside risk and stay focused on relative value and security selection.
Commentary
Mixed U.S. Energy Earnings Reinforce Credit Views and Outlook for Range‑Bound Oil Prices
U.S. exploration and production (E&P) companies delivered mixed second-quarter earnings results and guidance, with evidence of operational missteps by certain Permian Basin producers. One particular large producer’s report of drilling delays, higher planned well costs and higher gas-to-oil ratios sparked broader concerns about whether Permian producers can maintain efficiencies and execute on plans to drill larger wells.
Commentary
China: When Atlas Shrugs, Markets Shiver
The use of credit to fuel growth in China is weakening, a trend that has begun to depress demand for imports. Given China’s seminal role as an engine of global growth, the ripple effects will weigh on growth prospects for the countries most exposed to Chinese demand, including those in Asia and Latin America.
Commentary
Fed Balance Sheet Tapering: We Gotta Have Faith
The news coming out of the July Federal Open Market Committee (FOMC) meeting was a reference in the statement that the Federal Reserve expected to begin to implement its balance sheet normalization program “relatively soon,” which we (along with many market participants) took to mean at the upcoming September meeting.
Commentary
Banking on Change
A review of last month’s market-moving events across countries and asset classes
Commentary
Time to Run the U.S. Economy a Little Hot?
Following another underwhelming U.S. CPI report, it’s now entirely possible that core personal consumption expenditures (PCE) inflation – the Federal Reserve’s preferred measure, currently at 1.5% – will end the year at 1.3%, a far cry from the central bank’s 2% target.
Commentary
Weak U.S. CPI Underscores Unlikelihood of Another Fed Hike in 2017
Another underwhelming rise in the U.S. core Consumer Price Index (CPI) reported on Friday increases the chances that Federal Reserve policymakers use the September meeting to signal they plan to abstain from additional interest rate hikes until next year.
Commentary
China Leads Emerging Asia to Greater Role in Capital Markets
Over the next 12 to 24 months, we expect that Asia, led by China, will become a far more significant part of the global capital markets – and global investment portfolios.
Commentary
Emerging Market Local Debt: Growing Depth, Growing Opportunity
Earlier this year, Argentina, the Czech Republic and Uruguay joined the bellwether benchmark for the asset class, JPMorgan GBI-EM Global Diversified, taking the total to 18 countries. China, Egypt and another three countries may enter the index next year. The inclusions will make the EM local debt asset class much larger, deeper and more liquid.
Commentary
Interest Rates: How Superstar Firms Depress R‑Star
Over the past quarter century, large and ever-larger companies have significantly increased their share of total intra-industry sales across a majority of industries. These superstar firms – including Facebook, Amazon, Apple, Netflix and Alphabet’s Google (known collectively as FAANG) – increasingly dominate their respective industries in terms of revenues, profits and stock market capitalization. The winner these days may not take all, but most.
Commentary
Japanese Politics: Caution Warranted
After Japan’s Prime Minister Shinzo Abe reshuffled his Cabinet on 3 August, the big question is whether his administration can regain public support. In just the last two months, Abe's public approval ratings have plunged to around 30% – low enough to raise red flags.
Commentary
Munis in Focus: Credit Risk or Opportunity? Analyzing Munis Today
The muni backdrop looks benign, but be mindful of potential credit risks.
Commentary
The Coming Financial Volatility
Bond investors are from Mars, and central bankers are from Venus – or so suggests the bond market’s negative reaction to signals that the exceptional monetary policy accommodation of the last decade is winding down. Risk-asset markets, however, are ignoring the red flags that the bond markets are waving. Are they right?
Commentary
Looking Past Libor: What’s Next for Investors?
The UK Financial Conduct Authority (FCA) announced on 27 July that it would not sustain the London Interbank Offered Rate (Libor) – the key (and controversial) benchmark for hundreds of trillions of derivatives contracts – after 2021.
Commentary
European Periphery: Unsafe at Any Speed?
Five years ago this week, Mario Draghi’s landmark “whatever it takes” speech turned the tide of the euro crisis, the president effectively clarifying the European Central Bank’s role as a conditional lender of last resort to eurozone sovereign borrowers.
Commentary
Trump’s Victory: What’s Next for Currencies?
Much of the world has been waging a cold currency war since the autumn of 2016, and so far the winner is Donald Trump. The dollar rally that followed the U.S. election is over, and this past week the U.S. Dollar Index (DXY, which tracks the dollar’s value versus a weighted basket of major currencies) sank to its lowest level in more than a year.
Commentary
China and Emerging Asia: A New Dawn for the Capital Markets
Asia’s integration into world financial markets may be accelerating.
Commentary
Europe’s Long‑Term Economic Outlook: Better Now, Challenges Ahead
When PIMCO professionals gather for our annual Secular Forum to discuss the long-term global economic outlook, views on Europe invariably gravitate on two themes: anemic GDP growth and political risk.
Commentary
Housing Finance Reform: First Things First
Why is the U.S. housing sector diminishing when demand for housing remains robust?
Commentary
The Fed Balance Sheet and the Taper Tantrum That Ain’t (Yet)
The Federal Reserve is likely to begin normalizing its balance sheet in 2017. Why hasn’t this news rattled the bond market?
Commentary
Continued Weak Core CPI to Test the Fed
A growing number of Federal Open Market Committee officials have voiced concerns over decelerating inflation since the June FOMC meeting, and the latest inflation print likely did little to alleviate them.
Commentary
Political Shakes, Monetary Withdrawal
A review of last month’s market-moving events across countries and asset classes.
Commentary
In Search of Yields, Are Cash Investors Becoming Complacent About Risk in Prime Funds?
Since the global financial crisis, the notion of what constitutes an appropriate liquidity management and capital preservation strategy has become a source of heated debate among professional institutional investors and retail-oriented allocators alike, with varying opinions on how to balance a preference for returns against the need for immediate liquidity and capital preservation.
Commentary
Long‑Term Outlook for Australia: Less Rosy
After 25 years of steady economic growth, Australia is on the verge of wresting bragging rights from the Netherlands for the longest period on record without a recession. While this historic event should be celebrated, the future may not be as rosy.
Commentary
Avoiding Passive Pitfalls in Municipal Strategies
An active approach to the complex, fragmented municipal bond market may help investors avoid several common drawbacks of passive strategies.
Commentary
Time to Tend Your Hedges?
Equity market peaks (and troughs) are impossible to identify in advance. But this doesn’t mean that equity investments should simply be “set it and forget it.”
Commentary
Fed Minutes: Mission Accomplished on Rates, But Questions Remain on Balance Sheet Plan
The Federal Reserve hiked rates as expected at its meeting on 13–14 June 2017, and it made news by providing important details about its plans to normalize its balance sheet. However, one crucial detail the Fed did not provide: when it will commence that process of balance sheet normalization.
Commentary
ECB Policy: Are Markets Overreacting to Draghi?
Normalization of the European Central Bank’s (ECB) monetary policy never was a question of “if” but one of sequencing, timing and calibration. Financial markets reacted to ECB President Mario Draghi’s speech in Sintra this past week in a way suggesting the ECB might change all three of those policy normalization parameters.
Commentary
All Skewed Up? The Active Versus Passive Debate
There has been a lot of discussion about a recent academic paper, "Why Indexing Works," which makes a statistical case for passive investing in equities. The same logic applied to bonds, though, may make the opposite case: Passive fixed income management doesn't work, but active bond management does.
Commentary
Politics to Shape the UK’s Long‑Term Outlook
Just as the global economy faces a number of important pivot points that investors should look for over the next several years, so some domestically generated pivot points will shape the UK economy in the coming years – largely stemming from UK politics.
Commentary
What the Latest Healthcare Hiccup Means for the U.S. Economy
The effort to repeal and replace “Obamacare” hit yet another stumbling block this week when U.S. Senate Majority Leader Mitch McConnell decided to pull the bill from consideration after realizing he did not have sufficient votes for it to pass.
Commentary
Asia’s Long-Term Outlook: All Eyes on China’s Party Congress
The global economy faces several potential pivots in the direction and scale of monetary, fiscal, trade, geopolitical and exchange rate policies. One in particular will help determine the long-term outlook for China and emerging Asia.
Commentary
10 Reasons ESG Investing Is Growing
According to the Global Sustainable Investment Alliance, over $22 trillion of assets were managed under responsible investment strategies globally in 2016, up 25% from two years before. This is one of many statistics showing Environmental, Social and Governance (ESG) investing moving into the mainstream. We see 10 major trends contributing to the rise.
Commentary
Harnessing Uncertainty: Five Opportunities in the Core Bond Market
This is an exciting time to be an investor, but it’s also a very uncertain one. Risks to both the upside and downside are much higher than they were even a year ago.
Commentary
The Prize and the Price of Opportunistic Tightening
The U.S. bond market’s post-election optimism has now evaporated: The 10-year nominal U.S. Treasury yield has dropped by almost half a percentage point from its mid-March 2.62% post-election high, with lower implied inflation rather than lower real yields accounting for most of the decline.
Commentary
Emerging Markets: Commodity Oddities
Why falling commodity prices may not upend the EM rally.
Commentary
CPI Lags Expectations for a Third Straight Month
Another soft U.S. core Consumer Price Index (CPI) inflation report – the third in a row that has lagged expectations – could complicate the Fed’s intentions to raise rates one more time this year, as the central bank’s Summary of Economic Projections currently forecasts.
Commentary
Four Reasons Why the Fed’s Balance Sheet Unwind Shouldn’t Rock the MBS Market
Market participants increasingly expect the Federal Reserve to begin unwinding its balance sheet during the second half of 2017, and many have speculated that the agency mortgage-backed securities (MBS) market – and the U.S. housing market more broadly – could suffer as a result.
Commentary
Economic Growth Amid Policy Shifts
Political risk, reform efforts and potential monetary policy shifts cloud the outlook for China, Europe and the U.S.
Commentary
New Bond Issuance: The Active Management Advantage
New equity offerings can garner media buzz. Think of recent initial public offerings (IPOs) by Snapchat, Alibaba and Visa. Business media enthuse, investors clamor, and share prices often rise, at least initially.
Commentary
Politics: The Greatest Show on Earth?
A review of last month’s market-moving events across countries and asset classes
Commentary
2017 Secular Outlook: Pivot Points
With the probability of recession sometime in the next five years around 70% in our view, now may be a critical time to prepare for when the cyclical tailwind that began last year begins to fade. Over the next five years, the global economy may undergo five significant pivots in the direction and scope of monetary, fiscal, trade, geopolitical and exchange rate policies. Are investors too optimistic about the future economy? We address this and other crucial questions in PIMCO’s 2017 Secular Outlook – our long-term view for the global economy and markets.
Commentary
Fed Minutes: Cap and Trade
The minutes of the May Federal Open Market Committee (FOMC) meeting, released Wednesday, provided (as expected) more information on the committee’s thinking about how and when to start the policy of normalizing the size of the Federal Reserve’s balance sheet.
Commentary
For the UK, Is the Real Risk Above- or Below-Target Inflation?
In its recent quarterly inflation report, the Bank of England gave the market some fascinating insights into the challenges it will face in setting appropriate monetary policy over the coming years.
Commentary
Getting More From Your Equity Allocation
How can equity investors address the triple threat of a low return environment, scarcity of alpha and the tendency to chase performance?
Commentary
The Sources, Benefits and Risks of Leverage
When evaluating investment strategies it’s critical to understand the nature of the leverage being used.
Commentary
ESG in Action: Evaluating European Utilities
Why understanding Environmental, Social and Governance (ESG) factors is critical for credit analysis of European utilities.
Commentary
OPEC and Oil Prices: Looking Ahead to the May Meeting
The oil market outlook is always a bit complicated, in part due to the impact OPEC can have on balances. For all the attention paid to changes in U.S. shale output, OPEC is capable of swinging oil balances more in a single month than U.S. shale can in a year.
Commentary
Take Action: Five Ideas for DC Plan Sponsors
Active management has the potential to provide diversification, generate income and mitigate the risks of higher inflation and rising rates.
Commentary
Puerto Rico's Title III Bankruptcy: Initial Views and Expectations
In many ways the filings may mark “the end of the beginning” (as Churchill once said) of this chapter for Puerto Rico.
Commentary
No Single Culprit for April’s Weak U.S. CPI
Unlike in March, April’s soft inflation across a range of core goods and services prices cannot be explained away by large, one-off price adjustments or other quirks in the data.
Commentary
All Asset All Access, May 2017
In this issue, Research Affiliates offers insight into its CPI-based secondary return benchmarks, its business cycle modeling and continued opportunities in emerging markets.
Commentary
French Election: A Positive Result for Markets, But Don’t Be Complacent
Centrist candidate Emmanuel Macron will be inaugurated as the next French president on 14 May, thanks to a clear win in the second-round runoff against the far-right candidate Marine Le Pen.
Commentary
Brazil: Lower Rates for Good?
Brazil is often known for soccer, samba and pristine beaches. Among investors, something else also stands out about Brazil: double-digit interest rates that are significantly higher than its peers’ (see chart). That may soon change.
Commentary
Productivity: A Surprise Upside Risk to the Global Economy?
A bottom-up look at major industries around the world reveals significant potential for productivity growth.
Commentary
Leaving Money on the Table? Don't Invest in Credit Passively
When it comes to credit investing, we believe passive investors are implementing a suboptimal strategy and may be leaving money on the table as active management offers several potential advantages.
Commentary
A Less ‘Impulsive’ China: Bracing for Lower Growth
By focusing so intensely on U.S. political developments, investors risk missing a silent shift in what has arguably been the strongest driver of global reflation in the last five years:...
Commentary
Higher Mortgage Rates Are Likely With Proposal of ‘Single Security’
The Federal Housing Finance Agency’s proposal to increase liquidity and reduce costs to taxpayers could actually lead to reduced liquidity and higher mortgage rates.
Commentary
Trump’s First 100 Days: Should Investors Take Notice?
Looking at several metrics – legislative achievements, staffing in key areas and executive orders – President Trump’s first-100-day track record has been mixed.
Commentary
Brighter Outlook for Commodities Suggests a Fresh Look at Investment Benefits and Risks
Though uncertainties remain, we have a broadly positive outlook for commodities in the next year.
Commentary
A Fortuitous Coincidence for the ECB
PIMCO expects no policy changes at the ECB Governing Council meeting on Thursday, aside from a minor adjustment to the bank’s outlook for growth. We think ECB President Mario Draghi will repeat the message that although the economic recovery is gaining momentum...
Commentary
Peru’s Resilience
Many investors are concerned about the risks to growth and the potential for higher inflation in Peru following two recent shocks.
Commentary
French Election: Near‑term Risks Recede But Caution Still Warranted
Markets breathed a sigh of relief today as the moderate centrist candidate Emmanuel Macron qualified for the second round of the French presidential election in two weeks, together with the far-right anti-establishment candidate Marine Le Pen.
Commentary
Why Has U.S. Stock Market Volatility Collapsed?
If you had asked that question at the end of February this year, you could have plausibly pointed to two key factors to explain the drop in volatility. First, the U.S. equity market (as measured by the S&P 500) had rallied 10% since November’s surprise election of Donald Trump – and rallies in equities typically are accompanied by drops in volatility.
Commentary
Bonds Are Different: The Active Advantage
Ask an investor if most active bond funds outperform their passive counterparts and the response is likely to be "no."
Commentary
The Fed’s Balance Sheet: Some Insights in March Minutes, But Questions Remain
The way in which the Fed normalizes its balance sheet will have important implications for markets.
Commentary
Scaling Back: A Look at Six Key Macro Risks and Economic Drivers
We are now more confident in our baseline view that the global economic expansion will be strengthening and broadening over our cyclical horizon.
Commentary
Income Fund: 10 Years of Meeting the Income Challenge
It’s hard to imagine a more challenging decade for income investors than the past 10 years. It was bookended by the great financial crisis and the surge in populist politics that led to the election of Donald Trump as U.S. President.
Commentary
Removing Accommodation
The Federal Reserve faces three complications to removing monetary policy accommodation.
Commentary
Brexit Begins: Implications for Investors
We caution investors on sterling and UK gilts as Brexit negotiations commence and the likelihood of a “hard Brexit” remains high.
Commentary
Emerging Markets: The Clouds Lift
As 2017 progresses and the priorities of the Trump administration take shape, the outlook for emerging markets (EM) has evolved from uncertain to promising.
Commentary
Healthcare Reform’s Demise: Tax Reform Will Be Hard, Too
After the healthcare bill stalled in the House of Representatives, the most salient question is what’s next?
Commentary
Canada’s ‘Wait and See’ Budget
As expected, Ottawa presented a cautious budget for 2017 that focused more on implementation than on bold new initiatives, and there is much to commend about Finance Minister Bill Morneau’s wait-and-see approach.
Commentary
Scaling It Back
We expect the global economic expansion to strengthen and broaden over the cyclical horizon, but with improved growth and inflation prospects, central banks may scale back accommodation.
Commentary
Fed on Inflation: ‘Stabilize’ … ‘Sustained’ … ‘Symmetric’
Although there was no drama in the Federal Reserve’s decision today to remove 25 basis points of accommodation (also known as a policy rate hike), there was a surprising – and laudable – amount of substance in the changes to the accompanying Fed statement.
Commentary
The Bank of England’s Corporate QE: A Middling Outcome
In August of last year, the Bank of England (BOE) announced a new round of quantitative easing (QE) that included the purchase of sterling-denominated corporate bonds. Alongside a cut in interest rates, the Corporate Bond Purchase Scheme (CBPS) was designed to boost the UK economy amid a more negative outlook post-Brexit.
Commentary
In Credit Research, Indexes Equal Opportunity
Changes in index composition represent a source of potential return for active bond managers.
Commentary
U.S. Jobs Report: What’s Behind the Uptick in Labor Participation?
Today’s U.S. labor market report solidified market expectations that the Federal Reserve will raise the fed funds rate by 25 basis points at its two-day meeting next week.
Commentary
The Case for ECB Tapering
There is a strong case for the ECB to continue tapering its QE programme, to alter its forward guidance and to begin normalising policy rates.
Commentary
European Banking Outlook: The Storm Has Passed
Why Europe’s banks may be on a sounder footing in 2017.
Commentary
The Pace of Trump’s Policy Agenda: Three Big ‘Ifs’
It’s hard to believe that U.S. President Donald Trump has only been in office for a month, given the dizzying activity in Washington. Yet our observations from before the inauguration seem to be holding true, at least so far: Governing is indeed harder than campaigning.
Commentary
Fed Minutes: ‘Fairly Soon’
With Federal Reserve Chair Janet Yellen on Capitol Hill for two days of testimony last week, plus Vice Chairman Stanley Fischer’s interview on Bloomberg TV, plus the upside surprise on U.S. CPI inflation data released on 15 February, the minutes...
Commentary
Russia: Stagnant Stability
A recent trip to Moscow on the 100th anniversary of the 1917 revolution revealed not a whiff of revolutionary change in the economy, but rather stagnant growth mixed with structural stability. We could simply call it “stagnant stability.”
Commentary
French Election Jitters Underscore Caution When Investing in Europe
Market nerves in anticipation of the French presidential elections in April and May 2017 have driven a spike in 10-year French and Italian government bond spreads, which have climbed 30 to 40 basis points (bps) in recent weeks (to 75 bps and 195 bps over bunds, respectively).
Commentary
How the Fed’s Resolve Can Calm the Bond Market
The Fed could contain inflation fears in the bond market by taking a more hawkish stance.
Commentary
More Senior Than What? Potential Risks in Senior Bank Loans
Floating rate bank loans, which are typically the most senior debt in an issuer’s capital structure, have traditionally been considered more resilient than high yield bonds in the event of default.
Commentary
A New Phase in the Cold Currency War
One of the most interesting and, for many observers, surprising market developments year-to-date has been the gradual descent of the broad trade-weighted U.S. dollar from the lofty 14-year highs reached late last year.
Commentary
The Bank of England: How to Justify Doing Nothing
Ahead of Thursday’s quarterly Inflation Report, the Bank of England’s Monetary Policy Committee (MPC) faced a relatively tricky challenge.
Commentary
Eurozone Headline Inflation is Up, but Keep an Eye on Core
We see little probability of high core inflation rates in the eurozone, but instead a gradual increase toward the ECB target of just below 2% over the next few years.
Commentary
Canada's 2017 Economic Outlook: A Tale of Two "Tails"
Investors need to prepare for more extreme economic outcomes – both good and bad.
Commentary
The Paradox of Chinese Drift
While Chinese growth looks stable into early 2017, a more marked slowdown by the second quarter appears inevitable.
Commentary
Turkey – A Rolling Challenge
Turkish asset prices have come under heavy pressure recently, and the Turkish lira fell to a record low against the U.S. dollar in January.
Commentary
Sustainable Development Goals: Common Goals, Our Approach, Your Impact
How the United Nations Sustainable Development Goals can serve as a framework for ESG investors
Commentary
China: For Global Investors, It’s All About the Currency
Chinese local interest rates rose substantially late last year, and many bond offerings have been canceled, creating financial strain for some Chinese companies.
Commentary
Fed Minutes: Tilting More Hawkish
Many had not expected the minutes of the 14 December 2016 Federal Reserve meeting released this afternoon to make much news.
Commentary
Navigating Change: Opportunities in Quality Credit, Specialty Finance and Mortgages
The global economy is going through significant change, as Donald Trump’s incoming administration and shifts in public sentiment in other major economies create potential for new opportunities and risks.
Commentary
How Much Do I Need To Retire?
Grappling with the question of how much is one of the toughest relating to pensions
Commentary
Income Strategy Update: Active Positioning for a Volatile and Uncertain Environment
Markets have generally been risk-on since Donald Trump’s election as president. Yet tremendous uncertainty remains over future fiscal and monetary policies, and volatility persists at high levels.
Commentary
The New Cold Currency War
Earlier this year, we saw a transition from an old-style currency war (openly fought with negative interest rates and quantitative easing) to the “Shanghai co-op” – an implicit agreement, or truce, among major central banks that excessive dollar strength was bad for the global economy.
Commentary
The Fed Is Staring at a Nasty Rate Dilemma in 2017
Policymakers may have to juggle a rising dollar, higher yields and a lag in any Trump stimulus.
Commentary
Is It Really All About the Numbers?
Has the 70-80% replacement rate for retirement income met its use-by date?
Commentary
Will the Trump Administration Target the DOL Rule?
With deregulation seemingly high on the agenda for President-elect Donald Trump, the fate of the Department of Labor’s “fiduciary rule” is now unclear.
Commentary
Slower CPI Inflation: ’Tis the Season
The 15 December Consumer Price Index (CPI) release was more or less in line with expectations, but it did show a moderate deceleration in inflation from recent months.
Commentary
The Fed: Betting on Trumponomics
While most observers had expected correctly that the Federal Reserve would hike interest rates by 25 basis points today – markets had priced in literally a 100% chance – they did not think the Federal Open Market Committee (FOMC) would materially change its September projection for two hikes in 2017.
Commentary
Are Republican Presidents OK With Recessions?
You are probably familiar with the well-known statistic that, on average, the U.S. stock market has historically performed better when a Democrat rather than a Republican occupies the White House.
Commentary
Making America Reflate Again?
Donald Trump took the world by surprise in winning the U.S. presidential election.; While the Trump triumph and ensuing policy conjecture held the spotlight, a flurry of positive economic releases globally signaled solid fundamentals.; Risk sentiment built, particularly in the U.S.
Commentary
ECB Policy: 1% Is the New 2%
At its 8 December Governing Council meeting, the European Central Bank (ECB) extended its asset purchase program by nine months to the end of December 2017, but at a rate of €60 billion per month – a decrease from €80 billion currently.
Commentary
OPEC Deal Impresses, But Implementation Will Be Key to Prices
We believe the impact on balances and prices ultimately will depend on five key variables.
Commentary
Italian Referendum: Back to Politics as Usual in Italy
With around 60% of voters opting for a “no” and nearly 70% turnout, Italians on Sunday firmly rejected a constitutional reform that would have removed power from the Senate and left the lower house as the key legislative chamber.
Commentary
New Paradigm?
Secular forces in the global economy suggest we aren’t likely to see a new paradigm of stronger growth, higher inflation and higher interest rates under the Trump administration.
Commentary
PIMCO's Global Advisory Board Surveys the World Economy
The board’s expertise constitutes a valuable input into our investment process.
Commentary
Fed Minutes and the Election: The Case for December Grows Stronger
The minutes reveal a committee that had expected to hike at the meeting on December 13-14. Developments since could only have strengthened the case.
Commentary
Breakeven Inflation Rates: What’s Beyond the Post‑Election Bump?
Trump’s fiscal and immigration policies appear likely to boost the near-term inflation trajectory.
Commentary
Beyond Libor: The Evolution of ‘Risk‑Free’ Benchmarks
The how of transitioning to a new or revised benchmark rate will be as critical as defining what the new benchmark should be.
Commentary
Muni Investors: Look for Opportunities Amid Post-Election Policy Shifts
The tax-exempt municipal market has faced some challenges this fall: Yields trended higher in early October as the market struggled to digest the largest new issuance period of the year, and the indigestion has only increased following last week’s U.S. election outcome.
Commentary
Leveraging Opportunities in Bank Loans to Enhance Return Potential
With low interest rates across global markets, a number of investors are turning to credit assets to enhance returns.
Commentary
What Do the U.S. Elections Mean for Emerging Markets?
For much of 2016, a unique alignment of push and pull factors has driven strong performance in emerging markets (EM). The election of Republican Donald Trump and Republican majorities in the U.S. Congress on 8 November, however, represents a pivot point.
Commentary
Investors: Focus on State Polling as U.S. Election Nears
With less than a week to go until the U.S. presidential election, investor anxiety about next Tuesday’s outcome is running high, as evidenced by the recent move in risk assets.
Commentary
Fed Statement: No Waves, December Hike Still Likely
Last month, when the minutes from the Federal Open Market Committee (FOMC) meeting in September were released, they revealed that the decision not to hike the policy rate was a close call.
Commentary
Dollar Strength: Déjà Vu All Over Again?
Have you ever wondered why global markets have been so calm since the volatile first quarter? Well, the halt in the U.S. dollar’s appreciation played a major role.
Commentary
Popularity Up, Pound Down: Brexit and Volatility
Since the Conservative Party Conference earlier this month, UK asset markets have become increasingly sensitive to the UK’s prospective trading arrangements post Brexit.
Commentary
Asset Class Correlation: Untangling the Web
Understanding asset class correlation patterns is key to understanding true portfolio risk factor exposures and the embedded assumptions that inform investment decisions.
Commentary
Trouble with the Curve
A review of the month’s market-moving events across countries and asset classes.
Commentary
The ECB: A Little More Easing Before a Thorny Exit
Ensuring a smooth exit from extraordinary monetary policy will be no enviable task.
Commentary
U.S. Inflation Still on Track to Hit 2%
Today’s CPI release was a bit of a mixed bag, but overall it doesn’t change our view that headline year-over-year inflation should accelerate toward 2.0%–2.5% over the coming year.
Commentary
Active ETFs for Liquidity Management and Capital Preservation
As reform alters the landscape, investors look beyond money market funds.
Commentary
Money Market Reform: DC Plans Adapt to Sweeping Change
The SEC’s sweeping changes will likely make money market funds less risky – but far less attractive – to participants in defined contribution plans.
Commentary
As New SEC Rules Take Effect, It May Be Time to Look "Under the Hood" of Your Money Market Fund.
As new SEC rules take effect, it may be time to look “under the hood” of your money market fund.
Commentary
The Fundamentals of RAE: Pitfalls of the "Alpha Mirage"
With the soaring popularity of smart beta strategies, we see lots of investors flocking to whatever strategies have the best three-, five- and 10-year performance – and performance-chasing may ultimately be value-destroying. Some popular strategies’ historical success is little more than an “alpha mirage,” attributable mainly – and in some cases, entirely – to rising relative valuations. We favor a systematic process that results in dynamic factor exposures while still delivering broadly diversified, economically representative portfolios.
Commentary
What Lies Beneath
In our outlook for the remainder of this year and for 2017, we discuss the likelihood of continued economic expansion while assessing the underlying risks to growth.
Commentary
Rising Leverage in Emerging Asia: Where Is It Headed?
Japan offers lessons for investors worried about rapidly rising debt levels in emerging Asia, especially China.
Commentary
Fed Statement: Let the Dots – and the Dissents – Do the Talking
Going into today’s Federal Open Market Committee (FOMC) meeting, the question was in what way – or ways – the statement and the accompanying Summary of Economic Projections (SEP) would signal the committee’s conviction that it expects to hike rates later this year.
Commentary
The Rising Costs of Capital Preservation
An investment in money market funds since the beginning of 2009 would have decreased purchasing power by more than 14% on a cumulative basis.
Commentary
The New Neutral Yield Curve: A New Framework for the Bank of Japan
The Bank of Japan (BOJ) is at a crossroads. Despite a 3.5-year unprecedented experiment with unconventional policy tools, a war against deflation is still unwon. Meanwhile, the BOJ appears to be aware of its current policy limit or at least admits there are side effects. So what now?
Commentary
A World of Pure Imagination
A review of the month’s market-moving events across countries and asset classes.
Commentary
After Record USDA Projections, Where Are Corn Yields Headed?
Reports of what could be the biggest U.S. corn crop ever have put pressure on prices in recent weeks.
Commentary
Listening for the Market's Bell
The old Wall Street expression is “They don’t ring a bell at the top.” This snarky adage is usually employed by those saddened financial managers who ride a successful investment to a peak and then watch in horror as it reverses course to a level below their cost basis. They lay the blame at the feet of the amorphous market that failed to signal it was time to exit the ride.
Commentary
UK Corporate Bonds: Tailwinds from the BOE
Sterling investment grade corporate bonds have rallied by around 5% more than the equivalent UK gilts since the Brexit vote. While the quick gains may be over, we still see value – thanks to technicals as much as fundamentals.
Commentary
ECB Preview: More Easing Expected In December
We expect the European Central Bank (ECB) to leave policy unchanged at the 8 September Governing Council meeting.
Commentary
Libor Rising and Money Market Reform: Five Key Questions
Anticipation of U.S. money market reform in October has pressured short-term funding rates higher. What are the implications for banks and investors?
Commentary
Disruptive Regulation: A Secular Investment Opportunity
It’s been nearly a decade since the global financial crisis prompted an onslaught of regulations intended to abolish excessive risk-taking and make the financial system safer. Yet the implementation of reforms – and their disruptive effect on financial business models – will peak only over the next few years.
Commentary
Credit Markets Still Supported By Global Trends
Even after this year’s rally, credit remains one of the more appealing sources of income in financial markets.
Commentary
Deceptive Calm: Investing Globally in Stable But Not Secure Markets
As the year progresses, markets are displaying a strange dichotomy. Thirty percent of sovereign debt globally now offers negative yields, suggesting investors are increasingly focused on certainty and capital preservation even as several major central banks seek to stimulate growth and risk-taking.
Commentary
Asia-Pacific: Investment Implications of Our 2016 Secular Outlook
PIMCO’s 2016 Secular Outlook highlights a world that, over the next three to five years, will be stable but not secure.
Commentary
With Decisive Policy, Bank of England Stacks Odds in Its Favour
Look for very easy UK monetary policy to be with us for the cyclical horizon.
Commentary
A Constructive Case for Emerging Markets
Improving fundamentals in emerging markets warrant a more optimistic investment approach.
Commentary
High Yield Municipals Find a Sweet Spot
PIMCO believes the macro environment remains supportive of the municipal asset class. We see a U.S. economy that continues to expand, which is generally good for municipal credit fundamentals. Municipal defaults generally remain low. Historically, high yield municipal default rates have been significantly lower than high yield taxable counterparts. Moving forward, credit selection remains key. We continue to see value in MSA (Master Settlement Agreement) tobacco bonds; we believe risks to most Puerto Rico governmental bonds remain skewed to the downside, but we continue to assess the opportunities in the Territory.
Commentary
Asset Class Valuations: The Perceived Price of Certainty
Comparing P/E ratios across asset classes shows the perceived certainty of U.S. Treasuries coming at an expensive price.
Commentary
Libor: A Small Move Marks a Big Change
New U.S. money market fund rules have been both an albatross for money market investors and a beacon for ultrashort bond funds since they were announced by the SEC two years ago.
Commentary
Targets and Tactics: Overcoming Lower Return Expectations
As consensus grows on the prospect of lower asset class returns, investors are taking a fresh look at the potential consequences and solutions.
Commentary
Catching Up With the Medians
Saving for retirement: How well is the “median” U.S. family doing?
Commentary
The BOJ Hit Its Limit: A Summer Relief for Banks
The message was clear: The Bank of Japan (BOJ) finally admitted that its current policy framework hit the limit. Disappointed? Well, at least the BOJ’s decision on 29 July provides some relief for Japanese banks, insurance companies and pension funds.
Commentary
Detecting a ‘Smart’ Investment Strategy
How to pick smart-beta strategies using methods similar to those for selecting active managers.
Commentary
Losses on Italian Non-Performing Loans: Severity and Solutions
Losses look manageable over time, but a prompt solution now seems likely.
Commentary
King, Keynes and Knight: Insights Into an Uncertain Economy
The concept of “radical uncertainty” helps shed light on macro analysis in a world of insecure stability.
Commentary
Managed Futures and Multi-Strategy Funds: The Search for Diversification
Manager selection is critical: Only a subset delivered when it counted most.
Commentary
Are You Cashing In With ETFs?
How getting active may beat being passive in today’s market environment.
Commentary
National Monetary Policies Often Correlate, Sometimes Coordinate, Rarely Cooperate
International monetary policy cooperation could pose a threat to the credibility and public support.
Commentary
Commodity Investing: A New Take on Equities Versus Futures
A combination of commodity futures and broad stocks seems to provide better return per unit of risk than natural resource equities.
Commentary
Brexit: What’s Next for Markets, the UK and the Global Economy
In the following Q&A, portfolio managers Andrew Balls, Mike Amey, and Philippe Bodereau discuss PIMCO’s outlook for the UK and the European Union amid Brexit, and assess global ramifications.
Commentary
U.S. Real Estate: A Storm Is Brewing
Prices could decline amid volatility, creating opportunities for nimble investors.
Commentary
Come What May
A review of the month’s market-moving events across countries and asset classes.
Commentary
China and the New Global Monetary Order
China’s integration into the world economy began decades ago, but its integration into the global financial system is relatively new.
Commentary
The Global Outlook: Stable But Not Secure
Good investment opportunities remain, but investors must be compensated for growing and heightened uncertainty and risks of policy exhaustion.
Commentary
Liquidity Management and Arbitrage: An Opportunity for Defined Benefit Plans
Markets offer the prospect of defeasing near-term liabilities at a discount.
Commentary
The Downside of Central Bank Independence
Here’s a secular question for you: What if central banks weren’t independent?
Commentary
April Cools
A calmer tone prevailed across markets in April despite major central banks choosing to pause from adding substantial support.
Mixed economic data underscored a tepid fundamental backdrop.
The market rally continued in April, though underlying sentiment may have cooled more than the rally suggested.
Commentary
Canada’s Monetary Policy Stuck Between a Rock and a Hard Place
Understanding a central bank’s reaction function to volatile financial and commodity markets can help investors navigate an uncertain environment.
Commentary
Altitude Adjustment: Investing During a Period of Lower Returns and Higher Volatility
It can be difficult to adjust to the end of a good run. For years following the financial crisis of 2008, investors benefited from a rally in financial markets facilitated in part by expansionary policies of the Federal Reserve and other central banks around the globe.
Commentary
U.S. Housing Shines Bright in Global Economy
Demographics and new housing starts suggest that the U.S. could face a shortage in the near future.
Commentary
Rumpelstiltskin at the Fed
Though it seems incredibly farfetched, a massive Fed gold purchase program could echo a Depression-era effort that effectively boosted the U.S. economy.
Commentary
Corporate Management: Discerning Opportunities and Risks in Asian Credit
The annual movement of wildlife across the Serengeti-Mara ecosystem in Africa is one of the greatest spectacles in the natural world. The horizon fills with wildebeest, zebra, eland and gazelle migrating for fresh grass, tracked by Africa’s great predators.
Commentary
Factor Investing: Good in Theory, Difficult in Practice
Although factor investing can potentially deliver a return above that of the broader equity market, poor implementation can lead to unexpected outcomes.
Commentary
March CPI Report: Valuations Matter
The March report on the U.S. Consumer Price Index didn’t paint the rosy picture some were expecting. Headline CPI year-over-year was 0.9% versus the expected 1% and core CPI ticked lower to 2.2% for the 12 months ended March, down from 2.3% in February. Despite this March surprise, we believe Treasury Inflation-Protected Securities (TIPS) can weather much more before they underperform nominal Treasuries.
Commentary
Spring Awakening
In a volatile market environment, investors may look to cash alternatives in their effort to add stability to portfolios.
Commentary
The Times Are a--Changin'
Dovish comments and actions by central banks, including the Federal Reserve, helped sustain the market’s rally.
Fundamentals still indicated tepid growth even as global risk appetite built further through the course of the month.
March highlighted that shifts in political trends could feature prominently in the remainder of the year.
Commentary
European Bank Regulation: Expect a Shift
Regulatory uncertainty will create opportunities for private capital as banks retrench from some lending markets.
Commentary
Challenges Remain for Asia's Economies
Complicated growth and policy environments in China and Japan create challenges for the region.
Commentary
Harnessing Value in Dislocated Credit
Market volatility, diminishing liquidity and credit imbalances combine to create mispricings and attractive opportunities in leveraged finance.
Commentary
Actively Managing the Evolution in the Insurance Industry
How are insurance companies adapting to low returns, industry consolidation and new regulations?
Commentary
Wages Are Rising: Good News for Workers, the Economy … and the Fed
The recovery from the Great Recession of 2007–2009 has returned to the pattern of past cycles in which labor’s share of national income begins to rise. A challenge the Fed will face as it tries to engineer a “dovish” rate hike cycle is that investors, households and firms tend to associate Fed rate hike cycles with Fed efforts to reduce or limit inflation. But the Fed wants higher inflation from today’s levels, so it will not be inclined to run a hawkish policy that would prevent it. In the Fed’s current model, holding constant expected inflation, the only way to get inflation moving up to its 2% target is for the unemployment rate to be pushed below NAIRU (the non-accelerating inflation rate of unemployment).
Commentary
Arnott on All Asset March 2016
Rob Arnott, head of Research Affiliates, shares his firm’s market insights and allocation strategies for PIMCO All Asset strategies.
Commentary
Passive-Aggressive: Index Funds and Risk in European Bond Benchmarks
In our view, using a bond index fund today exposes portfolios to greater interest rate risk without commensurate compensation in the form of yield.
White Paper
The Best Time to Accumulate Long Credit Bonds May Be Now

by PIMCO, 3/28/16
Waiting until interest rates increase may not be the optimal strategy to acquire long credit bonds for plan sponsors concerned about potentially rising rates. Instead, these plan sponsors should consider buying long credit bonds now, while hedging the associated duration risk until rates rise to more comfortable levels. In doing so, investors could potentially earn an attractive yield on duration-hedged portfolios, realize compelling returns on investment grade fixed income portfolios, simplify the operational process of extending duration when rates do rise and improve credit-spread match relative to liabilities.
Commentary
Calmer C's Ahead?
China, Commodities and Central Banks Dominate the Global Outlook. Read our global economic outlook for the near term and implications for asset classes.
Commentary
An Ugly Deleveraging
For the European Central Bank to orchestrate a beautiful deleveraging, the economy needs the right mix of growth and inflation.
Commentary
Fear…Not?
The fears that had cast a pall over January weighed on the markets in early February as well, but sentiment improved sharply as the month progressed. Encouraging U.S. economic data contributed to an improvement in global risk appetite.
Investors marveled at yet another V-shaped trajectory in the markets in February, but concerns still lingered.
Commentary
Time to Move
PIMCO believes now is the right time for investors to consider a move into higher-quality credit as well as select high yield and bank loan sectors.
Commentary
The Recession of 2020
A U.S. recession this year is much less likely than a recession in, say, 2020.
Commentary
Arnott on All Asset February 2016
Rob Arnott, head of Research Affiliates, and Christopher Brightman, Research Affiliates’ Chief Investment Officer, share their firm’s market insights and allocation strategies for PIMCO All Asset funds.
Commentary
Asia-Pacific: A Broader Investment Landscape in 2016
In the turbulent market environment, five longer-term investment trends stand out for 2016.
It has been a turbulent year for Asia’s financial markets. In the following interview, Eric Mogelof, head of Asia-Pacific at PIMCO, puts events in perspective and discusses investment trends in the region for the year ahead.
Commentary
2016 Outlook: A Slow and Gradual Fed is Nothing for Municipal Investors to Fear
The combination of continued U.S. growth, muted global inflationary pressures and gradual Fed tightening bodes well.
Commentary
Negative Interest Rate Policies May Be Part of the Problem
Investors may see these experimental policy moves as damaging to financial and economic stability.
Commentary
70 Is the New 65: Demographics Still Support 'Lower Rates for Longer'
The so-called demographic cliff remains at least a decade away; meanwhile, global demographics should continue fueling the savings glut.
Commentary
Investing for Retirement: A Focus on Sustaining Income
Longevity protection strategies can simplify retirement planning and may reduce the risk of running out of money in retirement.
Commentary
Monetary Policy Stuck in the Mid?Atlantic
As we look forward to 2016, once again we are faced with the question of whether the Monetary Policy Committee (MPC) at the Bank of England (BOE) will finally raise interest rates, or whether this will prove to be another year where expectations for a move in official rates are to be dashed.
Commentary
Will Lower Interest Rate Volatility Last?
Though volatility has diminished in recent years, U.S. interest rates are unlikely to be structurally less volatile going forward.
Commentary
Policy Support Amid Sluggish Growth: Asia’s Economies in Transition
Policy will be critical over the coming year but options are constrained by excessive debt, domestic politics and potential asset bubbles.
Commentary
Money Market Reform and DC Plans Time Is Almost Up
SEC reforms will make money market funds far less attractive but sponsors have several capital preservation alternatives to consider.
Commentary
Federal Reserve Outlook for 2016
Up until the Federal Reserve’s historic December meeting, when the central bank increased its policy rate for the first time since 2006, investors were fixated upon when the Fed might finally move its policy rate up from the range of 0%–0.25%. The Fed set the rate at the zero bound in 2008 to combat a plunge in economic growth and to fight disinflationary pressures tied to the debt deleveraging process.
Commentary
The Sea Change in Repos, Swap Spreads and Dealer Balance Sheets: How Active Management May Benefit
Since the financial crisis in 2008, global regulators have been working hard to strengthen the banking system and forestall a similar calamity. A torrent of new regulatory requirements for financial institutions, for instance, aims to create global minimum requirements for liquidity and capital, increase transparency and decrease systemic leverage. The transactional intermediation that occurs between borrowers and lenders without governmental oversight – a vital piece of the world’s financial and funding mechanisms – has come under particular scrutiny.
Commentary
Arnott on All Asset December 2015
Rob Arnott, head of Research Affiliates, and Jason Hsu, Research Affiliates’ co-founder and vice chairman, share their firm’s market insights and allocation strategies for PIMCO All Asset funds.
Commentary
Rising Rates: Dispelling the Myth
Bond investors may have little to fear and potentially something to gain from rising interest rates.
Commentary
High Yield, High Opportunity
Valuations have improved and growth should keep defaults low outside of the energy and commodities sectors.
Commentary
Plodding Along? A Discussion of Today’s Global Economy
This year has seen the global economy continue along a path of modest overall trend growth, but the path has been anything but clear, due to the complexities of oil prices, central bank policies and developments in China. In this interview, Richard Clarida, global strategic advisor, and Joachim Fels, global economic advisor, discuss essential questions surrounding the world’s major economies.
Commentary
Gasoline and Coffee Fuel Our Daily Lives. Can Commodities Also Fuel Our Investment Portfolios?
Commodities are a tangible part of our daily lives. They are the food we eat, the energy that powers our cars and heats our homes, the metals that go into our electrical wiring and our jewelry. Yet investing in commodities can seem elusive.
Commentary
Gasoline and Coffee Fuel Our Daily Lives. Can Commodities Also Fuel Our Investment Portfolios?
Commodities are a tangible part of our daily lives. They are the food we eat, the energy that powers our cars and heats our homes, the metals that go into our electrical wiring and our jewelry. Yet investing in commodities can seem elusive.
Commentary
The End of Fiscal Obstruction
Fiscal policy in the U.S., eurozone and Japan looks set to become (mildly) supportive for growth.
Commentary
How European Insurance Portfolios Can Benefit From Alternatives
Adding alternatives may not only make economic sense, but it also has the potential to improve European insurers’ return on capital.
Commentary
The Changing Dynamics of Eurozone Inflation
Europe’s sovereign debt crisis and its governments’ responses to it have changed the relationship between inflation and economic slack in a way that is causing inflation to undershoot the ECB’s forecast.
Commentary
Four Strategies for Navigating the Equity Environment Ahead
Recent market turmoil suggests we could be at a turning point for equities. After several years of high returns and low volatility as the market rebounded off the lows of 2009, supported by unprecedented monetary policies, investors are faced with broadly full valuations, global growth that is still uneven and the prospect of rising rates in the U.S. In this environment we suggest four simple approaches that could enhance returns while potentially reducing risk.
Commentary
European Deleveraging Continues: Alternatives Investment Themes for 2016
With European bank deleveraging expected to continue for the foreseeable future, there are several developing opportunities to look to take advantage of.
Commentary
Gaps, Growth and Headwinds
Global growth is uninspiring. The global economy plods along with aggregate GDP growth of around 3 per cent to 3.5 per cent and similar levels of inflation. This has been true for the past several years and many expect it to continue for at least the next couple. This is partly because trend growth rates in major economies appear to have slowed from the pre-crisis pace. But slow growth is not just a supply-side condition.
Commentary
The ECB’s ABS Purchases – Catalyst or Dud?
Given the limited scope and focus of its ABS purchases, the ECB has not yet revived Europe’s lackluster ABS market.
Commentary
A Very British Recovery
The UK appears to be experiencing a typical British recovery, but needs further improvement to tolerate rising interest rates.
Commentary
Money Glut: More to Come, Still Effective
Given global lowflation pressures, the central-bank-fueled money glut is likely to increase further before year-end.
Commentary
A Fragile Transition Supported by (Further) Policy Accommodation
n the following interview, Portfolio Managers Adam Bowe, Isaac Meng and Tadashi Kakuchi discuss conclusions from PIMCO’s quarterly Cyclical Forum, in which the company’s investment professionals debated the outlook for global economies and markets. They share our views on economies and investment implications across the Asia-Pacific region over the next 12 months.
Commentary
Liquid Alternatives: Considerations for Portfolio Implementation
Since the financial crisis, investors have poured nearly half a trillion dollars into liquid alternative strategies – typically mutual funds and ETFs that deploy non-traditional strategies once reserved for large institutional investors.i These vehicles offer the potential for diversification, downside risk mitigation and attractive risk-adjusted returns with the transparency and daily liquidity many investors desire. Liquid alternatives have been a democratizing force for investors, and we believe today’s market environment arguably has only made them more attractive.
Commentary
In 2015, Volatility from a Phantom Rate Hike
Many investors are familiar with the adage, “they don’t ring a bell,” to warn when it is time to get in or out of an investment. Well, sometimes they do, or so the famed scientist Ivan Pavlov would likely contend. The physiologist trained dogs to salivate at the sound of a bell, having conditioned them to associate the bell with the delivery of food. Pavlov discovered that he didn’t actually have to deliver the food to get the canines to salivate in anticipation.
Commentary
Balancing Risks and Opportunities in the Multi-Speed World
Read our global economic outlook for the near term and implications for asset classes.
Commentary
The Unique Benefits of Mortgage-Backed Securities
MBS have potential to outperform U.S. Treasuries with high liquidity and low correlation to risk assets.
Commentary
Investing for Income: Meeting the Challenges of a Low Yield Environment
For many investors, generating a high and sustainable income stream is challenging in the current secular landscape, which PIMCO calls The New Neutral. Over the next three to five years, we expect to see global economies converging to modest trend growth rates as central banks are constrained to set policy rates at levels well below those that prevailed before the financial crisis.
Commentary
Navigating Divergent Global ILB Markets: Why Are UK Index-Linked Gilts Persistently Overvalued?
Current extremely low and negative real yields on UK index-linked gilts, particularly for long-dated bonds, do not appear to have any fundamental justifications.
Commentary
Equities: Enhancing Your Small Cap Allocation
Our New Neutral outlook is generally supportive of equities: Low discount rates, recovering but muted inflation and a drawn-out business cycle argue for positive equity performance. However, full valuations and uneven growth suggest returns may be significantly lower than long-term averages. This means that capturing equity alpha will be critical for investors to meet their return objectives.
Commentary
Crossover Bonds: Catching the Rising Stars
Many investors seeking yield in the current low interest rate environment are reluctant to take on high risk. Corporate crossover bonds, which straddle the line between the investment grade and high yield bond markets, may offer a solution.
Commentary
Commodities Remain a Valuable Portfolio Allocation
While the last few years of commodity returns are not an aberration, they are also not the norm.
Commentary
The Three Gluts
While the global savings glut is likely the main secular force behind the global environment of low growth, lowflation and low interest rates, both the oil glut and the money glut should help lift demand growth, inflation and thus interest rates from their current depressed levels over the cyclical horizon.
Commentary
The B-Side of Capital Preservation
Vinyl single records have two sides: The A-side is always the well-known hit song by the musician, and the other, called the “B-side,” is often a lesser known (or unknown) work. When it comes to cash management, the hit song on the A-side – “Capital Preservation Is King” – has been played over and over since the financial crisis.
Commentary
Money Market Reform: Reflections on This Critical Inflection Point for Cash Liquidity Investing
On July 23 2014, the Securities and Exchange Commission (SEC) formally approved additional reforms for money market funds. These changes will directly impact institutional investors and definitively alter the dynamics of liquidity markets.
Commentary
The BOJ’s Policy: What’s Next, More Easing? Or Something Else?
Investors are now debating what the next step will be for the Bank of Japan. It is a dramatic turn, isn’t it? Earlier this year, the consensus view was that the BOJ would move forward with additional easing – the question was ‘when’, not ‘if’.
Commentary
Bond Market Liquidity: Don’t Confuse Investment Risk With Systemic Risk
It is not surprising that the subject of bond market liquidity has come under increasing focus among regulators, investors and the media. While banks are now better capitalized, the combination of post-crisis capital and liquidity regulations and a lower return environment has made them less able and less inclined to function as market makers. Although bank-oriented regulation has made the system more resilient and less levered, it has also had the practical effect of reducing liquidity in markets that have historically relied on banks to support trading, such as in the corporate bond market.
Commentary
Secular Outlook: Implications for Asia-Pacific Investors?
We hope you have had the opportunity to review the summary from our secular forum in May: “The New Neutral Revisited,” written by PIMCO’s Group CIO Dan Ivascyn, Global Fixed Income CIO Andrew Balls an?d Global Strategic Advisor Rich Clarida. In this analysis, the authors identify the six key themes that emerged from our discussion, as well as six risks.
Commentary
Volatility as an ‘Opportunity Class’
Is volatility an asset class? It’s a question we often debate, internally and with clients. There’s no simple answer. Either way, though, it’s an academic point that matters less than our belief that volatility is an “opportunity class” – one with a variety of tactical and macro implications.
Commentary
Earning an Illiquidity Premium in Private Credit
With low yields and tight spreads prevalent in traditional liquid fixed income markets, many institutional investors are considering whether higher returns are available by assuming credit risk in private or illiquid form. We believe this type of alternative credit strategy may enhance portfolio returns, but investors should be extremely judicious when giving up liquidity, particularly today.
Commentary
Data Dependence Is Not a Monetary Policy, But Are the Dots?
At its June meeting, the Fed emphasized data dependence in setting monetary policy.
Although a data-dependent Fed is one that appears to retain a great deal of optionality on the timing and pace of future rate moves, data dependence itself is not a monetary policy.
The Fed’s reaction function to evolving data will likely determine the path of policy normalization. The “dot plot” provides some insight, but the dots alone don’t tell us how policy will play out if the macro data evolve differently from the baseline.
Commentary
Outrunning the Bear: Pension Strategy in a Low Return World
Pension investors often seek to meet two conflicting objectives: delivering high absolute returns and managing risk relative to liabilities.
Unfortunately, this approach has not produced the desired result because the strong absolute performance of risk assets has been eclipsed by even-faster growth in liabilities.
With the era of surging liability values most likely behind us, a realistic goal today may be a relative one: outperforming the value of liabilities, by a smaller margin perhaps, but with more diversification and less risk.
Commentary
Inflation Outlook: Approaching Target
Over the next three to five years, PIMCO expects the global economy will continue along a New Neutral path in which major economies tend to drift along at modest growth rates. At our annual Secular Forum last month, our global investment professionals rigorously debated the longer-term, or secular, outlook for the global economy and markets, and the broad conclusions we reached are detailed in “The New Neutral Revisited.”
Commentary
Lies, Damned Lies and Equity Skew?
Equity skew, which at its most basic purports to measure the difference in the value of stock options with different strike prices, is one of the most used (and abused) sentiment measures in the equity options market. While skew measures can occasionally offer valuable information on the flows within equity derivatives, they can also be highly misleading.
Commentary
Picking U.S. Energy, Housing and Other Credit Sectors for the Long Haul
Persistent trends in economies around the world are providing opportunities for focused, long-term investors in the credit markets. Mark Kiesel, Chief Investment Officer Global Credit, discusses promising themes PIMCO sees over the next three to five years, including the U.S. energy revolution, the rising Asian consumer, the ramifications of global banking regulation and latent demand in the U.S. housing market. PIMCO’s global investment professionals gathered in May at our annual Secular Forum to discuss our long-term, or secular, views of economies and markets around the world.
Commentary
Is the European Insurance Sector in a State of Emergency?
Europe’s insurance industry has responded to profound challenges with a high degree of agility and innovation on both sides of their balance sheets.
Commentary
U.S. Stands Out Amid Global Sluggishness
A year ago, PIMCO said the world was in The New Neutral, as the path to recovery dragged on years after the financial crisis. Last month, at our annual Secular Forum in which our global investment professionals gathered to discuss our long-term outlook, we affirmed that thesis, and we recently published “The New Neutral Revisited” detailing and updating our views. Scott Mather, Chief Investment Officer U.S. Core Strategies, discusses how the outlook for the U.S. differs, to a degree, from other large economies.
Commentary
The Affordable Care Act and Low Interest Rates: A One-Two Punch for Health Insurance Portfolios
Two common themes emerged from a recent PIMCO survey of U.S. health insurers: Underwriting performance will be a larger factor in asset allocation, and there will be more emphasis on liquidity and income. For now, health insurers generally expect increased premium volumes and shifts in insured profiles as a result of the Affordable Care Act. Re-examining investment policies and tiering liquid assets can help investment portfolios maintain flexibility while potentially contributing more to the bottom line.
Commentary
Forward Guidance Is Back at the Bank of England
The central bank seeks to reassure markets about its policy intentions and also stabilise gilt yields ahead of an anticipated rate hike in the U.S.
Commentary
Security Selection and Liquidity Management Are Key in the Steadily Growing Credit Market
Over the past several years, two trends have reshaped the market for U.S. investment grade (IG) corporate bonds: a significant increase in the size of the market (both in number of issuers and issues and in aggregate debt outstanding) and a contraction in dealer balance sheets.
Commentary
Align the Design: Considering and Evaluating Target-Date Glide Paths
Few responsibilities are as important to defined contribution (DC) plan sponsors as selecting a default glide path that best maximizes a participant’s odds of retiring on time and with sufficient lifetime income. The goal, put simply, is to maximize asset returns while minimizing volatility relative to the retirement liability – precisely what Objective-Aligned Glide Paths aim to achieve.
Commentary
Monetary Policy at Warp Speed
An imaginative twist on theoretical physics forms the premise of the science fiction series “Star Trek”: An engine called a warp drive enabled the Starship Enterprise to travel faster than the speed of light, going beyond known space to uncharted, exciting new worlds. The confounding detail was managing the sheer power inherent in the warp drive, including its potential to behave in unexpected ways.
Commentary
The Credit Analysis Process: From In-Depth Company Research to Selecting the Right Instrument
Credit can offer a broad range of investment opportunities. But in today’s low yield environment, an active and integrated investment approach is critical.
Commentary
Global Divergence, the Federal Reserve and the Impact on U.S. Insurers
Insurance publication SNL Financial recently sat down with members of PIMCO’s Financial Institutions Group to discuss PIMCO’s latest views on global divergence, the Federal Reserve and the impact on U.S. insurers in their investment portfolio positioning.
Commentary
Pregnant Pause
After re-engaging policy support in February following an 18-month hiatus, the Reserve Bank of Australia (RBA) wrong-footed many in the market by keeping policy on hold in the two subsequent board meetings. So was February's decision a "one-and-done" policy event or the start of a more aggressive easing cycle?
Commentary
Key Themes for Navigating Credit Markets in Alternatives Strategies
Against a backdrop of low volatility and tight spreads, 2014 turned out to be a challenging year for many alternative investors as they watched their trades become crowded, and reverse quickly when expected returns were not realized. One such example was the positioning among investors in advance of the European Central Bank’s (ECB) Asset Quality Review announcement; many had increased their exposure in anticipation of a tightening of European bank-related securities.
Commentary
The Unexpected Ripple Effect of New Bank Capital Requirements
In the aftermath of the 2008 financial crisis, lawmakers and regulators promulgated sweeping regulations that sought to reduce systemic risk and promote market stability.
Commentary
Expect Further Divergence in Emerging Market Economies
Each quarter, PIMCO investment professionals from around the world gather in Newport Beach to discuss the firm’s outlook for the global economy and financial markets. In the following interview, portfolio managers Michael Gomez and Lupin Rahman discuss PIMCO’s cyclical outlook for the emerging markets (EM).
Commentary
An Open Letter to the Eurozone
As it has once again become fashionable to send an open letter to foreign dignitaries, now is certainly a propitious moment to help focus attention upon dissolving a perplexing financial impediment. For while limiting nuclear proliferation and reducing armed conflict are headline grabbers, the more mundane topic of cleansing the channels of global finance is in fact a public policy good that can create a positive social impact in real time. As such, I now respectfully offer my thoughts on ways to enhance the effectiveness of the current policy path.
Commentary
Key Themes for Navigating Credit Markets in Alternatives Strategies
??We believe the current investment environment provides extensive opportunities for alternative investors.
Commentary
Supply-Side Yellenomics Is (Slowly) Losing Its Grip on Markets
Should investors worry about the possibility that the Federal Reserve might raise interest rates this year? How about the negative economic consequences of the rally in the U.S. dollar? “Hawkish” Fed mistakes?
Commentary
U.S. and Canada: Continued Recovery With Some Potential for Headwinds
?Each quarter, PIMCO investment professionals from around the world gather in Newport Beach to discuss the firm’s outlook for the global economy and financial markets. In the following interview, portfolio managers Ed Devlin and Mike Cudzil discuss PIMCO’s cyclical outlook for Canada and the U.S..
Commentary
Equity Cyclical Outlook: Between Fed lift-off and living in the New Neutral
Virginie Maisonneuve, PIMCO’s CIO Global Equities, and equity macroeconomic analyst Mark Richards provide an update on PIMCO’s views on equity markets.
Commentary
Will the UK Election Derail the Recovery?
While the economic outlook for the UK is not without risk, most notably if there is an extended period of political paralysis, the UK recovery is much better shape than during the last general election in 2010 and should stay its course. We believe the benign inflationary backdrop will aid economic growth that saw GDP gains of 0.6% for the final quarter of 2014. In an environment of subdued underlying inflationary pressures and sterling appreciating relative to its major trading partners, the Bank of England can afford to wait to tighten monetary policy.
Commentary
Duration: To Hedge or Not to Hedge?
Because duration tends to be an important component of the return profile in a bond portfolio, adjusting exposure rather than hedging it away may make sense for many investors. Low duration strategies may provide a level of interest-rate duration that provides a better trade-off between a full market beta (with interest-rate duration) and a fully duration-hedged beta.
Commentary
Corporate Bonds Offer Opportunities in the Slowing Economy
Lack of corporate leveraging and investment among Australian companies may provide a macro headwind to economic growth and, hence, future prospects for equity investors, but from a creditor's perspective, this should keep credit metrics relatively healthy.
PIMCO's bottom-up analysis has helped identify several opportunities, even within the resources sector, where strong balance sheets, competitive industry positions and sound management build a compelling case for credit investors despite the challenging period ahead.
Commentary
Fit & Focused
Many powerful forces are driving markets and asset prices; chief among them are global monetary policy, technicals and fundamentals.
We use rigorous top-down and bottom-up analysis to identify the best sectors and companies around the world.
We see opportunities in the U.S. (cyclical consumer and housing sectors), Europe (equities, bank capital securities, high yield bonds and corporate hybrids), China (property, technology and Macau) and Japan (cyclical industries, exporters and financials).
Commentary
In a Challenging Environment, Policy Easing Sweeps Through Asia
The key change to our cyclical outlook for Asia: We have further downgraded our growth forecast for China to the low-6% range as real borrowing rates remain elevated. In Japan, we expect growth to recover from last year's technical recession, following the delay in the next value-added tax (VAT) hike and the increase in the Bank of Japan's easing program.
Commentary
Can ECB Policy Heal Europe’s Ills?
In this interview, Managing Directors Mike Amey, Andrew Bosomworth and Lorenzo Pagani discuss the conclusions from PIMCO’s quarterly Cyclical Forum in March 2015 and how they influence our European investment strategy. They also delve into the impact of the European Central Bank’s (ECB) balance sheet expansion on growth and inflation and reflect on Europe’s improving economic health.
Commentary
Proposed Changes to U.S. Bankruptcy Code Could Create Opportunities in Distressed Credit
The American Bankruptcy Institute's (ABI) proposals aim to balance the objectives of effective reorganization of debtors and the maximization of asset values for all creditors and stakeholders. The proposals seem to mark an effort to modify the positions of different creditor classes in bankruptcy, a move that could disadvantage both senior and junior creditors depending on the particular case.
Commentary
Riding a Wave of Accommodation
PIMCO’s quarterly Cyclical Forum was held earlier this month to evaluate and assess the state of the global economy, to reach consensus on the near-term macroeconomic outlook, and to explore the tail risks to that outlook.
Commentary
Equities: Enhancing the Core/Satellite Framework
?In a lower-returning environment, investors may need to look beyond traditional active or passive approaches in order to capture equity alpha. The “building blocks” of equity alpha include high active share stock selection, smart beta-based strategies and portable alpha approaches. These complementary sources of alpha can be implemented in an enhanced core/satellite framework to allow investors to pursue the returns needed to meet their objectives.
Commentary
Positioning U.S. Community Bank Investment Portfolios for 2015
When market uncertainty is elevated and bank profitability is an ongoing concern, taking an extreme view toward investing cash or harvesting liquidity is not optimal. Currently, we do not see as much value in interest rate or duration risk for bank portfolios as yields imply a moderate path for future policy rates. We believe there are opportunities for banks to earn income without taking excess interest rate risk or limiting flexibility against the need to fund future opportunities.
Commentary
With the Bank of Canada, Is the Canadian Economy in Good Hands?
A disorderly decline in energy prices could spill over into consumer and business sentiment, which would worsen any drop in Canada's economic output. More rate cuts this year are likely a part of the Bank of Canada's base case scenario. Investors may be able to improve their returns by buying bonds with high-quality credit spreads, including Canadian bank senior debt and Ontario bonds.
Commentary
While the World Is Not Flat, Distributions May Be
?Investors have long relied on the assumption that asset returns are normally distributed with correlations that are slow to change. Based on our analysis, however, we now have flat distributions and correlations that are much less stable; a fat-tailed event to either the left or the right is as likely to occur as a non-event. Active management that recognizes and adapts to these changes will be essential to seeking strong returns in the future.
Commentary
Why the Bond Market Is Yielding Negative and What Negative Yields Mean for You
Negative yields on bonds are no longer unicorns. In Switzerland, Germany, Denmark and several other European countries, government bonds are trading at negative nominal yields. There are four potential reasons that can explain the negative yield conundrum and can also illustrate the trade-offs between different investment strategies.
Commentary
??Why Does the Internet of Things Matter?
The opportunity to gather, process and use data more effectively is potentially worth several trillion dollars across multiple industries over the next decade.
We expect most industries to adopt some form of this technology, with network effects and competitive dynamics leading to almost ubiquitous adoption beyond the current decade.
Commentary
Repression, Compression, Expression
Cumulative financial repression has led to compressed and recently highly correlated yields in most developed countries, while markets have been volatile as investors react and adjust to the new environment. Recent short-term spikes in volatility belie likely damped volatility at these low rates over time, suggesting a potentially attractive opportunity to sell longer-term volatility at current premiums.
Commentary
What Does the Current Low Interest Rate Environment Mean for Agency MBS?
After the agency MBS market in 2014 was dominated by low volatility, limited prepayment risk and strong performance, the strong rally in U.S. Treasuries in January resulted in just the opposite. With the Fed ending net purchases of MBS in October 2014, it seems unlikely for the private investment community to take the Fed’s place in the MBS market at this level of interest rates and spreads. PIMCO expects the environment for MBS in 2015 to be quite the opposite of 2014, resulting in higher volatility, cheaper valuations and more attractive excess return opportunities for the active manager.
Commentary
DC Managed Accounts: Shining a Spotlight on Investment Advice
?Nearly one in three defined contribution (DC) plans offers managed account and automated advice services that attempt to enhance investment outcomes with personalized advice. As the Government Accountability Office has reported, however, plan sponsors often have had limited or insufficient information to evaluate and monitor automated advice engines, despite having fiduciary responsibility over advice provided to participants.
Commentary
Scott Mather Discusses PIMCO’s Total Return Strategy
Bonds have continued to rally so far this year, even as the Federal Reserve contemplates raising interest rates. In the following interview, Scott Mather, CIO U.S. Core Strategies, discusses recent developments in the bond markets, the outlook for the year ahead and the investment implications for PIMCO’s Total Return Strategy. Mather co-manages the strategy with Mark Kiesel, CIO Global Credit, and Mihir Worah, CIO Real Return and Asset Allocation.
Commentary
The International Ramifications of ECB QE
By engaging in quantitative easing, the European Central Bank is pursuing its inflation mandate with a vengeance. Overall, we think the combination of quantitative easing, investment and lower oil prices will help eurozone growth reach approximately 1.3% in 2015. Global central bank balance sheets continue to expand: Although the Federal Reserve stopped purchasing assets in 2014, the Bank of Japan and now the ECB have stepped up buying bonds where the Fed left off.
Commentary
All the Children Are Above Average
Many investment strategies are centered upon discovering a long-term (average) valuation framework to help in asset allocation and security selection. The term surface of various risk parameters often moves in such a manner that the discounted forward value will point toward this long-term average. If a secular shift has taken place - if all the children are above average, so to speak - then maybe the “average” has changed.
Commentary
Commercial Mortgage-Backed Securities: Approaching the Later Innings of a Recovery
With the U.S. recovery as a supportive backdrop, PIMCO expects commercial real estate prices to rise 4%-6% in 2015. Commercial mortgage-backed securities issuance has increased for five years, and projections for 2015 are for growth of 20%-30%, driven largely by an increase in maturing loans on the supply side and the continued search for yield on the demand side. The growth in issuance does not come without concern: CMBS underwriting standards will likely continue to slip.
Commentary
PIMCO Introduces the PIMCO Multi-Strategy Alternative Strategy
by PIMCO, 2/3/15
In a New Neutral environment that anticipates muted returns and heightened volatility, many investors have looked to liquid alternatives in an effort to boost returns and lower overall portfolio risks. Our approach seeks to efficiently combine a range of complementary liquid alternative strategies, offering the potential for diversification and higher return per unit of risk than a single strategy could achieve on its own. This strategy can play a central role in liquid alternatives allocations or be used as a stand-alone complement to traditional stock and bond allocations.
Commentary
PIMCO Extends Its Dividend Suite With Two New Regional Strategies
As is the case with our other dividend strategies, we are unconstrained by benchmarks and focused on generating yield and capital appreciation by finding attractively valued companies that pay appealing dividends today and have an ability and willingness to grow dividends over time.
Commentary
Opportunities and Risks for Investors After the Oil Price Slump?
What we are seeing now is that oil prices, when OPEC refuses to balance the market, test the marginal cost of production, and costs fall. Some of the costs of the largest components of oil projects – high-spec sixth-generation rigs, pressure pumping, seismic, completion – have fallen between 20% and 45% in the space of months as overcapacity became evident and capital expenditure was revised downward.
Commentary
Commodity Outlook 2015: Watching the Supply Response Across Markets?
Today?s low oil prices should allow for supply and demand to come back into alignment by year-end, led by a decline in the U.S. output growth rate and a modest increase in global demand. We expect continued oversupply to weigh on natural gas prices this year, but some semblance of balance may return to this market in 2016. Grain prices may experience pressure in 2015 as low oil prices pass through to corn prices, which may cause producers to switch to higher-priced crops. With production growth likely having peaked, we expect metals prices to stabilize this year.
Commentary
Municipal Market Update: What's Ahead in 2015
Municipal bonds ended 2014 as one of the best-performing asset classes - buoyed by investors’ search for yield in a low interest-rate environment. For 2015, we are positioned cautiously for greater volatility in the fixed income markets. We currently prefer revenue-backed bonds over most general obligation (GO) debt, as these sectors typically benefit from dedicated revenue streams and do not have the pension challenges that many state and local governments face.
Commentary
Time to Get Off the Merry-Go-Round ??
In 2014, many investors de-risked their portfolios by moving into shorter-duration passive approaches but the potential for capital preservation from these strategies may face challenges. Passive benchmarks and strategies with pre-specified, structural interest rate exposure may have little to no flexibility around their positioning and may push investors into the heart of the proverbial storm. Active strategies not constrained by benchmark limitations may be optimal for investors as they can seek to manage exposure to interest rates.
Commentary
Global Equities 2015: Fasten Your Seat Belt for a Multi-Speed World
We sat down recently with Virginie Maisonneuve, PIMCO?s CIO Global Equities, and equity macroeconomic analyst Mark Richards to discuss PIMCO?s global equity outlook for the coming year.
Commentary
U.S. Lodging: The Recovery Checks In for an Extended Stay
Relatively high occupancy levels should drive room rate growth in the hotel sector over the next several years, despite some supply entering the market. We see opportunities in certain segments, such as premium hotels and C-corporations, due to high barriers to entry and pricing power.
Commentary
ECB Review: Blowing on the Embers of a Reflationary Fire
?Not to pursue our mandate would be illegal? is how Mario Draghi ended his last press conference of 2014. Mr. Draghi?s first press conference of 2015 began with the announcement of a quantitative easing (QE) programme that pursues the European Central Bank?s (ECB) inflation mandate with a vengeance. And rightly so, for the disinflationary trends in the eurozone had become all the more precarious as economic output and the price of oil continued to fall.
Commentary
Wait and See at the Bank of England
UK growth looks to be sustainable, with encouraging domestic demand, though we need to see business investment continue to pick up. Although inflation hovering below the 1% lower tolerance band of the Bank of England (BOE) remains a concern, we think it actually gives the central bank welcome breathing room during a period of uncertainty for the global economy. Looking ahead, we see compelling investment value in the intermediate part of the UK yield curve, namely five- to 10-year bonds, as the BOE plays the waiting game.
Commentary
What We Are Hearing From Asia-Pacific Investors: Five Themes for 2015
Amid lower forward-looking returns, investors are focusing on multi-asset solutions, enhanced beta, income and alternatives in Asia-Pacific. PIMCO is prepared to address these themes, drawing upon our time-tested investment process that combines high-level macroeconomic views with thorough on-the-ground research.
Commentary
The Swiss National Bank?s Unpleasant Experience of Sleeping Next to an Elephant
On 15 January 2015, the Governing Board of the Swiss National Bank (SNB) unexpectedly exited its minimum exchange rate regime, which it had adopted back in September 2011 when it was fighting sharp appreciation of the Swiss franc in the midst of the eurozone sovereign debt crisis.
Commentary
Seizing Credit Opportunities When Oil Prices Are Sliding
?We believe we are moving into an extended period of lower oil prices, and we are actively managing our clients? energy exposure with an eye toward benefiting from recent events. Differentiation between the winners and losers across countries, sectors and individual companies is essential. We currently favor subsectors and companies with strong asset quality, high barriers to entry, solid production profiles and strong balance sheets and liquidity profiles.
Commentary
The Long Growth Drag From Financial Market Tinkering?
Central bankers and regulators have greatly underestimated the negative impact their actions may have on the economic ?multiplier.? Over the next two to three years this miscalculation may settle into a permanent drag on global growth. Forget fears of bloated central bank balance sheets and their potentially inflationary effects ? rather than generating credit in the consumer sector, much of that ?liquidity? is being used to meet new capital requirements.
Commentary
Recovery Gaining Momentum?
U.S. growth will remain robust over the cyclical horizon due to increasing consumption driven by the narrowing unemployment gap and increase in disposable incomes. The Canadian recovery should continue, though divergent forces ? including the U.S. recovery and oil price declines ? could have significant implications for the economy. Growth will be muted across Latin America, with some economies benefitting from U.S. growth, and others dragged down by the slowdown in the eurozone and China.
Commentary
Rising Insurance Premiums: A New Impetus for Voluntary Funding of Corporate Defined Benefit Plans
?The Pension Benefit Guaranty Corporation will hike variable-rate premiums on unfunded liabilities in corporate defined benefit plans in 2015 and 2016. The increases along with muted return potential on stocks and bonds and aging plan demographics could make borrowing to reduce or eliminate funding shortfalls less expensive than paying PBGC variable-rate premiums. For efficient execution, we believe it is important to consider appropriate investment strategies before any funding decisions are made.
Commentary
The Second Wind of Abenomics?
Mr. Abe now has up to four more years in power. While investors are likely to be patient in the near term, unless Abenomics gains a second wind the way a tired athlete finds the will to pick up the pace and finish strong there is a risk that this post-election market euphoria could be short-lived. The time for him to act is now.
Commentary
A Rising Tide Lifts Most Boats
PIMCO expects global growth to accelerate in 2015, reaching about +2.75% year-over-year, with the majority of this improvement due to the (predominantly supply-driven) decline in oil prices. However, there will be large differences in growth dynamics among countries. While fiscal and monetary policies in most developed countries will stimulate growth in 2015, the U.S. Federal Reserve will attempt to break from the pack.
Commentary
Testing the Limits of Monetary Policy Without Fiscal Union
Over the next 12 months, we expect eurozone growth to accelerate from the current annualised run rate of 0.5% to a still-very-weak pace of approximately 1%, while the ultra-low inflation tells us there is a demand problem. With the ECB set to expand its balance sheet over the cyclical horizon, the biggest risk to growth is if the ECB buys large quantities of government bonds but the governments do nothing. We expect to remain overweight European peripherals and overweight European corporate credit, with the focus on financials.
Commentary
Outlook for the Global Credit Markets in 2015
The combination of fundamentals, technicals, valuations and global central bank policies drives our overall constructive outlook for global credit in 2015. Economic growth dynamics, including an improving outlook in the U.S., along with likely changes in global central bank policies, continued energy price volatility and the potential for more shareholder-friendly actions by companies inform our credit views and strategies.
Commentary
Strategy Spotlight: An Update on PIMCO'S Fundamental Index-Based Product Suite
The Fundamental IndexPLUS AR strategies combine the best of what passive indexing and active management aim to deliver: broadly representative, transparent equity exposure plus the potential for meaningful equity market outperformance.
Commentary
Follow the ECB Compass
As the European Central Bank continues to expand its balance sheet to counter low growth and ?low inflation, we believe European duration should remain relatively well-anchored and European assets should be well supported. Looking ahead, in a world of low yielding European core rates, we believe credit will continue to attract investors. We continue to see spread compression opportunities in peripheral sovereign, fundamentally improving banks and high yield.
Commentary
Designing Balanced DC Menus: Considering Equity Investments
Defined contribution investment lineups typically provide numerous equity choices but still may lack adequate diversification and return potential. Participants may benefit by accessing high-growth markets such as emerging markets and tapping in to dividend-paying stocks. Retirement outcomes could improve further by including portfolios structured using fundamental measures rather than market capitalization.
Commentary
The Big Squeeze Begins
Current European Central Bank policies, along with the regulatory environment, are constricting the two primary investment vehicles available to store cash. As many money market funds have maxed out the risk they can take and some regional European banks have started to charge the equivalent of negative rates on deposits, large cash investors are left to ponder how to avoid the potential loss of capital. We believe PIMCO's approach to balancing three key cash management trade-offs may provide an attractive solution for investors.
Commentary
Getting More From Your Equity and Bond Benchmarks
Benchmarks have long served as a starting point, or anchor, for investors, representing the neutral point for an investment decision. They serve as the basic ingredients that combine to form an investors asset allocation and result in a desired risk/return profile.
Commentary
The Great Escape??
Since the financial crisis, the Fed has engaged both conventional and unconventional tools in a colossal effort to smooth the deleveraging process, help put Americans back to work and boost wage growth. The Fed has achieved two out of three "escapes": 1) Escape from a liquidity trap: Get banks to lend. 2) Escape from quantitative easing: Stop the bond buying program. 3) Escape from the zero bound: Hike the policy rate above zero. Over the longer term, portfolios should be positioned for low policy rates not only in the U.S., but also in Europe and Japan.
Commentary
Is the Oil Price Slump an Early Holiday Gift for Some Consumers?
With 60% of global GDP driven by consumers, the impact that sustained lower oil prices will have on the global economy is an important factor for investors to take into account. The benefits of lower oil prices will not be evenly distributed and it is important to think about countries that stand to benefit more because of higher consumption and/or less economic dependence on oil exports.
Commentary
OPEC Meeting Post-Mortem: All Eyes on U.S. Shale
After averaging nearly $110 per barrel during the first half of 2014 and peaking at over $115 per barrel in June, Brent crude oil has fallen by over $40 in just a few short months.
Commentary
Unintended Consequences of Staying Early Termination Rights
The topic of too big to fail has been an intense area of focus for policymakers and market participants, and for good reason: Everyone has a vested interest in avoiding a repeat of the 2008 financial crisis and its corresponding aftershocks.
Commentary
The ECBs Shifting Regimes
The European Central Bank (ECB) is likely to commence a broad-based asset purchase programme, i.e., quantitative easing (QE), in the first quarter of 2015. As it stands, the eurozone is stuck in a liquidity trap, the risk of deflation is rising and inflation expectations are deviating from their long-term anchor. With the private sector deleveraging and the policy rate near zero, additional easing will require expanded asset purchases.
Commentary
The Tortoise and the ECB
It is curious that the ECB continues to slumber while the eurozones trading partners move steadily ahead. While not a certainty, it seems highly unlikely that the ECB will indefinitely allow its main trading partners to competitively devalue versus the euro. And since there is no reason to reinvent the wheel, Europes policymakers will likely unveil a familiar-looking and expansive QE policy designed to accelerate asset velocity and, in turn, reflate their equity market.
Commentary
Time to Look at Long Credit?
?Tactical decisions regarding the scaling of an LDI allocation cannot be based solely on Treasury market dynamics. Given recent underperformance of long credit relative to intermediate credit, LDI investors should consider increasing long credit exposure. A structured approach that combines rigorous top-down macroeconomic-analysis to take views on duration and credit sectors with equally thorough bottom-up credit research to identify companies where fundamentals are improving may deliver alpha that can help clients reduce their funding mismatch over time.
Commentary
Still A Winning Hand
The U.S. is finally enjoying a self-sustaining economic recovery, but slow global growth remains a concern and financial markets are bouncing up and down by the day. So what exactly does this U.S. recovery mean for investors?
Commentary
Investment Implications for UK DC Schemes in Light of Tax and Regulatory Changes
With greater flexibility and choices available to DC savers in the latter stages of their career, we believe DC schemes need to reconsider their traditional pre-retirement approach to providing low-risk, income-orientated and pre-retirement investment portfolios. The primary immediate challenge for UK DC schemes is navigating the need for capital stability versus a portfolio that can generate a sustainable income stream for DC savers in retirement.
Commentary
Hard to Hit Two Targets at Once: The ECB ABS Asset Purchase Programme
We believe that reviving the asset-backed securities (ABS) market is a better near-term goal, and the primary target of the European Central Banks (ECB) buying programme should be the new issuance market. Sizeable purchases by the ECB in the European ABS market carry the possible risks of crowding out established investors and suppressing interest in this asset class. By not crowding out existing investors while making the asset class more attractive to issuers and investors alike, the ECB has an opportunity to reach its ultimate goal to spur lending.
Commentary
Got Loans?
?We believe select investors looking to reposition portfolios may benefit from a move to senior secured floating rate loans.
CLOs have been an important source of demand in the market, and even with more strict risk retention rules just announced under Dodd Frank, we think demand will remain strong.
While the Fed has criticized some banks for not following their leveraged lending guidelines, Fed members themselves, in our view, do not appear concerned about loans having a major impact on financial stability.
Commentary
Opportunities Amid Divergence
As in developed markets, the trends of increasing growth and policy dispersion will be borne out in emerging markets over the next 12 months. Brazil has some of the highest interest rates in the world, which presents an opportunity for investors, and we expect the next four years will be marked by a better mix of fiscal and monetary policy. Because our outlook for China has moderated somewhat, we are focusing attention on trade and financial linkages and how the ripple effects of a slower China might unfold.
Commentary
Is the UK Getting Back to Business as Usual??
In light of the generally buoyant economy, we may start to see more normal conditions returning to the UK labour market and, importantly, upward movement in wage growth over the cyclical horizon. In turn, these developments are critical for the conduct and timing of monetary policy and the behaviour of the Bank of England's (BOE) Monetary Policy Committee. We believe investors may want to treat the BOE's interest rate cycle with caution in shorter-maturity bonds, while valuations offer more protection in intermediate bonds given PIMCO's New Neutral thesis of secularly low real interest rates.
Commentary
Setting Global Standards for Central Clearinghouses
While a possible central counterparty (CCP) failure is a very remote event, there is no one single solution that alone will prevent it. However, PIMCO believes that if several conditions are met, including 1) a CCP is capitalized correctly and sufficiently with its own skin in the game, 2) segregation of client assets are consistent across cleared derivatives, 3) CCPs have a way to access cash easily to manage liquidity and 4) stress tests are consistently performed and reviewed, a CCP will be much more likely to recover than to be forced into a resolution process.
Commentary
Practical Policy Prescriptions to Help Offset Geopolitical Uncertainties
We believe Europe should relax fiscal budget constraints to allow for fiscal stimulus to offset any economic drag, while maintaining extremely accommodative monetary policy. The U.S. and its relatively newfound energy renaissance can also play an important role in supporting Europe and the global economy by signaling its intention to compete for energy market share.
Commentary
Can Anything Go Wrong for the Markets???
?Risk management in proper portfolio construction consists of a combination of dynamic risk balancing, diversified beta sources, explicit options-based tail hedging and a minimum amount of liquidity. Faced with a long and expanding list of things that could go wrong, uncertainties about the likelihood of each shock and the lack of dependable precursory indicators, it seems that a structurally sound portfolio construction methodology that uses all these tools is essential.
Commentary
Our DNA
Our investment process, which lies at the heart of the value we offer clients, is ingrained it is stamped into our DNA. Our culture of rigorous and open debate will continue to animate quarterly forums of our global investment and executive leadership, as well as the daily meetings of the Investment Committee. We remain a team-oriented organization. Indeed, it could hardly be otherwise in a firm which over many years has grown to nearly 2,500 investment professionals and staff stationed in 13 global offices, with nearly $2 trillion in assets and a full suite of strategies, including co
Commentary
PIMCO Cyclical Outlook for the Americas: Recovery Remains Intact, Yet Uneven
U.S. growth can potentially exceed expectations over the cyclical horizon, in part bolstered by a healing consumer and a very accommodative Federal Reserve. While real growth in Canada has been modest in recent years, it increased to 3.1% in the second quarter and we expect that positive momentum to continue this year. In Latin America, we expect growth will pick up for the region as a whole with outperformance by smaller economies like Colombia and Panama.
Commentary
Slower Growth in China and Japan Pressures the Region
Our forecast for the global economy is below consensus mainly because of our views for regions outside of the U.S., including Asia, the emerging markets and Europe, although higher growth in the U.S. should offset some of the slowdown we see coming from China. Japan made a kick start under so-called Abenomics with massive monetary and fiscal reflation policies, but the recent data suggest to us that the effectiveness of those cyclical policies are already challenged by secular and structural headwinds.
Commentary
Europe’s Commercial Real Estate Deleveraging: ‘Not Too Fast, Not Too Slow’?
As European bank deleveraging accelerates, we expect that commercial real estate (CRE) will continue to constitute a significant proportion of bank assets to be sold, albeit with a shifting geographical mix. We believe CRE opportunities remain in the form of single assets and complex structured transactions in particular; but a disciplined approach will be key given competition in specific types of assets and in certain jurisdictions. This will require flexible capital, local investment expertise and hands-on asset management, in addition to strategic sourcing capabilities.
Commentary
Equities: Finding the Path to Value?
Going forward, earnings growth and stock selection - more than multiple expansion and beta - will likely play a bigger role in driving positive returns. Our research has uncovered numerous examples of stocks trading below our estimate of intrinsic value - notably in Europe and various special situations. Investors with the capacity for deep, fundamental research and a long-term unconstrained equity strategy may be positioned to capitalize on these opportunities.
Commentary
Emphasize Barriers to Entry?
We see many bottom-up investment opportunities in the global credit markets, particularly in industries with high barriers to entry. We view healthcare, lodging, Asian gaming, master limited partnerships/pipelines, energy, wireless telecom, cell towers, cable, satellite, media and U.S. banks as attractive industries. Companies unique patents, licenses, brands, content and intellectual property, among other advantages, can help support investment returns in both bull and bear markets.
Commentary
Distressed Corporate Credit: A Tale of Two Markets?
Middle market distressed credit may be an attractive source of higher returns in an overall low yield environment for investors able to access these opportunities. However, the higher return potential comes with greater risks. Imbalances in middle markets are building. ?Investors looking toward distressed credit markets should focus on companies that will likely be able to withstand periods of economic inertia, to undertake careful valuation practices and to strictly adhere to the absolute priority rule (in which senior creditors are paid in full before junior creditors).
Commentary
Escape Fandango?
When I entered the Fed-watching business over three decades ago, a clichd phrase of advice from graybeards was: Watch what they do, not what they say. Thinking back, there was not actually much Fed rhetoric to either watch or hear.
Commentary
Will Russia Derail the Eurozone Recovery?
Geopolitical tensions from Ukraine and the evolving trade war with Russia are threatening what is already a weak recovery in Europe, and could shave approximately 0.3%0.4% off eurozone growth. Should the situation escalate, we could expect an even greater drag with potential to push the eurozone back into recession. Looking ahead, we see attractive opportunities in peripheral bonds and favour an underweight currency position in the euro.
Commentary
Congress Will Go Out With a Whimper, But the Next Could Come In With a Roar
A government shutdown is highly unlikely this year, and most need-to-pass bills will likely pass either before the election or during the "lame duck" session of Congress. Should Republicans take the Senate, we should expect heightened policy uncertainty around issues such as the debt ceiling increase in 2015.
Commentary
For Wonks Only???
A credit-based financial economy (as opposed to pure cash) depends on an ever-expanding outstanding level of credit for its survival. Without additional credit, interest on previously issued liabilities cannot be paid absent the sale of existing assets, which in turn would lead to a vicious cycle of debt deflation, recession and ultimately depression.
Commentary
Late, Not Lost: The Economic Drag From the Millennial Generation
We believe concerns of a student debt "bubble" and perpetual financial weakness among Millennials are largely overstated. Understanding Millennials' financial trajectory is critical to our secular (3-5 year) outlook for home prices and the broader economy. We expect Millennials' financial position to improve, and pent-up demand could result in longer-term strength in housing and housing-related assets.
Commentary
Share and Share Alike??
Labor compensation as a share of national income fell sharply in 20092010 and has remained depressed: The share of national income at the end of 2013 was the smallest slice paid to labor in at least 60 years! During the last three U.S. business cycles, the rise in labors share that commenced during the expansion phase of the business cycle was not accompanied by a material rise in PCE inflation.
Commentary
Australia’s Terms of Trade: Implications For Credit Investors
Australia is contending with a multi-year decline in the terms of trade and a rebalancing toward the non-mining sectors of the economy. For companies, the macroeconomic consequences of a downswing in the terms of trade provide both challenges and benefits. For investors, it is important to find companies that have a clear, demonstrated understanding of the macro environment and can navigate the headwinds through operational efficiencies, cost control, market positioning and balance sheet management.
Commentary
Principled Populism?
In the years before retiring from PIMCO in 2010, I often interviewed candidates for professional positions here, usually at the end of the process, after they had been thoroughly vetted through several rounds of interviews. My task was not so much to test candidates qualifications as to take their measure and for them to take mine!
Commentary
Goodnight Vietnam?
It was a matter of happenstance I suppose certainly not serendipity. Our meeting may have been an inevitable coming together, but it was certainly not initially welcomed by me. Happenstance is the better word. Fateful happenstance.
Commentary
Strengthening the Euros Governance Structure?
?Todays relative tranquillity in eurozone financial markets owes largely to the ECBs willingness to hold the single currency together. However, history suggests the eurozones citizens ultimately will have to choose between returning to a regime of flexible exchange rates or retaining the single currency and deepening political and fiscal integration.
Commentary
Money Market Reform: Reflections on This Critical Inflection Point for Cash Liquidity Investing
Under the SECs new regulations, institutional prime and institutional municipal money market funds will transition to a floating net asset value. All money market funds (except government-focused funds) are required to impose liquidity fees and may use redemption gates if liquid assets fall below certain levels. Investors, both institutions and individuals, should view this industry inflection point as an opportunity to revisit their approach to cash investing. Actively managed short duration strategies are a compelling solution.
Commentary
Is Timing Everything? Practical Implementation of Tail Risk Hedging??
Just in time hedging is nearly impossible: By the time an investor decides to hedge, the market may already price in the significant risk of a tail event. Instead, hedges could be included as a permanent part of an asset allocation: what we might call just in case hedging. An optimal strategy may involve averaging into a hedging allocation. In addition, using a broader set of hedge instruments may help lower the costs. We believe that tail risk hedges have a place in any portfolio that has a substantial allocation to risk assets. ?
Commentary
The New Neutral: Investment Implications for Insurance Companies
Low rates are unhelpful to an industry with legacy long-term liabilities containing rigid embedded credited rates; they exacerbate asset-liability mismatches and pressure earnings margins. Insurers may want to recalibrate their expectations of future interest rates, as well as broad bond and equity market returns. In The New Neutral, with beta from stocks and bonds likely to be relatively low, insurers should look to enhance buy-and-hold return potential via active management.
Commentary
Are Prices Too High in U.S. Commercial Real Estate??
The recovery in commercial real estate (CRE) has been driven more by low rates than improvements in fundamentals. However, fundamentals are improving and capitalization rates should remain low amid low New Neutral policy rates. We expect capital flows in both debt and equity to CRE to continue to increase, and we see opportunities for investors resulting from capital flows, demographics, loan maturities and regulatory reforms. ?
Commentary
Choosing Winners in Asian Credit: Key Trends and Themes
Key trends include Asian credit supply, which is on track for another record year in 2014, and China's priority to promote cleaner and more efficient energy. Our bottom-up research and careful risk assessments informed by macroeconomic perspectives have us favoring select investments in several sectors of Asian credit markets, including state-owned enterprises in China and Korea, investment grade new issues and Basel III Tier 2 bank capital bonds. ?
Commentary
One Big Idea??
?Investing and business success can often depend on one BIG idea and its timing. The peaking of short-term interest rates at 20% in the early 1980s and the bursting of the DotCom and NASDAQ bubble 20 years later were excellent examples of big ideas that made or broke investment portfolios.
Commentary
Could Events in Iraq Shock Your Portfolio?
We expect a relatively small impact on oil prices for the rest of the year once the dust settles and sectarian lines are drawn. These events call into question Iraqs ability to keep increasing oil production, which will likely support elevated prices in the years to come. We believe owning oil as a portfolio defense presents an interesting opportunity. ?
Commentary
Designing Balanced DC Menus: Considering Inflation-Hedging Strategies????
Inflation-hedging strategies are fundamental to DC investment lineups and participants? need to build and preserve purchasing power in retirement. Plan sponsors should evaluate these assets separately and in combination before adding them to core lineups and target-date strategies. Selected assets or blends should be designed to deliver the primary benefits of inflation responsiveness, diversification relative to stocks, volatility reduction and downside risk mitigation.
Commentary
Getting in Gear for The New Neutral – What Does It Mean for Investors?
Smart beta is increasingly important when returns are likely to fall short of what most investors need and expect. Active managers can use multiple tools to help generate higher returns. With outcome-oriented strategies, investors can align their portfolios toward meeting specific risk and return objectives. Investors with more aggressive income or return needs may benefit from bespoke, multi-asset solutions. ?
Commentary
Euro-Sterling Credit: Yield and Spread Still Appeal
Framed by ongoing renormalisation in Europe and stronger UK growth, euro-sterling investment grade credit markets are in a favourable part of their respective cycles as corporates continue to deleverage, default rates are expected to remain low ahead and market liquidity has improved across Europe. We believe the sterling credit market provides a more balanced credit market and offers investors the opportunity for better total carry versus euro and global investment grade credit markets.
Commentary
Unconstrained Bond Investing in The New Neutral
At our recently concluded Secular Forum, PIMCO investment professionals from around the globe gathered in Newport Beach to discuss and debate the secular outlook for major world economies. With insight from guest speakers and new MBA/PhD hires, PIMCO coined the phrase The New Neutral to define its secular three- to five-year outlook for the world economies. In his most recent Investment Outlook, Bill Gross further elaborated on The New Neutral.
Commentary
Time (and Money) in a Cellphone
Our modern age is becoming more virtual than physical, which I find increasingly depressing if only because Ive failed to keep pace. I dont even own a cellphone. Still, it doesnt take a Boomer to observe that the reality outside as opposed to inside a computer or a cellphone should be the preferred experience. Scientists claim we are all just bits of information with billions of 1s and 0s, glued together to form a beating heart. Even so, Im sticking with live chirping as opposed to Angry Birds for now. Virtual reality seems just a tad UNreal to me.
Commentary
Seek Secular Staying Power in Global Credit
Secular Outlook Series: Mark Kiesel discusses long-term themes that underpin opportunities and risks in global credit markets.
Commentary
Multi-Asset Investing: Is Now the Time for Emerging Market Equities?
Although emerging markets (EM) will continue to grow faster than developed markets (DM), we believe the difference may be lower than what has been seen over the last five years. Higher earnings yields in EM equities offer partial compensation for risks, but careful analysis is warranted to assess the true valuation differential. A modest allocation to EM equities may be warranted based on relative price-to-earnings multiples and our expectation that policy rates will stay lower for longer than markets expect, which makes higher-yielding EM assets more attractive.
Commentary
Is There a UK Housing Bubble????
We see the UK experiencing a very traditional monetary cycle involving lower mortgage rates, higher house prices and then hopefully higher transactions. The Bank of England can address rising house prices either by raising financing costs via the banking system or by raising interest rates. Markets will watch BoE activity closely. Our expectation is for a gradual and modest interest rate cycle, with low rates in the UK economy for years to come. Housing may be an overvalued asset, but one that is secularly supported by low rates.
Commentary
The Crimean Conflict Has Affected Commodities Markets, Just Not Where You’d Expect
Since the end of February, when the Crimean crisis started to escalate, grain prices have responded to nearly every up and down of the crisis. Wheat is up 21%, and corn is up 10%. We believe investors looking to take a view on the future price of wheat or corn should do so through the options market. In this case, we think being long puts on wheat is an attractive way to implement our short wheat view.
Commentary
Five Things Your Credit Manager Shouldnt Be Doing (But Probably Is)
Questionable behavior among credit managers is back, but the good news is that we believe the credit markets still offer plenty of opportunities to potentially generate attractive returns. Smart, rational credit investing that avoids some managers nave reach for yield, and sticks instead to a deep focus on the long-term sustainability of companies balance sheets, may still reap rewards.
Commentary
What's the Game Changer for Gold?
In the coming days, PIMCO will publish its annual Secular Outlook. A cornerstone of our investment process, it sets the direction for how we will invest our clients assets over the coming three to five years. Of course, we revisit our outlook and investment conclusions each year to ensure their continued resonance and efficacy. Similarly, we have a regular strategic business planning process and conduct intermittent reviews. And, like our secular process, we often invite an outside expert or two to spark our thinking and challenge our priors.
Commentary
Europe, Not Too Hot, Not Too Cold Sweet Spot for Credit Investors
European economies are improving, yet the regions low growth and low inflation will keep the central bank engaged. As such, European duration should be safer versus other major developed economies. Given recent European Central Bank comments pointing to a further easing bias, we believe it makes European assets relatively attractive, especially in sectors with deleveraging fundamentals, positive technicals and attractive valuations.
Commentary
Managed Futures: Positive Trends Ahead??
Trend-following, the primary approach used in managed futures strategies, seeks positive returns by capturing momentum across major asset classes. Despite exceptional performance in the 2008 financial crisis, trend-following strategies were less successful in subsequent years, in part because massive central bank interventions increased market correlations, suppressed volatility and curtailed left-tail events.
Commentary
The ?Whites of Their Eyes?: The Fed?s Changing Reaction Function
While the unemployment rate has historically been one of the Federal Reserve?s key measures of spare capacity, and thus inflation risk, those eagerly awaiting each month?s employment report for signals on the Fed?s likely response may be barking up the wrong tree. The central bank still attempts to estimate the natural rate of unemployment, but conflicting signals from the labor market have clearly made the Fed less willing to trust its models. The result: Inflation will be more important than employment in the Fed?s decision-making process.
Commentary
De-Risking Pensions in a Time of Tapering
Despite improved funding in corporate defined benefit pension plans, some sponsors concerned about rising rates may be tempted to delay glide path prescriptions to boost fixed income allocations. For these sponsors, a better approach might be to break de-risking into two steps, potentially allowing for significant risk-reduction benefits yet preserving tactical flexibility in timing purchases of long-duration bonds. Any reduction in equity and other return-seeking assets should be implemented in short order to lock in recent market gains. ?
Commentary
Achoo!
There?s nothing like a good sneeze; maybe a hot shower or an ice cream sandwich, but no ? nothing else even comes close. A sneeze is, to be candid, sort of half erotic, a release of pressure that feels oh so good either before or just after the Achoo! The air, along with 100,000 germs, comes shooting out of your nose faster than a race car at the Indy 500.
Commentary
Henny Pennies
While the Fed?s qualitative guidance may have increased uncertainties over monetary policy, volatility will likely remain contained by powerful short- and long-run forces related to the economic outlook. In the UK, we should at least respect the risk of a hike late in the first quarter of 2015, earlier than what is currently priced in. In Japan, we believe the BOJ will remain full throttle on its current monetary easing for some time.
Commentary
Designing Balanced DC Menus: Considering Diversified Fixed Income Choices
Sponsors of defined contribution plans face a dual challenge: They must present investment options appropriate for plan members and design menus that encourage selection of well-structured portfolios. We believe that actively managed strategies designed to potentially reduce risks, invest globally and enhance yield relative to the index may improve diversification and lower concentration risk in fixed income offerings. Plan sponsors may consider a range of return and risk measures as they evaluate current and prospective fixed income offerings.
Commentary
Credit Availability Underpins Recovery in Commercial Real Estate Prices, But Also Poses Risks to CMB
Credit availability, low interest rates, limited new construction and improving economic conditions have contributed to the recovery in commercial real estate (CRE) prices. We expect a strong 2014 in the commercial mortgage-backed securities (CMBS) market, which has been a primary source of CRE credit expansion. Increasingly aggressive loan underwriting is a concern. CMBS investors need to speak with their wallets and push back on either valuations or underwriting standards if recent trends continue.
Commentary
Uncovering Opportunities in Emerging Markets
Emerging markets have underperformed expectations, but the longer-term secular outlook remains constructive for many regions. Highly negative investor sentiment and outflows have sharply reduced prices, significantly improving relative value in emerging markets. We see opportunities in emerging markets in interest rates, sovereign credit and select companies for investors with a longer-term investment horizon. ?
Commentary
Can You Have Your Cake and Eat It Too?
Many insurers would like to optimize both total return and book yield income, which may be seen as competing and divergent goals. In fact many insurers fall somewhere on the spectrum between these goals or shift their objective based on business and market conditions. While it has long been an accepted practice to track manager performance with regard to total return, tracking book income has been more elusive: PIMCO has an innovative and unique solution to help manager?s track alpha generated by active managers.
Commentary
Assuage Your Fears of Rising Rates with Global Diversification
?Although PIMCO believes interest rates are fairly anchored in the near term, we think investors can position their fixed income portfolios more defensively. Global diversification across developed and emerging markets can offer a defense against rising U.S. rates by reducing the concentration of risks within a portfolio, while also potentially lowering volatility and enhancing returns.
Commentary
Avoiding Losers Is as Important as Picking Winners in High Yield Markets Today
Although high yield bonds span a broad range of sectors, industries and individual credits, their yields today tend to fall within an increasingly narrow range. Narrow dispersion means portfolio decisions that target outperformance should now be guided by avoiding deteriorating credits as much as by selecting the most attractive rising stars. Strategies for picking the rising stars can extend to CCC rated credits where agency ratings lag the improvement in the underlying credit profile.
Commentary
Moving Forward With the Normalization of Yields
One response to yield normalization is to consider retaining core bonds and diversifying the specific risk factor of concern, in this case duration. In the past, global bonds have captured most of the upside but avoided a significant amount of the downside relative to domestic-only bonds. Generating capital gains from bonds in a rising yield environment requires defining concretely what yield normalization means ? where yields are going and when they will get there ? and setting these expectations against forward market pricing, country by country.
Commentary
Bob
PIMCO recommends overweighting credit and to a lesser extent volatility and curve. Underweight duration. Although credit spreads are tight, they are not as compressed as interest rates, which are now in the process of normalization. While PIMCO agrees with Janet Yellen that such normalization will be a long time coming (the 12th of Never?), probabilities suggest that as the Fed completes its Taper, the 5?30 year bonds that it has been buying will have to be sold at higher yields to entice the private sector back in.
Commentary
Warning Signs in Leveraged Credit?
Though leveraged credit markets are less levered than they were pre-crisis, signs of more lenient, issuer-friendly terms are prompting regulators (including the Fed) and investors to voice concerns.
Regulators have tightened lending guidelines, but strong demand versus supply means the market is able to find ways around such guidance.
Detailed bottom-up credit analysis with an emphasis on long-term fundamentals and loss avoidance remains crucial to investing in leveraged credit today.
Commentary
U.S. Growth Offers a Tailwind for the Region
PIMCO expects growth in the U.S. to improve due to a reduction in fiscal drag, although the Federal Reserve?s tapering and slowing growth in China are risks. While higher U.S. growth should offer a boost to exporters, Canada will likely face headwinds from a housing correction and drop in consumption. Latin America has fared relatively well amid the recent volatility in emerging markets, but differentiation across credits and markets continues to increase.
Commentary
Signs of Life??
As mining investment in Australia tapers, improvements in other sectors of the economy recently have allayed some concerns of a collapse in domestic demand. We share the cautious optimism but stop well short of expecting higher policy rates this year. Australian bond yields remain highly correlated to global developed market bond yields, and without a near-term domestic catalyst to cause that correlation to break, Australia?s yields are more likely to gradually rise, particularly in the longer end of the yield curve, which isn?t supported by anchored policy rates. ?
Commentary
Why Key Long-Term Trends Matter to Stock Pickers
The combination of demographic changes, climate change and the ongoing shift in emerging markets over the next 30 years will have long-term consequences for supply and demand factors and business sustainability for many companies. The impact of these long-term trends must not be underestimated. It is crucial for equity investors to not only be attuned to them, but also to understand how companies are adapting to the shifts in the global corporate operating environment. ?
Commentary
?Mind the Gap?: Adapting to a Post-Crisis World in Transition
??Barring any sharp deterioration in global geopolitical risk, the medium term outlook for equities is quite positive in an environment where we see subdued growth and inflation amid healing economies. From a markets standpoint, valuations are not very expensive ? they?re not cheap, but they?re not expensive versus historical standards for the market overall.
Commentary
A Sustainable Recovery??
Early signs indicate that the long awaited increase in business investment is underway. In turn, that bodes well for real income growth and the sustainability of the economic recovery. Given the improved economic prospects and the change in rhetoric at the Bank of England, the central bank could well be an early adopter of tighter monetary policy. We expect the BoE to hike rates ahead of the US Federal Reserve. While we beli?eve the British pound has already reflected the BoE?s guidance for official rates to rise by mid-2015, the bond market has yet to fully reflect the new environment. ?
Commentary
Striking a Balance: Risks and Opportunities in Emerging Market Debt?
?We believe the risk of a full crisis in emerging markets is greatly diminished as the initial conditions of such economies nowadays are quite different. Although there are vulnerable credits out there, the mark-to-market volatility in the financially strong emerging market economies can present advantages as longer-term fundamentals reassert themselves. By monitoring key triggers and employing a differentiated investment approach, investors may be able to take advantage of attractive valuations in emerging market debt. ?
Commentary
We See Opportunities in Commodities
Fundamentals and some recent data suggest that challenging trends for commodity investing may be coming to an end. Commodities may increase their role as an important and unique source of returns, diversification and protection from unanticipated inflation. As commodity sectors are each dominated by unique factors, we see even more opportunities to add value through active management.
Commentary
We See Opportunities in Commodities
Fundamentals and some recent data suggest that challenging trends for commodity investing may be coming to an end. Commodities may increase their role as an important and unique source of returns, diversification and protection from unanticipated inflation. As commodity sectors are each dominated by unique factors, we see even more opportunities to add value through active management.
Commentary
Deflationary Pressure and Tight Credit Facilities Weigh on Eurozone Recovery?
The eurozone is enjoying a broadly balanced resurgence in economic output and domestic demand. Deflation risk is real, and the European Central Bank?s asymmetric attitude toward its inflation target could contribute to a decline in inflation expectations. In the current climate, we continue to favour select regional credit exposure and look to generate attractive returns across European credit and asset-backed securities.
Commentary
PIMCO Cyclical Outlook: A Steady Passage in 2014?
PIMCO's baseline expectation is for 2.5% to 3% real growth in the U.S., thanks to trends toward growth and spending in the consumer, corporate and public sectors. In the eurozone, our baseline expectation of 1% to 1.5% real growth calls for a broad-based cyclical improvement in domestic demand amid steady external demand. We anticipate Japan will be the only major developed economy experiencing a slowdown this year, down to 0.5% to 1%, and we expect China's growth will continue slowing as well, with growth in the range of 6.5% to 7.5%.
Commentary
How Much Slack Is in the U.S. Economy? The Inflation Jury Should Decide
The unemployment rate may not be a reliable indicator of output slack in the U.S. economy. We?ll know (with a lag) if the economy has reached the end of the cyclical downturn when inflation picks up. The Fed will have to choose between risking a hawkish mistake or being behind the curve, waiting to see inflation actually increase. We expect it will choose the latter.
Commentary
2014: A Transition Year - Back to Fundamentals
The past several years have seen multiple regime changes in financial markets in Europe, each dominated by different factors and requiring a distinct approach to fixed income investing. As spreads tighten to pre-2008 levels, it is now time to ask whether a shift in investment style is due. Macroeconomic developments and inflation expectations are likely to be key determining factors in whether 2014 will be a good year for European bond investors.
Commentary
The Second Coming
Almost permanently affixed on the whiteboard of PIMCO's Investment Committee boardroom is a series of concentric circles, resembling the rings of a giant redwood, although in this case exhibiting an expanding continuum of asset classes with the safest in the center and the riskiest on the outer circles. Safest in the core are Treasury bills and overnight repo, which then turn outwards towards riskier notes and bonds, and then again into credit space with corporate, high yield, commodities and equities amongst others on the extremities.
Commentary
Ukraine: Geopolitical Risk Rising For Global Markets
Following Russia?s military intervention in Crimea, the situation in Ukraine remains extremely fluid. The outcome will determine to a large extent the systemic nature of the crisis and its impact on global markets, not just Europe. Russia stands to lose the most if this conflict should escalate into a full-fledged military confrontation, given the country?s financial, economic and reputational stakes.
Commentary
Is It Time for the Fed to ?Level? With Markets?
If unemployment continues to diminish and quantitative easing tapers to its expected conclusion, the Federal Reserve will likely feel compelled ? if not by consensus, then by markets ? to refine the forward guidance that it provides to the public today. With inflation running below 2%, the Fed may consider a price level target, together with more holistic measures of the state of the labor market, as a replacement for the unemployment threshold in offering guidance on the future pace of policy normalization.
Commentary
U.S. Housing: Investors Reach for Higher-Hanging Fruit
PIMCO expects house prices to transition to steady secular growth, with nominal price increases of 5%?10% cumulatively over two years. An environment of reduced volatility and steady gradual growth may result in tightening risk premia and spreads as the market begins to price in this new dynamic. Over the coming years, we will focus on whether the underbuilding of single-family homes is ultimately resolved through housing starts, rental growth or continued price appreciation.
Commentary
Flirting With Deflation
Over the medium term, we see downside risks to both growth and inflation in the eurozone, unlike the ECB?s more balanced view. However, even if eurozone inflation sinks close to 1% in 2014?2015, as PIMCO forecasts, this in itself probably would not be low enough for the ECB to consider further easing. A lack of further policy action may undermine the ECB?s credibility to anchor longer-term inflation more closely to 2%.
Commentary
Smoother Sailing in Washington?
With the debt ceiling increase out of the way, we should expect many fewer fiscal fights ? and less policy uncertainty and potential market disruptions ? emanating from Washington in 2014. We also expect Washington to do less harm from an economic growth perspective. We estimate that fiscal drag in 2014 will be about 0.4% of GDP. As we enter an election cycle, we expect Congress will do very little that is constructive for the economy in the year ahead ? meaning that tax reform and an immigration overhaul will likely have to wait.
Commentary
The Next Phase of Housing's Recovery: Which Five Investments Should You Own Today?
PIMCO has significant top-down and bottom-up expertise dedicated to understanding the U.S. housing market cycle. In 2006, we warned U.S. housing prices were significantly overvalued, which led to our defensive positioning heading into the recession. In 2011, we turned bullish on real estate and added investments such as non-agency mortgage-backed securities, banks and homebuilders that we felt would benefit from an eventual recovery in housing prices.
Commentary
Leveraged Finance Outlook: Riding the Low Default Wave
Following strong performance in 2013, we expect low (1%-3%) defaults in leveraged finance markets this year. Issuance should remain healthy, and continued slow but steady growth in the U.S. economy should offer further stability to these companies. However, careful credit selection and monitoring of sector trends remain imperative. Investors with low tolerance for volatility and more interest rate sensitivity may emphasize loans, while investors with greater risk tolerance and a more benign outlook for rates may look to high yield.
Commentary
New Maestro, Seasoned Band
The process by which the Fed carries out its duties is institutionalized, firmly rooted and unlikely to change - no matter who is at the helm. The core personal consumption expenditures (PCE) price index will be one of Janet Yellens most important guiding lights for future Fed policy.
Commentary
Most 'Medieval'
Unlike today, when most believe that animals were put on this Earth for humanitys pleasure or utility, most people in the Middle Ages believed that God granted free will to Adam, Eve and all of His creatures. Animals were responsible in some strange way for their own actions and therefore should be held accountable for them.
Commentary
High Yield in 2014: Where Can You Look for Upside in a 'Medium Yield' Market?
Default rates and credit losses in high yield markets remain below their long-term averages, and we believe default rates will remain low in 2014 and 2015 as well. Investors should consider positioning for better convexity via exposure to sectors with favorable industry dynamics and positive event risk from M&A or equity offerings, potential upside from price recovery in high quality bonds trading below par and exposure to select new supply from former investment grade companies.
Commentary
2014 Oil Outlook: How Slick Is the Oil Slope
While the supply outlook tilts the balances toward bearish in 2014, an improving global economy is a positive for oil demand and a support for prices. With roll yields positively contributing to returns, investors ultimately could be paid to hold a security that hedges both global event risk and any resulting shock to inflation. Growth in shale oil has been a powerful moderating force for prices by both filling an important gap in global supply and demand and by anchoring the back end of the futures curve.
Commentary
All Things in Moderation, Including Housing
In our view, the cooling housing market and other domestic factors will keep Canadian growth at a modest 1.75%-2.25% in 2014, despite a boost from higher U.S. growth. While we expect a correction in Canadas housing market to begin this year, the macroeconomic environment and the availability of mortgage credit suggest a housing crash is unlikely. In this environment, we think the Canadian dollar should remain attractive, 10-year bonds should offer the potential for gains, and provincial bonds will likely outperform federal government and corporate bonds.
Commentary
Demystifying Gold Prices
What is it about gold prices? Many people seem to believe they are impossible to predict, or even understand. At her Senate confirmation hearing in November, Janet Yellen said, "I dont think anybody has a very good model of what makes gold prices go up or down." Ben Bernanke also said last year that "nobody really understands gold prices, and I dont pretend to understand them either." While many factors influence the price of gold, PIMCO believes there is one that can explain the majority of changes in gold prices over the past several years: changes in real yields.
Commentary
Rummaging for Yield - The Case of the Insurance Investor
Since the height of the global financial crisis in 2008, insurance companies have faced three key challenges: First, insurance companies urgently needed to address new critical risk management issues as banking sector and peripheral sovereign credit risks significantly increased in Europe. Second, the prospects of longer-term low yields forced insurers to identify alternative sources of meaningful yield. And third, insurance companies needed to prepare for pan-European insurance regulation Solvency II.
Commentary
Ordem e Progresso
Amid stagnant growth and high inflation in 2013, Brazils equity market was one of the worst performers, the real was a chronic underperformer and the corporate sector struggled. Brazil needs to anchor economic policy around a stringent and credible primary surplus target rather than run the current mix of loose fiscal policy, subsidized public credit and ever tighter monetary policy. Valuations are attractive, but unless an effective policy mix is restored, the outlook for order in Brazils financial markets is less certain.
Commentary
Kansas
In the coming year, traditional money market strategies, long viewed as safe havens, will be challenged by new regulations, near 0% returns and a lack of investable assets. Short-term bond strategies could provide the right balance between risk-taking and liquidity management, and offer the potential for positive returns. Active managers have a distinct advantage because they can manage interest rate volatility and potentially source assets by identifying underappreciated sectors.
Commentary
U.S. Inflation Outlook 2014: Signs of Life
We expect headline CPI to rise to around 2.0% year-over-year in 2014, with our base case oil forecast in the $105-$110 per-barrel range and expectations for food prices to be stable. PCE, in our view, will likely remain below the Feds 2% target, around 1.5%. Individuals will get some relief at the supermarket, but they will feel a pinch from landlords, who will likely raise rents.
Commentary
Seesaw Rider
Theres 50 ways to leave your lover and maybe more than that to lose your money or "break the buck," as some label it in the money markets. You can buy the Brooklyn Bridge, bet on the Cubs to win the World Series or have owned 30 year Treasury bonds in 2013, to name just a few. But bridges and baseball aside, what youre probably interested in hearing from me is how to avoid breaking your investment buck in 2014.
Commentary
Waiting for the Great Pumpkin
Shortly before Thanksgiving, I had the privilege of being on an investor panel at Bank of Americas Debt Capital Markets and Derivatives Conference. On the panel before me was a trio of BofAs chief strategists, among them Michael Hartnett, their chief investment strategist. Mr. Hartnett reminded the audience that he was the man who coined the phrase "The Great Rotation" and after much anticipation, at long last, it was here.
Commentary
China's Consumer Stocks: Opportunities Despite Slower Growth
A weaker macro environment and curbs on spending by government bureaucrats have hit a range of consumer businesses and, in some cases, forced a reassessment of expansion plans. While Chinese consumption may be challenged in the near term, we think the impact will be felt most in the retail sector where slowing demand is compounded by oversupply. We see opportunity in other sectors that benefit from secular demand growth and constrained supply or strong brands, notably casinos and luxury sectors.
Commentary
PIMCO Cyclical Outlook for the Americas: Riding the Cross-Currents of Higher U.S. Growth and the Fed
In the U.S., lower fiscal drag and the possibility of higher consumer and corporate spending should drive growth higher in 2014. Supported by higher U.S. growth and stabilization in Europe and China, Latin America is set to grow 3%-4% on average, but with a large dispersion across countries. Canada should benefit from the U.S. recovery but will likely lag U.S. growth due to lower consumption and residential investment.
Commentary
Coal in the Fed's Stock-ing
Forward guidance has become an increasingly common practice among global central banks. Communicating a possible change in the policy rate could have a large effect on long-term interest rates. Capital has moved literally around the globe as a result of central bank activism in developed countries. Looking ahead, we expect 2014 to be a year of increased differentiation across emerging markets in terms of economic fundamentals, policy reactions and market outcomes.
Commentary
Australia Inc.
In 2013, real growth in business investment in Australia outside the mining sector slowed to almost zero, in part due to the high exchange rate. While some sectors of the economy such as housing appear to be improving, we continue to expect sub-trend growth in 2014 due to the subdued outlook for business investment. The RBA will most likely have to keep interest rates low for an extended period to ease the transition away from mining-assisted growth and encourage a weaker exchange rate.
Commentary
PIMCO's Cyclical Outlook for Asia: Growth Is Stabilizing but Not Stellar
In China, near-term economic performance will be dominated by the dialing back and forth of credit conditions by policymakers, while long-term reform progresses incrementally. Japans GDP growth will slow in 2014 due to a consumption tax hike but will still be above the countrys potential growth as it is assisted by reflationary policies. The pace of Australias growth will slow due to weakness in manufacturing and mining, reflecting tempered growth in China.
Commentary
A Much Better Dilemma
While the UK economy is likely to avoid reverting to growth levels of recent years, it must transition into a more durable recovery involving business investment, higher productivity and stronger real wages. However, headwinds for domestic demand look significant and the banking system appears to favour secured lending to consumers over businesses. We believe that much of the rise in bond yields is already behind us. With clearer value in shorter bonds, our preference lies in short and intermediate gilts.
Commentary
Settling In
An improving outlook for U.S. housing will be constructive for consumer spending, confidence and jobs. There are many ways to invest directly and indirectly in companies that should benefit from higher housing prices, a pickup in home repairs and remodeling, and residential investment spending. We continue to favor select investments in homebuilders, building materials, appliance manufacturers, lumber, home improvement, banks, title insurance, mortgage origination and servicing, and non-Agency mortgage-backed securities.
Commentary
PIMCO Cyclical Outlook: Synchronized Optimism
In the U.S., the abatement of fiscal policy tightening combined with steady improvements in labor market demand and higher asset valuations is likely to drive an increase in real growth. The eurozone should finally emerge from recession in 2014, and Japan is likely to continue to grow with the continued assistance of extraordinarily expansive policies. In China, external demand will likely improve, but domestic demand will likely slow somewhat.
Commentary
Muddling Through: The 'Realpolitik' of the Eurozone Crisis
The long-term cost of Europes economic recovery is likely to challenge social tolerance and political will to achieve a fully integrated fiscal and political union. Although able to exploit the untapped potential of European treaties, the soon-to-be-elected 8th European Parliament looks more likely to continue to muddle through. We see low medium-term risk for government and corporate bonds with maturities of up to three years, but caution may be required for securities with longer maturities and lower down in the capital structure.
Commentary
On the Wings of an Eagle
Ive always liked Jack Bogle, although Ive never met him. Hes got heart, but as hes probably joked a thousand times by now, its someone elses; a 1996 transplant being the LOL explanation. Hes also got a lot of investment common sense, recognizing decades ago that investment managers in composite couldnt outperform the market; in fact, their alpha would be negative after fees and transaction costs were factored in.
Commentary
Guidance Counselors
Forward guidance is an explicit communication by a central bank that provides information today about the timing for specific policy tools in the future. There are at least three types of forward guidance: calendar-based, outcome-based and optimal control. Since 2011 the Fed has deployed both calendar-based and outcome-based guidance. We expect the Yellen Fed to enhance the current outcome-based guidance to convey more information about the timing and pace of policy moves.
Commentary
DC Plan Design for the Bumpy Road Ahead
In late October, PIMCOs CEO and Co-CIO Mohamed A. El-Erian presented the keynote speech at Pensions & Investments West Coast Defined Contribution Conference. He also spoke with P&I about top-of-mind concerns for retirement plan providers and sponsors. The Q&A below is based on that conversation.
Commentary
When Flexibility Meets Opportunity in the European Commercial Real Estate Market
The pace of asset sales by European banks has been slower than many anticipated due to the fragile economic, political and regulatory environment across the continent. A complex CRE landscape and the pervasive effects of cognitive bias, capital rigidity and the unintended consequences of regulation mean mispricing can occur frequently. Unlocking value in this environment requires a flexible approach to investing across the capital structure and the resources to source, underwrite, structure, service and operate commercial real estate assets.
Commentary
Sovereign Ambitions to Develop Infrastructure Benefit Emerging Asia's Utilities Sector
The scope for infrastructure development in emerging Asia is tremendous, and the utilities sector has potential to contribute to and benefit from that growth. In general, we have found that state-owned utilities benefit from a range of operational advantages, partly as a result of the governments vested interest. PIMCOs bottom-up research allows us to analyze evolving company- and sector-specific factors within the greater macroeconomic picture to identify the best investment ideas in Asias utilities sector.
Commentary
Scrooge McDucks
With the budget and debt ceiling crises temporarily averted, perhaps a future economic priority will be to promote economic growth; one way to do that may be via tax reform. How to proceed depends as always on the view of the observer and whether the glasses are worn by capital, labor or government interests.
Commentary
Positioning for Municipal Market Volatility
We do not anticipate a significant increase in the frequency of municipal defaults, but there are pockets of credit stress in U.S. municipalities and territories, particularly those with unfunded pension obligations and unsustainable budget imbalances. Large concentrations of exposure to Puerto Rico within subsets of the municipal market will likely lead to an increase in spread volatility across other municipal sectors in the coming quarters.
Commentary
Connecting the DOTs: The Role of North America's Emerging Markets' in Achieving Energy Independence
The midstream energy sector is likely to grow more quickly than the overall U.S. economy over the next several years, creating the potential for attractive investment opportunities. North Dakota, Oklahoma and Texas, or the DOTs for short, stand to disproportionally benefit from strong growth in onshore U.S. oil and gas shale development. PIMCOs approach is to identify and invest in the companies, including pipeline operating companies, favorably positioned to benefit from prolific oil production.
Commentary
Watch for the Signals on Policy Direction Out of Washington
As expected, the deal that passed Congress on October 16 is another short-term, kick-the-can package. The big question is whether we will have to endure yet another saga next year, when Congress is once again forced to address the debt ceiling and fund the government. We are skeptical on the outlook for the bipartisan budget conference committee: The main obstacles to a grand bargain that have existed for the past two years continue today.
Commentary
The Squeeze Play
Reductions in Treasury bill and commercial paper issuance compounded by developments on the demand side mean the squeeze play is on for many short-term portfolios. Investors should consider the potential for substantive changes to liquidity conditions as banks contend with increases in capital requirements due to updated Basel III regulations. Active management of short-term investments is important: Dont rely on static regulatory frameworks or traditional indexes to determine a portfolios unique liquidity needs.
Commentary
Taper Time - Mining, That Is
Recent data suggest that mining investment is tapering, with the sector detracting from real growth in the first half of 2013. We see three possible growth scenarios: a handoff to the corporate sector; no handoff, with demand continuing to slow; or a handoff to the highly levered household sector, which would create long-term risks. Until we see meaningful signs of a growth handoff from the mining sector to a new balance sheet that has the capacity to expand, our base case calls for sub-trend growth and low interest rates, supporting bond prices over the cyclical horizon.
Commentary
Getting Serious About Investing Responsibly
To date, much of ESG-related investing has focused on negative screening, but we believe there is a better approach. This approach rests on three pillars: identifying and analyzing key ESG issues facing a given investment sector, engaging with the issuers of securities, and supporting the development of markets for ESG investments.
Commentary
After Detroit: Rigorous Research and Credit Selection Is the Key to Investing in Municipal Bonds
Detroit recently declared bankruptcy, setting off the largest municipal Chapter 9 proceeding in history. There has been and will continue to be a lot of noise in the media, underscoring challenges but also presenting opportunity for experienced investors. PIMCO has long favored special revenue essential service bonds over GO bonds. Detroit Water and Sewer bonds are payable by a pledge of and statutory lien on net revenues of the water or sewer system, and as such benefit from provisions in the federal bankruptcy code ensuring that the pledge is not affected by the petition.
Commentary
The New Normalization of Fed Policy
The Fed is sending a message that the unwinding of its extraordinary accommodation will be done with great care and patience, and will take time - a long time. In delaying a taper, not only did the Fed show markets it has little tolerance for any tightening of financial conditions, it also strengthened its forward guidance considerably. The Feds decision to delay a taper will likely relieve some of the upward pressure on longer-term interest rates.
Commentary
Washington's Prolonged Saga and the Market's Reaction
The federal government shutdown represents yet another self-inflicted wound to already modest growth. While the market seems to be mostly sanguine about the government shutdown, a breach of the debt ceiling which we feel is highly unlikely would be incredibly negative for financial markets.
Commentary
Survival of the Fittest?
I hate crows and my wife Sue hates bugs, but like most married couples we have learned to live with our differences. Crows eat bugs though, and bugs eat bugs, and that scientific observation sets the context for the next few paragraphs of this months Investment Outlook.
Commentary
PIMCO Cyclical Outlook for the Americas: A Slow-Moving Fed Benefits Economies on Both Continents
PIMCO expects the U.S. economy to grow 2.0%2.5% over the next year. However, a continued government shutdown would be a drag on growth. In Latin America, we see growth picking up to 3.0%3.5%, but the outlook varies by country. Mexico should fare well, but Brazils story is more mixed. In Canada, we believe the housing correction will be less severe than many are predicting, and we expect GDP to grow 1.5%2.0% over the cyclical horizon.
Commentary
Investing In Corporate Bonds: The Compelling Case For Active Management
Passive investment returns in the Canadian corporate bond market have been unimpressive because of the way corporate bond indices are constructed and factors unique to the Canadian market. Unconstrained by these limitations, active managers with global reach may provide superior returns. The current environment presents an attractive opportunity for Canadian investors to implement a wide discretion, active approach to managing corporate bonds.
Commentary
PIMCO Cyclical Outlook for Europe: Near-Term Recovery, Long-Term Risks
While Europe has emerged out of recession, the relative tightness of monetary policy means the eurozone is still struggling to get back to potential pre-Lehman growth rates. The European Central Bank should be able to maintain stability over the cyclical horizon while policymakers continue to address outstanding issues as they look to build a less vulnerable monetary union. We are selective in our approach to regional credit and remain neutral on the euro, balancing our cyclical outlook with longer-term secular concerns on the eurozone outlook and valuations.
Commentary
Secular Trends in Asian Credit Markets Shape Long-Term Investment Themes
The next several years will likely see many Asian corporate issuers to come to the market for financing, whether to pursue long-term business plans or to employ traditional corporate finance and leverage strategies. Rigorous credit research, flexible resources, experienced local portfolio management and strong relationships with local stakeholders are all crucial to uncovering attractive opportunities while monitoring volatility in Asias credit markets.
Commentary
The Euro Tug-of-War
Faced with lingering economic stagnation, record unemployment and continued political strife in the region, the common consensus for a depreciation of the euro seems only natural and very much required to counter the weak cyclical position of the eurozone. The rising current account surplus in combination with net long-term capital inflows point to a stronger euro that could stay with us for an extended period; such a development could potentially undermine the fragile social consensus to continue with the necessary structural and fiscal reforms.
Commentary
U.S. Commercial Real Estate: Will the Good Times Last?
The CRE market has experienced a gradual recovery in asset pricing since the 2008 financial crisis. Despite the duration of the recovery, there continues to be dislocation in the CRE market that astute investors can capitalize on. We believe certain properties in non-major markets look attractive for acquisition, and have been acquiring residential land on an opportunistic basis.
Commentary
Growth and Rising Stars
While developed market growth in several regions is picking up cyclically from low levels, overall global economic growth should remain subdued over the next several years. We believe credit spread tightening and rating upgrades are most likely for specific companies in industries and areas with strong growth. We see these "rising star" companies in the U.S. and European auto sector, the gaming, energy and chemical industries and in sectors tied to the U.S. housing market.
Commentary
A Fine Balance in the Global Profits Cycle
In the U.S., we expect growth to accelerate over the cyclical horizon, but to disappoint elevated consensus expectations. In Europe, we also expect growth to accelerate, but just barely, and also below consensus. In Japan, we expect growth to remain heavily reliant on aggressive fiscal and monetary policies. And in emerging markets, we expect a stabilization in growth assisted by central banks regaining control of currency and financial market conditions. The outlook for global corporate profits is a key measure of success in determining the handoff to self-sustaining growth going forward.
Commentary
Is the Commodity Supercycle Dead?
While commodity price appreciation wont likely mirror the supercycle, this shouldnt necessarily imply a negative view on commodity returns going forward. We believe commodity prices are at reasonable levels from a long-term valuation perspective. In addition, the roll yield from investing in commodities is the highest its been since 2005. The outlook for commodity returns today seems broadly consistent with historical returns, and commodities remain an important tool for hedging inflation risk.
Commentary
What's Happening to Bonds and Why?
To say that bonds are under pressure would be an understatement. Over the last few months, sentiment about fixed income has flipped dramatically: from a favored investment destination that is deemed to benefit from exceptional support from central banks, to an asset class experiencing large outflows, negative returns and reduced standing as an anchor of a well-diversified asset allocation.
Commentary
Seventh Inning Stretch
They say that reality is whatever you wish it to be and I suppose that could be true. Just wish it, as Jiminy Cricket used to say, and it will come true. Realitys relativity came to mind the other day as I was opening a box of Cracker Jacks for an afternoon snack. Thats right I said Cracker Jacks! I cant count the number of people who have told me during the seventh inning stretch at a baseball game to make sure I sing Cracker Jack (without the S) because thats what the song says. I care not. No one ever says buy me some potato chip or some pea
Commentary
Policy Uncertainty on the Rise
Congress seems to be digging in and ramping up the rhetoric in advance of a possible government shutdown, a debt ceiling increase and a probable selection of a new Fed chair. We think it is likely policymakers will agree to a short-term deal to fund the government and avert a shutdown, and also cobble together a resolution on the debt ceiling, although neither is likely until the last minute. The Fed chair debate will likely continue to sway markets over the next few months, leading to greater uncertainty and greater market volatility.
Commentary
Switcheroo
What is priced into the bond market in terms of its outlook for the Federal Reserve? Does the increase in interest rates sufficiently reflect the markets perceived policy shifts?
Commentary
Using Equities to Hedge Inflation? Tread With Care
Historically, broad equity returns have not intrinsically provided a good hedge against inflation. Three key attributes may help companies withstand inflationary environments - pricing power, supply side advantages and a willingness and ability to sustain dividend hikes at a rate faster than inflation. To realize equities long-term potential as a key source of portfolio returns, investors should consider enlisting active managers who select stocks with a view on inflation and its effect on specific companies.
Commentary
Purgatory Is Heaven
Since June, the Fed has stressed three messages: Tapering is not tightening, the federal funds rate will not move in tandem with a slowdown in asset purchases, and any change in Fed policy will rely on data, rather than a date. If Ben Bernanke leaves the Fed when his term expires, whoever is chosen to replace him will be bound by rules and the strength of the institution. The outlook for interest rates depends more on the Feds overall approach to the policy rate, and PIMCO believes the Fed will not increase that rate until 2016.
Commentary
What Role for Emerging Markets After the Sell-Off?
While history suggests that the sell-off in emerging market bonds could ultimately offer attractive buying opportunities, it is important to anchor investment decisions firmly within a forward-looking economic and market outlook. Continuing vulnerabilities in global growth suggest there is fundamental value in EM bond yields at present valuations, as interest rate hikes priced into EM yield curves are unlikely to materialize in an environment of tentative growth.
Commentary
Bond Wars
Adaptation is tantamount to survival in the physical world. So argued Darwin, at least, and I am not one to argue with most science and its interpretation of natural laws. Adaptation has been critical as well for the survival of countries during wartime, incidents of which I am drawn to like a bear to honey, especially when they concern WWI. Stick with me for a few paragraphs on this the following is not likely to be boring and almost certainly should be instructive.
Commentary
Alternatives for Today's and Tomorrow's Market Challenges
Investors should consider alternative investment strategies, which could enhance diversification and the potential for alpha, or risk-adjusted returns, because returns from traditional asset classes in coming years may be lower and more volatile than those realized historically.
Commentary
Calm Has Replaced Fear in the Bond Market
Calm largely returned to the bond market in July following a bout of turbulence in June. Volatility declined across the broad spectrum of fixed income assets, with interest rates and credit spreads falling from their highs, in some cases dramatically. Flows have also turned positive in many market segments, particularly for high yield and bank loan securities.
Commentary
Canadian Secular View: Into Darkness?
Many investors are buying Canadian federal government bonds, shorting Canadian bank stocks and selling Canadian dollars in anticipation of a prolonged downturn. While significant risks are clearly facing the Canadian economy, our baseline forecast does not justify positioning our portfolios for a prolonged Canadian downturn.
Commentary
The Tipping Point
Ive spun a few yarns in recent years about my days as a naval officer; not, thank goodness, tales told by dead men, but certainly echoes from the depths of Davy Jones Locker. A few years ago I wrote about the time that our ship (on my watch) was almost cut in half by an auto-piloted tanker at midnight, but never have I divulged the day that the USS Diachenko came within one degree of heeling over during a typhoon in the South China Sea. Engage emergency ballast, the Captain roared at yours truly the one and only chief engineer.
Commentary
Stay the Course
It is that time of the year again. As school schedules give way to summer vacations, many families will be packing up the SUV to head to one of this nations amazing national parks. Years ago, my young family traveled to Yellowstone National Park, home of Yogi Bear and Old Faithful. The requisite float trip down the Snake River was arranged and a good time was had by all a bit of spray but nothing too jarring. Only days later, I returned to the Snake River and had the ride of a lifetime.
Commentary
Floating-Rate Notes: A New Frontier in Treasury Investing
For investors, Treasury floating-rate notes (FRNs) will likely offer a hedge against rising rates and a yield pickup over a T-bill. For the Treasury, FRNs could help reduce the risk that an auction could fail to attract customer interest, and also help diversify its investor base. PIMCO will evaluate the merits of these securities based on our macroeconomic top-down view and valuation-focused bottom-up analysis.
Commentary
Efficient Pension Investing
Adapting the Sharpe ratio to pension portfolios can help plan sponsors choose among a multitude of investment options designed to achieve the same goal. In our experience, the most significant efficiency gains have come from shifting from intermediate bonds to long-term bonds and introducing lower-volatility substitutes to equities.
Commentary
Promise to Be Irresponsible
We believe the recent rise in real rates and fall in inflation expectations could jeopardize the U.S. economic recovery. We also believe these are a direct result of uncertainty about the Federal Reserves ultimate goal. Low real yields accompanied by sufficient nominal growth are the necessary prescription for a still ailing economy.
Commentary
Taking Seniority: Looking to Bank Loans in Uncertain Markets
Bank loans are senior secured loans to non-investment-grade corporations. They are floating rate instruments, secured by the collateral of that company and senior in the capital structure. Bank loans can be a more defensive way for investors to move into the high yield space, due to the collateral and their senior position. While we have seen yield spreads tightening among loans, on a relative basis we do think loan valuations still look attractive. PIMCOs investment process helps us seek these attractive opportunities while managing risk.
Commentary
Which Way for Bonds? Mapping a Path Forward
In 1980, the Federal Reserve, led by Paul Volcker, tightened the quantitative noose to tame double-digit inflation, fueling an unprecedented tailwind for bond prices. Thirty years later we find ourselves at the other extreme, as central banks print money in the trillions of dollars to stimulate economic growth, and inflation is abnormally low. While we are not likely to see a repeat of that type of bull market any time soon, we also do not believe we are at the beginning of a bear market for bonds.
Commentary
Managing the Odds: Overcoming Exit Strategy Biases with Tail Risk Hedging
Rather than making an exclusive choice we believe that rebalancing, options purchase and diversification should all be considered on the same footing. Is it better to dynamically de-risk if markets begin to fall to lock in gains, or is it better to purchase explicit tail hedges? Our tendency, as humans, to be time-inconsistent, with behavior changing as the situation changes, makes dynamic rebalancing prone to behavioral biases. At pricing levels of low option premia the purchase of options to prevent time-inconsistent behavior seems like a judicious decision.
Commentary
How Asia's Growth Transitions and Policy Experiments Are Shaping the Global Outlook
Our view is that Chinese GDP growth will downshift, averaging 6%-7.5% for the next five years as net exports and investment are reaching their limits. In Asia, Japan is perhaps the economy closest to the T-junction described in PIMCOs global secular outlook: The destination of Japans journey looks increasingly uncertain, with multiple potential outcomes that could stabilize or destabilize the global economy and markets.
Commentary
Liquidity Markets Likely to Evolve Under Proposed Money Market Reforms
We view the SECs proposed regulations on money market funds as a pivot point for cash and liquidity management. If the first proposal is adopted, prime institutional money market funds would convert to a floating net asset value share price. That conversion would likely cause some volatility in pricing. As we do not expect yields to increase in the near-to-medium term, in our view the risk-reward tradeoff would not be as attractive for investors.
Commentary
A Longer Time Horizon Can Be an Advantage for Value Investors
We believe that given challenging prospects for attractive investment returns, the value premium could become even more important in the years ahead. Even in an uncertain environment like we are currently experiencing, we believe the merit in owning equities for the long term is unchanged: We want to participate as an owner in a growing, profitable business.
Commentary
Broader Use of Bail-Ins Could Spur a Revival of Asset-Backed Securities in Europe
We believe ABS issuance will likely increase in Europe as eurozone developments and possible future bail-ins potentially result in higher risk premiums and funding costs for European banks. Although regulators are playing catch-up, capital markets are making room for a more credit-intensive product, helping to lead the way for a resurgence in ABS. Due to concerns over the security of bank deposits, investors may look to the ABS sector, which offers collateralized bonds that are free of bail-in risk.
Commentary
Will Green Shoots Flourish in U.S. and Latin America?
The US economy is much further along the road to repair relative to its developed market peers, but it is still dealing with an unsustainable fiscal situation. Latin America is closely coupled to the rest of the world. What happens in the U.S., China and Europe over the secular horizon is especially critical. Our secular investment outlook calls for a more defensive posture toward risk. In U.S. fixed income, this suggests positioning for alpha rather than capital appreciation.
Commentary
The Role of Cash in Multi-Asset Portfolios
Determining the optimal allocation to cash is as challenging as ever in todays unusually uncertain markets. When allocating to cash, investors should consider a multi-dimensional framework to assess the liquidity of the underlying cash instruments. In our view, the most attractive risk-adjusted opportunities for cash investors lie just outside the traditional money market space.
Commentary
Wounded Heart
Joseph Schumpeter, the originator of the phrase creative destruction, authored a less well-known corollary at some point in the 1930s. Profit, he wrote, is temporary by nature: It will vanish in the subsequent process of competition and adaptation. And so it has, certainly at the micro level for which his remark was obviously intended. Once proud, seemingly indestructible capitalistic giants have seen their profits fall short of everlasting and exhibited a far more ephemeral character.
Commentary
Defense and Selective Offense
Given the markets newfound risk appetite for credit and less attractive valuations, we are taking advantage of global credit market liquidity in an effort to reduce our overall risk posture. In our selective offense approach, we continue to favor U.S. housing and housing-related areas, in addition to select investments in the energy, pipeline, specialty finance, gaming, hospitals, and airline and auto industries, given the more positive fundamental outlook for these sectors.
Commentary
Into the Woods
Excess liquidity, falling net issuance and higher correlations among assets complicate the eventual exit that the Federal Reserve and other central banks must make from their extraordinary policies. The Bank of Japans ideology has completely changed to tackling deflation from tolerating deflation. The key focus in the coming months will be how private sectors react. Investors who depend chiefly upon central bank activism may put themselves at risk. They may need to hedge volatility by ensuring their investments are built more on solid fundamentals and reasona
Commentary
In an Era of Uncertainty and Lower Returns, It's Time for Alternatives
The initial economic and capital market conditions of the 1980s set the stage for a multi-decade bull market for stocks and bonds. Times have changed, however, and traditional investment portfolios are unlikely to deliver returns as healthy as those enjoyed for much of the last 30 years. Its time to think alternatively about asset allocation and index construction, sources of alpha and beta, and risk and return objectives to increase the probability of success in what we believe is a new era for investors and financial markets.
Commentary
UK Secular Outlook - Morphing into the Carney Era
The UK remains in a stable disequilibrium, one that needs to either transform into growing economy with narrowing income differentials or risk a more aggressive policy response. Financial repression, protection of real purchasing power, tail risks of accelerated currency weakness and price sensitivity will likely dominate UK markets over the secular horizon. Investors may consider progressively reducing exposure to assets susceptible to tail risks. Higher quality short-dated income-generating, inflation-hedging and non-sterling assets remain attractive.
Commentary
Global DC Plans: Similar Destinations, Distinctly Different Paths
DC plans in in the U.S., Australia and the U.K. may benefit from better aligning asset allocation defaults to workers needed outcome: purchasing power in retirement. Focusing on needed outcomes would suggest a higher allocation to real assets, earlier de-risking and consideration of tail risk hedging.
Commentary
Reflation in the Balance
Four of the worlds major central banks are now all in when it comes to ballooning their balance sheets in correlated, if not coordinated, efforts to achieve escape velocity in their economies. In accounting for the impact of quantitative easing on two key balance sheets, we are able to interpret, monitor and calibrate the programs currently in place. This in turn can help us prepare portfolios if or when sentiments and inflation expectations shift.
Commentary
Filling the Hole We Have Dug
Mining investment contributed more than 60% of the growth in Australias GDP in 2012. The expected decline in mining investment will likely leave a significant economic hole in the short term that needs to be filled. PIMCO expects easier monetary policy will be needed to support other sources of domestic growth, such as non-mining business investment, household consumption and housing construction.
Commentary
Europe's Crossroads: The End of the Muddle Through?
The eurozone may be nearing a critical junction, owing to its weak growth, weak institutions, debt dynamics and domestic and cross-border political challenges. The German government may take a more active leadership role after its national election, but it is more likely it will continue with piecemeal measures. Considering the current low yield environment and ample central bank liquidity, it is important to focus on absolute yield levels and returns, and consider global alternatives such as emerging market securities and currency exposure.
Commentary
How to Turn the ECB Straggler into a Central Bank Pacemaker
In our opinion, the ECB will be most effective if it can design a programme that helps banks deleverage more quickly to stimulate growth in the real economy. To have a meaningful impact on Europes broken transmission mechanism, any ECB programme needs to not only lower the cost of credit, but also be regionally tailored or big enough to be effective. Long-term investors should remain focused on the quality of issuers balance sheets rather than simply taking more risk because of lower prospective returns.
Commentary
As Energy Demand Outpaces Supply, Asia Looks Overseas to Refuel
Many Asian countries are encountering growing energy shortages due to declining indigenous resources and domestic consumption growth. Oil companies in Asia frequently engage in overseas acquisitions. In many cases, these transactions help enlarge reserve base, access technological know-hows and enhance corporate profitability. Strong sovereign support is a key investment thesis in the Asian oil and gas sector. Through our bottom-up analysis, we are finding numerous investment opportunities.
Commentary
Making the Most of Equity Allocations
We believe slowing global growth and deleveraging are likely to result in lower long-term returns for equities. Traditional approaches to building equity portfolios may not be enough for investors to meet their return goals. We have found three complementary ways investors can enhance equity return potential: fundamental indexes, index-plus strategies and high active share stock selection approaches.
Commentary
Stress Points: What High Frequency Data Tell us About Hidden Tail Risks
Whereas rare events that occur over lower frequency, longer horizons are much harder to find (and hence much harder to derive statistics from), intraday events create a larger, more accessible data set that can be used to supplement data on tail events. Analyzing the reactions of different markets to intraday tail events can provide valuable information for investors looking for effective tail risk hedges for their portfolios.
Commentary
Hold Your Houses: The Housing Recovery May Take Longer Than You Think To Reach Consumers
New residential construction needs to double from 2012 levels to meet long-run stable demand, and the pace of that increase is critical. Consumer credit growth is hindered by strict lending standards, continued deleveraging and limits to mortgage equity withdrawal. As a result, the balance of mortgage debt is unlikely to meaningfully increase in the next 12-18 months, delaying a return of the virtuous consumer cycle.
Commentary
New Normal ... Morphing
The New Normal has morphed to include consequential elements of a "stable disequilibrium." In the midst of notable multi-speed dynamics, the global economy as a whole is muddling along a road that will give way over the next three to five years to one of two stark alternatives: either sustainable global growth, institutional and political renewal in the West and safe deleveraging; or growth shortfalls that cause financial instability, fuel greater social tensions, accentuate political dysfunctions and complicate debt traps.
Commentary
Global Bonds: A Flexible Solution for an Uncertain Market
The recent rallies in both safe-haven and risk assets have left many investors in a quandary. We believe alpha, or above-market return, will have to play a greater role for investors seeking to meet return targets. In our view, the current environment affords many opportunities for generating alpha.
Commentary
There Will Be Haircuts
It has been the objective of the Fed over the past few years to make even more innovative forms of money by supporting stock and bond prices at cost on an ever ascending scale, thereby assuring holders via a Bernanke put that they might just as well own stocks as the cash in their purses. Gosh, a decade or so ago a house almost became a money substitute. MEW or mortgage equity withdrawal could be liquefied instantaneously based on a never go down housing market. You could equitize your home and go sailing off into the sunset on a new 28-foot skiff on any day but S
Commentary
Europe's Sovereign Debt Problem: A Call for a Clear Destination
Without political commitment to a common fiscal destination, the long-term instability and market distortions within Europes capital markets are likely to intensify. To preserve the euro, the eurozone must develop federal fiscal policies that tackle significant economic, cultural and societal differences and define a credible roadmap to achieving structural reforms, a banking union, political union and fiscal union. Historical precedents in Europe may help guide the way.
Commentary
Enhancing Credit Returns in 2013
While credit achieved exceptional returns in 2012, achieving such returns in 2013 will be challenging in light of less upside potential and limited spread compression. Challenged by continued loose central bank monetary policies, alpha generation plays an increasingly significant role in seeking attractive total returns within credit portfolios.
Encouraging investors to provide managers with a variety of innovative approaches and flexibility may enhance the return potential of a European corporate bond portfolio without materially changing overall credit or interest rate risks.
Commentary
The Pharaoh's Dream
As yields on assets decline, central banks ultra-loose monetary policies are effectively forcing investors further out the concentric circles into lower quality, more illiquid sectors in search of positive yielding assets after deducting inflation. In order to achieve 6%-7% returns in the future, investors may be required to take on more risk. Allocating part of a portfolio away from middle circle asset classes into assets with higher return potential as well as assets offering liquidity is the right strategy in our opinion.
Commentary
Hyperactive Monetary Policy: The Good, the Bad and the Ugly
Hyperactive monetary policy (HMP) is in full force as fiscal policy retreats. The benefits of HMP outweigh the costs for now. Despite cyclical growth, we will likely not achieve escape velocity and eventually the costs will likely overtake the benefits.
Commentary
Global Investing in 2013: Policy Dominance, Active Management and a New Paradigm in Currencies
We expect that the impact of ongoing global policy experimentalism on real economic growth and financial markets will likely vary substantially from country to country, creating both risks and opportunities. With flexible, active global strategies investors can potentially benefit from a broader opportunity set and the ability to go off benchmark in an effort to both avoid risks and tap opportunities.
Commentary
Telling (Taper) Time
Investors need be alert for signs of progress in the many employment indicators the Fed is watching, and listen closely to what the Fed is saying to know when bond buying will be tapered. The failure to achieve escape velocity is why the Fed is using its printing press to purchase $85 billion of securities monthly. These purchases will continue, the Fed says until the outlook for the labor market has improved substantially. The Fed has made progress toward achieving escape velocity but the progress must be sustained for the Fed to throttle back on its stimulus.
Commentary
Don't Pay Too Much for That Bordeaux - Or That Bond
The financial markets reliance on ratings agencies and benchmarks, along with regulations, can cause distortions in the value of some securities. These price distortions can create potential opportunities for some investors. Investors should consider aligning capital allocation with outcome-oriented objectives that arent influenced by credit ratings or benchmarks.
Commentary
PIMCO Cyclical Outlook for Asia: How Leadership Changes Are Shaping Asia's Outlook
For Asia, slow but not slowing global growth will likely keep external demand neutral, and policy developments will therefore help shape the economic outlook. In Japan, we see a significant boost to aggregate demand coming from the concerted monetary and fiscal expansion of the new Abe government. In China, concerns about inflation, housing market excesses, and long-term financial stability are prompting policy restraint that should keep growth below 8% this year.
Commentary
Can Something Good Be Cheap Too?
Over the last eight years, the least volatile components of the MSCI World Index tended to have lower valuations, higher profit margins and higher dividend yields. This anomaly, which appears to be among the most persistent in all of equity space, is rooted in speculative human behavior such as the lottery ticket phenomenon.
Commentary
PIMCO Cyclical Outlook for the U.S.: Back From the Brink
We expect the largest contributors to U.S. growth this year will be housing and related industries, increases in capital expenditures (albeit from very depressed levels), certain manufacturing sectors, such as the auto industry, and the energy sector. We see roughly 1.7 percentage points of drag on GDP coming out of Washington far less than the four to five percentage points of potential drag had there been no fiscal cliff resolution. We believe the Fed will continue with hyperactive monetary policy, which we now call QE Infinity, that does not have an explicit end date or progr
Commentary
A Man in the Mirror
Am I a great investor? No, not yet. To paraphrase Ernest Hemingways Jake in The Sun Also Rises, wouldnt it be pretty to think so? But the thinking so and the reality are often miles apart. When looking in the mirror, the average human sees a six-plus or a seven reflection on a scale of one to ten. The big nose or weak chin is masked by brighter eyes or near picture perfect teeth. And when the public is consulted, the vocal compliments as opposed to the near silent/ whispered critiques are taken as a supermajority vote for good looks.
Commentary
Whatever It Takes in Japan? It Takes an 'Audacious' Monetary Policy!
The BOJ will have to make some key monetary policy decisions soon, given Kurodas sincere but ambitious desire to achieve 2% inflation within two years. The BOJ has lagged far behind other major central banks in the deployment of its balance sheet since the onset of the financial crisis. Expect Japans monetary policy to be more aggressive and experimental as it shifts toward reflating the economy. For global investors, this may mean a modest economic growth contribution from Japan, at least over a cyclical horizon, as well as additional central bank liquidity pouring into global m
Commentary
What Happened to That Export-Led Recovery?
With nearly 50% of the UKs total exports going to Europe, an economic area constantly flirting with its own recession, it is no surprise to see that UK trade performance has been challenged.As the US continues to re-heal, and trade becomes more geographically diversified, we should see exports start to grow once more, albeit off a modest base. The easing in sterling is undoubtedly welcome and will improve prospects for exports, but it is unlikely to be a game changer.
Commentary
Investors Need to Pivot
Fixed income investors need to think differently in the current environment. Investors may want to consider pivoting to strategies that are less focused on traditional benchmarks and more oriented to generating income and providing greater flexibility to hedge against rising rates, widening credit spreads or higher inflation.
Commentary
Rising Political Risk and Ongoing Economic Weakness Challenge a Difficult Journey to Recovery
Looking ahead, it will continue to be a very bumpy journey as we anticipate economic contraction in the eurozone by -0.75% to -1.25% over the next year, hampered by growing political risk and fiscal tightening. Although we expect the pace of contraction in the eurozone to diminish over 2013, the duration of the recession is likely to be longer than consensus forecasts.
Commentary
Finding the Sweet Spot
Where is the investment sweet spot in todays global financial markets? The uneven global growth outlook means there are opportunities and risks for both credit and equity investors.
Commentary
Washington May Be Ready to Take a Break From the Brink
With Washingtons dysfunction not in the forefront, the economy could be more unencumbered to grow, with markets trending in a similar direction. The Feds proactive policies should continue to favor overweight positions in the five-year through 10-year part of the Treasury yield curve and support interest-rate-sensitive sectors of the economy most notably housing. In the longer term, however, we would advise investors to be cautious: Without meaningful long-term structural deficit reform, real growth will inevitably lag in the U.S.
Commentary
DC Plan Sponsors: Now's the Time to Get More From Bonds
Long on equities and light on bonds, todays DC plan lineups may expose participants to extreme market risks. Plan sponsors could potentially improve retirement outcomes by trimming choices for stocks and considering additional options for bonds. The inclusion of active fixed income strategies with global exposure or additional income opportunities could help participants reach their retirement goals.
Commentary
Forecasting Bond Returns in the New Normal
PIMCO has a detailed framework for deriving a forecast for secular bond returns based on our most current expectations of policy rates and the inflation-adjusted (or real) bond risk premium.
We start by defining the expected secular real policy rate as the expected average rate of the fed funds rate after adjusting for inflation over the next 10 years.
Commentary
Forecasting Bond Returns in the New Normal
PIMCO has a detailed framework for deriving a forecast for secular bond returns based on our most current expectations of policy rates and the inflation-adjusted (or real) bond risk premium. We start by defining the expected secular real policy rate as the expected average rate of the fed funds rate after adjusting for inflation over the next 10 years.
Commentary
The Walk of Life: Stepping Away From Dire Straits and Toward Active Short-Term Mgmt Strategies
Money market investors may find the benefits of recent regulatory and industry reforms bittersweet at best, as they are still tolerating borderline zero percent yields in a persistent low rate environment. Without creative strategies for liquidity management, many investors are finding themselves in the "dire straits" of actual negative real returns on their cash allocations even with modest current levels of inflation.
Commentary
Global Volatility
The Fed's new communication strategy may, in fact, be a more sensible policy prescription than calendar rate guidance. We expect increased market volatility, particularly around economic data releases. Investors with an understanding of the Fed's now increasingly transparent reaction function will find opportunities to profit in the volatility markets. According to our model of the Feds reaction function, presently every .25 of a percent unexpected change in the unemployment rate is likely to lead to roughly an 11 basis point change in the five-year Treasury yield.
Commentary
Rational Temperance
While the market was indeed moving in the direction of "dot-com" fever three to four years later, the Dow Jones Industrial Average at the time was a relatively anorexic 6,000, and the trailing P/E ratio was only 12x. For a central bank that was then more concerned about economic growth and inflation as opposed to stock prices, risk spreads, and artificially suppressed interest rates, the Chairman's query made global headlines, became a book title for Professor Robert Shiller and a strategic beacon for portfolio managers thereafter.
Commentary
Love, Money or Disappointment: What Will Asian Credit Investors Find in Their Red Envelopes?
Our cyclical economic outlook for Asia in 2013 is unusually dependent on breakthroughs in structural policies. Although we continue to favor select opportunities in key sectors, in general Asian credit spreads are trading historically tight. Bottom-up research is critical, along with careful top-down views on shifting economic conditions, and investors need adequate compensation for taking credit risk. Some sectors and companies can grow significantly faster than their respective economies.
Commentary
Uncovering 'Diamonds in the Rough' in Today's Credit Markets
There are still good opportunities for yield and total return in the credit markets, but there has been a shift in where and how investors can find them. A "diamond in the rough" is a credit that is under-covered, or not actively followed or researched by many investors. At PIMCO, we identify these opportunities through our top-down and bottom-up investment process. We've identified a number of sectors that appear poised for above-average growth.
Commentary
Expanding the Toolkit for Monitoring Your Equity Managers
Investors may want to consider active share when assessing whether and how their active equity managers add value beyond a passive benchmark. The methods for monitoring investment managers are well established. But given the importance of getting portfolio allocation right in a low-growth, low-return world, it's worth examining new ways to assess risk and value added. While tracking error has been held as a key measure for active risk, it may include elements that reflect market conditions rather than managers' actual decisions on risk.
Commentary
The Squeeze: Reassessing the Japan/Korea/China Manufacturing Nexus
If the yen settles between 95 and 100 to the dollar, it could be a game changer for Japanese companies which have restructured to become profitable at 75 yen to the dollar. Some Korean companies, especially those in heavy industry, may be squeezed by intensified Japanese and Chinese competition. We expect Korean firms to fish in profit pools in businesses related to their core competencies, chiefly to the detriment of Asian and European competitors.
Commentary
Understanding Derivative Overlays, in All Their Forms
Passively managed overlays are typically based on a simple formula, while active approaches involve more complex algorithms or decision-making. Overlay examples include portable alpha, LDI, currency, completion, rebalancing, and tactical asset allocation overlays -- as well as tail-risk hedging and hedge fund replication. Potential benefits include the ability to effectively manage cash, reduce costs and risk exposure, simplify manager transitions and express tactical views.
Commentary
Unconventional Policies and Capital Flows
Although quantitative easing has grabbed the headlines, a number of central banks around the world have enacted other extraordinary measures in attempts to manage their economies. The Swiss National Bank (SNB), for example, adopted an exchange rate peg versus the euro while increasing its foreign exchange reserves to almost 80% of Swiss GDP.
Commentary
Feasting in a Time of Famine: The South African Consumer
South Africa's consumer sector has been on a strong run for the past several years, but there are signs the consumer is now coming under pressure. For all the challenges that have faced the South African economy, most listed consumer companies have enjoyed a great run since 2008. However, a combination of factors strong growth in retail sales and credit along with the rise in consumer debt levels and weak employment growth suggest the South African consumer sector may have pulled consumption forward in a way that could prove ultimately unsustainable.
Commentary
Credit Supernova!
They say that time is money. What they don't say is that money may be running out of time. There may be a natural evolution to our fractionally reserved credit system which characterizes modern global finance. Much like the universe, which began with a big bang nearly 14 billion years ago, but is expanding so rapidly that scientists predict it will all end in a "big freeze" trillions of years from now, our current monetary system seems to require perpetual expansion to maintain its existence.
Commentary
Pension Liabilities Time to Get Real
Creeping pension liabilities are an increasing concern for credit investors. Companies should provide more granular information on both sides of their pension balance sheets, as well as use more realistic assumptions. A few companies have improved their disclosures in recent years, but in general the information available to investors is still far from what we need.
Commentary
Searching for Growth in a Low-Growth World
We believe corporate profit growth will fall short of sell-side consensus estimates. But companies with inflation-linked revenues and supply side advantages to drive revenue growth, and those with ample cost levers to improve margins, are positioned for sustained earnings growth in the New Normal.
Commentary
Tail Risk Hedging: It Pays to Be Countercyclical
The cost of hedging in absolute terms is back to pre-crisis lows. Quiet markets, low volatility and a lack of visible risks on the horizon can lead to complacence and increasingly dangerous, leveraged positions. Many credit markets have been direct beneficiaries of the belief in seemingly lower tail risks in equity markets, and could also end up suffering if there is a re-emergence of widespread fear of, and upward repricing of, these tails. Investors should consider taking this opportunity to reload their hedges as soon as they can.
Commentary
PIMCO's Secular Forum Preview
It is almost time again for PIMCO's Secular Forum a critical part of the firm's investment process. This annual event, which takes place each May, brings together our investment professionals from around the world to debate and specify the key themes that we believe will affect the global economy and, consequently, our investment strategies over the next three to five years from asset allocation and relative value positioning to returns expectations and risk management.
Commentary
The Year Past, The Year Ahead
The multiyear run of performance by emerging market (EM) sovereign external debt has been remarkable but residual valuations look either just fair (investment grade) or expensive (high yield) versus other comparable credits. We still see abundant opportunities in EM local markets, while EM equities are poised to benefit from a relatively low starting point for both earnings and earnings expectations.
Commentary
The Year Past, The Year Ahead
While not immune to global economic headwinds, emerging market investments remain well positioned to outperform their developed world counterparts over time. The multiyear run of performance by emerging market (EM) sovereign external debt has been remarkable but residual valuations look either just fair (investment grade) or expensive (high yield) versus other comparable credits. We still see abundant opportunities in EM local markets, while EM equities are poised to benefit from a relatively low starting point for both earnings and earnings expectations.
Commentary
How the Platinum Coin Could Work (or Backfire)
The unusual move of minting a large platinum coin might shock politicians into cleaning up the fiscal mess. But the rest of the world may see it as inflationary.
Commentary
Ten Acts for Chairman Bernanke in January 2013
Federal Reserve Chairman Ben Bernankes term ends in January 2014, and it is unclear whether he will stay on for another. We expect Bernanke will muster every means he can over the next year to help the U.S. and indeed the world emerge from a gloomy time.Here, then, are 10 items we suggest for Ben Bernankes to-do list in 2013.
Commentary
From Cliff to Ceiling: No Clear Signal for Investors
We expect the last minute deal in the lame duck session to result in about 1.3% of GDP contraction, slightly less than our earlier prediction of about 1.5%. The compromise eliminated (or at least delayed) the possibility of the most damaging equity market outcomes. The deal failed to set up a framework for structural deficit reform in 2013. Almost immediately, Congress must address the debt ceiling, the sequester and the continuing resolution to keep the government funded.
Commentary
An Unconstrained Approach to Bond Market Investing
Investors are increasingly focused on alternatives to traditional investment strategies. Unconstrained bond portfolio construction should be driven by an outcome-oriented goal, with strategies assessed on an individual risk/reward and correlation basis, and each investment in the portfolio evaluated rigorously for the expected risk and return as well as the potential impact of the correlation to other investments in the portfolio.
Commentary
Money for Nothin' Writing Checks for Free
It was Milton Friedman, not Ben Bernanke, who first made reference to dropping money from helicopters in order to prevent deflation. Bernanke's now famous "helicopter speech" in 2002, however, was no less enthusiastically supportive of the concept. In it, he boldly previewed the almost unimaginable policy solutions that would follow the black swan financial meltdown in 2008.
Commentary
Rolling Tail Hedges: The Dynamic Tradeoff between Cost and Potency
In our hypothetical illustration, rebalancing tail risk hedges more frequently than once a year offers some benefit under all volatility curves (ignoring transaction costs) but the benefits are greatest when the volatility curve is flat or steep. Some of the benefits of rebalancing can quickly disappear if the transactions costs are large. Two key points for investors to consider: Hedging has to be a systematic, repeated, asset allocation decision to obtain best long-term benefits, and the hedge program has to be active and consider pricing levels so efficient rebalancing can be implemented.
Commentary
PIMCO's Cyclical Outlook for Asia: Awaiting the Policy Breakthrough
Our base case for China includes incremental policy reform, but we also see an increased chance of a potential positive surprise on reform, resulting from the recent changes in leadership. Japan's new government will likely focus on reflating the structurally impaired economy, but policy effectiveness will remain questionable. Australia is being burdened by the unintended consequences of the policy responses of others, accompanied by the impending rebalancing of the Chinese economy.
Commentary
PIMCO Cyclical Outlook for Europe: Policy Developments Will Shape Growth Prospects and Risks
Policy developments in particular, the European Central Banks acceptance of its role as a lender of last resort have helped to normalize European financial markets but been insufficient to promote decent growth. Eurozone leaders recently laid out a long-term roadmap to achieve stability, but the plan faces great execution risk, technically and politically, and in cross-border coordination. We continue to take a cautious approach and underweight European credit risk and European financials in general, looking for specific opportunities rather than broad exposure.
Commentary
Energy Face-Off: North American Energy Independence vs. Canada's Export Plans
President Obama's November 2011 postponement of a decision on whether to permit an oil pipeline from Canada's oil sands to the U.S. Gulf Coast caused a barrage of protests and negative press in Canada. Canada's new focus on building capacity to sell to Asia-Pacific could hinder U.S. ambitions of energy independence from overseas oil, since the U.S. imports roughly 30% of its crude oil from Canada. We see investor opportunities in rail transportation and pipeline systems that possess excess capacity.
Commentary
PIMCO Cyclical Outlook: At Policy Crossroads
The maturation of the global cyclical growth phase suggests we look to a handoff to more secular drivers of growth. But strong secular drivers remain elusive due to the continuation of New Normal headwinds.Policies are at important crossroads in every major economy. 2013 will be the year of policy change, with policymakers in major economies challenged to enact structural changes that spur private sector growth before government-balance-sheet-led growth is exhausted.
Commentary
Strawberry Fields Forever?
As John Lennon forewarned, it is getting harder to be someone, and harder to maintain the economic growth that investors have become accustomed to. The New Normal, like Strawberry Fields will take you down and lower your expectation of future asset returns. It may not last forever but it will be with us for a long, long time.
Commentary
The Bank of Canada Has Barked, But Will It Bite?
As Canadian consumers have increased their mortgage debt and bid up housing prices, the potential for a disorderly unwinding of these imbalances rightly concerns the Bank of Canada. PIMCO believes that the banks next policy move will be to raise interest rates, but with the traditional aim of fighting inflation rather than reducing home prices and consumer debt. We expect the Bank of Canada to continue tightening mortgage credit and using moral suasion to damp the housing boom and discourage consumers from taking on more debt.
Commentary
Deja Vu All Over Again
If the eurozone is to endure, it will require reduced economic differences among countries and larger common fiscal capacity. Emerging market central banks are likely to remain in wait-and-see mode while looking to the U.S. for clarity on the fiscal negotiations and domestic macro prints for signs of moderation in both inflation and activity. While central banks in advanced economies have not traditionally used explicit policies to target exchange rates, the European debt crisis may change all that.
Commentary
After the Election, Fiscal Cliff Outcome May Surprise
Our base case for a fiscal cliff resolution continues to be a lame-duck mini-deal that would reflect about 1.5% of GDP in fiscal contraction in 2013 (vs. nearly 5% without a deal). But the dynamics of polarization and partisanship that played a role in past dysfunctional negotiations may have gotten worse. On a more optimistic note, it is widely known that second-term presidents are largely interested in their legacies spearheading noteworthy, bipartisan and lasting accomplishments for the history books.
Commentary
What Would Happen at the Fed Under a Romney Presidency?
Between now and the election expect markets to continue to reflect the changing election probabilities. Expect Treasury yields to climb if Romneys probability of victory increases due to fear of what he will do when it comes to Fed nominations. However, any substantial rise in Treasury yields based upon a Romney victory is likely to be a buying opportunity, because Fed policy will be accommodative regardless of who controls the White House.
Commentary
Time To Vote!
So I pulled out my magic lamp that for some reason works only every October 22nd, and rubbed until the Genie appeared in his red and white checkered cloak with a 10-inch diameter Flavor Flav clock hanging ceremoniously around his neck. Being a rather forward, although not disrespectful Genie, he immediately said, "Mr. G, instead of the yield on the 10-year Treasury, perhaps this year you should wish to know who is going to win the Presidential election?"
Commentary
Muddling Down the Middle
PIMCO expects that the debate over the fiscal cliff will end in fiscal consolidation, but not a fiscal catastrophe. Unfortunately, while the Fed's monetary policy actions have been, by and large, successful in achieving its intermediate-term goal of increasing asset valuations, they have not been effective in influencing real economic outcomes. Our forecast for the drag on GDP from the fiscal cliff in the coming year is roughly negative 1.5%. Improvement in the housing market will only fill a small part in that hole.
Commentary
Blurring Lines: Positioning for Developed and Emerging Market Realignments
The demographic, financial and political lines separating developed and emerging countries are increasingly blurred, and we believe bond investors will need to adapt. Not only do investors need to take a more holistic approach to analyzing and investing in sovereign debt, they also need to reconsider their strategic thinking regarding benchmarks and their tactical approach to seeking returns. PIMCO Global Advantage Strategy utilizes a GDP-weighted benchmark and capitalizes on PIMCO's global resources to create a portfolio designed to reflect the evolving international opportunity set.
Commentary
Lender of Last Resort Move Crucial to Regional Stability
While the ECB's engagement as a lender of last resort is crucial, Europe's big four governments must provide political commitments supportive of ECB policy to counter the lingering threat of a Greek exit, address convertibility risk, and build a more stable union. However, this will require sustained growth. Faced with capital flights from the periphery and lowered credit ratings, the key challenge remains crowding-in private and foreign official investors to buy peripheral sovereign debt.
Commentary
Long/Short Investing: Bon Apptit
Long/short equity is a distinct investment approach that seeks to reduce downside risk while still capturing much of the equity markets upside potential. By removing the long-only constraint, long/short managers have an expanded opportunity set with the potential to generate returns and mitigate risk from both long and short investment ideas. Long/short equity strategies have a lower long-term volatility and risk profile than the market as a whole and have captured a good percentage of price movement in up markets and a smaller percentage in down markets.
Commentary
Inflation Regime Shifts: Implications for Asset Allocation
Investors who are concerned about inflation should focus on increasing their exposure to asset classes that provide a positive beta to changes in inflation. We believe that asset prices are much more sensitive to inflation surprises than actual inflation levels themselves. Given the current macro environment, investors face the possibility that low growth and high inflation may coexist. Commodities provide a levered response to inflation. Investors can hold a relatively small amount of commodities to hedge a much larger portfolio.
Commentary
The New TIPping Point
The Federal Reserve's QE3 program combined with more aggressive communication are likely to have implications for Treasury Inflation Protected Securities (TIPS).
Commentary
High Yield and Equities Mind the (Equity) Gap
High yield bonds returned 12% through September, even as corporate defaults continued to rise, albeit gradually. While the default rate is an important market metric, it has been a lagging indicator of high yield bond total return performance. Investors should closely monitor equity markets for signals on where high yield spreads may go.
Commentary
Keep up the pressure the US jobs crisis is not yet over
The monthly US employment report has evolved steadily: once a lagging indicator of the underlying state of the economy, it is now seen more as a leading indicator of economic, political and social trends. Friday's data tell us, for once, rather good news.
Commentary
Thrown in Over Their Heads: Understanding 401(k) Participant Risk Tolerance vs. Risk Capacity
Our analysis suggests as investors in target-date strategies near retirement they become more attuned to market swings. We believe 401(k) plans cannot succeed if participants jump out of markets at the bottom and possibly miss a rebound. Plans need to have tolerable downside risk, so participants can ride the market waves. The way to manage target-date assets, in our view, is to focus first on the risk capacity of participants relative to meeting an income goal. We ask, how much of one's final income will need to be replaced in retirement?
Commentary
Collective Action Clauses: No Panacea for Sovereign Debt Restructurings
Beginning next year, collective action clauses (CACs) will become mandatory for sovereign bonds issued by European countries under U.K. law. CACs, which allow a supermajority of bondholders to agree to changes in bond payment terms, became popular following Argentina's default in 2001 and even more so after the financial crisis of 2008. On balance, the introduction of CACs in European government bond markets in 2013 is positive for investors.
Commentary
Overtime, Then (not so) Sudden Death
The FDIC's unlimited insurance coverage on demand deposits is set to expire on December 31. While the expiration by itself might not be a game changer, it adds to the uncertainty that looms over liquidity strategies as global interest rates continue to be squeezed. We believe that actively managed short-term strategies that dynamically adjust to market conditions are viable solutions, with more attractive risk and return characteristics than money markets.
Commentary
Pottersville
The excessive use of debt fueled by money printing was the pathway to the global debt crisis. Fed Chairman Ben Bernanke, an expert on the Great Depression, understands the ravages of debt deflation and his every action has been to prevent it from occurring. Greater care must be taken in the future to ensure that our fiat based, fractional reserve system does not run amok. This is why regulators are demanding that banks raise capital, reduce their proprietary trading activities, and shift their business models closer to a utility-style model.
Commentary
Damages
How could the U.S. not be the first destination of global capital in search of safe (although historically low) prospective returns? Studies by the CBO, IMF and BIS (when averaged) suggest that we need to cut spending or raise taxes by 11% of GDP and rather quickly over the next five to 10 years. Unless we begin to close this gap, then the inevitable result will be that our debt/GDP ratio will continue to rise, the Fed would print money to pay for the deficiency, inflation would follow, and the dollar would inevitably decline.
Commentary
QE and the Equity Market: Is the Fed Driving or Along For the Ride?
Federal Reserve officials have said several times that among other benefits, its quantitative easing (QE) programs have helped boost U.S. equity prices. Based on our analysis, QE has not been the driving force behind rising equity prices in recent years. How does the Federal Reserve measure the success of its asset purchase programs, or quantitative easing (QE), since the 2008 financial crisis QE1, QE2, Operation Twist (OT) and QE3?
Commentary
Falling Off the Fiscal Cliff?
When we look at how the fiscal debate is likely to play out, rather than how it should play out, our base case is the fiscal cliff will likely be resolved in a short-term deal before the end of the year, making what was a cliff more like fiscal black diamond still dangerous, but not likely to land the economy in a body cast.
Commentary
No Free Lunch? The Real Impact of Lower Rates in Brazil
The Brazilian government wants to keep interest rates low but also guard against inflation; so the authorities have moved down a path of "macro-prudential" measures, with a broad range of implications for equity investors. In reality, as the cost of capital in Brazil falls, the returns and cash flows from regulated businesses are coming under pressure. In this environment, we find that consumer businesses are the most appealing, especially if growth accelerates.
Commentary
PIMCO'S Cyclical Outlook for Asia: Structural Slowdown Shaping Near-Term Growth Dynamics
Rather than a hard landing for China, we foresee a structural downshift that could be called a "New Normal with Chinese characteristics." Australia has considerable scope for additional rate cuts and more expansionary fiscal policy to address regional weaknesses. The Japanese economy will be affected by weak economic growth in China, which will add more pressure for the Bank of Japan to respond.
Commentary
The Volatility Risk Premium
Amid elevated global macroeconomic uncertainty and market turbulence, investors are searching for ways to diversify portfolios with non-traditional asset classes. Volatility risk premium strategies aim to capture a return premium over time as compensation for the risk of losses during sudden increases in market volatility. We believe investors seeking to diversify their equity risk exposures should consider adding volatility risk premium strategies to their portfolios, albeit with appropriate diversification across major option markets, active risk management and prudent scaling.
Commentary
The Cure for Baldness
Rarely does one find market commentators offering moderate, balanced investment advice these days. More likely one will find extreme headlines designed to capture maximum attention.
We believe it is worthwhile to take time to craft an investment strategy that can withstand a range of market outcomes.
In a lower-return world, we look to buy companies that are attractively priced and that can grow faster than the market as a whole, and we actively manage downside risks.
Commentary
Australias Second-largest Export It Isnt Coal
With growth in China now moderating, and the price of commodities and Australias terms of trade now declining, many investors are questioning how the Australian dollar has managed to remain well-supported. The explanation lies mainly in the changing structure of the funding of the current account deficit. Going forward this will likely have important implications for monetary policy in Australia if the decline in national income growth is not offset by a similar decline in the Australian dollar.
Commentary
PIMCO Cyclical Outlook: Building Rickety Bridges to Uncertain Outcomes
Without structural change aided by well-planned fiscal policy, we are afraid the nominal bridges of monetary policy will fail to reach their desired outcomes. The probability of a deflationary left-tail outcome emanating from the eurozone has declined substantially in the short run, yet outright economic growth in the eurozone will remain elusive in 2013.The much-publicized "fiscal cliff" is set to hit the U.S. economy on January 1, 2013, and could reduce U.S.
Commentary
The Lending Lindy
Our entire finance-based monetary system led by banks but typified by insurance companies, investment management firms and hedge funds as well is based on an acceptable level of carry and the expectation of earning it. In a New Normal economy where lenders dance to the Blue Danube instead of the Lindy, how should we move our own feet? Carefully, I suppose, and with recognition that historic returns are just that historic.
Commentary
The ESM: Saviour, Super SIV or End of the Road?
So long as the fundamental issues about the future of the eurozone remain unsolved, the extra supply of ESM bonds will likely drive up the borrowing costs of its weaker stakeholders. Without a cap on or exit clause from additional capital calls, the ESM could lead northern eurozone countries down a difficult and unsustainable path.
Commentary
Real Estate Resiliency: the REIT Model Proves its Mettle
REIT unsecured debt has been one of the best-performing sub-sectors in the entire investment-grade credit area. When insurance companies began to look at REIT unsecured debt, they asked for the same type of covenants associated with property-level mortgages. These requirements have coalesced into a standard REIT covenant package. We believe low default rates and relatively high recovery rates make the sector attractive over the long term particularly for buy-and-hold investors.
Commentary
'Japanification'
The same dark forces that Japan has been battling could continue to infect the developed world. During Japan's banking crisis deflationary expectations became embedded in the economy early on, preventing real short-term rates from remaining negative and thereby clogging monetary transmission. One of the chief explanations for the outbreak of deflation in Japan was the difference in the structure of the labor market.
Commentary
Europe's Unstable Hammock
This summer I have been asked a lot about Europe -- not so much by economists but by others concerned that the lingering crisis there would make their daily economic life even more challenging. In responding to these questions, I have often struggled to summarize in a few sentences the causes of Europe's existential crisis, let alone what is likely to occur next (including elements of a solution) -- that is until I tried to use a hammock.
Commentary
The Chinese Hangover: As Infrastructure Spending Drops, So Does Demand for Chinese Steel
The Chinese steel industry today shows many signs of serious economic difficulties brought about by the unprecedented size and speed of industry expansion. However, as the country's focus shifts away from public investments and toward tax cuts, it will be difficult for China to absorb this overabundance of domestically produced steel. Ripple effects of this oversupply may include softening iron ore prices, a possible drop in the Australian dollar, and potentially weaker global steel prices.
Commentary
The ECB Is Too Tight Absolutely and Relatively
Looking at measures of the quantity of money and its transmission into the real economy reveals that ECB policy is quite tight. Growth hardly stands a chance under this scenario. Relatively tight monetary policy would perhaps be understandable if the eurozone were threatened by inflation. However, inflation is low and falling in the Eurozone. The ECB may be playing a game of chicken with European policymakers. If true, this is a dangerous strategy.
Commentary
Preparing Portfolios for Inflation
Although disinflation has seemed the more likely scenario in recent years, PIMCO expects inflation to accelerate from recent levels over the next three to five years, but double-digit rates are unlikely. An understanding of the constituents of the Consumer Price Index can help us design portfolios that seek to better defend against inflation. The core building blocks of such portfolios are commodities, Real Estate Investment Trusts and Treasury Inflation-Protected Securities.
Commentary
A Second Wave of Capital Flight Reaches Eurozone Core
During the first phase of the euro crisis, private capital flowed out of the "peripheral" countries to the core of the eurozone, but this shift had no adverse impact on the euro. Now, investors are taking their capital out of the eurozone altogether. The euro threatens to fall further, possibly leading to serious concerns about a devaluation spiral.
Commentary
Diamonds in the Rough
The demand for most high-quality, income-producing assets continues to exceed supply due to a weaker growth outlook and aggressive policy action by global central banks. Yet we are still finding numerous opportunities globally through our bottom-up research that targets areas around the world where fundamentals are supportive and the outlook remains constructive.
Commentary
Remarks to the NBER-Sloan Conference on the European Crisis
We believe that this intersection between what economists and policymakers know - is a critical one to get right, and not only for a long-term investor like PIMCO. You see, unless there is a strong economic anchor, policymakers (and their political bosses) will lack the conviction and foundation needed to take difficult decisions and explain them well to citizens. So it is crucial for both sides to know what is known - and also to recognize, to the extent possible, the known unknowns.
Commentary
Cult Figures
The long-term history of inflation adjusted returns from stocks shows a persistent but recently fading 6.6% real return since 1912. The legitimate question that market analysts, government forecasters and pension consultants should answer is how that return can be duplicated in the future. Unfair though it may be, an investor should continue to expect an attempted inflationary solution in almost all developed economies over the next few years and even decades.
Commentary
What Next for Spain?
As part of its bank recapitalization program, Spain has ceded fiscal sovereignty, and this is a positive step toward resolving the euro debt crisis. We believe its eurozone partners should now make good on their summit agreement to use European Financial Stability Fund and European Stability Mechanism instruments in a flexible and efficient manner.
Commentary
The Longest Yard
As the global slowdown progresses, we can expect central banks to deploy more policy tools without limits to stem the pace of deleveraging. In Europe, quantitative easing using ESM bonds could prove to be another bridge that buys politicians more time, but does not solve the root problem. We expect real economic growth in China to be muted. While some stabilization is possible later this year, it is hard to foresee a sustained recovery.
Commentary
Equity Implications for a Modest-Return World
With equities likely to see modest returns over the secular horizon, we believe that capturing alpha will be critical for investors seeking to meet target portfolio returns. Equity valuations appear reasonable, but volatility is likely to remain elevated amid slowing global economic growth and macroeconomic risks. As macro events drive markets, the probability of fundamental mispricing increases, providing opportunity for active managers to add value.
Commentary
Secular Outlook: Implications for Investors
For investors, the biggest challenge now is moving from a world of normal distributions, with expected occurrences around the mean, to one of bi-modal distributions where more extreme scenarios prevail. Key institutions, including governments and central banks, were previously stabilizing forces but are now helping to accelerate underlying, destabilizing trends in the global economy and financial markets.
Commentary
Low Interest Rates Are Not Enough
Welcome to what could be called "GGIRC," the great global interest rate convergence whereby interest rates steadily converge to zero in many countries around the world, both advanced (other than the crisis European economies) and emerging (other than the persistent financial basket cases). In theory this is a good thing for a global economy. In practice, however, the situation is much more complicated and not so benign.
Commentary
One More Dance
We are witnessing a synchronized slowdown worldwide that is beginning to affect corporate profits. The most likely right-tail event is the Federal Reserve launching another round of quantitative easing. We dont believe liquidity alone can engineer sustainable, real economic growth in the context of a secular deleveraging cycle. But we acknowledge that equity portfolios would likely benefit should the Fed keep the music playing a little longer.
Commentary
The Upside of Low Interest Rates for Pension Plans: Issuing Debt to Fund Pension Liabilities
Issuing debt allows a sponsor to de-risk without waiting for market events or cash contributions to reach the level of funding that triggers a shift in asset allocation. There are a number of ways in which a sponsor may benefit from replacing inefficient debt (in the form of a pension deficit) with the tax and accounting advantages of marketable debt.
Commentary
Investing off the Beaten Track in an Uncertain Global Economy
The global economy remains in a multiyear period of global deleveraging; it will be an uncertain and, at times, volatile process. The substantial uncertainty and volatility affecting interrelationships across different markets are providing relative-value opportunities. Alternative strategies can be enticing, but the decision to use them needs to be fully informed and weighed against all the options.
Commentary
Europe Risk Preparedness
PIMCO's risk management process is dynamic and flexible, allowing us to evolve to understand, quantify and manage risks in broad scope and at the portfolio level. We are particularly focused on preparation for multiple potential scenarios, from a one-country redenomination to a full break-up of the eurozone into 17 separate currencies.
Commentary
Rethinking Asset Allocation
As risk and return characteristics evolve, we believe investors need to adapt the way they think about using asset classes. Asset classes are likely to be affected by the situation in Europe and, more broadly, by high debt levels in developed countries. The related political debate about austerity vs. growth is also critical. Fixed income investors should note whether countries control their own currencies and can monetize their debts. Those that can may be greater inflation risks.
Commentary
UK Perspectives: The Labour Market's Mixed Blessings
Although UK unemployment has held at a much lower level than in previous recessions, employment among workers under 25 has fallen significantly since 2008. There is already a whiff of stagflation about the UK economy, and we need to take steps to support youth employment before we end up with longer-term unemployed. In this environment, UK investors should seek inflation protection and exposure to countries and companies without stressed balance sheets or secular growth challenges.
Commentary
End Game: What Happens to Residential Mortgage-Backed Securities if There's a Eurozone Exit
An exit would substantially affect euro-denominated RMBS mortgage collateral. Currency redenomination and devaluation would likely wipe out the entire available credit enhancement for most deals. Losses of redenominated loans could overwhelm credit support, even for well-performing deals.
Commentary
Pretzel Logic
The primary pension-related change in the legislation is to give temporary funding relief by altering the discount rate used for liability valuation and represents the third such change in the past decade. The estimated revenue impact from lower minimum required contributions seems optimistic to us, and misses some fairly obvious costs. Congress essentially extended a welfare transfer from the Haves to the Have Nots.
Commentary
The Intersection of Monetary Policy and Volatility Markets
When the Fed exhausted the power of its traditional monetary policy tools, it turned to increasingly creative and innovative policy measures. During periods of Fed balance sheet expansion, both interest rate and equity implied volatility experienced significant declines. The opportunities presented by the intersection of monetary policy and volatility markets are often compelling, because most options market participants are not looking at the world through a policy lens.
Commentary
Equity Investing in a Lower-Return, Volatile World
Company balance sheets in developed markets are generally in good health and many are well positioned to generate growth even in difficult times.
We expect growth to moderate in emerging markets, although still outpace the trajectory in the developed world. Certain companies may temporarily face lower capacity utilization.
A focus on quality is invaluable. We define quality by clean balance sheets, high operating margins and access to high-growth markets with barriers to entry.
Commentary
Level Best
Craving instant information gratification, many of us spend much time trying to forecast and analyze short-term changes in economic data. Looking at the trends in the levels of economic data over a period of five to seven years provides refreshing insight and perspective on the economy that are often distorted by the daily data noise. Specifically, trends in the Consumer Price Index, the U.S. Dollar Index and real GDP reveal important insights about the economy, markets and policy.
Commentary
What's In A Name?
Not only banks and insurance companies but sovereign nations as well cannot all be counted on to guarantee a return of principal, let alone a return on investment. An authentic debt crisis which the world is now experiencing can only be ultimately cured in two ways: 1) default on it, or 2) print more money in order to inflate it away. There are very few clean dirty shirts in this world. Timing in investment markets is critical and at the moment the U.S. is considered to be the cleanest.
Commentary
U.S. Economic Outlook: Potential for Growth, Vulnerability to Policy Mistakes
There are very early signs of improvement in the housing market. Another plus is the shift in U.S. energy supply from imported oil to domestic oil and natural gas. The U.S. economy still faces significant headwinds from over-indebtedness, large imbalances, growing inequality and policy incrementalism. In our view, investors need to consider the implications of rising forward tax rates and that price inflation will play a greater role in generating nominal GDP growth than in the past.
Commentary
Focusing on Capital Preservation: Stable Value and Possible Alternatives
Stable value, which combines an actively managed fixed income portfolio with a contract to help assure principal and income, offers capital preservation potential and historically higher risk-adjusted returns than money market and low duration strategies.
Commentary
Emerging Markets Converge With the Developed World
We expect to see growth moderating in emerging economies over the secular horizon, but still outpace growth rates in Europe and the U.S. Emerging economies entered this period of global uncertainty with relatively clean balance sheets, reasonably high degrees of policy flexibility, and substantial dry powder in the form of international currency reserves. Emerging markets are likely to be affected by the considerable growth headwinds and uncertainty emanating from the developed world.
Commentary
U.S. High Yield: A Closer Look at Junk Spreads
Investors are cautious about high yield bonds which have become more volatile following strong performance and inflows earlier this year. We believe the cyclical bottom in default rates is behind us, and based on a tightening in lending standards compared to last year, we expect a gradual increase toward the mean in default rates and credit losses in 2012.
Commentary
Why Inflation Could Rise Over the Long Term
In developed markets, there is a serious debt problem, and inflation is one of the only "solutions" we see as likely to occur. We see a secular rise in global commodities prices, with some cyclical dips as the middle class expands in merging markets in the years ahead, consuming more commodities. Structuring portfolios in an attempt to guard against high inflation should be a central element of any investment strategy.
Commentary
Choosing the Right Asset Class in Emerging Markets: Why it Matters
Depending on individual risk tolerances during the past five years, it may have made more sense to overweight one or two EM asset classes and at times to avoid one or two EM asset classes altogether. In general, asset classes are better viewed as carriers of risks rather than each being considered a risk in its own right. This phenomenon is readily apparent in the emerging market space. We have advocated that asset allocation in EM should be dynamic with respect to both segment and country.
Commentary
U.S. Commercial Real Estate: A Technical Affair
We believe attractive investment opportunities will arise in sectors of CRE that haven't yet caught the eye of technicals-driven capital. Demand for CMBS arguably comes from a lack of alternatives as opposed to any sort of inherent belief in rental fundamentals. Fickle technical factors are not the only headwinds: Deleveraging, regulatory uncertainty and weak fundamentals add further pressure.
Commentary
Three Years and Counting
In addition to muted economic growth, record low interest rates, and sustained high unemployment, extraordinary equity market volatility has been a repeated feature of the past three years. As heightened volatility persists, many equity investors remain on the sidelines. We think a better investment approach is to invest globally, across asset classes, reflecting the likelihood of the various outcomes.
We believe managing against downside shocks is enormously beneficial to compounding attractive returns over the long term.
Commentary
Asia's Role in Global Economic and Portfolio Rebalancing
We expect that the reallocation of global investor portfolios toward more balanced allocations to emerging market bonds the Great Migration to support Asia in the coming years. To pivot to a growth model that emphasizes domestic demand, China must alter government policy on taxes, profits of state-owned enterprises as well as make other structural changes. Japans growth will continue to be challenged by secular dynamics, and by the countrys inability to respond to them.
Commentary
Time Running Out for European Credibility
Mondays disappointing market reception to the bailout package for Spanish banks is a reminder to European policymakers of something that is more than familiar to veteran sovereign crisis managers in emerging countries: The greater the erosion of policymaking credibility, the harder it is to get the private sector to buy into your plans. As a result, rather than crowd in private capital, seemingly bold policy measures end up facilitating its exit. The answer is not to do less but, rather, to be more comprehensive and coherent in what you do.
Commentary
The Purveyors of Notgeld
It is through this emergency money and repressively low interest rates that the worlds central banks create conditions that compel investors to seek out value in real assets and move outward along the risk spectrum. Investors should focus on assets that are likely to benefit from central bank policies designed to reflate deflated economies: commodities, land, equipment and software, for example. In equities, this means favoring entities in the developing world over those of the developed world in particular those reliably expected to pay a dividend.
Commentary
Remarks to the 12th Annual International Seminar on Policy Challenges for the Financial Sector
Let me start with what I will refrain from doing specifically, I will not pre-empt the detailed discussions that you may have on such topical issues as regulatory principles, SIFIs, market infrastructure, stress testing and, of course, the rapidly changing nature of sovereign risk in advanced countries. Instead, I will try to touch on three more general topics that, in addition to your critical detailed analysis, I believe are important in assessing the potential impact of regulatory reform in terms of the past, present and future.
Commentary
Liquidity Lessons: The Critical Importance of Budgeting for Overlay Strategies
One approach is to tier liquidity into current and contingent tiers, where some assets are kept in more liquid form and others are kept in higher-yielding investments. Quantifying how much of the immediate category is needed is a relatively straightforward risk-management exercise involving estimating the potential mark-to-market change in value of the overlay. Our view is that locating the liquidity pool internally has a number of potential advantages over an external model.
Commentary
Investors Position for a Synchronized Global Slowdown
The insufficient job creation, stagnant earnings and alarming long-term unemployment highlighted by Mays disheartening jobs report underscore Americas persistent unemployment crisis. The numbers also speak to a synchronized slowdown that is now taking hold of the global economy a phenomenon that is being signaled by virtually every other data release out of Europe, the U.S. and emerging countries.
Commentary
Tomorrows Europe
Our secular view is that the status quo is not an option for the eurozone. In the near term, we believe it is more likely than not that Greece will exit the eurozone. While a Greek exit would likely be messy and volatile, our baseline view is that a smaller union will persist. To be sustainable, it will have to be underpinned by much stronger fiscal union, greater support for the banking system, and mutualization of debt to mitigate cross-border capital flight risks.
Commentary
Snapshot on Spain: And the Money Keeps Rolling Out
The severity of the Spanish financial crisis can be most vividly seen through the balance of payments data. March data shows net financial inflows of 533 million, but that includes ECB funding for the Spanish banks. When excluding the ECB funding, i.e., mostly private sector flows, the data shows 66 billion in outflows. In the past 12 months, 193 billion in private capital has left Spain, a whopping 18% of GDP.
Commentary
Asset Allocation: Does Macro Matter? Part II
We see the conventional, valuation-based approach to asset allocation as akin to looking in the rearview mirror, which may lead to suboptimal investment outcomes when important macroeconomic shifts take place. We believe an econometric framework to assess the impact of shocks to GDP growth and inflation provides the missing link between macroeconomic forecasts and portfolio performance. Investors should constantly complement, review and revise qualitative and quantitative macroeconomic analyses with judgment, experience and a view on current events.
Commentary
The Global Industrial Sector: Have Profit Margins Peaked?
Factors driving profit margin expansion in the industrial sector include globalization, EM capital expenditures, a focus on profitability and global labour arbitrage.
Potential headwinds include a slowdown in global growth drivers, rising labour rates and global deleveraging.
We believe profit margins are most at risk in product areas where EM companies are benefiting from state capitalism and seek to take local advantages global.
Commentary
Wall Street Food Chain
Soaring debt/GDP ratios in previously sacrosanct AAA countries have made low cost funding increasingly a function of central banks as opposed to private market investors. Both the lower quality and lower yields of such previously sacrosanct debt represent a potential breaking point in our now 40-year-old global monetary system. Bond investors should favor quality and clean dirty shirt sovereigns (U.S., Mexico and Brazil), for example, as well as emphasize intermediate maturities that gradually shorten over the next few years.
Commentary
Delayed Entitlement: The Changing Economics of Retirement
Its a foregone conclusion that Baby Boomers retirements will be very different from the retirements of their parents. To understand how, we need to explore the impact of the most recent financial events on Baby Boomers. The conventional wisdom is that as the leading edge of Boomers converged on age 65, their associated retirements are well underway and the economic and societal effects of this demographic-driven, transfer-payment-promised contingent are just beginning. In the next three to five years we should face a rapid and unprecedented expansion of entitlement expenditures.
Commentary
Into the Great Unknown
Amid great uncertainty and huge challenges in Europe, it can be helpful to cut through all the detail and map out what we know and what we dont know. This is at best depressing and, at worst, terrifying. Taking together the known knowns and the known unknowns, it seems likely that the eurozones big four Germany, France, Italy and Spain as well as other German satellite countries will find a way to hang together in a smaller currency union backed by stronger regional co-ordination and financing mechanisms.
Commentary
Loss Capacity Drives 401(k) Investment Default Evaluation
Based on our research, we believe retirement plan participants capacity for loss may be much lower than many investment default options accept as tolerable.
Regardless of asset allocation structure, an investment default option should maximize the likelihood that each plan participant will meet his or her retirement income needs.
One of the keys to meeting a set income replacement goal is to understand how much plan participants can afford to lose at every age as they approach retirement.
Commentary
Why Invest in Asian Credit?
Asian sovereign and corporate credit offer more attractive yields than a number of other global fixed income sectors as investors take on additional risk. Given Asian markets diversity and the global macroeconomic environment, investors may wish to consider investment managers with a strong global macro process coupled with strong relationships with local stakeholders and experience in local portfolio management and markets.
Commentary
Goodbye Planet Rates, Hello Planet Quantity: Credit Markets in a Zero Rate World
There is a sense that developed market economies are somehow undergoing a reversed metamorphosis reverting from butterfly back to caterpillar where growth is crawling as opposed to flying. The fear of credit destruction, perhaps triggered by deflationary scares, becomes a bigger obsession for central banks. The culture of credit risk-taking changes as rates go lower and approach zero with a perennial risk of the economy tipping into deflation.
Commentary
Global Shipping: Any Port in a Storm?
With the exception of LNG tankers, all three major shipping categories have been suffering from a supply glut. This, combined with higher fuel costs, has led many shipping companies into financial distress. Although banks have worked with ship owners through this down cycle, they have also pulled back from financing the industry. We believe downside risks are likely minimized in the shipping industry for new lenders and investors. Vessel values are depressed by rates that are sometimes below owners' operating costs and by an oversupplied market that suppresses secondary market values.
Commentary
Avoiding a Cold Shower in the Cash Markets
A concern for investors would be to vigilantly monitor the global marketplace for any changes in the liquidity markets, reviewing aspects and conditions in both the unsecured and secured markets. The second source is the capital market participants themselves. Reduced or reallocated dealer balance sheets have led to wider bid-offer spreads in the marketplace. The final evolutionary condition to monitor is the regulatory environment in the U.S. The SEC and the Fed have recently become critics of the current structure of 2a-7 money market funds.
Commentary
Equity Investing: From Style Box to Global Unconstrained
PIMCO sees greater potential benefit to global portfolios in strategies that are unconstrained by a benchmark, and with managers who think about absolute return at least as much as they think about relative return. We believe the style box approach resulted in too great a focus on returns relative to a very narrow index and led investors to have too short of an investment time horizon in which to evaluate their managers, and that the cycles of style performance and the narrow benchmarks in the style box world encourages manager turnover and undermines long-term portfolio return potential.
Commentary
Policy Confusions & Inflection Points
During this important annual event, PIMCO colleagues from around the world debate the major trends that will play out over the next three to five years, focusing not on what should happen, but what is likely to happen. Based on the 2012 Secular Forum discussions, we expect three themes to play out: continued policy and political confusion, overly incremental public and private sector responses and, therefore, greater potential for inflection points. In terms of regions, the status quo is no longer an option for Europe.
Commentary
Brazil: Compelling Opportunities for the Long Term
Although economic growth has moderated somewhat in recent years, Brazils growth story remains compelling.
Underpinned by favorable GDP growth, Brazilian bank fundamentals are solid; banks are closely regulated and well-capitalized.
PIMCO believes several key corporate sectors oil, gas, utilities, infrastructure and major banks will dominate the outlook for Brazil over a secular horizon thanks to stronger pricing power and improved profitability.
Commentary
Benchmarking Tail Risk Management
While tail risk hedging is a critically important area of modern portfolio management practice, the relative newness of the area means standard frameworks for benchmarking such portfolios have not developed. In fact, weve found that once the framework for proper tail hedge construction is defined based on key guidelines (including exposures, attachment, cost, and basis risk), the task of creating a proper index becomes relatively straightforward. To compensate for insufficient real-time performance measurement, tail hedges need to be evaluated on the basis of scenario analysis.
Commentary
Going Global Can Pay Dividends
In todays low yield environment, many investors now include dividend-oriented equities in their portfolios in an effort to reach their income goals.
U.S. investors with home market bias risk severely limiting their income potential because in the U.S., dividend payout ratios are on the decline, taxes are potentially on the rise, and valuations in sectors that typically offer attractive dividends are near historical highs.
In our view, global equities can provide more attractive dividend income opportunities and offer potential for additional benefits, including diversification
Commentary
When Quality Pays: A Fundamental Approach to Pursuing Lower Risk and Higher Returns
Determining which fundamentals may lead to higher returns would give equity investors a useful tool for constructing portfolios.
Quality can be defined for equities by analyzing fundamental factors, such as operating margin, leverage (debt to equity ratio) and dividend yield.
The factors that define quality tend to lead to lower risk in individual equities.
As these fundamental factors in part lead to lower volatility, they may also lead to higher returns to the extent the stocks participate in the low volatility anomaly.
Commentary
European Elections Complicate Outlook
Markets will likely price in a larger risk premium following Sundays election outcomes on account of political uncertainty and the related range of specific risk factors, including greater concerns about creditworthiness and eurozone exit. This speaks, first and foremost, to the spreads of certain European sovereigns, with negative spillover effects on equities and other risk assets. Fortunately, there is a silver lining, though it will take some time. It comes in the form of a hope that the electorates message on Sunday will be interpreted by Europes leaders as a call for bold action.
Commentary
Back In
U.S. housing may be a decent place to put money over the next several years due to improved absolute and relative valuations. U.S. housing fundamentals have improved significantly, led by lower prices, record low mortgage rates, improving inventory and delinquency trends and a gradually improving labor market, which in combination are helping homebuyer confidence and potential demand. While the outlook for U.S. housing has improved, several headwinds remain, including tight credit, potential supply from the shadow inventory and weak household formation due to a subpar economic recovery.
Commentary
Watchful Waiting
Today, the Federal Reserve itself faces an unusually uncertain period because it lacks a complete understanding of the potential side effects of its unconventional policy actions; in particular the elongated timeline of its zero interest rate policy and its massive money printing. What matters in shaping market expectations about inflation and deflation are the credibility of fiscal policy, the prospect for real economic growth and the central banks commitment to step back from the punch bowl.
Commentary
Rethinking Best Practices for Bank Investment Portfolios
The turmoil in capital markets and changes in the regulatory environment have sparked changes in bank investment portfolios and caused many banks to reevaluate portfolio management practices. Banks without the resources to develop new processes may be forced to limit their investment opportunity set, possibly limiting earnings and diversification potential in the securities portfolio. The investment portfolio may represent an opportunity to improve bank revenues and risk-adjusted performance by expanding into investments with improved return and diversification potential.
Commentary
Wind Shear Avoidance: Why There Is Value in Momentum
Explicit tail hedges that look expensive in a normal world may indeed turn out to be cheap if the unimodal morphs into the bimodal.
When faced with bimodal outcomes, momentum as a risk factor becomes potent, and cost-efficient exposure to momentum becomes critical to proper portfolio construction.
In this world of low, pegged interest rates, an investor who is going to take risk needs other means to make the portfolio more inured to unforeseen shocks and market storms. Investors should look at effective alternative beta strategies, such as momentum, that can be implemented efficiently.
Commentary
Tuesday Never Comes
The current acceleration of credit via central bank policies will likely produce a positive rate of real economic growth this year for most developed countries, but the structural distortions brought about by zero bound interest rates will limit that growth and induce serious risks in future years. Gradually higher rates of inflation should be the result of QE policies and zero bound yields. Focus on securities with shorter durations bonds with maturities in the 5-year range and stocks paying dividends that offer 3%4% yields. Real assets/commodities should occupy an increasing percentage.
Commentary
TIPS for Value Investors: Whos Afraid of Negative Yields?
Why wasnt the recent TIPS auction a blockbuster among Main Street investors? We believe they were frightened away by the -1.08% real yield.
We would argue that the negative real yields that are explicit in TIPS also represent the implicit discount rate for ALL financial assets in the U.S.
Moving away from TIPS into nominal yield is a bet on inflation being less than 2% for the next five years and less than 2.25% for the next 10 years a pretty bold bet!
Commentary
The Shrinking Social Security Trust Fund: Are We Really Surprised?
If trends continue, it is quite possible that the OASI trust fund could run out of money in little more than a decade.
Over the past five years the exhaustion date of the OASI trust has been brought forward by eight years. We are heading in the wrong direction.
What is causing the shortfall? Setting aside the actuarial ps and qs, the core of the problem comes down to mortality, demographics and growth.
The most likely solution will be lower indexation of wage growth for benefit determination, delayed retirement for those set to retire in 10 or more years and higher taxes for everyone.
Commentary
Decoding Duration to Better Understand Your Portfolio
Duration is often used as a shorthand way to communicate the interest rate risk of a fixed income portfolio. We frequently encounter duration quotations presented as though no subtleties exist. These quotations average duration exposures across maturities and across currencies, implicitly assuming that yields across maturities and currencies are equally volatile and perfectly correlated. We approach the task of understanding interest rate risk with a more complete view of the risk dynamics driving interest rate sensitivity.
Commentary
Release Oil from the SPR? Better to Take the Long View
A temporary release aimed at influencing short-term prices could actually send an unintended bullish signal to the market that long-term spare capacity in OPEC producers is insufficient to meet supply losses. After the release of oil from the SPR in 2011 prices initially fell by 7%, but quickly rebounded as the market priced in the challenge of redelivering the oil to the SPR in the future. With few options, governments have limited ability to influence oil prices and so should focus instead on policies that impact the medium to long term.
Commentary
How European Politics Could Impact Markets
Fed up with how all the economic, financial and policy news out of Europe have been contributing to equity market volatility? Well, not only will this continue but, now, we must also get ready for something new over the next few weeks: the impact of elections. In addition to their consequential national impact, the series of forthcoming elections involve cross-border implications that influence prospects for regional policy coordination and, therefore, the nature and speed of the solutions for Europes debt crisis.
Commentary
Asia-Pacific Portfolio Committee on PIMCOs Cyclical Outlook
We do not expect to see aggressively expansionary policy to combat the incremental economic slowdown in China. We believe that most countries in emerging Asia will continue to put their currency appreciation on hold, as inflation is expected to remain subdued over the cyclical horizon.
We are concerned about the sustainability of Japans economic growth beyond 2012, as the governments reconstruction spending will fade in 2013. Relatively speaking, Australia is indeed a beneficiary of higher commodity prices as a result of the strong demand for coal, iron ore and liquid natural gas.
Commentary
The Elusive Equilibrium: How Financial Markets Shape Global Rebalancing
The mental and organizational infrastructure in the asset management industry has been built for a world with a sharp dichotomy between developed countries and emerging markets. Effective portfolio management requires an integrated approach that eschews the traditional dichotomy between developed and emerging markets. Emerging markets account for about 36% of global output and 68% of global GDP growth, but only represent about 4% of the equity portfolios of U.S. investors. We believe the representation in bond portfolios is even lower.
Commentary
What the Return of Market Volatility Tells Us
Signals of a challenging outlook are much louder in European bond markets. Last week, yields on peripheral government securities went from flashing orange to again flashing red, with Spanish risk spreads near or at record levels. All this speaks to the unsettling situation of markets that remain highly dependent on policymakers who, themselves, are stuck in the muddled middle: unable to deliver sustainable outcomes or to exit from their market interventions. This is the unfortunate reality of an "unusually uncertain" outlook, blunt policy tools, and a rather dysfunctional political context.
Commentary
Dutch Disease Lite in Australias Economy
Australia is probably more likely to feel the effects of an extended structural change in the economy as resources continue to be reallocated, rather than the effects of a full-fledged, but transitory, case of Dutch disease. China is Australias largest trading partner, and Chinas historical focus on infrastructure building has amplified the divergence in Australias two-speed economy. We believe Australias strong initial conditions should help ensure that Commonwealth Government Bonds remain one of the worlds cleanest dirty shirts for risk-averse investors.
Commentary
Evolution, Impact and Limitations of Unusual Central Bank Policy Activism
I will speak in a central bank and to central bankers about the role of their institutions particularly the Federal Reserve and the European Central Bank in todays highly complex, perplexing and historically unusual policymaking environment. I will go further and try to link actions to motivations. And, when it comes to implications, I will attempt to put forward questions and hypotheses that, I believe, are critical for the future of the U.S. and global economies but for which I, like others, have only partial answers.
Commentary
Newtonian Profits
Today many equity investors are asking whether corporate profit margins can stay strong. Stock prices today are anchored on strong profits, hence investors intense focus on the sustainability of those profits. If they fall, stock prices are likely to follow. No doubt individual companies and sectors will face margin pressure. But for the equity market as a whole, our central scenario is for corporate margins to remain strong in the near future. We are buying individual companies we like based on our analysis of their own fundamentals in the context of the economic environment they are in.
Commentary
Emerging Market Rates: A Different Cycle
The business cycle in EM has been conducive to easing policy rates. Global growth decelerated noticeably in the second half of 2011, and this included most EM economies. While we expect EM local rates will move higher again as the business cycle progresses, the cyclical highs will likely be lower than the previous highs, reinforcing the secular trend towards lower rates. We like EM local rates with a strong credit quality, steep local curves and high real rates that may offer compensation for taking inflation risks. The local markets of Brazil, Mexico and South Africa all stand out.
Commentary
Global Equities: Building a Research Mosaic for the Information Age
As a result of increasing correlations across the globe, identifying the best global franchise opportunities at attractive valuations is becoming increasingly important. We believe that taking a broader global perspective and comparing a companys valuation and growth outlook versus their global competitors is just as germane as looking at them relative to their country or region. Identifying Chinese and non-Chinese companies that will gain and lose in this process is a critical long-term challenge when constructing a global portfolio and not an easy one.
Commentary
Markets Wake Up to Central Banks' Complicated Tradeoffs
This week's market action serves as a vivid reminder of how dependent valuations are on central bank policies, and especially the aggressive provision of liquidity by the Fed and the ECB. The question for markets thus boils down to whether central banks will do more; and the issues these institutions face are extremely and increasingly complex. The global sell-off started on Tuesday with the release of the minutes of the most recent FOMC meeting. They were read by many as signaling less eagerness on the part of the Fed to embark on yet another round of liquidity injections.
Commentary
Beyond Bonds: The Role of Risk Assets in Liability-Driven Investing
In liability-driven investing, unless the plan is fully immunized or significant leverage is employed, the bond portfolio only hedges part of the liabilities. Overall, when diversifying across risk assets, there are choices that may be more attractive to pension plans than they are to liability-agnostic investors, such as risk assets with exposure to duration. Plan sponsors who choose to maintain a short duration stance on a total portfolio basis should consider alternative sources of diversification beyond equities.
Commentary
To QE or Not to QE
If the Fed does nothing, asset prices could fall, threatening Americas fragile economic recovery. But if the Fed decides to battle the forces of deleveraging, it could commit a classic error by acting during a turning point and thereby doing too much. During Operation Twist, the Fed will absorb the equivalent of all of the issuance of U.S. Treasury securities maturing beyond seven years. When Operation Twist ends, global investors will be left to shoulder the burden.
Commentary
Auctions Never Fail!
The increase in volatility can reach a breaking point when dealers are no longer willing to absorb risk and the issuer loses market access, irrespective of whether an auction fails or not. Individual countries are working to regain credibility and address their debt-sustainability but what is needed is an explicit collective commitment towards fiscal union. Catalysts for uncertainty may only be a few weeks away with the elections in Greece, France and a referendum in Ireland looming. Foreign investors who preferred to remain on the sidelines during the rally may reappear as sellers.
Commentary
The Great Escape: Delivering in a Delevering World
When interest rates cannot be lowered further or risk spreads significantly compressed, the momentum begins to shift, gradually yields moving mildly higher and spreads stabilizing or moving slightly wider. In such a mildly reflating world, unless you want to earn an inflation-adjusted return of minus 2%-3% as offered by Treasury bills, then you must take risk in some form. We favor high quality, shorter duration and inflation-protected bonds; dividend paying stocks with a preference for developing over developed markets; and inflation-sensitive, supply-constrained commodity products.
Commentary
Regulated Energy: Rise and Shine
Regulated energy companies natural gas pipes, gas utilities and electric utilities have generally been seen as the sleepy cousins of more exciting energy subsectors like exploration and production, or coal extraction and production. But we have witnessed a number of events and regulatory developments in recent years that we believe are re-energizing the regulated energy subsector, more clearly distinguishing it from other members of the energy sector family and providing the potential for an abundance of opportunity for astute investors.
Commentary
Transmission Channels
We believe the European debt crisis will likely flare up again, and equity investors should consider positioning portfolios to be more resilient against such a shock. A disorderly Greek default, if it occurs, would likely shock the eurozone and the globe via at least four transmission channels: the European banking system, European sovereign debt markets, corporate financing markets and regional trade. The shock of a massive Greek default would likely swing investor sentiment strongly toward risk off, putting pressure on equity markets globally.
Commentary
Western Medicine
Liquidity is buying time for European countries, but their economies are growing too slowly to support their debt loads. Just as there is no reason to assume U.S. household debt levels will continue to climb, there is also no reason to assume companies that benefitted from that debt-fueled spending will grow at historical rates. Until we see sustainable, real economic growth in America, we believe equity investors should carefully scrutinize the assumptions underlying consumer discretionary stocks and consider global companies that are selling into higher growth markets.
Commentary
Andrew Balls Discusses PIMCO's European Cyclical Outlook
The ECBs intervention has helped the European system undergo a slower and more orderly deleveraging process but it does not deal with the twin underlying problems of too little growth and too much debt in the countries at the center of the crisis. The eurozone faces a daunting set of challenges, including technical and economic challenges but highest on the list are politics and coordination. Greeces potential exit from the eurozone remains a significant risk and one that could lead to contagion across the eurozone as investors reassess the potential currency risk.
Commentary
You Can No Longer Say Corporates Without EM
In our view, the risk profile for EM corporates has improved thanks to stronger sovereign balance sheets and economic growth prospects compared with developed markets. While EM corporates generally have not garnered as much attention as sovereigns, PIMCO expects that significantly more assets will be managed against an EM corporate bond index this year. The road ahead for risk assets may be bumpy. But PIMCO believes the case for focused EM corporate bond investing remains compelling based on improved credit fundamentals, a solid macro backdrop, and potentially attractive yields.
Commentary
Investment Management with a Conscience
Earlier this year the Financial Times ran a series of editorials under the title Capitalism in Crisis. Contributors ranged from Bill Clinton and Alan Greenspan to FT editors Martin Wolf and John Kay. There was also a submission with the byline, Occupy London. While I am admittedly unable to add much to their collective wisdom, I think a sound analysis of capitalism requires an understanding of the role of the investment management industry within the financial services ecosystem."
Commentary
Systemic Risk, Multiple Equilibria and Market Dynamics What You Need to Know and Why
In assessing the possibility, duration and impact of systemic risk factors, we need to analyze the interaction of expectations with market (endogenous) and policy (exogenous) circuit breakers.
In the current environment, the prevalence of some subjective bimodal expectation distributions (e.g. Europe related) speaks to the multiple equilibrium features of sovereign debt markets.
Multiple equilibria give rise to a range of scenarios, each quite different and each with its own distribution of returns, risks, correlations, and market functioning.
Commentary
PIMCO Cyclical Outlook: Navigating the Hurricane of Global Deleveraging
We expect the eurozone economy to experience a recession in 2012 on the back of continuing pro-cyclical fiscal austerity measures. We expect 2012 to be the year in which the residential construction sector begins to gradually contribute to U.S. economic growth after a long and painful five-year hiatus. Major emerging market economies are struggling with domestic over-investment, rising income inequalities and inflation risks. Therefore, PIMCO expects major emerging market economies to be less of a global engine of growth in 2012-13.
Commentary
Remarks at the Launch of USAIDs Policy on Gender Equality and Women Empowerment
Many of us have a responsibility, indeed an obligation, to do whatever we can to ensure that both conscious and unconscious biases are better identified and minimized. This is a multi-year, multi-faceted effort. As illustrated by the USAID policy, it involves research, education, advocacy and action; as well as measurement, accountability and mid-course corrections. For all these reasons, we admire the important work being done on gender equality and the empowerment of women. We strongly endorse the importance of greater and equal opportunities.
Commentary
U.S. Covered Bonds: Reassessing Credit Risk and Relative Valuations
We believe nominal spread analysis is insufficient, since investors must now consider recovery and default risk under various economic conditions.
Our factor-based approach provides a means to quantify default probabilities across a range of outcomes instead of analyst-defined ad hoc assumptions.
We also investigate historical CDS spreads as a means to quantify default risk relative to national home price appreciation.
The potential for an emerging U.S. issuer market, combined with ongoing foreign issuance, leads us to believe the U.S. covered bond market has viability.
Commentary
Beyond Risk-on/Risk-off: Paying Heed to Peripheral Cues in Portfolio Construction
The availability of high-frequency information, technological advances in electronic trading and the dominance of government and regulatory policy factors made the world since the crisis of 2008 a risk-on/risk-off environment. In January 2012, S&P 500 implied correlations began to fall. It appears that stocks are beginning to take a bit more of their individuality back so that other assets dont move in lock step. Investors may benefit from a focus on policymakers, relative value opportunities, hedging potential left tail events, and diversification.
Commentary
TARGET2: A Channel for Europe's Capital Flight
The Eurosystem's TARGET2 transaction system introduces elements of fiscal union via the back door. The large TARGET 2 positions developing among national central banks in the eurozone reflect capital flight from the periphery to the core and de facto introduce transfer and burden sharing elements of a common fiscal policy. Monetary policy ends up substituting for fiscal policy without going through the same democratic channels that governments' expenditure and taxation decisions entail. Taxpayers in the eurozone are contingently liable for losses incurred by monetary policy operations.
Commentary
Positioning Your Portfolio When You Dont Have All the Answers
Faced with difficult questions like the European debt crisis, portfolio managers have two possible courses of action: feign omniscience and seek to position portfolios for one outcome, or admit to not knowing the answer and seek to position portfolios to prosper in the most likely scenarios and hold ground in the least.
We believe the latter is the better course because two extreme outcomes appear increasingly likely for almost all asset classes, which increases the risk involved in choosing the wrong answer.
Commentary
Credit Counts: The New Municipal Bond Market
Today, the primary emphasis in security selection must be placed upon creditworthiness and the relative value of credit spreads. When the spread on a bond more than compensates an investor for its underlying risks, the bond becomes an attractive candidate, PIMCO believes. Investors with the resources and process in place to conduct proprietary credit research may have a strong competitive advantage.
Commentary
De-Fence
Over the past 30 years, an offensively minded Federal Reserve and their global counterparts were printing money, lowering yields and bringing forward a false sense of monetary wealth.
Successful investing in a deleveraging, low interest rate environment will require defensive in addition to offensive skills.
The PIMCO defensive strategy playbook: Recognize zero bound limits and systemic debt risk in global financial markets. Accept financial repression but avoid its impact when and where possible. Emphasize income we believe to be relatively reliable/safe; seek consistent alpha.
Commentary
Game Changer
In addition to strong secular tailwinds supporting the energy sector, highly expansionary global monetary policies from many central banks are adding cyclical support to globally traded commodities like oil.
In the U.S. energy sector, we believe that onshore natural gas shale and oil shale developments are creating opportunities to invest in energy companies that may grow significantly faster than the overall U.S. economy.
Commentary
PIMCO
Given the bimodal nature of the expected distribution of outcomes, it is important for investors to remain nimble so they can respond to high frequency data and global public policy developments.
We expect the Bank of Canada to remain in wait-and-see mode until it is clear which way the economy is tipping.
In our base case scenario, we estimate Canadian bond market returns in the range of 2%-4%, and if we tip into a virtuous cycle of economic recovery, we anticipate the possibility of negative absolute returns.
Commentary
Rethinking Risk: Pension Plans Should Adjust to Global Realities
Many governments are carrying higher levels of debt, which can increase both economic and asset volatility as well as default risk.
The resulting incremental increase in default risk suggests pension portfolios may have less duration than implied by traditional measures.
Pension plans with high levels of equity exposure should consider increasing durations and credit exposure.
Investment guidelines may need to be adjusted so they dont measure credit risk simply by the World Banks definition of emerging markets.
Commentary
Something Old, Something New, Something Borrowed and Something 2
Given the Feds targets for both inflation and long-run normal employment, the new framework suggests continued lower bound rates, forward guidance and potentially additional QE. The Fed explicitly extended the length of time that it expects interest rates to remain exceptionally low and kept the door open to adjusting at a future meeting the size and composition of its balance sheet. The Fed reached unanimous agreement on a published numerical inflation target of 2% that, in its judgment, best satisfies its mandate to achieve price stability.
Commentary
From Argentina to Athens?
There are way too many discomforting similarities between what has been happening in Greece recently and Argentinas 2001 path to economic and financial turmoil.
Unless Greek and European officials reflect on key lessons from Argentina's experience back then, the parallels could also end up including a financial meltdown, a deep output collapse, and social and political turmoil.
Greece need not and should not - continue to follow Argentinas example of eleven years ago.
Commentary
Western Medicine
Liquidity is buying time for European countries, but their economies are growing too slowly to support their debt loads. In the U.S., household debt is declining, but remains high. There is also no reason to assume companies that benefitted from that debt-fueled spending will grow at historical rates. Until we see sustainable, real economic growth in America, we believe equity investors should carefully scrutinize the assumptions underlying consumer discretionary stocks and consider global companies that are selling into higher growth markets.
Commentary
Inflation Outlook 2012: Benign, But Watch the Tails
Headline inflation, as measured by the Consumer Price Index (CPI) in the U.S., ran at 3.0% in 2011, up from 1.5% for 2010.
Our base case is for inflation to moderate this year, heading to slightly below 2%. Longer term our bias is toward higher inflation, and we feel any deflationary episode is likely to be short-lived.
Faced with this possibility of higher inflation, many investors may need to examine their allocations to assets associated with real return potential, including Treasury Inflation-Protected Securities (TIPS), real estate, commodities and equities.
Commentary
Notes from the CES: As Old Tech Tries to Stay Relevant, Investors Need to Be Careful
Revenue growth rates at many large investment grade technology companies have declined in recent years while debt issuance has risen, in part because of nearly full market penetration in certain high-tech products but also due to less innovation.
PIMCO is very selective in the investment grade tech sector, favoring companies with strong and growing patent portfolios in areas of secular growth, strong free cash flow generation and low leverage.
Commentary
Still Losing the War on Unemployment
The first Friday of every month, you will find me among those eagerly waiting for the release of the latest government data on jobs. Such eagerness, however, should not be confused with joyfulness. While the numbers have markedly improved over the past year, too much of the commentary has been overly partial and, sometimes, dangerously misleading a situation that is likely to grow worse in the run-up to the November elections.
Commentary
Investment Management in the Age of Austerity
The broader financial industry is in a state of contraction, and the primary drivers of investment management revenue have become less reliable.
Higher volatility and lower returns have fundamentally changed the relationship between investors and the managers to whom they entrust their wealth. We are all being held to a higher standard.
We believe those investment management firms that can adapt and absorb these profound changes will come out ahead and will be best prepared to deliver value to their clients.
Commentary
Life and Death Proposition
When interest rates approach zero they may transition from historically stimulative to potentially destimulative/regressive influences. Recent central bank behavior, including that of the U.S. Fed, provides assurances that short/intermediate yields will not change, and therefore bond prices are not likely threatened on the downside. Most short to intermediate Treasury yields are dangerously close to the zero-bound which imply limited potential room, if any, for price appreciation. We can't put $100 trillion of credit in a system-wide mattress, but we can move in that direction by delevering.
Commentary
Investment Opportunities in the Changing Cash and Short Duration Markets
Volatility has soared in the cash markets as the eurozone crisis has deepened, prompting many investors to pull cash out of prime money market strategies over the last year.
With U.S. interest rates on hold until 2014 and regulations on 2a-7 money market strategies putting pressure on yields, cash investors will likely face near-zero yields for several years.
In this environment, we believe investors should reassess their liquidity needs and consider putting cash that is not needed right away into short and low duration instruments instead of money market strategies.
Commentary
To Fight or Not to Fight the Worlds Central Banks
We are skeptical that fiscal austerity alone is sufficient for all eurozone countries to grow and remain solvent. We thus expect the ECB to continue supporting the euro area with liquidity in 2012.
Recent central bank policy in China is oriented toward stabilizing growth in a political succession year, while balancing lingering inflation and medium-term systemic risks.
Investors may want to hedge portfolios by looking to select emerging markets with the ability and willingness to cut policy rates both from a cyclical as well as structural perspective.
Commentary
Tide Turns for Structured Credit
Many investors remain skeptical, but the market environment for structured products has changed markedly since the financial crisis of 2008.
Current pricing now reflects a more realistic view of the underlying fundamentals, including weakness in the global economy and U.S. housing market.
We believe now is the time to consider entering the structured credit market.
Commentary
TIPS for Financial Repression
Treasury Inflation-Protected Securities got a boost last week after the Fed extended the period of time it is likely to maintain unusually easy monetary policy and moved toward adopting a formal inflation target of 2% for the Personal Consumption Expenditure Index. Bernanke said that the central bank was likely to allow deviations from this target if employment was not where the Fed thinks it should be. We think financial repression is likely to persist and real interest rates are likely to be lower than recent history would suggest for the foreseeable future.
Commentary
Questions and Answers About S&Ps European Downgrades
Sovereign downgrades will likely be another trigger for cuts in the ratings of European banks. Nearly all major eurozone banks are on negative watch.
Even those securities guaranteed by eurozone sovereigns that were not downgraded are also in the ratings agencies crosshairs.
The most significant downgrade for benchmark compositions was Portugal -- downgraded to below investment grade by S&P, consistent with Moodys and Fitch.
Commentary
Riding the Global Roller Coaster: The Outlook for Emerging Markets High Yield Corporates in 2012
Because many emerging market high yield companies were able to deleverage after the 2008/2009 crisis, we believe they are generally in a stronger position than their developed market counterparts.
Limited financing needs should provide technical support to the overall emerging markets corporate market.
In an environment where lending conditions tighten in international capital markets, domestic markets may become a source of funding for EM HY corporates.
Commentary
Asia-Pacific Portfolio Managers Discuss PIMCOs Cyclical Outlook
We expect emerging Asia growth below the market consensus due to its less aggressive policy responses compared to 2008-2009.
The Asia-Pacific region is less affected than others by eurozone turmoil but contagion is still a risk through direct trade and the regional production chains that characterize Asias export-oriented economies.
In this environment, we favor Australian government bonds for their high credit quality, low-beta currencies such as the Chinese yuan, corporate issuers that have delevered, covered bonds and mortgage-backed securities.
Commentary
The Mess That Is the Eurozone Inflation-Linked Bond Market
Italian ILBs now mostly reflect credit risk and tend to trade at a discount to compensate for the higher volatility. Unless the eurozone collectively decides to inflate their way out of their sovereign debt problems through a large increase in the ECB balance sheet, Italian inflation-linked bonds are likely to keep trading like a more volatile and less liquid version of nominal Italian bonds. A European investor looking to secure consumption of real assets in the future may wish to think about alternative measures to help protect their real purchasing power when hedging real liabilities.
Commentary
Thinking About the Implications of Rising Euro-Exit Risks
Even if the euro survives this crisis intact, the market will price in uncertainty as the crisis evolves. Scenario planning is indispensable for investors.
Politics may prevent the European Central Bank from buying government bonds, but it could provide funding support via a special government or banking intermediary. This balance sheet expansion could be a negative for the euro.
Within the eurozone we believe investors should look at alternatives to the government sector, including agency, regional government and covered bonds.
Commentary
Do Friday's European Downgrades Matter?
Friday's downgrades of European sovereign ratings debt is all over the place-from those dismissing it as old news to those viewing it as part of a larger and consequential transformation of the international monetary system. What follows is an attempt to provide a guide to the multi-faceted implications. It focuses on three types of consequences: 1 those that are unambiguous and already reflected, albeit not fully, in market valuations. 2 those that are less well understood but will become clearer. 3 those that are consequential but where the analytics are still largely unknown at present.
Commentary
Chaos Theory
How developed nations address their fiscal deficits will have broad implications for equity markets. Debating a future of inflation vs. deflation is radically new territory for investors. The chaotic nature of the choice facing societies is whipsawing equity markets and dominating bottom-up factors. Equity investors seem to be pricing in a combination of outcomes, with the largest weighting going to a goldilocks, mild inflation scenario. But the markets large daily swings reflect jumps back and forth as investors update the probabilities of very different destinations.
Commentary
Macro Matters: Incorporating Top-Down Views in Emerging Market Equities
From 2003 to 2011, over 50% of returns of the MSCI Emerging Markets Index came from country-related and currency-related factors.
Over the next 12 months, there will be elections in countries representing just under half of global GDP. Therefore, we expect more policy experimentation, varying degrees of effectiveness, and unintended consequences.
Currencies are also an important driver of EM equity returns, and the cost of hedging currencies has meaningfully declined over time.
Commentary
Stock Volatility: Not What You Might Think
Contrary to finance theory, lower risk appears to produce the potential for higher returns over the long term.
Volatility tends to amplify stock returns so higher risk generally leads to higher returns in a positive market and greater losses in a negative market.
Over the long run, lower volatility stocks can lead to higher returns because avoiding the downside can have powerful effects on compounding.
Higher volatility stocks tend to fit the definition of speculative, while low volatility stocks can offer the potential for preservation of principal and a satisfactory risk-adjusted return.
Commentary
Towards the Paranormal
The New Normal, previously believed to be bell-shaped and thin-tailed in its depiction of growth probability and financial market outcomes, appears to be morphing into a world of fat-tailed, almost bimodal outcomes.
A new duality credit and zero-bound interest rate risk, characterizes the financial markets of 2012, offering the fat left-tailed possibility of unforeseen policy delevering or the fat right-tailed possibility of central bank inflationary expansion. Until the outcome becomes clear, investors should consider ways to hedge their bets.
Commentary
Delayed LDI Implementation: Making it Worth Your While
With interest rates so low, many defined benefit plan sponsors have delayed implementing or expanding LDI programs, often using intermediate duration bond portfolios instead.
Traditional intermediate duration portfolios may not offer the most attractive yields or the best credit match for pension liabilities, and may make the transition to long-term bonds difficult later.
We believe plan sponsors in a waiting mode should consider switching to long duration portfolios with a synthetic overlay in an effort to reduce duration exposure.
Commentary
PIMCOs Scott Mather Discusses the Global Implications of the Eurozone Crisis
The ECB does not want to be a bridge to an unsustainable and adverse economic destination. They would rather force politicians to address the critical problems of the currency union now.
Greece will continue to have an unsustainable debt load until policymakers can come up with a credible plan to generate economic growth.
Ultimately, the eurozone countries and many other developed economies have very similar problems: unsustainably rising debt loads coupled with structurally weak and imbalanced growth.
Commentary
Hot Potato
The world is playing a game of hot potato with European financial assets, and the European Central Bank is a reluctant player. Together, Europes fiscal and monetary authorities can likely avert a systemic accident, but they must act quickly and courageously. Differentiation among emerging market monetary policies is increasing. And in Australia, the central bank will likely need to ease further in 2012. If every central bank enacts similar monetary policy tools, those tools compete for the same targets (financial and inflation stability), thereby potentially eroding their effectiveness.
Commentary
The Three Rs of Investing
The inability to achieve sustainable levels of economic growth raises the risk of recession in many developed world economies. Under financial repression, market interest rates are kept very low for a very long time period with the hope of stimulating investment, but repression also starves savers to the benefit of borrowers. Increasing risk with an uncertain distribution of possible outcomes should lead to caution regarding traditional models and asset allocation practices.
Commentary
Downward Spiral
Europe's crisis is morphing again -- for the third time in only 12 months -- and the implications for the global economy are even more complex, unsettling, and troubling.
Commentary
Asset Allocation and Risk Management in a Bimodal World
Fat tails and negative skewness in the distribution curve can arise from the mere possibility of multiple equilibriaeven if both individually appear normal. Once markets arrive at a resting place among different equilibria, they tend to become trapped due to a variety of restraining forces. For all these reasons, we believe that the core building blocks of asset allocation and option pricing in the current macroeconomic environment should allow for the possibility of multimodality. This significantly changes the conceptual approach towards portfolio construction and risk management.
Commentary
Rethinking Asset Allocation: PIMCOs Strategy for a Changing World
Alpha generation is a distinct component of the strategy because it is critical to actively seek opportunities in all global markets in this challenging environment.
Explicit tail risk hedging is essential to prepare for more frequent significant downturns, both to mitigate their effects and to potentially benefit from them.
The strategy is positioned to navigate a world of muted growth in the Western economies, significant market volatility, recurring balance sheet issues and continued income and wealth convergence of the emerging world with the developed world.
Commentary
Neither a Quick nor Comprehensive European Fix
European leaders still need to do a lot more, and quickly, if they are to catch up and get ahead of the crisis. Accordingly, and regrettably, the specter of volatility caused by European headlines will not recede for long. Investors need to continue to watch and worry about Europe.
Commentary
Emerging Markets Bonds and Currencies in an Uncertain World
Even if global risk deteriorates significantly, emerging markets may continue to offer compelling risk-adjusted return characteristics. Emerging markets external sovereign debt, along with receiving interest rates in higher-quality EM countries, could be the best relative performers. EM currencies would likely sell off sharply in risk-off periods but would also tend to rebound robustly when risk appetite returns. Several Asian currencies are likely to be the best relative performers. Emerging markets assets remain a risk asset class and will not be immune to waves of global jitters.
Commentary
After the Flood: Surviving in a Sea of Debt
Since 2009, developed country governments have run fiscal deficits unprecedented outside of wartime, and their debt levels have reached epic heights. Investors accustomed to considering only the interest rate risk associated with their developed government bond holdings have been shocked to find that credit risk has become dominant in many cases. For investors in government bonds, inflation and currency debasement have the potential to be just as costly as outright default. Investors should consider focusing on GDP, or national income, as a measure of a countrys ability to service its debt.
Commentary
Waiting for All In
Without a more forceful and coordinated policy response, Europe now faces an increasing risk of a hard landing. In this uncertain environment, volatility will likely remain high, liquidity poor, risk premiums wide and the global economy fragile as financial and credit conditions tighten. Easier monetary policy as well as the potential for more balance sheet support from a larger consortium of global central banks is now needed over our cyclical horizon. If these actions are coordinated and timely, investors and risk takers would be more likely to move off the sidelines.
Commentary
Eurozone Leaders Need to Agree on a Plan for Deeper Fiscal Union
One of the many worrying aspects of the European debt crisis, even after more than two years of worsening financial and economic conditions, is that there still appears to be no shared understanding and analysis of the problems facing the monetary union. Therefore, with yet another summit of leaders scheduled for December 9, it is very hard to be confident that European political leaders and the European Central Bank are close to agreeing on a credible and comprehensive plan.
Commentary
Evaluating Optimum Currency Areas: The U.S. versus Europe
While economic integration has progressed materially since the inception of the EMU, the U.S. scores much higher in terms of labor productivity, labor mobility and wage flexibility. Research shows that wage rigidity-defined as wage freezes or cuts as a fraction of total workers-is much lower in the U.S. than the eurozone. Eliminating these rigidities is crucial for the eurozones growth as an optimum currency area. Albeit painful, the intensity of the debt crisis in Europe may force a quicker progress of reform implementation, which could be a competitive advantage for the EMU in the future.
Commentary
Life Finds a Way
Even the most sophisticated risk management models can't protect against scenarios we've never even contemplated. In this New Normal economic environment of slow economic growth, high volatility and enormous macro risks we don't believe ignoring major downside risks is prudent for equity investors.
We believe investors are best served by employing a combination of three strategies to actively manage downside risk in equity portfolios to hedge against the risks they can see, and equally importantly, the risks they can't see.
Commentary
Prepare for a Different Financial Landscape
With the European crisis continuing to dominate the news, many people now realize that todays global economy faces an unusually uncertain outlook. Indeed, Europes turmoil is but one of the multiple global re-alignments in play today. What may be less well recognized is the extent to which specific sectors are already changing in a consequential and permanent manner. This is particularly true for global finance where volatility has increased, liquidity is evaporating, and the role of government is pronounced but inconsistent.
Commentary
Beware the Falling Euro
Neither the U.S. economy nor U.S. stock indexes will benefit from the euros decline. A declining euro means a rising dollar in relative terms, so our exports will necessarily become less competitive. During the Great Depression, the country that devalued its currency the quickest and the most was the country that was least affected by depression and that recovered the fastest. This truism will aid Euroland, and hinder the U.S. recovery.
Commentary
Family Feud
Investors should recognize that Eurolands problems are global and secular in nature; it will be years before Euroland and developed nations in total can constructively escape from their straitjacket of debt. Global growth will likely remain stunted, interest rates artificially low and investors continually disenchanted with returns that fail to match expectations. Investors should consider risk assets in emerging economies, and bonds in the strongest developed economies, where the steep yield curve may offer opportunities for capital gains and potentially higher total returns.
Commentary
Playing 'What If?' with Oil Prices and a Potential Strike on Iranian Nuclear Facilities
The impact of a major disruption in the supply of oil from Iran would depend on the IEAs intervention, the duration and the degree to which any attack might be a surprise. The market has less cushion than it did earlier this year due to production outages and relatively strong non-OECD demand, leading to sharp draws on inventories. Excess capacity is virtually exhausted and we doubt other OPEC nations would be able to compensate for a reduction in Iranian oil production. In light of these possible price spikes, investors should evaluate how their portfolios might be affected by inflation.
Commentary
3 Things to Watch This Week
The business sections of this weekend's newspapers understandably focus on last week's disappointing stock market performance (the worst in two months for the S&P) and another round of credit downgrades for European sovereigns (Belgium, Hungary and Portugal). Yet, these are essentially lagging indicators. The stories that may well materialize in the next few weeks will be more heavily influenced by what happens this week to Europe's latest yield curve inversion, core bond rates, and policy announcements.
Commentary
Whether the U.K. is in the Euro or Not, We Are All in This Together
Can the U.K. economy withstand a further sharp deterioration in the European debt crisis? The prospect of European recession, coupled with the U.K.'s program of tight fiscal policy, points to a challenging economic outlook for the U.K. A weak eurozone means weak export prospects at a time when the U.K. is trying to rebalance its economy towards greater exports. The U.K. economy has made great strides in stabilizing its banking system, but it is not yet in a position where it can withstand a systemic European crisis involving multiple defaults.
Commentary
Ben Bernanke: The Decider
Amid great economic stress, policymakers have missed many opportunities to improve the situation and better the lives of people.
The leadership void in the U.S. was illustrated by the dismal display of policy dysfunction that led the country to lose its AAA credit rating. European leaders have fared no better.
Ben Bernanke and the Fed, however, have demonstrated leadership. What is both remarkable and instructive for the outlook for monetary policy is how active the Fed remains even though it has reached the zero-bound for interest rates.
Commentary
QE2 and Its Impact on Sterling Credit Markets
The removal of government bond supply combined with the likely suppression of yields may encourage investors to seek out greater yield via investment grade bonds in the credit markets. The BoEs new round of QE could exacerbate the imbalance between supply and demand and leave a hole in supply that is highly unlikely to be filled by sterling credit issuance. The lack of issuance in the case of non-financials is generally due to strong corporate balance sheets, undrawn credit lines at banks and the rebirth of the loan market.
Commentary
Act and Learn Versus Debate and Wait
Signs of disappointing policy outcomes are, unfortunately, all around us. Over the last two years, American policymakers have failed miserably to lower persistently high unemployment despite a series of stimulus measures, fiscal and monetary, conventional and unconventional. In Europe, the debt crisis has spread despite numerous summits, declarations, policy actions and political changes. In both cases, policymakers identified and sometimes mis-identified the problems and took highly publicized steps to solve them. Yet to no avail. The identified problems not only persisted, they deepened.
Commentary
Is Now the Right Time to Hedge Tail Risk?
Not all hedges have equally increased in value, giving investors the option to reduce the cost of their hedges by considering both direct and indirect hedges.
Tail risk hedging may allow certain investors to maintain an allocation to risk assets where they might otherwise deem the position to be too risky and it can also help stabilize portfolios on a mark-to-market basis. Investors may decide to either start implementing hedges now, phase the tail risk strategy in over a period of time, or put the infrastructure in place now and defer implementation until market conditions change.
Commentary
Known Unknowns
We believe investment managers can analyze numerous data sources and apply lessons learned from past economic cycles to make assessments about the global economic outlook. These managers can make reasonable judgments about asset classes over the long term and, through rigorous bottom-up research, develop an edge regarding the outlook for individual companies. However, the market is much better at aggregating all the information that could affect any of the thousands of companies in the stock market than any investor could possibly be. Hence predictions are likely to be wrong.
Commentary
Could America Turn Out Worse than Japan?
There was a time when America looked down on Japan for the latters inability to deal with its economic problems. No more. Like Japan, America is now realizing how difficult a post bubble economy can be. The fear is that it will also find out that that it lacks some of Japans attributes needed to cope with long years of economic stagnation. The US has no time to waste to build on the important, albeit small progress that has been made in recent weeks. If it does not, there is a risk that the countrys economic fate could end up being even worse than what Japan has experienced.
Commentary
Pennies from Heaven
Growth is the commodity that the world is short of at the moment.
Once interest rates inch close to zero and discounted future cash flows are elevated in price, it's difficult to generate much more return if economic growth doesn't follow.
Equity markets should be dominated by dividend yields and the return of capital via share buybacks, as opposed to growth.
In fixed income assets, we suggest that portfolios should avoid longer dated issues where inflation premiums dominate performance.
Commentary
Asia-Pacific Portfolio Committee Discusses Cyclical Outlook for Globe and Region
China will likely focus more on rebalancing of the investment-focused domestic economy this time, rather than on reflating of the economy to engineer higher growth as it has done in 2008 to 2009.
Japans fiscal policy will need to be expansionary to facilitate reconstruction efforts.
We believe Australian government bonds have the potential to outperform U.S. Treasuries on a local currency basis, particularly in a left-tail global economic scenario.
Commentary
Eyes on the Prize
Before Nobel laureates Tom Sargent and Chris Sims developed their methods, economists and policymakers had no rigorous way to incorporate expectations into their statistical models.
There is a limit to forward guidances effectiveness, which is why the Fed has pursued other policy options since hitting the zero lower bound.
An uncanny correlation exists between the Feds preferred measure of the publics long-term inflation expectations and the timing or initial announcement of a quantitative easing or twist program.
Commentary
Salami Tactics
Repeated attempts to solve the eurozone's sovereign crisis have failed, reflecting a coordination problem among its fiscal authorities and between the ECB and governments.
Markets will not return to supporting the eurozone as it stands, signaling the EMU's leaders to choose one of two solutions: downsize to a smaller, stronger group of countries or adopt a federation with political and fiscal union.
A comprehensive solution not only needs the right tools in place, but also requires a credible commitment with regard to sequencing and executing the long-term plan.
Commentary
All That Glitters Is Not a Cash Equivalent
The latest volatility has investors asking questions about the securities they own, in particular probing any exposures to European issuers.
Cash investors often over-allocate to money market and bank investment vehicles, while the most attractive risk-adjusted opportunities might fall just outside of this space.
We currently see opportunities in short-dated, non-financial BBB-rated corporate bonds, along with dollar-hedged bonds and bills issued by sovereigns with solid balance sheets.
Commentary
Prediction? Pain
?Recent Federal Reserve activity has pushed down the long end of the yield curve, spiking the present value of plan liabilities and widening the funding chasm.
The pain of the pension community shows up most obviously in funded status estimates.
High and increasing levels of implied equity risk premium in pension plans suggest sponsors expectations are increasingly optimistic about future contributions from risk assets.
Commentary
?Repeating the Future
For long-term investors, meaning those prepared to stay invested for three, five and even 10 years, who can endure volatility, we believe equities can offer attractive returns.
In an extended period of slow economic growth and deleveraging, interest rates are likely to remain low. Actual income generation from investments is important.
Hopefully society can institutionalize the lessons from this crisis so that future generations dont repeat it: Individuals, corporations and countries should only borrow to fund long-term investment, not current consumption.?
Commentary
The Markets for Contagion
Markets are in the unusual and very uncomfortable position of being wholly dependent on policymakers and politicians. The investment relevance of company analysis, no matter how good, pales in comparison to the importance of getting the policy calls correct. Faced with this, investors should also remain cautious. Yes there are already opportunities but they will be even more attractive down the road given that the world is now subject to both a synchronized slowdown and de-leveraging.
Commentary
Why Good Companies May Get Even Cheaper for Awhile
Should investors buy good companies trading at historically attractive prices? According to conventional wisdom, this simple question has an equally simple answer - "of course" - that is supported by the vast majority of historical cases. But before acting on conventional wisdom, investors should ask themselves why so many unthinkables have turned into reality over the last few months. By doing so, they would be forced to consider important qualifiers arising from historic structural changes buffeting the global economy and, therefore, financial markets.
Commentary
Six Pac(k)in'
Long-term profits cannot ultimately grow unless they are partnered with near equal benefits for labor.
There is only a New Normal economy at best and a global recession at worst to look forward to in future years.
If global policymakers could focus on structural as opposed to cyclical financial solutions, New Normal growth as opposed to recession might be possible.
Commentary
The Fed's 'Twist' Turns into a Problem for Pensions, Insurers and Households?
In its attempt to stimulate borrowing by making long-term money cheap, the Fed has harmed large swaths of savers. A look at three groups in particular proves instructive: pension plans, life insurance companies, and households saving both inside and out of 401(k)s.
Commentary
PIMCO Cyclical Outlook: Growth Risks, Policy Polarization and Rethinking Returns
Over the next 12 to 18 months, we expect the global economy to expand at a very modest real rate of 1% to 1.5%
Global imbalances have continued to rise in the post financial crisis environment, global leaders continue to fail in their policy coordination efforts, and deleveraging and reregulation continue to be critical over the course of our cyclical horizon.
We are transitioning into a world where we believe the incentives of policymakers and the divisiveness of politics will become the predominant drivers of investment returns and economics.
Commentary
Chinas Escalation up the Value Chain: From Low-Cost Manufacturers to World Leaders?
As labour demographics change, China could suffer a double whammy of a falling savings rate and a diminishing labour force.
The size of its domestic market allows China to spend more on research and development (R&D) and so potentially build technology and scale more quickly than many foreign competitors.
In particular, we have identified wheel loaders and excavators as two sectors where we expect the Chinese to successfully migrate up the value chain.
Commentary
Volatility Is With US for Awhile Longer
There were three culprits for last week's market dramatic sell-off: first, yet another downgrading of the outlook for global growth, including in the form of a stark warning from the Federal Reserve on "significant" downside risks (and, for an institution that selects its words very carefully, significant translates to something nearer to horrid); second, recognition that this situation increases the challenges facing policymakers who, for the large part, have been MIA for way too long; and third, a worrisome amplification of the crisis in Europe.
Commentary
All Eyes on Europe
The longer policymakers wait, the more likely Europes financial crisis will deteriorate. The risk of a global liquidity trap has also increased as many healthy balance sheets around the world are also refusing to engage. Germany and other strong sovereign nations in Europe have to make a choice: continue to provide financial assistance to countries with more debt and assist in helping to restructure the debt of some European peripheral countries, or potentially move forward with a smaller, stronger group of countries-or at the extreme walk away from the Euro and the EU all together.
Commentary
Muni Veterans Discuss Economy, Downgrades and Silver Lining
Many municipal balance sheets are in reasonably good shape and default rates remain a small fraction of the overall market.
The downgrade of Americas AAA rating to AA+ had a knock on effect on municipal bonds. However, we believe of greater consequence to bond issuers, and to the market, is the outcome of federal budget negotiations.
We feel essential service revenue bonds tend to have more consistent revenue streams and lower (or no) pension and medical liabilities than general obligation issues.
Commentary
Ya Gotta Believe!
Central banks around the world consider easing monetary policy amid concerns of a global economic slowdown.
At least one major central bank, however, appears to be taking an opposite stance: China. Policymakers there are concerned about inflation, excessive credit and property speculation.
In other emerging nations, central bankers are generally poised to ease, but have less ammunition than they did after Lehman collapsed.
Commentary
Time for a Smaller and Stronger Eurozone
The euro should, indeed must, be saved. And it can be saved provided Europe is willing to make hard structural and institutional decisions. The time has come for the eurozone -- Germany and France in particular, but also Austria, Finland and the Netherlands -- to decide how they would like European integration to evolve; and they need to do so quickly. They have two conceptual choices: restore stability to the current, heterogeneous zone; or opt for a smaller but stronger one.
Commentary
Market Preview - What to Look for This Week
Global markets again find themselves in the uncomfortable back seat of a car driven erratically by policymakers. The hope is that policy responses in both America and Europe will enable them to build on last week's solid gains and, thereby, improve the outlook for jobs and economic growth. This can happen if most/all of what follows materializes. Top-down issues are still important drivers of markets. It is not a comfortable place for markets given the recent history of recurrent policy shortfalls and debacles. Yet it is also reality for now.
Commentary
The G-7 Disappoints Again
Unlike recent G-7 meetings of finance ministers and central bankers that were essentially ignored, there was quite a bit of interest in the one held this past weekend in Marseille. That interest turned out to be misplaced, however, as the G-7 delivered little of substance yet again. The G-7 issued a communiqu whose disappointing lack of content contrasts sharply with the deteriorating health of the global economy, the intense risks ahead, and legitimate policy confusion. The G-7 is fortunate that it is not required to justify the expenses of its meetings in terms of what is achieved.
Commentary
A Powerful Obama Speech
At long last, President Obama did enough this evening to upgrade the quality of the nation's economic debate. He presented a credible program that is focused on the right structural areas. Now he must strengthen it and complement it with a sensible fiscal component; and Congress must discuss it in a cooperative and constructive manner. A lot is at stake, especially for those that have been jobless for too long but also for American society as a whole. Let us hope that Washington is, collectively, able and willing to follow through.
Commentary
Teaching to the Test
Many managers are focused on beating benchmarks, rather than helping clients achieve their investment objectives. Clients save and invest their money for specific reasons, such as for retirement or childrens education and managers should focus on helping them meet those goals. Many managers are really closet indexers masquerading as active managers while charging premium fees for benchmark returns. Many equity managers deviate very little from their benchmark because they are terrified of potentially underperforming it.
Commentary
The Changing Landscape of Global Investing
National and global realignments are fundamentally and durably changing the global investment landscape.
Investors face the challenge of recalibrating some of the traditional parameters that are key to managing risk and delivering returns.
There are also implications for investment management firms which are yet to be sufficiently reflected in the thinking and actions of the industry as a whole.
Commentary
Helicopter Ben risks destroying credit creation
The concept of showering money over national economies to combat deflation has been an accepted principle of monetarism for decades. A helicopter, however, is not your average aeroplane, and the usual laws of aerodynamics do not necessarily apply in all cases. Similarly monetary policy at the zero interest rate bound introduces a new dynamic that may conflict or even reverse standard logic that lower interest rates across the sovereign yield curve are everywhere and always stimulative to economic growth.
Commentary
Tuesday's Market Preview Is Not Pretty: El-Erian
Again, already fragile U.S. markets will be influenced by developments on the other side of the Atlanticand in a week in which there is great anticipation for President Obama's "mission critical" speech on the American economy. Europe's deepening debt and growth crisis amplifies the importance Obama's effort to deal with America's deepening unemployment and growth crisis; and does so by raising both the stakes and the challenges for the President. Tighten those seat belts. It will be a bumpy and volatile week as markets are held hostage to policy developments in both America and Europe.
Commentary
Austerity is not Enough
Before the Jackson Hole meetings over the weekend, it was no surprise that all eyes were on central banks. They have demonstrated in recent years that they can act swiftly and decisively when they choose to. While eurozone governments have failed to maintain a united front to deal with a sovereign debt crisis, and American politicians have concocted their own budget crisis, central bankers have retained the moral and operational high ground. Yet, given the problems of growth in the U.S., and of growth, solvency and the coherence of the eurozone, there is a limit to what central banks can do.
Commentary
New-Fangled Love Songs
Liquidity concerns may affect all European peripheral bond markets unless the European Central Bank counters the rush for the exits with an enlarged daily checkbook.
In the U.S., discord between rich and poor has led to lower, not higher, Treasury yields as approaching recessionary winds force the Fed and private investors to favor bonds.
We prefer investing in the cleaner dirty shirt countries of Canada, Australia, Mexico and Brazil, along with non-dollar currencies that have strong trade ties with the Asian continent.
Commentary
Why Washington Urgently Needs to Break America's Negative Feedback Loop
It is tempting to dismiss all this market volatility as just irritating "noise" rather than insightful "signals". But, be very careful before you are opt for this seemingly comforting interpretation. There is a lot in play today that requires a bold response out of Washington. This is not just an American phenomenon. Europe is in a much worse situation. And, if policymakers on both sides of the Atlantic don't get their act together, they will run out of tools that have a chance of being effective circuit breakers. Things could get a lot worse before they get better.
Commentary
?The Case for Tail Risk Hedging in Emerging Market Equities
While our secular outlook for emerging markets is solid, we expect long-term success will be earned by those who can manage cyclical risks.
There is a tradeoff between the cost of establishing a hedge and the downside protection that it imparts to a portfolio.
The best approach to tail hedging is a flexible one; using dynamic rebalancing, diversification and affordable option-like securities.
A diversified macro approach to hedging tail risk actually may be more efficient for EM than it is for developed asset classes.
Commentary
Developed Market Banks: Why PIMCO Pathfinder Takes a Selective Approach
The Pathfinder Strategy is currently limited to only a handful of banks that are best characterized by PIMCO as deep value opportunities.
We generally do not see meaningful upside potential in equity positions of developed market banks over the secular horizon.
Our concerns primarily revolve around three factors: loan growth, balance-sheet risk along with capital levels and regulation.
Commentary
Policy Dithering Will Further Fuel the Crisis
The world economy is now in the grips of a damaging feedback loop involving deteriorating fundamentals, lagging policy responses and destabilised financial markets. If policymakers do not act boldly, and do so in a globally-coordinated fashion, the world risks tipping into a prolonged recession with worrisome institutional, political and social consequences.
Commentary
No Turning Back: The ECB Brings Its Balance Sheet to Bear on Italy and Spain
The European Central Bank has crossed the Rubicon. By buying Italian and Spanish government bonds, it has brought a much-needed and credible external balance sheet to bear. There is thus the potential for an end to damaging games of chicken between the eurozones monetary and fiscal authorities and, therefore, stabilizing the eurozones systemically important government bond markets. But there remains huge uncertainty, together with large technical and political execution risk.
Commentary
Saying No to Keynes and Fiscal Folly
?Taxpayers have been hoodwinked into believing the cost from profligate government spending is low relative to the benefits.
The Keynesian revolution ignited a decades-long abuse of the core principle of Keynesian economics: for government to increase spending when private sector aggregate demand weakens and stymies job growth.
The central banker is left to shoulder the burden, seeking all the while to pressure the fiscal authority to amend the abuse of Keynesian economics and decades of fiscal folly.
Commentary
Saying No to Keynes and Fiscal Folly
?Taxpayers have been hoodwinked into believing the cost from profligate government spending is low relative to the benefits.
The Keynesian revolution ignited a decades-long abuse of the core principle of Keynesian economics: for government to increase spending when private sector aggregate demand weakens and stymies job growth.
The central banker is left to shoulder the burden, seeking all the while to pressure the fiscal authority to amend the abuse of Keynesian economics and decades of fiscal folly.
Commentary
Unprecedented Fed to the Rescue
After Mondays gut wrenching 635 point fall, the Dow Jones index surged an impressive 430 points on Tuesday. In the process, investors experienced a wild 640 point intra-day roller coaster! Gold prices set another record while Treasury yields fell sharply, with the 2-year closing at an eye popping 0.2% and the 5-year at an equally stunning 1.0 percent. Tuesdays combination of unusual, if not unprecedented, market moves had a lot to do with the Fed. Once again, the institution came to the rescue of an equity market under severe pressure, and did so in a bold manner.
Commentary
Cash vs. Tail Risk Hedging: Which Is Better?
PIMCO has done much research over the last eight years of managing so-called tail risk for our clients, and weve come to the conclusion that flexibility and the use of all tools are paramount. The main difference between cash as a hedge against systemic risk and, say, put options is that a dollar of cash remains a dollar of cash regardless of the market, but option values change as either the underlying asset moves down or as the perception of risk changes. In short, we believe guarding against the tails is best achieved by a mix of approaches rather than blind adherence to one.
Commentary
U.S. Downgrade Shouldnt Cause Liquidity Investors to Cash Out
Surprises are not a new phenomena for money market and other short-term investors.
Our sense is that that money-market funds and other short-term strategies seem well positioned for the aftermath of the downgrade.
In the short-term, we believe U.S. Treasury bills will continue to be highly sought after as a short-dated liquidity alternative, especially by central banks.
S&Ps downgrade should serve as another wake-up call to investors to continually determine their liquidity needs.
Commentary
The Other Shoe Drops: Munis Tied To Government Get Downgraded
We believe the implications from the downgrade as well as the overall environment make a good case for muni investors to prefer essential-service revenue bonds over General Obligation (GO) securities.
This is not the first time that we have seen the muni market face potential ratings downgrades.
The muni market has become a market where credit analysis is increasingly important.
Commentary
U.S. Downgrade Heralds a New Financial Era
There will be endless debate on whether S&P, the rating agency, was justified in stripping America of its AAA rating and even attaching a negative outlook to the new AA+ rating. But this historic action has now taken place, and the global system must adjust. There are consequences, uncertainties, and a silver lining. Not so long ago, it was deemed unthinkable that America could lose its AAA. Indeed, risk free and US Treasuries were interchangeable terms so much so that the global financial system was constructed on the assumption that Americas AAA was a constant at the core.
Commentary
Making Sense of Thursdays Violent Market Sell-Off
Technical factors played a role in Thursday's unsettling market moves, including the disorderly across-the-board collapse in the price of risk assets in the final hour of trading and the related surge in U.S. Treasurys. But they were not the cause. Rather, they amplified three factors that will determine the fate of markets in the weeks ahead. First, it is now undeniable that the U.S. economy is weakening across the board. The second factor relates to confidence. Markets are worried that policymakers will not be able to put the economy back on the right path. And then there is Europe.
Commentary
Kings of the Wild Frontier
The U.S. has averted a debt crisis, but there remains a stain on our reputation.
Nothing in the Congressional compromise reached over the weekend makes a significant dent in our $1.5 trillion deficit. In addition to an existing nearly $10 trillion of outstanding Treasury debt, the U.S. has a near unfathomable $66 trillion of future liabilities at net present cost. Aside from outright default, there are numerous ways a government can reduce its future liabilities. They include balancing the budget, unexpected inflation, currency depreciation and financial repression.
Commentary
America Will Avoid Default But There's A Lot More to Do
Politicians are taking an important step this weekend to remove the threat of a debt default and to focus more credibly on problems facing the economy. We should thank them for that. But we should also remind them that their work is far from done. Washington should waste no time in redoubling efforts to remove the multiple policy uncertainties and structural impediments that stand in the way of restoring America on the path of high growth and plentiful job creation. Anything short of that will imply further economic and social deterioration, and a greater erosion of America's global standing.
Commentary
Why Global Debt Dramas Recur
Neither Europe nor America can sustain the sort of economic recovery that would make a meaningful dent in their debt dynamics. As a result, different governments are opting for different approaches, including harsh austerity, financial repression and, in one case, a potential debt restructuring.
De-levering pressures will be with us for years, and governments will mix and match from the menu of options. Accordingly, periodic debt dramas will recur. And we all need to understand the dynamics and the likely choices governments will make going forward.
Commentary
Could a U.S. Debt Downgrade Trigger a Financial Crisis?
A downgrade of U.S. credit could spark a new financial crisis. Would the impact be as great as when Lehman Bros. failed? Treasurys have been defined for decades as the risk-free financial instrument; faith in them is far stronger than it was in debt of Lehman. U.S. Treasuries are a $14?trillion market. Lehman had approximately $600?billion of liabilities before it failed, less than 5% of the size of the Treasury market. These factors suggest that a U.S. downgrade has the potential to be as bad, or perhaps worse, than the Lehman shock.
Commentary
The 'how' undermines the 'what' of the debt ceiling debate
I am confident that Washington will find a way to compromise on a mini-deal, rather than a grand bargain, that raises the debt ceiling and avoids a debt default. They may even manage to evade a downgrade of the nations vaunted AAA credit rating, though this is more uncertain. But fiscal solvency is not merely a function of deficits and debt. It is also highly sensitive to economic growth: The lower an economys growth rate, the higher a budget deficit is likely to be, the larger the debt accumulation, and the greater the need for yet another round of fiscal austerity to safeguard solvency.
Commentary
Eurozone Leaders are Fighting Contagion, But is it Too Little, Too Late?
European politicians and bureaucrats may want to focus on their summer holiday plans rather than the eurozone sovereign crisis, but with Italy and Spain facing ongoing contagion they may have to forget their holidays and get to work. When the eurozone leaders finally got around to their summit on July 21, they no doubt hoped that the announcement of a new bailout plan for Greece and plans to expand the role of the European Financial Stability Facility (EFSF) would buy them some time. Unfortunately, that has not happened.
Commentary
Is There Equity Beta in Oil?
Oil exposure can increase equity beta in an investment portfolio.
Historically, correlations between oil prices and equity prices have varied widely, depending on economic conditions.
Determining whether oil price movements are driven by changes in supply or demand can help identify when the correlation between oil and stock prices is likely to be high or low.
Investors can then know when exposure to oil is tilting their portfolios toward higher or lower equity beta.
Commentary
How to Orchestrate an Orderly and Credible Restructuring of Greeces Debt
?Identifying how much solvency relief Greece needs is complicated, not least because there is no magic debt ratio that is sustainable.
Identifying how much political capital might be bought in European Union creditor countries and beyond is more straightforward.
Contagion risks are positively correlated with any benefits Greece might experience from a potential restructuring.
Commentary
Secular Outlook: Implications for Investors
As the economy undergoes important realignments, investors will need to rethink their traditional approaches to managing their portfolios. As the lines between interest rate and credit risk become blurred, finding sources of safe spread becomes even more critical. More, not less, discretion is warranted when navigating volatile global markets, avoid sectors affected by financial repression and hedge against inflation and/or adverse tail events. We believe investors need to look at risk factors rather than traditional asset classes when making asset allocation decisions.
Commentary
Earning 'Extra Credit' Through Short-Term Strategies PIMCO
Given renewed concerns over liquidity and credit, investors can potentially do better by considering actively managed short-term strategies that invest beyond traditional U.S. money-market guidelines. The current credit situation in Europe is different from that in both 2008 and 2010 because initial liquidity conditions in the short-term markets are better. In our view, investors should evaluate potential investments within the wider scope of relative value opportunities and not simply for the incremental yield they may offer above risk-free returns.
Commentary
Are There Any Rungs Left on the Housing Ladder?
Headwinds to housing demand, and thus the overall market, could last for years.
It appears that limited mortgage availability and vulnerable consumer health are restraining demand.
Also weighing on the market is regulatory uncertainty over the future structure of mortgage finance and the resolution of foreclosure overhang.
We believe the housing market, considered to be a key driver of the economic recovery, will generally remain weak for the foreseeable future.
Commentary
Are Emerging Markets Ready to Lead the Global Economy?
We forecast emerging economies will expand at a faster pace than advanced economies over the secular horizon. The challenge for emerging market central bankers is to remain ahead of inflation expectations and retain credibility on inflation targeting. We feel they are well positioned for this. We believe global investors remain significantly underweight emerging market assets. We expect this underallocation to decrease, providing multiyear support for the asset class.
Commentary
What a Multi-Speed World May Mean for Equities
Equity investors may look in unfamiliar places as they navigate potential shifts in the global economy. An apparent rebound in risk tolerance since the financial crisis has supported higher equity valuations. Emerging market economies appear to be undergoing a mid-cycle rebalancing. We view this as a welcomed cyclical adjustment rather than the end of their growth cycle; long-term fundamentals remain intact. We believe advanced economies should continue to see headwinds to growth, and that potentially means investors may be generally willing to pay lower multiples to earnings.
Commentary
Europe Must Consider Radical Options
Europe has been applying a liquidity solution to a solvency problem. The approach, which has bought time, is near exhaustion as it has failed to improve debt sustainability, restore access to markets and put in place the conditions for sustainable growth. Time is approaching for a radical change, with policymakers potentially facing two options. They could opt for greater fiscal union to include cost-effective guarantees and transfers, rather than just loans, in exchange for individual countries sacrificing a significant amount of national sovereignty.
Commentary
America Needs a Grand Bargain, But All It?s Getting Is a Mini Deal
To address its economic woes, America needs to transition from a series of ad hoc measures to a more holistic policy approach. Aided by President Obamas personal and highly visible involvement, politicians are likely to meet the August 2nd debt ceiling deadline. A "grand bargain" can serve as the catalyst for unifying diverse policy actions into clearer, more comprehensive drivers for growth and medium-term fiscal sustainability. This would intensify pressure on other systemically-important parts of the world-particularly Europe and China-to join the US in striking their own grand bargains.
Commentary
America and Britain's Economic Policies Will Soon Be Similar
?By imposing austerity programs,t he U.K. is hoping to free up resources that can be devoted to pay down debt. The U.S. is hoping to create resources to pay down debt via economic growth ? an approach that can have disappointingly narrow feasibility. Other options include restructuring or defaulting on debt, inflating out of it and imposing financial repression by paying creditors less than they deserve.
Commentary
The End of Currency Wars?
International capital is flowing to countries with good growth prospects and to countries with central banks confident enough to raise interest rates.
Certain nations are placing controls on capital or intervening in currency markets with an eye to maintaining economic competitiveness.
We see central banks in the U.S. and the U.K. winding down monetary stimulus that has exacerbated the situation. Also, we see potential for emerging market currencies to appreciate, and that may give developed nations a boost.
Commentary
Is Europe?s Debt Crisis a ?Lehman Moment? for America?
Europe?s debt problem is a headwind for what remains a disappointing U.S. economic recovery.
There is now broad-based recognition of America?s persistent economic weakness. The Federal Reserve has been forced again to revise downwards its growth projections for both 2011 and 2012.
In order to avoid a repeat of the total Lehman paralysis in the face of an external shock to the U.S. economy three conditions must be met: a banking system that remains robust, no disruptions to money market funds and limited blockage to the plumbing of the country?s payments and settlement system.
Commentary
With Housing Fragile, the Risks of Public Policy Error Are High
We are seeing signs of what we have long suspected: There never was a housing recovery. The market is in an arguably fragile state that we believe is far easier to break than to fix. If we ended government support, mortgage rates could rise significantly, because home loan investors would need to be compensated for greater credit risk, and loan availability could decline. Those two factors would put downward pressure on home values.
Commentary
Sunlight on U.S. Banks
Among global banks, we believe U.S. banks are in a stronger position to absorb deterioration in the macroeconomic environment in Europe. U.S. banks also look attractive given their profitability, improving asset quality and capital position. Global banks vary dramatically in their asset quality and ability to meet capital requirements over time. As a result, we believe financial markets will continue to reward the strongest and safest banks and penalize the weakest. While we remain cautious on the U.S. housing market, U.S. banks appear to have the resources to manage further weakness.
Commentary
Covered Bonds: Strong Demand, New Regulations Create Global Momentum
Basel III?s long-term funding and liquidity coverage requirements could boost demand, create technical support for valuations.
The EC has proposed an exemption excluding covered bonds from private sector participation in post-insolvency burden sharing.
The Covered Bond Act could alter the way regional banks in the U.S. rely on the Federal Home Loan Bank (FHLB) system for funding.
Commentary
?Attractive Yield Opportunities Remain in Floating Rate Loan Markets
We believe the general trend toward more diversified capital structures may be positive for investors in the loan market.
Recent changes in loan market investor mix have had and will likely continue to have a positive impact on loan spreads.
In addition to price, leverage and other quality measures in new issues also generally remain attractive.
Commentary
Five To-Do's for the IMF's New Managing Director
Circumstances have catapulted Christine Lagarde into the role of leader of the IMF: the world?s most influential and fastest-responding multilateral institution. Lagarde will need to hit the ground running if her tenure as IMF managing director is to be an inspiring story of institutional transformation. She should waste no time in establishing a legitimate selection process for the next managing director that is truly based on merit. She must strengthen the analytical robustness of the IMF?s response to debt crises, and prepare the Fund?s balance sheet for the risk of future impairment.
Commentary
Higher Commodity Prices and the End of Economic Growth Without Inflation
Global inflationary patterns may shift amid higher commodity prices.
We expect commodity prices to be generally rising going forward, though with volatility and differentiation among commodities.
Emerging markets going through a particularly commodity and energy intensive phase of growth may affect what developed-world consumers pay for commodities.
Currencies are another factor. If developed-world policymakers attempt to make their economies more competitive via a cheaper currency, that could lead to higher inflation for those that are net importers.
Commentary
On Governments as Portfolio Managers
Energy markets are focusing intensely on the price impact of today?s International Energy Agency decision to release oil supplies.
Governments (and central banks) getting pulled deeper into markets as portfolio managers, as opposed to regulators and supervisors.
Policymakers are trying to differentiate between good and bad inflation ? namely, enhancing the former and countering the latter.
Commentary
A New Era of Global Financial Repression
Investors need to be especially alert to increasing financial repression. Any sovereign policy that interferes with free market activity and the pricing of debt or currency can be thought of as financial repression. Repressionary policy rates percolate through the global financial markets and affect asset prices across the risk spectrum. Many emerging market countries use repressionary tactics to capture a larger share of global growth.
Commentary
Can U.K. CPI Really Get Back to Its 2% Target?
?U.K. CPI (Consumer Price Index) will likely continue to be buffeted by food and energy inflation. To generate the conditions necessary to bring inflation down more aggressively would put even greater pressure on U.K. households. The Bank of England is right to be cautious on raising the Bank rate given the current state of the economy.
Commentary
School Daze, School Daze Good Old Golden Rule Days
The past several decades have witnessed an erosion of our manufacturing base in exchange for a reliance on wealth creation via financial assets. Fiscal balance alone will not likely produce 20 million jobs over the next decade. Government must take a leading role in job creation. A growing number of skeptics wonder whether college is worth the time or the cost.
Commentary
What's Weighing Heavily on the Markets
Balance sheets and other structural problems will repeatedly impact headlines (and weigh on markets) unless policymakers alter their course. European policymakers and the IMF have spent the last year treating Greece?s predicament as a liquidity problem as opposed to what it is: a solvency and growth crisis. By ignoring the basic issue of Greece?s solvency, some previously pristine balance sheets are now contaminated. In the U.S., political dithering (and bickering) is complicating the country?s ability to deal effectively with structural impediments.
Commentary
Game Change for Bond Investors?
Over the next three to five years, we argue that market behavior may be vastly different than what typical cyclical models would predict. Sovereign debt, which is at the core of our global financial system, is undergoing a seismic shift. Governments practicing financial repression may be transferring wealth from creditors (citizens) to debtors (governments) to the detriment of creditors, fixed income investors and savers.
Commentary
The End of QEII: Gaining Clarity, Losing the Treasury?s Biggest Customer
?The Fed?s policies and its fat balance sheet are playing a powerful role in shaping financial and economic conditions around the world. The drain of a single dollar from the financial system will signal a reversal of Fed policy and thus have a major bearing on financial conditions. Depending on the speed of the economic slowdown, the Fed could decide to keep a level of discretion over when and what will be reinvested in its portfolio.
Commentary
America?s Dangerous Debt Ceiling Debate
?In today?s polarized environment in Washington, Republicans and Democrats are unwilling to compromise ?too early.? Such political paralysis on key economic issues is increasingly unsettling for the U.S. private sector, and for other countries that rely on a strong U.S. at the core of the global economy.
Commentary
How Strategic Deficit Reduction Could Spur Growth
Much of the evolution of our secular economic outlook for advanced economies will depend upon the degree and success of structural policy changes. To date, few such policies have been implemented. We think the U.K. is implementing what is probably the best combination of fiscal and monetary policies to address deficit reduction with an eye to structural issues. In the U.S., we see great economic benefit from shifting some public spending from consumption to investment ? for example, to the energy sector, where the U.S. has a large deficit vs. the rest of the world.
Commentary
Understanding Recent Market Movements
Despite massive fiscal and monetary stimulus, the U.S. economy has frustratingly failed to gain proper traction.
The U.S. economy faces structural impairments in housing, credit, public finances, and the functioning of the labor market.
The situation in Europe is another factor undermining market sentiment.
Structural problems require structural solutions that are adopted within a clearly communicated overall vision.
Commentary
The Eurozone Needs a Plan B, as 'Quarantining' the Weak Is Too Costly
The eurozone?s peripheral debt crisis is morphing into a tussle between politics and economics and the strains are beginning to show. Greece and Ireland are on programs that are neither restoring stable debt dynamics, nor in keeping current investors engaged or attracting new ones. Portugal is now following the same approach. The better and more realistic approach for the eurozone as a whole might be to acknowledge the Greek plan is not working and move to Plan B ? address the need for a restructuring of Greece?s public debt and perhaps that of other countries too.
Commentary
U.S. Must Move Beyond Financial Band-Aids
Structural problems require structural solutions to improve the labour market, housing, credit and medium-term fiscal sustainability. Some analysts will encourage investors to look through these ?temporary and reversible? factors. We should not. The U.S. lost its edge in educating, training and retooling its labour force. This slippage has been extremely costly.
Commentary
Buy Cheap Bonds with Safe Spread
If the government is going to artificially repress yield, then focus on the parts of a bond that are less repressed! Rather than outright default, many countries attempt rather successfully to keep nominal interest rates lower than would otherwise prevail. Over the long term, this ?financial repression? results in a transfer of wealth from savers to borrowers. Investors shouldn?t give their money away, and at the moment, the duration component of a bond portfolio comes close to doing just that ? because it doesn?t yield enough relative to inflation.
Commentary
The Danger of Emerging Market Inflation
If left unchecked, high and accelerating inflation in emerging markets will have growing adverse economic, social and political effects. In addition to undermining overall growth and resource allocation, emerging market inflation imposes a very heavy burden on the poor and erodes political unity. Emerging economies will tap multiple policy brakes as they seek to counter mounting inflationary pressures. And they will continue to grow, but not enough to pull up decisively the sluggish advanced countries.
Commentary
Secular Outlook: Navigating the Multi-Speed World
It is a world that heals slowly and unevenly, and remains structurally impaired. Balance sheets, both across and within economies, are still out of equilibrium. We expect advanced economies will face sluggish growth and persistently high unemployment over the secular horizon. Emerging economies will achieve higher growth but face recurrent inflationary concerns. We do not expect policymakers to boldly address structural problems. By targeting negative real interest rates, they will pursue financial repression that undermines the ?real return? contract that savers expect.
Commentary
Strauss-Kahn Allegations Are Consequential for the Global Economy
Should Strauss-Kahn be forced to step down, this would catch the IMF with a selection process for the top position that is still overly dominated by politics.
The allegations facing Strauss-Kahn are serious and will take time to be investigated properly. In the meantime, they have caught Europe still without a sustainable solution to the debt crisis in its periphery.
Commentary
The Caine Mutiny (Part 2)
Low policy rates and the increasing negative real yields that they engender as inflation accelerates represent an immediate threat to investment portfolios. Bond prices dont necessarily have to go down for savers to get skunked during a process of debt liquidation. PIMCO advocates a renewed vigilance, stressing bond market alternatives available globally, including developing/emerging market debt at higher yields denominated in non-dollar currencies.
Commentary
The End of QEII: It?s Time to Make the Donuts
With quantitative easing the Federal Reserve has in essence picked the pockets of Treasury bond investors throughout the world. Ultimately, the U.S. must own up to its past sins and let the deleveraging process play itself out. The U.S. must invest in its people, its land, and its infrastructure, as well as promote free trade, to achieve economic growth rates fast enough to justify consumption levels previously supported by debt.
Commentary
Anchors Away?
Public expectations of future inflation are an important determinant of actual inflation. We really don?t know if longer-term inflation expectations are well anchored. We just know they tend to adjust slowly to actual inflation. The substantial economic costs of bringing down high inflation are largely due to the need to bring down inflation expectations. Most central banks that recently enacted unconventional monetary policies are seeking to exit from them.
Commentary
Skunked
Medicare, Medicaid and Social Security now account for 44% of total federal spending and are steadily rising. Previous Congresses (and Administrations) have relied on the assumption that we can grow our way out of this onerous debt burden. Unless entitlements are substantially reformed, the U.S. will likely default on its debt; not in conventional ways, but via inflation, currency devaluation and low to negative real interest rates.
Commentary
A special visit to Tokyo
Japan is recovering from the horrible calamities, but doing so in the midst of enormous challenges and high uncertainty.
Commentary
Andrew Balls Discusses PIMCO?s European Cyclical Outlook
Europe?s outlook hinges on limiting contagion from the most troubled peripheral countries. The European Central Bank has signaled its intentions to start tightening, which could complicate the outlook for the more distressed countries. We think the Bank of England will begin to tighten rates over the summer. The UK outlook depends on the impact of fiscal tightening.
Commentary
Understanding Japan?s Disasters
Japan?s reconstruction challenge will likely be more difficult than after the Kobe earthquake. Negative wealth and income effects this time around will be more severe, and the recovery process will probably take longer and be more complex. Japan's disasters will add to the global economy?s headwinds.
Commentary
PIMCO Cyclical Outlook: U.S. Economy, Global
PIMCO continues to foresee a multi-speed global recovery over the next few years. The U.S. is experiencing a cyclical economic rebound, but its strong durability is uncertain. Several countries in Europe face headwinds to growth over our cyclical horizon. Japan?s growth rate will likely fall in the near term, but reconstruction activities should stimulate growth over time. We expect real economic growth in key emerging economies to remain at a solid rate during 2011, but lower than 2010.
Commentary
World Near Tipping Point?
Much of the potency of policy responses has been used up in the successful efforts since 2008 to avoid global depression. The longer the persistence of supply disruptions, the greater the risk of core inflation increasing. Questions about the end of quantitative easing in the U.S. pose a challenge for policymakers.
Commentary
Japan Will Recover
Japan has the ability to recover economically from these horrible natural disasters. Japan?s immediate focus is on the enormous human suffering, and rightly so. Attention also turns towards the extent of the damage to the economy and its reconstruction and rehabilitation plans. The good health of Japan is central to a robust global economy that generates lots of jobs and enhances productivity.
Commentary
Two-Bits, Four-Bits, Six-Bits, a Dollar
A successful handoff from public to private credit creation has yet to be accomplished, and it is that handoff that ultimately will determine the outlook for real growth and stability. Because quantitative easing has affected all risk spreads, the withdrawal of nearly $1.5 trillion in annualized check writing may have dramatic consequences. Who will buy Treasuries when the Fed doesn?t? The question really is at what yield, and what are the price repercussions if the adjustments are significant.
Commentary
Differentiated Change in the Middle East and North Africa
For two months, developments in the Middle East and North Africa (MENA) have taken most by surprise. What started as an protest in Tunisia has developed into a regional phenomenon that has toppled regimes and is threatening others. Indeed, every day seems to bring an historical event that is changing the region and impacting the global economy. Governments across the globe have spent weeks playing catch up in the midst of unthinkable developments in MENA. They have organized emergency evacuations of citizens and constantly responded to realities on the ground, including the violence in Libya.
Commentary
The Global Economic Impact of this Weekend's Developments
In the short run, regional developments will be stagflationary for the global economy. In the next few days, markets will react to the changed outlook for the region and the global economy. Over time, market apprehension is likely to give way as the impact of greater long-term stability in a key part of the world is felt.
Commentary
Viewing Chairman Bernanke?s Remarks Through the Lens of Emerging Economies
Bernanke's comments will raise eyebrows among policymakers in emerging economies. His remarks highlight persistent differences in analysis that complicate policy discussions. International cooperation will not materialize unless advanced and emerging economies converge on a common analysis of the key issues. My hope is that the G-20 meeting will take an important step in this regard, and do so by recognizing that there is more than one perspective to today?s global challenges. I fear, however, that this may not materialize as yet.
Commentary
Muni Market Bargains? A Closer Look at Municipal Debt, Deficits and Pensions
Although real, pension problems will not lead to an immediate debt crisis this year or the next five years. A default by Detroit, for example, would not precipitate bankruptcy filings by large cities across the nation. The municipal market will continue to migrate from being a low-risk asset class to a credit asset class.
Commentary
Spain Is Not Greece and Need Not Be Ireland
Spain?s success is of acute relevance to the rest of the eurozone. Unlike Greece, Spain does not have a direct public finance crisis. Spain is where Ireland was a couple of years ago, but is clearly keen to avoid Ireland?s experience. To avoid a bad outcome in Spain (and the rest of the eurozone), additional, significant and highly visible progress needs to be made within the next few weeks.
Commentary
Devil?s Bargain
Money has become the economic and political wedge for profound changes in American society. Perhaps the most deceptive policy tool to lessen debt loads is the ?negative? or exceedingly low real interest rate that central banks impose on savers and debt holders. Old-fashioned gilts and Treasury bonds may need to be ?exorcised? from model portfolios and replaced with more attractive alternatives both from a risk and a reward standpoint.
Commentary
Nice Speech, But Now Obama Must Act
The president left no doubt that tackling unemployment was a priority. Success on this would also facilitate the medium-term budget reform that he is targeting. Mr. Obama must make clear jobs creation can no longer depend simply on stimulus, federal government hiring, and the hope that previous drivers (such as construction) will return.
Commentary
Europe Is Running Fast to Stand Still
The sequencing of Europe?s debt crisis is depressingly similar ? the plot stays the same, with a slightly different cast depending on the country in the spotlight. Yet, judging by the run-up to the meeting of European Union finance ministers in Brussels on Monday, European officials seem intent on repeating it over and over again.
Commentary
Off With Our Heads!
American politicians and citizens alike have no clear vision of the costs of a seemingly perpetual trillion-dollar annual deficit. Meanwhile, policy stimulus is focused on maintaining current consumption as opposed to making the United States more competitive in the global marketplace. Dollar depreciation will sap the purchasing power of U.S. consumers, as well as the global valuation of dollar denominated assets.
Commentary
Germany in a Lose-Lose Situation
The problem is that Germany's current approach ? centered on dealing with liquidity problems now and solvency centered later ? is not working.
A liquidity approach that delays the day of reckoning may be good regional politics, but it's bad economics. It does not restore sustainable growth to the periphery, and it exposes the core to contamination. Rather than simply doubling up on a faltering liquidity approach, the time has come for Germany to lead a more holistic solution focused on addressing the periphery?s debt overhang and competitiveness problems.
Commentary
Allentown
The global economy is suffering from a lack of aggregate demand. In the U.S. and Euroland, many policies only temporarily bolster consumption while failing to address the fundamental problem of developed economies: Job growth is moving inexorably to developing economies because they are more competitive. Unless developed economies learn to compete the old-fashioned way ? by making more goods and making them better ? the smart money will continue to move offshore to Asia, Brazil and their developing economy counterparts, both in asset and in currency space.
Commentary
Ireland Rescue Is Not a Game Changer
Ireland's new liquidity package does little to deal with its debt overhang, or to reduce the embedded cost of its debt. Instead it aims to introduce stability into market conditions. It took time for Europe to recognize the severity of the peripheral debt crisis. Now it is also recognizing that liquidity support (while necessary) may not be enough.
Commentary
Irish Crisis Demands New EU Response
Advanced economies are not wired to operate at elevated levels of sovereign risk. The longer these spreads persist, the greater the decline in investment activity and employment. If things are left as they are the risk of further social unrest will rise, while tax revenues will collapse at a time when budgets are already under enormous strain. The policy responses of eurozone governments were supposed to buy a few years of calm, but ended up by delivering only a few months. A more effective and credible approach is now needed.
Commentary
A Kind Word For Ben
The Fed makes policy consistent with its legislative mandate handed down by the democratically elected government of the United States. Price stability (mandate-consistent inflation) that promotes bubbles in asset prices and debt creation is a prescription for a debt-deflation bust and a subsequent liquidity trap. Acting irresponsibly relative to conventional wisdom is precisely the right approach for reversing an economy facing, or worst yet, mired in a liquidity trap.
Commentary
We've Voted. What's Next For the Economy?
With the two chambers of Congress split between Democrats and Republicans, the conventional wisdom likely to be repeated over the next few weeks is that political gridlock is good for the economy. While often true, that is not the case today. Democrats and Republicans must meet in the middle to implement policies to deal with debt overhangs and structural rigidities.
Commentary
Run Turkey, Run
The Fed's announcement of a renewed commitment to quantitative easing has been well-telegraphed, and the market's reaction is likely to be subdued. We are in a 'liquidity trap,' where interest rates or trillions in asset purchases may not stimulate borrowing or lending because consumer demand is just not there. The Fed's announcement will likely signify the end of a great 30-year bull market in bonds and the necessity for bond managers and, yes, equity managers to adjust to a new environment.
Commentary
The Fed Feels Compelled to Experiment
Judging from the minutes of the September 21 Federal Open Market Committee meeting, it is virtually a foregone conclusion now that the Federal Reserve will announce on November 3 that it is re-engaging in 'unconventional policies.' As a body, the FOMC recognizes that the benefits of quantitative easing come with potential costs and risks, including unintended consequences. Despite this tricky and uncertain balance, it feels compelled to act.
Commentary
Stalled Post-crisis Reforms Must Be Restarted
In the early part of this crisis, swift coordinated global policy action saw a painful economic collapse replaced by employment gains and greater financial stability. However, the marked failure to continue coordinated action reflects two critical weaknesses that now must be taken seriously: an insufficient appreciation of the mix of post-crisis forces; and a growing void at the center of the international system. For the IMF this means acting on long-standing governance and representation problems ? and doing so by going well beyond what is being currently contemplated.
Commentary
Beyond Brinkmanship: A Better Economic Path for the U.S. and China
It is in virtually no country's interest - including that of the United States - for China's economic development to derail. China is the world's strongest growth engine, its largest creditor and its biggest trade partner. Rather lecturing China on its exchange rate, the United States should be doing more to push its European allies to allow a larger Chinese voice in multilateral forums. Beijing, in turn, should think carefully about how it can help the United States and the global economy to bridge the hole of balance-sheet repair.
Commentary
Cyclical Outlook
The influence of emerging economies is on the rise, while developed countries are retrenching. Monetary policy in the developed countries will remain extraordinarily accommodative for an extended period, with policy rates pinned close to zero and use of quantitative easing. PIMCO will therefore position its duration and curve strategies accordingly: overweight investments in the developed world, concentrated in the 'belly' of yield curves. In contrast, an increasing share of its positioning in the 'spread sectors' will be allocated to the emerging markets, including their currencies.
Commentary
Stan Druckenmiller is Leaving
The economic drivers that once pumped up asset prices and favored the production of paper over commodities are now retrograde. The reality during Stan Druckenmiller's 'old normal' was that prosperity and overconsumption were driven by asset inflation that in turn was correlated with leverage and interest rates. Investors are now faced with bonds yielding 2.5 percent and stocks staring straight into new normal real growth rates of 2 percent or less. There is no 8 percent there for pension funds. There are no stocks for the long run at 12 percent returns.
Commentary
An Interesting Week Ahead
The failure to reduce risk spreads in peripheral European countries means that the public sector bailout is not working. The list of industrial countries wishing to depreciate their currencies is not matched by a list of emerging economies happy to let their currencies appreciate significantly. As a result, foreign exchange tensions are mounting, and the price of gold has been driven to a new record level. This week will shed light on whether policymakers can do anything to deal with these two issues.
Commentary
Judging Obama, Geithner and Goolsbee
The Obama Administration's announcement Wednesday of its new economic policy initiative will be closely watched by markets and will likely impact equity and bond valuations around the world. A disappointing performance today would be met with even greater market skepticism, higher 'self-insurance' by households and companies and further disappointment among America's friends and allies.
Commentary
Why Another Fiscal Stimulus Won't Do
The main debate in Washington today is whether or not to do more of the same: another fiscal stimulus and another round of quantitative easing by the Federal Reserve. This conflicts with evidence that a broader and more holistic response is needed. Policymakers must address key structural issues, including the drivers of growth and employment creation; the high risk of skill erosion and lost labor productivity; financial deleveraging in the private sector; debt overhangs; the uncertain regulatory environment; and the unacceptably high risks facing the most vulnerable segments of society.
Commentary
Mr. Gross Goes to Washington
Americans now know that housing prices don't always go up, and that they can in fact go down by 30-50 percent in a few short years. Having grown accustomed to a housing market aided and abetted by Uncle Sam, the habit cannot be broken by going cold turkey into the camp of private lending. Private mortgage lenders will demand extraordinary down payments, impeccable credit histories and significantly higher yields than what markets grew used to over the past several decades.
Commentary
When Unconventional Become Conventional
Conventional monetary policy is undergirded by the doctrine of central bank independence, founded on the proposition that fiscal authorities, hostage to the political process, inherently are prone to an inflationary bias. When the economy suffers from private sector deleveraging and a fat-tail risk of deflation, however, conventional monetary policy is not enough. In such circumstances, the central bank has a profound duty to act unconventionally, ballooning its balance sheet by monetizing assets, either government or private, or both.
Commentary
Deciphering Today's Violent Market Moves
Tuesday's Federal Open Market Committee statement confirmed what the high frequency partial data have been signaling for a few weeks now: that the U.S. economic recovery has lost momentum. Expectations have evolved in an interesting manner - from the more familiar bell curve (a dominant mean and thin tails) to a much flatter distribution with fatter tails. In such a universe of expectations, short-term news can have a disproportionate impact on market valuations. When you are potentially on the road to deflation, a small change in probability will have an amplified impact on markets.
Commentary
El-Erian on Why the Payrolls Report Matters
The employment picture constitutes yet another headwind - and a significant one - to the already-faltering U.S. recovery. More Americans are struggling to earn enough to maintain their standard of living. The time has come for Washington to realize that the existing policy mix is not appropriate for the task at hand.
Commentary
Uncertainty Changing Investment Landscape
The unusual uncertainty in the economic outlook reflects the disruptive combination of deleveraging, reregulation, structural unemployment and other ongoing structural changes. It seems that, wherever we look, the snapshot for 'consensus expectations' has shifted from traditional bell-shaped curves to a much flatter distribution of outcomes. This changing shape of distributions affects conventional wisdom in the investment world.
Commentary
Private Eye
The economy's New Normal of deleveraging, reregulation and deglobalization will neither be aided nor abetted by a slower-growing population, or by cyclical policy errors that thrust Keynesian consumption remedies on a declining consumer base. Current deficit spending that seeks to maintain an artificially high percentage of consumer spending can be compared to flushing money down an economic toilet. It would be far better to create and mimic other government industrial policies aimed at infrastructure, clean energy, more relevant education and less costly health care services.
Commentary
Facts on the Ground
What the developed world faces is a cyclical deficiency of aggregate demand, the product of a liquidity trap and the paradox of thrift, in the context of headwinds borne of ongoing structural realignments. Front-loaded fiscal austerity would only add to that deflationary cocktail. And that's what the market vigilantes are wrapped around the axle about: They are not fleeing the sovereign debt of fiat currency countries but rather fleeing risk assets, which depend on growth for valuation support.
Commentary
Stress Test Is No Shortcut to Stability
Will the testing of 91 European banks by regulators stabilize the region's finances? After all, a similar approach in the U.S. last year may have helped normalize financial markets there. The U.S. stress test, however, applied to institutions that were the main cause of the financial instabilities, and the government had budgetary room to support the sector. Europe's concern about banks is a derived concern, reflecting worries about sovereign debt in some countries and the overall economic situation; and there are greater limits today on budgetary resources.
Commentary
The Real Tragedy of Persistent Unemployment
The US faces a low growth/high unemployment trap, which would have four consequences: erosion of skills in the labor force, pressure on social safety nets, dampened spending by those who are employed, and less risk-taking by companies. El-Erian suggests several policy initiatives to combat unemployment.
Commentary
Alphabet Soup
The lack of global aggregate demand ? resulting from too much debt in parts of the global economy and not enough in others ? is the essence of the problem. The solution, according to William Gross, may be to add the letter 'R' to your name (as in Roubini, Reinhart, Rogoff, and Rosenberg) or, better yet, to embrace the words 'New Normal.'
Commentary
Mohammed El-Erian on a Disappointing G-20 Compromise
Mohammed El-Erian digests the 'unusually long communiqu from the G-20 Summit in Toronto.' El-Erian expresses his concerns about the future of a post?global financial crisis world that is in desperate need of better cross-border policy coordination and harmonization.
Commentary
Beyond the Growth Vs. Austerity Debate
This weekend?s G-20 meeting will likely fuel, not resolve, the heated debate triggered by a combination of exploding debt and deficits in industrial countries, and the recognition that many now face a future of muted growth and high unemployment. In one corner stand the 'growth now' camp, arguing that expansion is a prerequisite to service their debt sustainably. Against them stand the 'austerity now' camp, who want budget cuts to lower risk premiums and stave off disruptive debt restructurings. The two sides are both right, and wrong.
Commentary
Sovereign Wealth Funds in the New Normal
Sovereign wealth funds are generally well-equipped to navigate financial markets after the crisis of 2008 and amid current fiscal strains in Europe. Yet they too face potential challenges, as the global economic recovery is unlikely to follow a straight and simple path. How these funds confront these challenges will speak directly to their effectiveness in investing national wealth to benefit current and future generations, as well as their contributions to stabilizing a fluid global economy.
Commentary
Some Unpleasant Keynesian-Minsky Logic
Thirty years ago, virulent inflation demanded robust monetary authority independence, so as to pursue a draconian monetary policy that even disciplined fiscal authorities when their loose policies contradicted the overriding goal of winning the war against inflation. For the past decade, however, a more collaborative relationship between monetary and fiscal authorities has been required in order to cut off the fat tail of deflation risk, notably in recessions. The European Central Bank needs to realize this, even if future policies threaten to unmoor long-term inflation expectations.
Commentary
Can Emerging Markets Save the World Economy?
High growth and financial stability in emerging economies are helping to facilitate the massive adjustment facing industrial countries. But that growth has significant longer-term implications. If the current pattern is sustained, the global economy will be permanently transformed. Specifically, not much more than a decade is needed for the share of global GDP generated by developing economies to pass the 50 percent mark when measured in market prices.
Commentary
On the Need to Listen Carefully to What the G-20 is Saying
The recent G-20 communique is a further confirmation that structural and balance sheet realities are imposing themselves on the global economy. Compared to what the world has known for the last 40 years, this results in a highly unusual configuration of growth, debt and deficits. It also raises legitimate questions about the prospects for self-sustaining private sector recoveries in industrial countries. Finally, it loudly illustrates the limitations of cyclical policy responses and international coordination, as well as associated problems with unintended consequences and collateral damage.
Commentary
Two Will Get You Three (or) Three Will Get You Two
Fiscal tightening and budget conservatism may have come too late for Greece and its global lookalikes. Continued deficit spending may be an exorbitant privilege extended to only a few. Caught in the middle are many developed countries that will likely face muted growth rates and a continued bumpy journey toward their destinations. Investors must respect this rather tortuous journey in the months and years ahead for what it is: a deleveraging process based upon too much debt and too little growth to service it.
Commentary
Return of the Nervous Weekend
Having over-romanticized the cyclical bounce, some investors are now scrambling to reposition their overextended portfolios now that structural problems are undeniable. The disruption in financial markets is not a garden-variety market fluctuation. Instead, it?s an overdue recognition that the global economy faces an uncertain future that involves slower growth and greater government regulation. Structural problems require structural solutions. The question is whether policymakers in Europe will acknowledge this, or remain hostage to hope for an immaculate recovery.
Commentary
Difficult Choices Still Facing Europe
The beneficial impact of last weekend?s $1 trillion 'shock and awe' intervention by Europe to save Greece and safeguard the euro is fading - even more quickly than officials had feared. This is the result of two main factors. First, having analyzed the news out of Europe in depth, markets recognize that the liquidity-based approach cannot sustainably address what is at heart a solvency problem. Second, markets are concerned that short-term stability is being pursued at the cost of long-term viability.
Commentary
Driving Without a Spare
Mohamed El-Erian recounts the results of last week's PIMCO Secular Forum on the three- to five-year outlook for the global economy and the markets. Participants concluded that we are heading toward a world that is re-regulated, de-levered, and growing less rapidly in the industrial countries. It will be a world in which concerns about the dark side of globalization temper enthusiasm for its net benefits, and in which politics matter a lot for markets and the economy. The drama playing out in Europe these days is a vivid illustration of this general secular characterization.
Commentary
After the Crisis: Planning a New Financial Structure - Learning from the Bank of Dad
This commentary contains remarks by PIMCO's Paul McCulley at last month's Hyman Minsky Conference on the State of the U.S. and World Economies. McCulley says that the Federal Reserve, the FDIC and the Treasury all provide public goods to banking by guaranteeing that demand for liquidity will not exceed bank assets. It's quite natural that levered-up non-bank financial intermediaries don't want to be treated like banks. If they are going to have access to the public goods associated with banking, however, then they must follow the same rules that banks do.
Commentary
Understanding the Greek Aftershocks
The Greek crisis has already morphed into a regional shock. It now stands on the verge of morphing into a more global phenomenon. Some countries will benefit, mainly on account of capital flows coming out of the euro area. The majority will not. And even those that do benefit should remain vigilant and responsive. Like most other countries in the world, they will also end up suffering from the consequences of lower international demand and renewed disruptions to the global banking system.
Commentary
Lovin' Spoonful
If a chef were to concoct a gourmet investment recipe, he would likely blend a teaspoon of intelligence with a tablespoon of common sense. The rating agencies in recent years have displayed little of either. In addition, they have brazenly sold their reputations for unbiased judgment to the very companies they purported to judge. Those looking to profit at their expense will dismiss them. They no longer serve a valid purpose for investment companies that are free of regulatory mandates, and that can think with a teaspoon of intelligence and a tablespoon of common sense.
Commentary
Many More Chapters Left in the Greece Drama
Sunday's loan announcements from the European Union and the International Monetary Fund will not mark the end of the Greek debt crisis, nor will they constitute a much-needed turning point that can be sustained for many months. Instead, they will part of the multi-stage process that still has a few rounds left. If design and implementation issues emerge, future rounds may involve a reopening of negotiations and a recasting of the approach in some areas.
Commentary
Greek Crisis Endangers Private Sector
The Greek debt crisis has morphed into something that is potentially more sinister for Europe and the global economy. What started out as a public finance issue is quickly turning into a banking problem too; and what started out as a Greek issue has become a full-blown crisis for Europe. Absent some remarkable change in the next few days, things will get even more complex for the public sector. It may have no choice but to combine its own exceptional financing efforts with talks on a controversial approach that will be familiar to emerging market observers - private sector involvement.
Commentary
Complex Structural Changes in China and the Global Economy
China has come to a point where its size and global impact are large. Policy in China will have to be set within a delicate balancing act between domestic growth and development and distributional challenges on one hand, and recognition of global impacts on the other. The large developing countries need to understand better than they currently do that their growing size and presence in trade in goods and services is forcing uncomfortable structural change in the advanced countries as well.
Commentary
Why the Greek Rescue Isn't Going According to Plan
The triumphant announcement from Greece, the European Union and the International Monetary Fund a couple of weeks ago has not calmed markets, nor has it lowered Greek borrowing costs. Buoyed by a cyclical recovery, markets around the world have yet to recognize the complexity of this situation. When they do, it will also become apparent that Greece is part of a wider, and historically unfamiliar phenomenon ? that of a simultaneous and large disruption to the balance sheets of many industrial countries.
Commentary
Paul McCulley Discusses PIMCO's Cyclical Outlook
In an interview, PIMCO Managing Director Paul McCulley discusses his firm's cyclical economic outlook and its impact on investment strategy. PIMCO's cyclical outlook revolves around two core tensions in the global economy. The first is the huge disparity in the rate of recovery between highly leveraged developed countries and relatively balanced developing countries. The second tension is the resistance to cyclical recovery in the developed world due to deleveraging and other headwinds.
Commentary
Comments Before the Money Marketeers Club: Reflections and Ruminations
In a technical discussion of monetary policy, McCulley argues the 2 percent real federal funds rate constant in the Taylor Rule should be toast. In a world of deleveraging and cash hoarding, it makes absolutely no sense to reward holders of cash with an after-tax real rate of return. May Wall Street relearn the doctrine of profit-motivated stewardship, he says, and unlearn the false god of speculation-driven avarice.
Commentary
Rocking-Horse Winner
Prudent lending must be directed not only towards sovereigns that can escape a debt trap, but ones that can do so with a minimum of reflationary consequences and currency devaluation. A unit of quality credit spread will do better than a unit of duration. Rates face a future bear market if global reflation is successful as central banks eventually normalize quantitative easing policies and 0 percent yields. Spreads in appropriate sovereign and corporate credits are a better bet as long as global contagion is contained. If not, a rush to the safety of Treasury bills lies ahead.
Commentary
How to Handle the Sovereign Debt Explosion
The simultaneous deterioration of public finances in many advanced economies represents a significant regime shift with consequential and long-lasting effects. In 2008 and 2009, governments had to step in to counter the simultaneous implosion of housing, finance and consumption, and now the world must deal with the consequences of how they did this. Governments will not be able to rely on growth or private sector holdings to overcome their debts. Policymakers will need to make difficult decisions about higher taxes and lower spending.
Commentary
Don't Care
A lack of global aggregate demand, brought by twenty years of accelerated globalization, is the fundamental economic problem of our age. Many states have used government debt to make up for shortfalls in aggregate demand. But as the crises in Dubai, Iceland, Ireland and Greece show, not every state is able to pay off its new debt load. Investors should therefore concentrate on states that have lower credit or inflationary risk, such as Germany and Canada, and avoid higher-risk states such as Greece and the U.K.
Commentary
The Ring of Fire
Bill Gross reviews two recent analyses (the Reinhart/Rogoff book and the McKinsey study) of the plight of economies faced with large fiscal deficits. He says that these support PIMCO?s view of the Ne
