More than a decade ago, hundreds of US garage entrepreneurs were working on shoestring budgets to develop drones with dreams of scaling the new technology. Then China’s DJI introduced a small, inexpensive drone with a stable built-in camera.
The market continues to impress, with the S&P 500 reaching another record high despite a surprisingly weak retail sales report. I had to look twice at the numbers because the weakness was broad, including the important control group, with the previous month also revised slightly lower.
America remains the best country in the world to get rich. Some see this as cause for celebration, while others view it as evidence of a broken capitalist system. As an economist, I am less interested in debating whether billionaires (or trillionaires) should exist than in asking what the alternative is.
Governments can print money, but they cannot print credibility. Once investors begin to question a country's fiscal trajectory, borrowing costs rise, confidence erodes, and policy choices become increasingly constrained. The age of cheap debt allowed many governments to overlook these limits. Today, they are becoming harder to escape.
Discounted municipal bonds could expose you to unexpected taxes. Here's what to know before you buy.
Join the experts at State Street Investment Management for an educational webcast exploring sector performance, key macro drivers, and income-focused opportunities that may help support client outcomes.
As private credit further cements its role as a primary source of corporate financing, it will be essential to balance opportunity with prudent risk management for long-term stability and sustainability.
VettaFi today officially completed its acquisition of RAFI Indices, LLC from Research Affiliates Global Holdings, LLC. The deal was originally announced in June 2026. The transaction unites RAFI’s decades of deep, academically grounded intellectual property with VettaFi’s agile, modern indexing infrastructure.
As growth accelerates, the first question a leadership team has to answer is not how big the firm can get. It is where the frontier sits, the exact point at which scale stops generating lift and starts generating drag.
A divorce. A house fire. A serious accident or illness. The death of a family member. Caring for elderly parents. Life events like these are hard and emotionally draining. To make things worse, they also require us to deal with finances and make significant, complex money decisions.
Small-cap equities are winning out against their large-cap counterparts in a classic David versus Goliath ETF battle. After years of mega-cap technology dominance, small-cap equities have delivered investors a historic first half of 2026.
Goldman Sachs Group Inc., Blackstone Inc. and Apollo Global Management Inc. had been working tirelessly for months to draw up debt deals that would help developers of artificial intelligence systems pay for chips from Nvidia Corp.
The yield on 30-year US Treasuries hit the highest in almost two decades, reflecting investor angst over surging government spending, a flood of long-dated bond sales and inflation that’s been stuck over the Federal Reserve’s target for the past five years.
The nation’s affordable-housing shortage is fueling a fast-growing corner of the municipal bond market, as lenders securitize portfolios of multifamily mortgages to free up capital for new loans.
Wealth managers are beating a retreat from private credit and ramping up a search for alternatives, as they continue to reel from sudden exit restrictions at several major direct lending funds earlier this year.
If the bad news is that members of Generation Z can’t afford to buy a house until they are middle-aged — which isn’t really bad news, honestly, but anyway — then the good news is that at least they are investing their money in high-performing assets.
“Think Like An Investor” is chapter 1 of a 5-part series examining the narratives around “investing for the long run. Learning to think like an investor rather than a speculator is not a personality quirk or a matter of taste. It is the entire game, and the good news is that it is a skill you can actually build, starting today.
I’ve said it before, and I’ll say it again: it’s not the political party that matters, but the policies. Investors, I believe, are better served when they focus not on the partisan noise and headlines but the policies that bring about change.
There is no one-size-fits-all approach to choosing between individual bonds and bond funds. The choice depends on an investor’s goals, time horizon, risk tolerance, need for predictable income, and available assets.
Global equity markets continued their strong summer run this week, supported by what has been an exceptionally strong second-quarter earnings season.
For over two decades, US equities have been the global market leader, outperforming the Stoxx Europe 600 by an astonishing approximately 530%. While Europe’s recent comeback has narrowed the gap, the forces underpinning US leadership remain firmly intact. Below, we revisit the case for US versus European equities and reiterate why we maintain our preference for US equities.
The first step in recovery is recognizing a problem. For decades, some U.S. states have had problems with indebtedness. But as we take stock of state finances today, we see many examples of recovery.
This bargain-hunting environment sets up a stark divide for upcoming earnings. Walmart (WMT) remains uniquely positioned as its dominant grocery business continues to draw trade-down traffic from higher-income households, whereas Target (TGT) faces headwinds due to its heavier mix of discretionary home and apparel goods.
For savers, it drives them to seek bigger and bigger returns to keep up with the government’s monetary devaluation. At first, a simple savings account with a relatively low yield will do the trick. But as the dollar loses purchasing power, you need a better return to keep up. So, maybe you stick your money in a higher-interest-yielding CD.
Join the experts at Eaton Vance for an educational webcast that unpacks the nuances of preferreds amid the new Fed regime, geopolitical landscape, and economic backdrop.
Chris Galipeau discusses high-conviction insights that go beyond media headlines.
Hoisington Investment Management — managed by Hunt and Hoisington — sharply reduced its clients’ bond duration and put the proceeds in Treasury bills. That reversal of such long-held opinions deserves serious attention. I will summarize Hunt’s new views and some counterpoints to help you assess his new stance.
Today’s market does not represent today’s economy. The ratio of market value dependent on future economic activity versus present activity has never been higher. These companies have earnings now, but those earnings stem from investments in the future, not present consumption.
US existing home sales fell a little in July, according to data released last week by the National Association of Realtors. But what really stands out when one looks at the numbers is how little they’ve changed over the past three years. This July, homes were selling at an annual pace of 4.06 million. In July 2023, it was 4.08 million.
Patients need financing that is approved on the spot and fits the cost and timing of their specific procedure. This is the gap that a newer class of lenders — including CareCredit, Affirm, Sunbit, and Cherry — has been built to fill. The growth of buy now, pay later healthcare financing over the past two years reflects how quickly demand has caught up with supply.
Gone are the days of capital-light and cash-flow-rich technology businesses such as internet search, e-commerce and social media. The game now is artificial intelligence, and you had better have hard assets and deep pockets to play, the kind of money few companies have laying around.
So let’s do the work the timeline skips, starting with separating what actually happened from what the narrative needs you to believe. Then we’ll ask the only question that pays: should any of it change how you’re positioned this morning?
As investors debate whether and when the Federal Reserve will raise interest rates, market expectations for further tightening are building around the world — and spelling trouble for bonds.
Reasons to be wary about stocks are quickly disappearing and a Goldilocks scenario looks increasingly likely. That’s precisely why it’s a perfect time to hedge against a market priced for perfection.
Gold extended a two-week advance as pared back expectations for further Federal Reserve rate hikes put pressure on the dollar, making bullion cheaper for most buyers.
We are in a debt trap. Our political process can’t reduce spending and/or raise taxes enough to balance the budget, so the debt grows and grows. This has to end, and I think it will do so in the event I’ve called The Great Reset.
Investors are remaining cautious about the markets, according to our U.S. stocks and economy report this month. Our report notes that while investors have continued to pile into the market via strong ETF flows and high margin debt balances, they've done so reluctantly with more subdued attitudes.
Recent trends are sending confusing signals about the health of the U.S. labor market. Since late 2025, the employment/population ratio has moved lower even as the unemployment rate has declined.
The softening inflation data for June and July was broadly supportive of our view that monetary policymakers should keep interest rates unchanged for the remainder of the year. Unfortunately, the picture is likely to become less favorable over the next several months, particularly if oil and gasoline prices continue to move higher. While lower gasoline prices contributed to the improvement in inflation during June and July, they do not tell the whole story.
Whether fixed income investors are focused on locking in yield, managing duration risk, or building resilient core portfolios, bond ETFs have been seeing elevated demand this year.
The arrival of the new academic year prompted me to revisit a piece that we wrote in 2023, which detailed the damage that the pandemic had done to young students. In the years immediately following COVID-19, achievement scores skidded, suggesting that online learning was a poor substitute for time in the classroom.
Many things in healthcare really have gotten dramatically better and cheaper. Sequencing a human genome, for instance, cost close to a billion dollars in 2003. Today, under $1,500, making CRISPR therapy available to treat a plethora of diseases that once had no cure.
In 3Q26, global fixed-income markets continue to navigate a complex backdrop as resilient growth, elevated inflation, hawkish central-bank pricing and the AI infrastructure buildout intersect. Growth remains supported by the US consumer, fiscal spending in Europe and AI-related capital investment, while inflation is expected to moderate through 2026 and into 2027.
Franklin Templeton Institute finds valuations across fixed income sectors becoming more attractive, with all-in yields approaching compelling levels—a signal to consider moving from a short-duration bias toward core bond portfolios.
The US will soon announce unprecedented economic measures against Iran, Treasury Secretary Scott Bessent said, intensifying the Trump administration’s effort to force Tehran’s capitulation after almost six months of war.
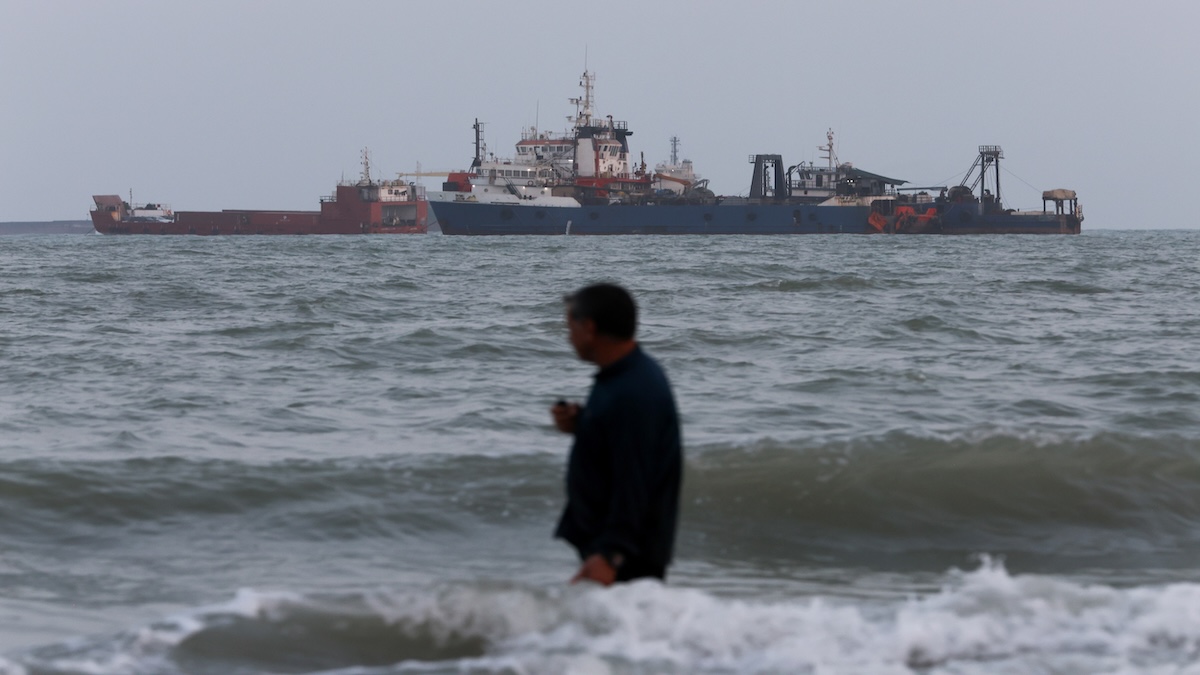
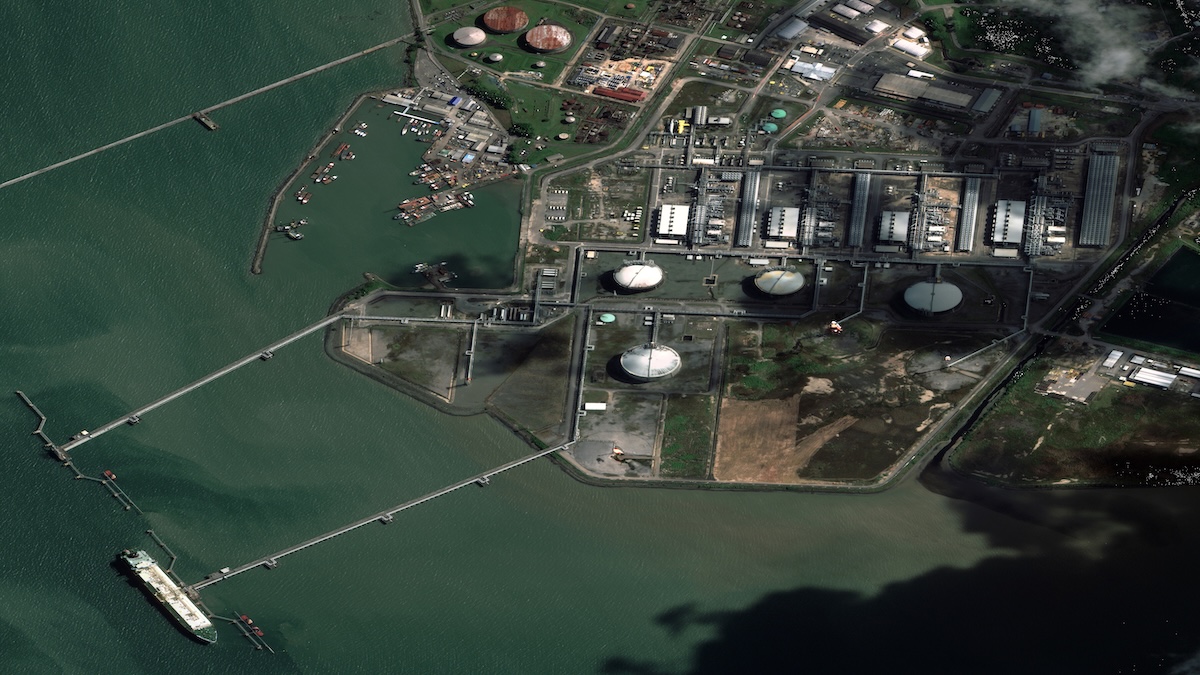
The Venezuelan gas deal comes at a time when prolonged hostilities between the US and Iran have hampered global energy supplies, including about a fifth of liquefied natural gas shipments that normally traverse the war-choked Strait of Hormuz.
Goldman Sachs Group Inc.’s agreement to buy Neos Investments for as much as $2.25 billion marks a new front in Wall Street’s ETF battle: paying up for specialist firms that have found growth beyond the industry’s low-fee giants.
For most high-net-worth investors, the bond sleeve of a portfolio isn't there to generate eye-popping returns or provide cocktail party fodder. Its job is much more mainstream: support a targeted lifestyle, cover tax bills, dampen equity market volatility, and provide "dry powder" when the world turns sideways.
The S&P 500 towed an anchor for much of the summer as a historic momentum and leverage unwind under the surface dragged on the equity benchmark before breaking out to fresh records last week.
The consumer remains resilient, but spending is becoming increasingly selective. Bank of America’s August Consumer Checkpoint showed total card spending per household increased 5.0% year-over-year in July, with spending excluding gasoline up 4.3%.