When a typical business finds its supply chain costs have risen, it will absorb the increase to keep its customers happy. Nvidia isn’t a typical business. It enjoys gross profit margins of 75% and commands between 70% and 90% of the global market for artificial-intelligence chips.
The US economy expanded at an unrevised 1.5% pace in the second quarter, though underlying details showed stronger consumer spending and business investment than initially reported.
Vanguard, known mostly for its low-fee index funds, will add Altruist’s wealth technology and custody platform, the firm said in a statement Wednesday. It didn’t disclose terms.
The future of geothermal energy, a renewable source that has charged up conservatives and liberals alike, is being charted in a scrubby patch of sagebrush, halfway between Las Vegas and Salt Lake City.
Recent Kitces’ research found no meaningful difference in wellness between advisors who worked in a traditional office versus at home or elsewhere. What did matter was alignment: Advisors thrived when they had the flexibility to work in an environment that matched their personal preferences.
Equity markets stumbled this week despite an economic backdrop that continues to show signs of broadening. While concerns about consumer strain are mounting, those worries have so far been offset by ongoing strength in business investment, particularly spending tied to artificial intelligence (AI).
Markets continue to hold up remarkably well as we move through the traditionally difficult second half of August, but the risks beneath the surface have shifted. Commodity prices are rising, money growth remains stronger than I would like, and long-term interest rates are again testing important levels.
It’s been a busy year in the game of ETF landgrab. And a colorful one, too. From exciting M&A deals to some splashy building-from-scratch newcomers, we are seeing a little bit of everything as asset managers look to build scale and capture the impressive growth momentum of the ETF market.
James Carville, Bill Clinton’s chief political advisor, once quipped that if he could be reincarnated he wanted to come back as the bond market because “You can intimidate everybody.”
Interest rates are moving higher, and the forces behind the move appear to be persistent inflation and an economy that continues to grow more strongly than many anticipated. Economic growth is generally advantageous, and moderate inflation is a normal feature of a healthy economy.
When the Electronic Numerical Integrator and Computer, or Eniac, was first built by the University of Pennsylvania for the US Army in 1946, it weighed about 30 tons and had 18,000 vacuum tubes that filled an expansive room.
As the credit cycle ages, defaults are likely to remain front and center. But for investors evaluating private credit alongside public markets, measuring defaults is not as straightforward as it may seem.
We think the gap between women’s confidence and ability underscores that effective plan communications must educate, engage and empower participants across the board. Women may worry more, but they’re clearly knowledgeable and forward-thinking—qualities that can be reinforced. Men may register more confidence but could still use refreshers on financial basics.
Macro strategists and global portfolio managers have their hands full on this final week of August. As we said recently, this is no time to mail it in before Labor Day in the U.S. And for equity traders and bottom-up analysts, NVIDIA (NVDA) writes the storyline in the sessions ahead. The world's most valuable company reports Q2 results after the bell on Wednesday.
This may come as something of a surprise since the financial press has not written or said much about how well this important—and opportunity-rich—subset of small-cap has performed over the last several months.
Join the experts at SS&C ALPS Advisors and VettaFi for a Product Due Diligence Session on August 25th at 12:30 pm ET to discuss midstream defensiveness and the structural tailwinds supporting energy infrastructure.
Today, many clients expect their financial advisor to be involved in the estate planning process — and they’re willing to switch advisors to find one who offers this expertise, according to a July report by digital estate planning platform Trust & Will.
I wrote several years ago that the only thing you can count on the stock market to do is fluctuate, and that the wisest response is usually to do nothing. Looking less often will not change your return. It will make you far less likely to damage the return you already have.
The WealthTech market has a serious AI-washing problem. The term borrows directly from a parallel wealth management executives already understand. Just as greenwashing described investment managers who marketed ESG commitments they could not substantiate, AI washing describes technology vendors who relabel rules-based automation as artificial intelligence.
Kevin Warsh’s first major speech as chairman of the Federal Reserve has become an unexpected trial of his slimmed-down communications style.
US stocks advanced on Tuesday as technology names rallied and investors continued to prepare for Nvidia Corp. earnings and the Jackson Hole Symposium.
Treasuries gained as a decline in crude oil eased inflation concerns and the pressure on Treasury Secretary Scott Bessent, who has been moving to halt a months-long selloff that pushed the longest-dated yields to the highest in almost two decades.
The artificial intelligence trade is booming, and so is the hunt for new ways to diversify AI exposure. Traders can buy power futures, track the technology’s beneficiaries and back data-center real estate projects, alongside buying the usual haul of chipmaker shares.
Yields on 30-year US bonds broke 5% last week, a level not seen since before the Great Financial Crisis. The Treasury Department bought bonds in an attempt to lower yields. It worked — for a day, then bond yields went back up. Meanwhile, in a not-exactly-unrelated development, the US national debt just passed $40 trillion.
In the first part of this series, I promised that the next enemy we would face is the one you cannot fire, mute, or unfollow, because it is “You.” You can learn every valuation metric ever invented, memorize the two questions that decide everything, and still hand most of your returns back to the market for one simple reason.
Chris Galipeau discusses high-conviction insights that go beyond media headlines.
Without a doubt, the number-one story in the financial markets of late has been the run-up in longer-dated Treasury (UST) yields. Indeed, headlines in both traditional and social media have centered on the fact that bond yields are now at levels not seen in nearly 20 years, or the time period right before the Financial Crisis hit in 2007.
The 30-year U.S. Treasury yield has touched roughly 5.3% in the past week, a level not seen in nearly two decades. Global counterparts in Europe, the U.K., and Japan have climbed to similar heights.
For the past five weeks, markets have been focused on a steady stream of corporate earnings, supported by upbeat management commentary and another quarter of strong results. But with second quarter 2026 earnings season nearing its end, investors' attention is shifting back to the macro backdrop.
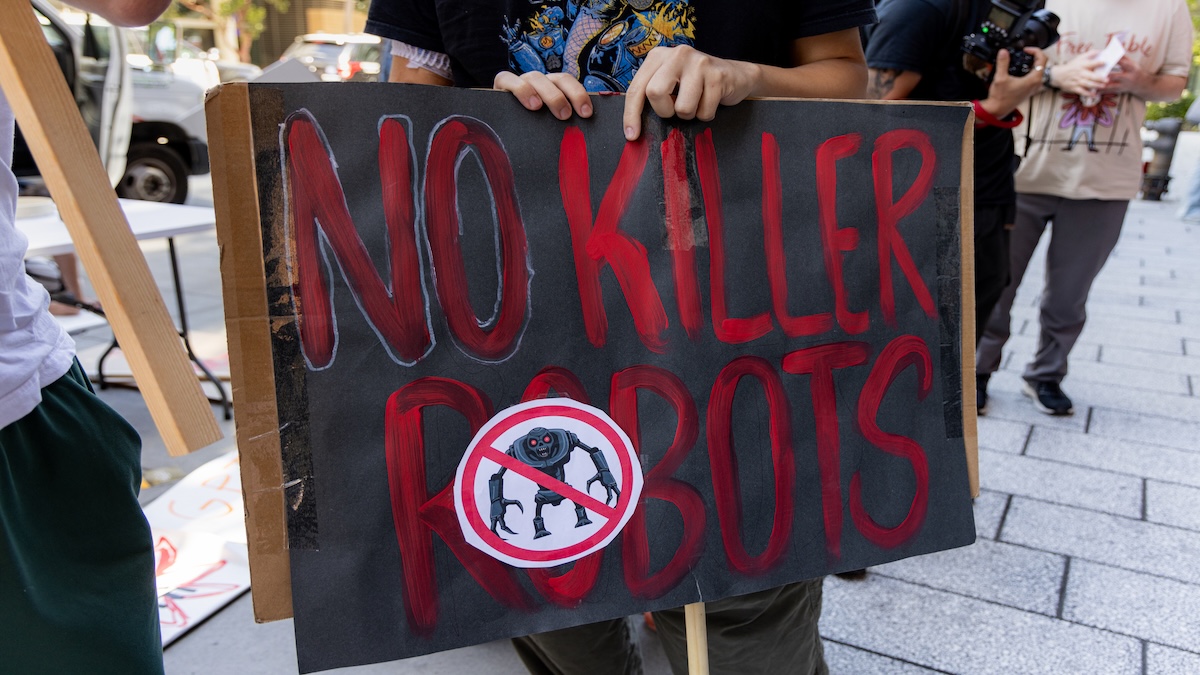
Something strange has been happening in America lately. The Wall Street Journal says this is the summer when the U.S. became “a nation of Luddites.” The Economist calls it “the Summer of Ludd.”
U.S.-listed ETFs pulled in a record $193.42 billion in July, pushing year-to-date net inflows to $1.23 trillion. That total is the strongest seven-month haul on record, according to ETFGI’s July 2026 U.S. ETF industry report.
When it comes to equities exposure, investors typically gravitate toward a passive, market-cap-weighted index as the default strategy. These strategies are often billed as an efficient, low-cost method to capture broad market returns. As such, cap-weighted funds that track the S&P 500 or MSCI World have taken in trillions of dollars in global capital. However, within these market-cap-weighted indexes, a structural flaw exists.
Join the experts at SoFi for a product due diligence session covering the evolving income landscape and how options strategies can help investors pursue monthly income in different ways.
When portfolios become standardized, investor experience becomes standardized right along with them, even though almost nothing else about those investors is standard. Their goals, tax exposure, risk tolerances, and individual spending needs are too individualized to be captured by many models that purport to be customized.
While it is useful to analyze holdings by asset class, a portfolio-wide view can provide additional insights. Typically, the bond sleeve and the equity sleeve are seen as entirely separate. However, they usually hold unnoticed concentrations in different companies.
Amazon.com Inc.’s Andy Jassy has begun making an audacious boast during conference calls this year. Though his company remains a top Nvidia Corp. customer, it’s also one of the world’s largest makers of data center chips in its own right.
US stocks traded lower before the bell on Monday as investors prepared for a busy week of economic data and important earnings from Nvidia Corp.
The question facing advisors is no longer whether clients can hold digital assets, because many already do. It is whether the firm can explain, in writing, how each position was sized, why a particular product was chosen, and where that decision is recorded. Most firms cannot, and that gap is the exposure.
The Treasury Department could opt to draw down some of its cash pile to fund expanded buybacks of higher-yielding, older securities, CNBC reported Monday, citing two senior Treasury officials.
The debt problem is real. It just isn’t a bomb. As we’ve written before, the debt and deficit problem isn’t what you think. It’s a tax on future growth, collected slowly, and normal interest rates are simply the price of money doing its job, not the crisis the headlines keep selling.
Most of us try to be mindful not to put all our eggs in one basket. But the now-familiar concern that most portfolios are quite concentrated in a relatively small group of large US tech companies means that investors may still be doing just that.
Today, the backdrop for real assets has reset. Growth is returning, but in different parts of the market than many investors remember. While in the post-pandemic period performance was defined by scale, now it is the result of adaptability and having access to a broad array of organization sizes and business plans.
The minutes from the most recent Federal Open Market Committee (FOMC) meeting, released this week, revealed a committee that remained broadly hawkish. Policymakers continued to characterize inflation as elevated and emphasized that upside inflation risks persist.
No doubt, AI can be an unnerving tool. But it isn’t magic, malevolent, or secretly sentient. With some reasonable rules in place, policymakers should be able to keep the bots in line, and unleash the benefits for everyone else.
To some, the debate over inflation targeting is largely an academic exercise. But its outcome will have direct consequences for the paths of global interest rates and global markets. Some background on how we arrived at this juncture, and where we might go from here, follows.
In this video, Chuck Carnevale examines 20 fast-growing businesses that appear reasonably or attractively valued, focusing on the GARP principle—Growth at a Reasonable Price. The central message is that investors shouldn’t simply look for great companies; they should look for great businesses at sensible valuations.
On the first few trading days of every month, America’s paychecks hit the stock market. Most 401(k) contributions now default into index-tracking funds, which buy the same stocks in the same proportions whatever the price.
In the early weeks of Kevin Warsh’s start as chair of the U.S. Federal Reserve, there has been renewed focus on how “underlying” inflation should be measured to guide decisions on interest rates.
On the back of the White House’s cryptocurrency confab, which brought together policymakers and leaders of the digital asset community, Bitcoin notched a double-digit gain over August 19-20 — a rally that pumped new life into the largest digital currency.
For 11 of the 12 years following the 2008 financial crisis, U.S. stocks beat international markets. But that trend has flipped: Over the past four years, international equities have taken the lead.