In this article, Russ Koesterich explains how strong fundamentals have supported stocks, but rising bond yields may soon begin to challenge market valuations.
Interim data takes center stage, with Costco, Ford, Robinhood and Charles Schwab offering fresh reads on consumers, autos and retail trading
US Treasury Secretary Scott Bessent made waves with his recent announcement that the Treasury would at least double the size of its buybacks of long-term debt in the coming months. He argues that long-term yields do not reflect fundamentals, suggesting that the Treasury's intervention is aimed to restore proper market functioning.
Markets opened on a sour note on Monday after Treasury Secretary Scott Bessent unveiled “Operation Economic Outcast.” This initiative was to include sweeping sanctions against Iran and the networks that enable the regime to evade existing restrictions. Bessent did not explicitly mention Iran’s enablers, but many assumed China was the primary culprit.
It’s back-to-school season, and the ETF market is closing out a summer that proved anything but slow. August brought $180 billion in fresh net ETF asset inflows and saw the number of new ETFs coming to market cross 1,000 for the year. August also saw a barbell strategy against macro risks become a popular approach with ETF investors.
The recent IPO of SpaceX and the anticipated IPOs of Anthropic and OpenAI are focusing attention on how to invest following a liquidity event. Here, we discuss several important decision points.
August was a good month in financial markets, with the S&P 500 up around 2.7%. The market leaders came from the commodity complex, with gold and bitcoin (not sure how this should be classified) being the two top performers.
This summer has delivered "blockbuster" returns, both positive and negative, while the possibility of quick and seemingly easy gains continues to draw investors toward speculative areas of the market. In his latest insight, Richard Bernstein, Global Head of Macro & Customized Investing, shares five charts that cut through the noise and highlight important shifts in credit creation, inflation, global growth, market leadership, and asset class performance.
The future of financial planning is not about advisors becoming therapists. It is about advisors becoming better facilitators of meaningful, structured conversations that lead to better decisions. You don’t have to start with perfect skills. Start with a better process.
There are ways to learn how to work with difficult people. I have a process I call ARTICA that I teach to help you shift your approach when someone is being difficult. Their behavioral style isn’t going to change, so you need to be the one to think of a different approach to see if you can shift yours. In turn, they might change their approach.
The firms I see succeeding with AI right now aren't the ones with the flashiest assistants. They're the ones whose compliance officers helped design the architecture instead of it being handed over after the fact. That single change — inviting compliance into the build, not just the review — is the difference between an AI program you can defend and one you're hoping no one ever questions.
Record fixed income ETF inflows in August pushed year-to-date ETF totals past $1.4 trillion, with short-term bonds leading the surge.
Billions in federal support are flowing toward nuclear energy, but most investors can't tell you which companies actually receive it. When a $17.5 billion manufacturing loan program was announced for AP1000 reactor supply chains, social media tagged the wrong tickers entirely. This session breaks down where that capital is really headed and how a thoughtful approach to index construction can provide more focused exposure to companies benefitting from that headline number.
Americans like to spend money, and they’re good at it. But they also feel kind of bad about it.
Investors are being offered a new way to bet on space via a fund that focuses exclusively on a sector thrust into the limelight by the IPO of Elon Musk’s SpaceX.
US stocks flipped between small gains and losses on Wednesday after a three-day skid, as oil prices halted a sharp advance, easing inflation concerns as traders weigh the Federal Reserve’s potential path for interest-rate hikes.
Federal Reserve Chairman Kevin Warsh used his keynote speech in Jackson Hole, Wyoming, last week to map out some of the key data points he leans on to read the US economy, offering new insight into his approach to policy making.
Most people experience transportation through roads and airports. Traffic jams on highways and delays at major hubs are familiar frustrations. But the world's most important transportation network lies largely out of sight.
Kevin Warsh’s Jackson Hole speech was notably hawkish. But I came away from the speech even more confident in Warsh and thought it was one of the best speeches I’ve heard from a Federal Reserve chair. Most importantly, Warsh is refocusing on factors missing from the Fed’s framework for years: an explicit recognition that money supply and bank credit matter for the Fed’s inflation outlook.
Highly concentrated US equity markets have been a consistent theme in recent years. Now, after the latest reconstitution of a major US equity benchmark, concentration is taking on a new form, with the Magnificent Seven’s grip loosening and semiconductor stocks gaining more influence. In essence, millions of passive investors received a new portfolio without making a single decision.
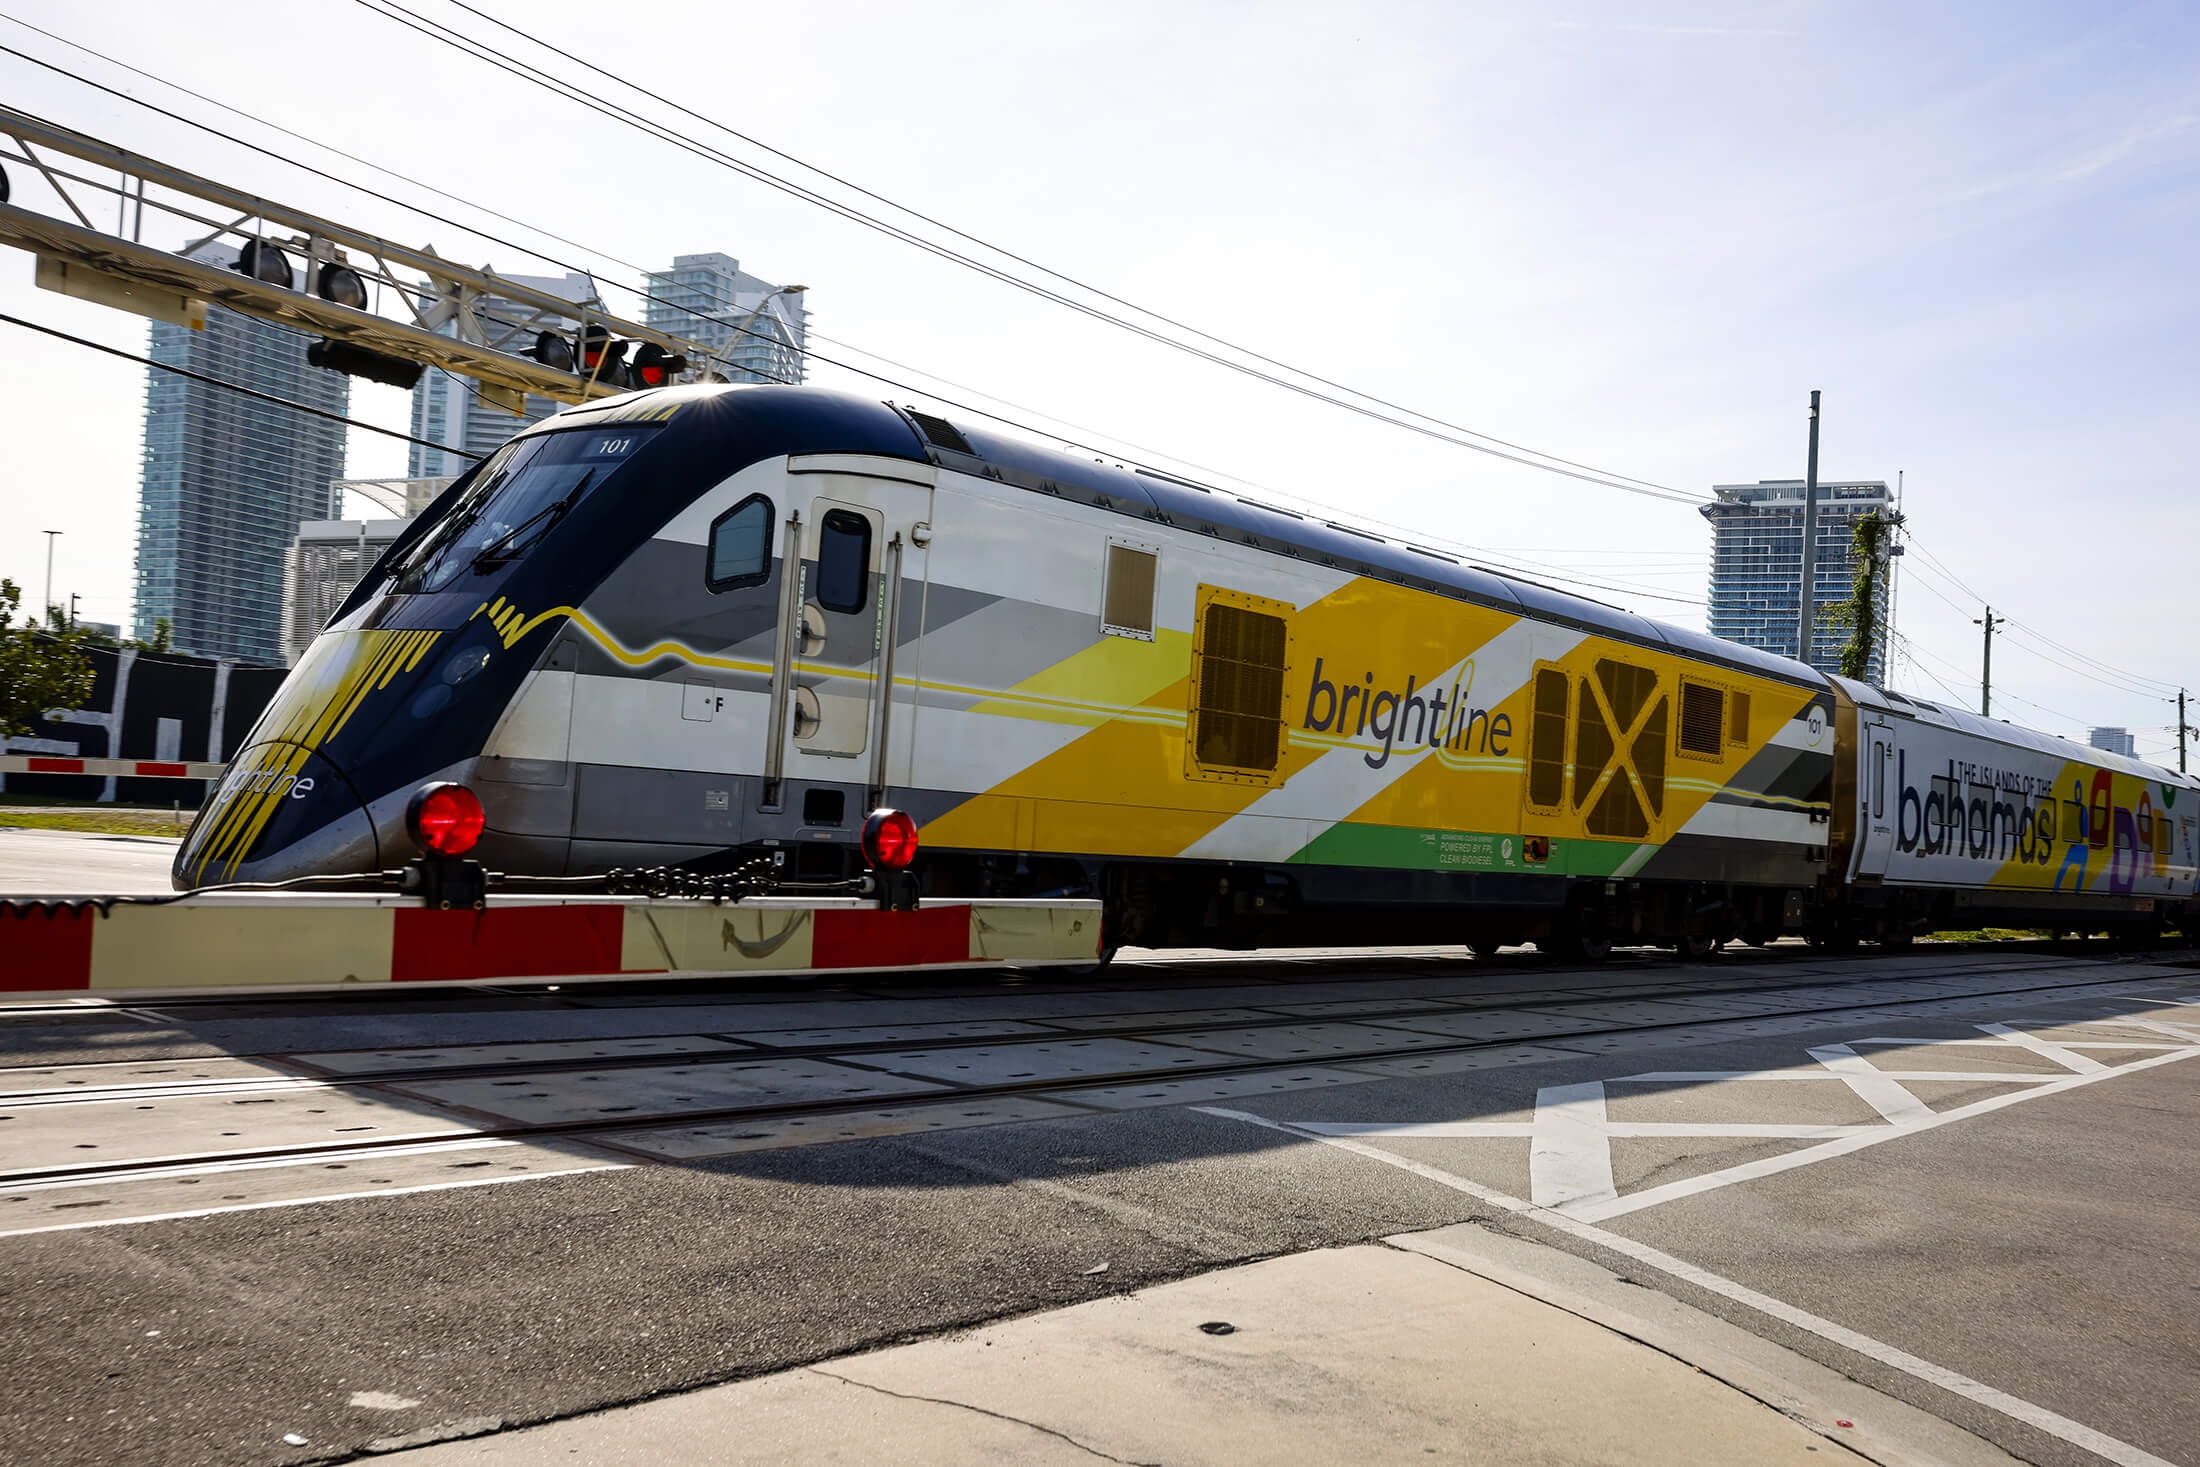
Brightline has reached a deal with municipal-bond insurer Assured Guaranty Ltd. that would provide the debt-laden Florida railroad with at least $350 million in new loans if it heads into Chapter 11 bankruptcy, according to people familiar with the matter.
AI-driven scarcity is allowing companies perceived as lower quality to post the revenue growth, margin expansion and rising returns that investors associate with quality, lifting estimates, multiples and stock prices.
The high-yield market appears expensive at first glance. Spreads sit near the tight end of their historical range, which implies limited compensation for credit risk. However, spreads relative to their historical levels do not capture the full opportunity set of the asset class. Corporate fundamentals remain healthy, defaults are low, and the quality of today’s high-yield universe is higher than its long-standing reputation might suggest.
The backup in global yields since late February has reignited the debate over the potential knock-on effects for corporate borrowers, particularly through higher refinancing costs and weaker debt-servicing capacity.
Should the recent value rotation be viewed as a regime shift-driven change in market preference, or a simple reversal trade? We think there is a compelling case to be made for the former. In a regime of higher interest rates and stubbornly above-target inflation, the market is increasingly focused on capex intensity, free cash flow conversion, and the cost of capital.
State Street’s top inflows for its SPDR ETFs during the year-to-date period and the past four weeks suggest that while investors have confidence in U.S. large caps, they’re still looking to hedge their bets by allocating to gold.
The autism care economy is expanding across healthcare, technology, education, and behavioral services. As a result, investors are beginning to look at the companies serving it through a broader investment lens.
Artificial intelligence is quickly becoming a bigger part of financial advisors’ workflows, but the technology is still in the early stages of adoption. LPL Financial experts share how agentic AI can help advisors with workflows
Advisors who build a third-quarter planning call into their process tend to see fewer IRS notices land on their clients' desks. Tax season teaches clients to think about taxes once a year. The advisors who win their trust are the ones who think about taxes all year round.
An estimated $124 trillion is expected to transfer through 2048, including about $105 trillion to heirs. We have spent a great deal of time estimating the value that will transfer from one generation to the next. However, if advisors expect to maintain the value received, we should be equally interested in whether the value we provide in exchange is evolving with it.
Billing and compensation may not be glamorous, but they're foundational. And for leadership teams, the question isn't only whether software can be built faster with AI. It's whether they want to own the budget volatility, compliance exposure, integration complexity, support responsibility, and distraction of running an internal platform this close to revenue.
There is a reasonable argument that population decline is not a catastrophe. Fewer people means less pressure on housing, energy, and food. Automation may cover some of the missing labor, and countries have absorbed demographic shifts before. Those adjustments take decades, though, and you will likely retire before they finish.
Regional lenders Truist Financial Corp. and Fifth Third Bancorp. have paused distribution of products tied to billionaire financier Mark Walter’s biggest insurance firm, according to people with knowledge of the decisions.
In Part I of Indexing Redefined, the foundational strategies comprising Research Affiliates’ fundamental indexing methodology (RAFI) were introduced. With the baseline premise established, there is one myth to debunk: Some detractors may assume that RAFI is merely a niche value strategy.
Not since 2006 have yields on the longest-maturity Treasuries been this high for this long, with a gaping budget deficit, another wave of corporate issuance and a potentially decisive Federal Reserve meeting set to keep investors wary of US debt in coming weeks.
T. Rowe Price Group Inc.’s chief executive officer sees tax-loss harvesting strategies as a growth area, but remains confident that its offerings won’t draw regulatory scrutiny.
An almost-vertical rally in gold-miner stocks in the past month is whetting the appetite of investors who have been whipsawed by messages from Washington policymakers.
As government bond yields across the world erupt, corporate credit has rarely looked calmer. Yet even in that market, about $1 trillion of bonds are telling a much different story.
Massive AUM may earn an RIA a buyer’s attention, but it does not automatically earn a premium valuation in the rapidly evolving M&A landscape.
The first two articles in this series were about behavior. This one is about arithmetic. There are three numbers that decide most of your investing life. Let’s do the math Wall Street skips, one number at a time.
Despite ongoing geopolitical tensions, growing questions about the scale of AI-related spending and steadily rising bond yields, market volatility remained remarkably subdued this summer.
Federal Reserve Chairman Kevin Warsh used his Jackson Hole speech last week to lay out what he thinks of monetary policy. Two things jumped off the pages of his speech.
A credit-allocation problem is complicating the Fed’s dual mandate, with current policy restrictive for many consumers and weaker borrowers, but less so for large corporates, higher-quality issuers, and borrowers with access to private credit.
In a week that saw NVIDIA, the largest company in the world, report strong earnings that sent its stock sharply higher and reinvigorated optimism in the artificial intelligence (AI) trade, fiscal and monetary policymakers continued to provide the biggest headlines.
As the month of August came to a close, the first index mutual fund got to celebrate a key milestone. The mutual fund in question is the Vanguard 500 Index Fund (VFINX), which originally launched on August 31, 1976.
A hard line on trade was a popular plank of the first Trump candidacy. But once in office, his advisors used slow, conventional investigations and negotiations toward the goal of fairer terms of trade.
Beneath relatively muted index-level volatility, single-stock implied volatility remains high. In today’s low-correlation environment, individual stocks are moving more independently, keeping single-name volatility high even as those moves offset at the index level.
San Antonio has been my adopted home for close to 40 years now. I’ve watched it grow through more than one boom cycle, but recent Redfin data suggests we could be looking at a bust.
Join the experts at CIBC & Precidian Investments for a product due diligence session exploring their ADRhedged ETF (ADRH).
Over seven years ago, I wrote a piece using the 1960s TV sitcom Gilligan's Island to provide a simple example of why productivity is the most important driver of economic growth. In this article, I present the next episode of Gilligan’s Island, describing what happens after the benefits of innovation stop driving economic growth.