The future of retirement planning is not a new model replacing an old one, but a more holistic approach that blends rigorous analytics with important client input. Advisors who adopt this integrated model will find that it deepens client conversations, clarifies tradeoffs, improves long-term decision-making.
The latest inflation report points to a hard truth: The US is not going back to a 2% inflation rate anytime soon. At least not easily.
Periods like this can feel especially tense, with higher stakes and more urgent headlines. Yet over time, markets have shown they are forward-looking and resilient, absorbing uncertainty rather than freezing in it. While today’s geopolitical backdrop may feel unsettling, it fits a long history of disruptions that markets have ultimately navigated.
On September 2, TMX VettaFi Head of Research Todd Rosenbluth appeared on the Schwab Network to discuss ETF inflows nearing record highs in 2026 and the 50th anniversary of the first-ever index fund, the Vanguard 500 Index Fund. The fund’s ETF share class, which trades under the ticker VOO, is a bit newer, having launched in 2010.
Chris Galipeau discusses high-conviction insights that go beyond media headlines.
Most coverage of Trump Accounts treats them as a parenting question, or a discussion comparing them to 529s. For founders and business owners the analysis of them is slightly more nuanced.
Demand for fixed income ETFs hit a historic high-water mark in September. Investors and advisors turned to fixed income ETFs at a record-breaking pace, driving 2026 net inflows of $446 billion past all-time levels with months to spare. The massive tide of capital arrives at a critical juncture.
In our final chapter for this series, we will dig into that exact question. Unfortunately, there is good and bad news, and it can be summed up in a single sentence.
Is the AI infrastructure buildout one big trade in credit? So far, the market seems to think so. Spread dispersion – differences in borrowing costs among issuers – across the financing chain remains limited despite sharp differences in underlying risk. This contrasts with equities, where performance has become increasingly differentiated.
Last week, the refining margin on European gasoil, the benchmark that sets the price of diesel and heating oil across much of the world, closed at roughly $94 a barrel over Brent crude, according to Bloomberg data. That figure is normally somewhere between $12 and $18.
As policymakers adapt to new leadership, navigate a challenging geopolitical backdrop and contend with meaningful internal debate over the path of interest rates, the stakes remain high. Below, we discuss what to expect from next week’s Federal Reserve (Fed) meeting and provide perspective on the recent rise of Treasury yields to multi-year highs.
Attractive yields and resilient credit conditions are creating opportunities across fixed income, but uncertainty around inflation and interest rates makes flexibility, selectivity and disciplined risk management especially important.
In Part III, the focus will center on practical applications of this discipline. In particular, how advisors can integrate the methodology into modern asset allocation, and why it offers an evolutionary leap for passive investing that’s available through exchange-traded funds (ETFs).
According to new data from J.P. Morgan Asset Management’s 2026 Defined Contribution Plan Participant Survey, 73% of savers said they wish they could hit an “easy button” and fully delegate their wealth management.
Join the experts at Swan Global Investments and VettaFi to explore active, uncapped defined risk strategies and how they can help advisors navigate today’s challenging market environment.
As I go through the strengths and weaknesses of each model, my goals are to point out where the models are strong and to point out potential weaknesses such as conflicts of interest, which are important to be aware of in working with clients. Although we are all fiduciaries, financial incentives matter because we are all human. I know great advisors across all fee models.
Heading into the September 16 FOMC meeting, the debate over whether the Fed should raise rates or hold is heated. To help you appreciate the range of views, I present this article as a courtroom exercise. I will let the prosecution make its case for a rate hike, and the defense for a hold.
ETF share classes represent a structural innovation that combines the benefits of mutual funds and exchange-traded funds (ETFs) within a single pooled portfolio. This evolution expands investor choice, offering both ETF and mutual fund shares under a unified investment strategy.
Many market participants have highlighted how value investing is back as the equity market rally broadened out beyond high-flying growth names. However, taking an index-based approach to the value style requires looking under the hood. Not all value ETFs are created equally.
Market madness has never been hard to diagnose. It’s almost two centuries since Charles Mackay published Extraordinary Popular Delusions and the Madness of Crowds. Benjamin Graham pioneered value investing in the 1930s by inviting everyone to think of “Mr. Market” as a manic-depressive who makes mistakes that can be exploited.
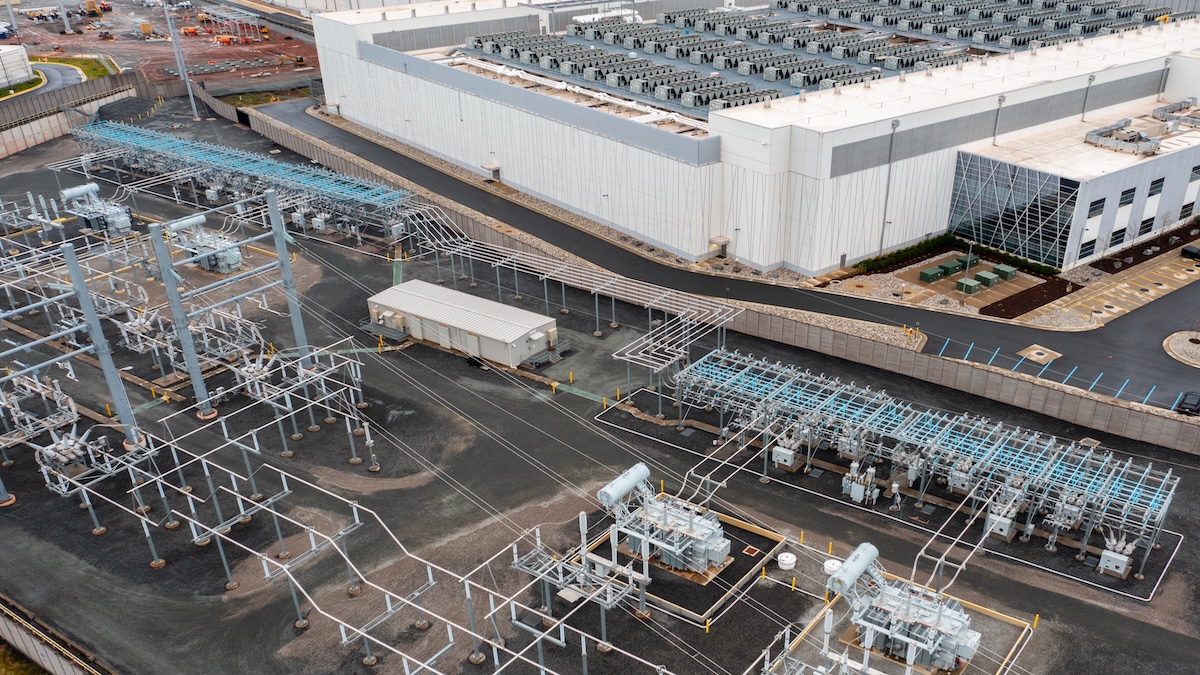
America’s data center boom will need $110 billion to build 45 gigawatts of new power generation through 2030, according to an analysis by Moody’s Ratings.
The list of challenges confronting Wall Street piled up this week. Oil firmly above $100. Inflation refusing to disappear. A defiant bond market that all but dared Scott Bessent to bring more policy firepower.
China criticized warnings from leading US technology executives to put the brakes on artificial intelligence development and claims that Chinese progress posed a dire security threat to the world.
The bond selloff has driven a key Treasury yield to the verge of 5%, worsening angst from Wall Street to Washington about higher borrowing costs hitting the US economy.
For many investors, a 401(k) is simply a retirement savings account. For high-net-worth families, however, it can become a sophisticated planning tool that supports tax efficiency, wealth accumulation, and long-term legacy objectives.
Every few months, a new essay declares that the US debt trap has finally sprung. The latest one making the rounds from The Economist is well written and genuinely unsettling. It argues that Washington has borrowed so recklessly that the Federal Reserve no longer dares to raise interest rates. Doing so, the piece warns, would detonate the whole structure and send financing costs spiraling out of control.
Equity markets generally moved lower as rising yields and energy prices created a more challenging backdrop. Higher yields can be particularly difficult for long-duration equities, where a greater share of expected cash flows sits further into the future.
Some investors are questioning how much further this year’s rally can run with the S&P 500 Index up 12.3% through the first eight months of the year. Encouragingly, history suggests that strong starts tend to persist; when the S&P 500 has gained more than 10% through August it has advanced from September through December in 25 of 28 instances, an 89% positive hit rate.
Occasionally, we are confronted with decisions where there are no easy options. The prevailing circumstances bound our choices, and we may face criticism no matter what we do. Collectively, the Federal Open Market Committee (FOMC) finds itself in just such a situation as it prepares for its upcoming meeting.
The recent employment report provided reassurance that the US labor market remains resilient. The economy added 162,000 jobs in August; the previous two months’ gains were revised higher by a combined 55,000, and the unemployment rate held steady at 4.1%.
How can investors recognize when a stock is severely overvalued—and decide whether it may be time to take profits?In this video, Chuck Carnevale, co-founder of FAST Graphs and “Mr. Valuation,” examines 22 popular stocks that appear overvalued or have recently begun correcting.
Investors can’t get enough of ultrashort bonds. Driven by concerns over high equity valuations and rate volatility as the U.S. Federal Reserve mulls over the direction of interest rates, capital preservation strategies appear to be the elixir to help ease uncertainty. As such, ultrashort bonds have been seeing greater demand as traditional safe havens fall short on yield or carry unwanted duration risk.
There is so much going on, it is hard to know where to begin. The data is all over the place. I had a long and epic dinner in New York with David Bahnsen, Rene Aninao, and Brian Syztel which has my mind buzzing with ideas and new concepts.
One or a few high-performing stocks can provide a big boost to portfolio values. But they’re hard to come by and often struggle to maintain their momentum over time. Because these stocks increase portfolio concentration, investors must balance the risk of overexposure against the tax cost of diversifying. A thoughtful, tax-aware plan may help bring portfolios back in line.
Don't let September's macro headline noise fool you. Today’s economic backdrop won’t likely trigger a broad market freeze like 2022, but there will be winners and losers. Cash-rich mega-caps, AI infrastructure plays, and scaled market leaders (the SpaceX, Anthropic and OpenAI tier) command their own gravity.
U.S. equities were little changed on the week – the S&P 500 rose 0.1 per cent, the NASDAQ gained 0.4 per cent, and the Russell 2000 added 0.12 per cent – but those modest moves masked a far more turbulent week in the global rates markets.
With a handful of stocks attracting most of the recent headlines, it’s easy to forget that investors continue to find opportunities across a broad range of sectors.
US convertible bond sales have reached their highest annual total on record, according to data compiled by Bloomberg, as companies look to fund heavy artificial intelligence-related spending.
Wall Street has a rule for how equity bull markets end: the economy rolls over or the Fed tightens until something breaks. Neither is in place right now, but rate risk is creeping back.
US stocks fell for a fourth straight day, their longest slide since June, as the relentless climb in oil prices and fresh evidence of sticky inflation boosted Treasury yields and bets the Federal Reserve will lift interest rates.
A quarter-century after the Sept. 11, 2001, terror attacks, families returned to the World Trade Center site on Friday to read aloud the names of the dead, marking a milestone anniversary of a tragedy that reshaped America.
A key gauge of US consumer prices rose by more than expected last month, bolstering the case for Federal Reserve officials to raise interest rates next week.
As wealth management firms scale, sustained organic growth increasingly depends on strong business leadership. Firms that build scalable client acquisition strategies, develop talent and create operational infrastructure can position themselves to grow beyond founder-led models and capitalize on the industry’s long-term opportunities.
History suggests slower Fed tightening tends to support stronger market returns and firmer economic growth, while faster hikes typically deepen drawdowns.
While the name is new, Syzygy is not. Syzygy, formerly Research Affiliates, will extend our multi-decade sub-advisory relationships in asset allocation and long-only active equities and expand into other active diversification strategies in the coming quarters.
In this article, Russ Koesterich argues that momentum remains supported by strong earnings growth, making the factor attractive despite market risks.
Portfolio Managers Jonathan Coleman and Aaron Schaechterle outline why they believe momentum in small-cap stocks relative to large caps can continue, highlighting favorable earnings growth prospects, appealing relative valuations, and other structural tailwinds.
2026 began with 10-year Treasuries right around 4%, which many viewed as a comfortable place. The comfort came from some simple math—2 plus 2 equals 4. The long-term real yield on the 10-year Treasury was around 2% and the Fed’s inflation target is 2%.
Market volatility persisted in August as investors were again forced to reassess escalating tensions and an exchange of military strikes in the Middle East, while softer labor-market data was countered by mixed inflation readings.
With so much attention focused on what the Federal Reserve (Fed) might do at its policy meeting next week, it’s a good time to look back at history to get a sense of how stocks might respond should the Fed hike rates as the market (barely) expects.