Oil prices climbed further Tuesday, with Brent crude rising 1% to $97.95 a barrel and briefly touching $99.46, according to the Associated Press. The benchmark has climbed from around $72 over the past two months. Fighting tied to the war with Iran has clouded hopes for reopening the Strait of Hormuz to tankers.
The S&P 500 gained 2.7% in August 2026 and four indexes hit all-time highs, but only five of eleven sectors rose and the Fed’s speech at Jackson Hole put a rate hike back on the table.
The U.S. ETF market reached $16.4 trillion in AUM in August 2026, driven by record product launches and a defensive shift to Treasuries.
Chris Galipeau discusses high-conviction insights that go beyond media headlines.
Stock investors are caught between the pull of strong earnings and mounting macroeconomic risks, with key events carrying binary outcomes that argue for some protection.
A sudden reversal in momentum for previously high-flying shares of industrial companies over the past three weeks has some investors bracing for more pain ahead.
If you look deeply into a speculative bubble, you can already see the collapse. If you look deeply into a market collapse, you can already see the bull market. The road up and the road down are the very same road. Even so, aside from knowing that our investment position presently requires a safety net regardless of shorter-term conditions – we have utterly no opinions, preferences, or scenarios about the market outlook even a month or a quarter from now.
I haven’t always taken the most conventional approach to economics. In a world where many practitioners construct elaborate models to arrive at conclusions, I often find more value in simply following my instincts. During stressful times and paradigm changes, thinking outside of the equations is essential.
My goal with this letter will be to not interrupt your long weekend too much. But there are some things that are happening that are important. My basic thesis for quite some time has been that we are in a Muddle Through Economy, which I’ve always meant that to me the GDP will grow slightly south of 2% over time.
The “K-shaped” divide endures even as it evolves. Higher-income households keep benefiting from equity gains, home price appreciation, and solid earnings, while lower-income households face mounting pressure from elevated costs and tighter credit. But recent data suggest the story is becoming more nuanced.
For the past six weeks, we’ve walked through the forces creating America’s K-shaped economy, housing, healthcare, education, wages, incentives, and the political consequences when enough people decide the system is not working for them. This week let’s look at the situation from a more optimistic angle.
Sift through the filings of pension funds and insurers around the world and one thing stands out: some of the biggest holders of US assets have little protection against a weaker dollar, leaving the currency at risk of steeper declines if sentiment suddenly turns.
US job growth surged in August and the unemployment rate held steady, suggesting the labor market has more momentum than previously thought.
US stock futures erased early gains to briefly touch session lows on Friday after the US added 162,000 jobs in August, raising concerns that the Federal Reserve may hike interest rates soon.
Global fixed income and equity ETF strategies posted gains and saw inflows surge in August, even amid ongoing macroeconomic turbulence and elevated long-term borrowing costs. International equities maintained their year-to-date lead over U.S. stocks throughout the month, led by notable strength in emerging markets.
Stocks have enjoyed a powerful run off the spring lows and have largely shrugged off concerns around growth, inflation, higher interest rates, the effects of artificial intelligence (AI), geopolitics, and policy uncertainty. As the calendar turns to September, however, they are entering what has historically been, from a seasonality perspective, the most challenging month of the year for equities.
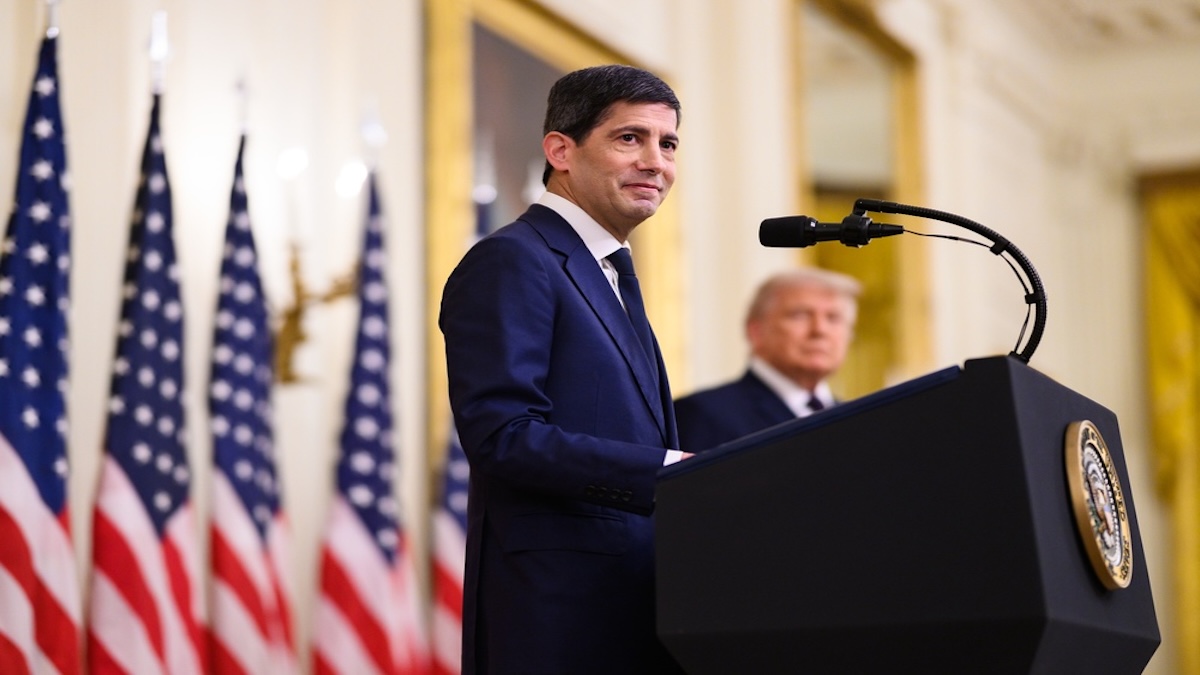
Kevin Warsh's Jackson Hole speech struck a decidedly hawkish tone and was arguably the clearest signal yet that the Federal Reserve is actively considering additional tightening. Markets responded by raising the probability of a September hike to roughly 60% and pricing approximately 60 basis points of cumulative tightening through the middle of next year.
With recent data weakening the case for an immediate increase in rates, markets have sharply pared expectations for near-term tightening, with a hike no longer fully priced before early 2027.3 This moderation in rate-hike fears has been supportive for gold.
The saying “May you live in interesting times” is becoming relevant in the bond market for all the wrong reasons. “Interesting” usually means “trouble.”
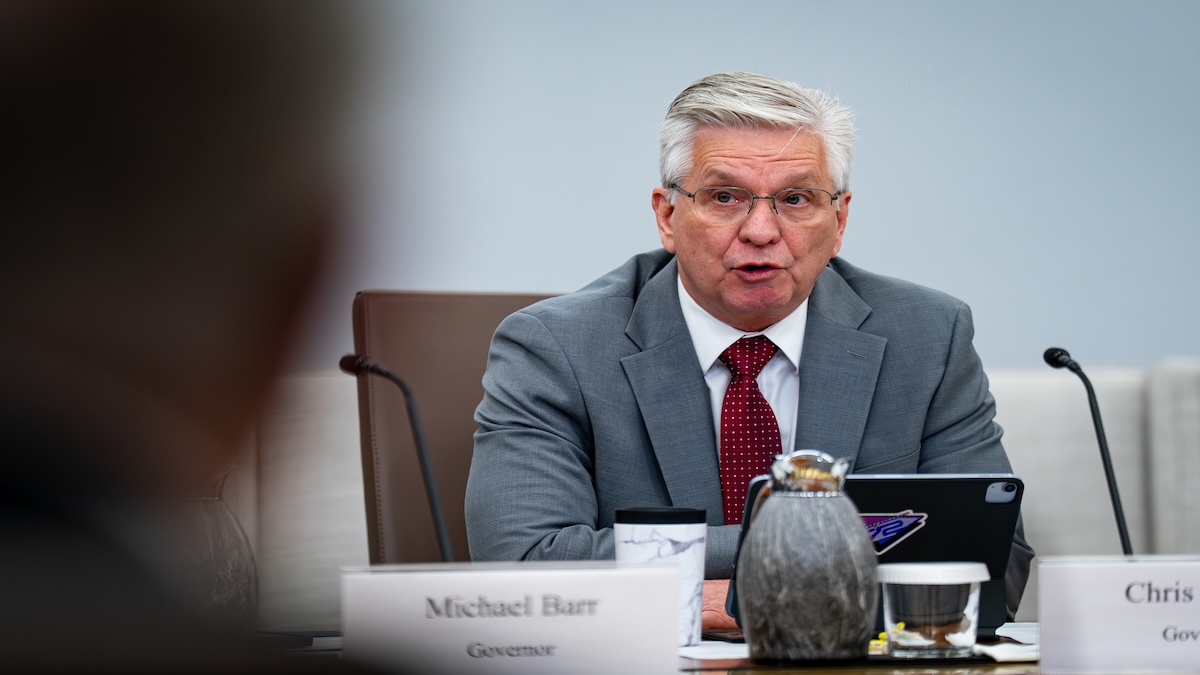
Federal Reserve Governor Christopher Waller said his next decision on interest rates will be “heavily influenced” by August inflation data due next week, adding it may not take much to nudge him toward supporting a rate hike at the Fed’s upcoming policy meeting.
US stock futures posted modest gains Thursday as bond yields stabilized near multi-year highs and investors digested latest commentary from Federal Reserve Governor Christopher Waller. Chip stocks fell after Broadcom Inc.’s results.
House poised to pass bill to avoid government shutdown, two new members set to join the House, Fed chair speech boosts rate hike possibility, and national debt hits $40 trillion.
The month of August reminded many investors that the markets rarely move in a straight line. A combination of encouraging economic fundamentals, uncertainty in the bond market and renewed geopolitical turmoil led to increased volatility and shifting market leadership. But the underlying backdrop reinforced that the US economy continues to expand at a sustainable pace.
The topic d’jure is that Kevin Warsh just gave his first Presser (Oh yes, we love that word) as new Chairman of the Federal Reserve, and it was fascinating, although in fairness, I have a Zen and the Art of Motorcycle Maintenance streak in me that delights in what others might consider head-rolling minutiae.
In this article, Russ Koesterich explains how strong fundamentals have supported stocks, but rising bond yields may soon begin to challenge market valuations.
US Treasury Secretary Scott Bessent made waves with his recent announcement that the Treasury would at least double the size of its buybacks of long-term debt in the coming months. He argues that long-term yields do not reflect fundamentals, suggesting that the Treasury's intervention is aimed to restore proper market functioning.
Markets opened on a sour note on Monday after Treasury Secretary Scott Bessent unveiled “Operation Economic Outcast.” This initiative was to include sweeping sanctions against Iran and the networks that enable the regime to evade existing restrictions. Bessent did not explicitly mention Iran’s enablers, but many assumed China was the primary culprit.
It’s back-to-school season, and the ETF market is closing out a summer that proved anything but slow. August brought $180 billion in fresh net ETF asset inflows and saw the number of new ETFs coming to market cross 1,000 for the year. August also saw a barbell strategy against macro risks become a popular approach with ETF investors.
August was a good month in financial markets, with the S&P 500 up around 2.7%. The market leaders came from the commodity complex, with gold and bitcoin (not sure how this should be classified) being the two top performers.
This summer has delivered "blockbuster" returns, both positive and negative, while the possibility of quick and seemingly easy gains continues to draw investors toward speculative areas of the market. In his latest insight, Richard Bernstein, Global Head of Macro & Customized Investing, shares five charts that cut through the noise and highlight important shifts in credit creation, inflation, global growth, market leadership, and asset class performance.
Record fixed income ETF inflows in August pushed year-to-date ETF totals past $1.4 trillion, with short-term bonds leading the surge.
US stocks flipped between small gains and losses on Wednesday after a three-day skid, as oil prices halted a sharp advance, easing inflation concerns as traders weigh the Federal Reserve’s potential path for interest-rate hikes.
Federal Reserve Chairman Kevin Warsh used his keynote speech in Jackson Hole, Wyoming, last week to map out some of the key data points he leans on to read the US economy, offering new insight into his approach to policy making.
Kevin Warsh’s Jackson Hole speech was notably hawkish. But I came away from the speech even more confident in Warsh and thought it was one of the best speeches I’ve heard from a Federal Reserve chair. Most importantly, Warsh is refocusing on factors missing from the Fed’s framework for years: an explicit recognition that money supply and bank credit matter for the Fed’s inflation outlook.
The backup in global yields since late February has reignited the debate over the potential knock-on effects for corporate borrowers, particularly through higher refinancing costs and weaker debt-servicing capacity.
Should the recent value rotation be viewed as a regime shift-driven change in market preference, or a simple reversal trade? We think there is a compelling case to be made for the former. In a regime of higher interest rates and stubbornly above-target inflation, the market is increasingly focused on capex intensity, free cash flow conversion, and the cost of capital.
State Street’s top inflows for its SPDR ETFs during the year-to-date period and the past four weeks suggest that while investors have confidence in U.S. large caps, they’re still looking to hedge their bets by allocating to gold.
Not since 2006 have yields on the longest-maturity Treasuries been this high for this long, with a gaping budget deficit, another wave of corporate issuance and a potentially decisive Federal Reserve meeting set to keep investors wary of US debt in coming weeks.
An almost-vertical rally in gold-miner stocks in the past month is whetting the appetite of investors who have been whipsawed by messages from Washington policymakers.
The first two articles in this series were about behavior. This one is about arithmetic. There are three numbers that decide most of your investing life. Let’s do the math Wall Street skips, one number at a time.
Despite ongoing geopolitical tensions, growing questions about the scale of AI-related spending and steadily rising bond yields, market volatility remained remarkably subdued this summer.
Federal Reserve Chairman Kevin Warsh used his Jackson Hole speech last week to lay out what he thinks of monetary policy. Two things jumped off the pages of his speech.
A credit-allocation problem is complicating the Fed’s dual mandate, with current policy restrictive for many consumers and weaker borrowers, but less so for large corporates, higher-quality issuers, and borrowers with access to private credit.
In a week that saw NVIDIA, the largest company in the world, report strong earnings that sent its stock sharply higher and reinvigorated optimism in the artificial intelligence (AI) trade, fiscal and monetary policymakers continued to provide the biggest headlines.
As the month of August came to a close, the first index mutual fund got to celebrate a key milestone. The mutual fund in question is the Vanguard 500 Index Fund (VFINX), which originally launched on August 31, 1976.
A hard line on trade was a popular plank of the first Trump candidacy. But once in office, his advisors used slow, conventional investigations and negotiations toward the goal of fairer terms of trade.
Beneath relatively muted index-level volatility, single-stock implied volatility remains high. In today’s low-correlation environment, individual stocks are moving more independently, keeping single-name volatility high even as those moves offset at the index level.
San Antonio has been my adopted home for close to 40 years now. I’ve watched it grow through more than one boom cycle, but recent Redfin data suggests we could be looking at a bust.
The appeal of democratic socialism is real because the pain it speaks to is real. I won’t pretend otherwise. But intentions are not outcomes, and history has handed us the outcomes in ink, from Caracas to the old Soviet bloc to the Nordic countries that quietly kept their capitalism. The promise is a beautiful cake. The aftertaste is shortages, capital flight, inflation, and a new elite standing where the old one used to be.
Our real gross domestic product (GDP) forecast for 2026 is 2.5% (based on our Global Investment Management Survey) versus the Federal Reserve’s (Fed's) forecast of 2.2% and the Wall Street consensus of around 2%. The economy remains resilient and the consumer is strong.