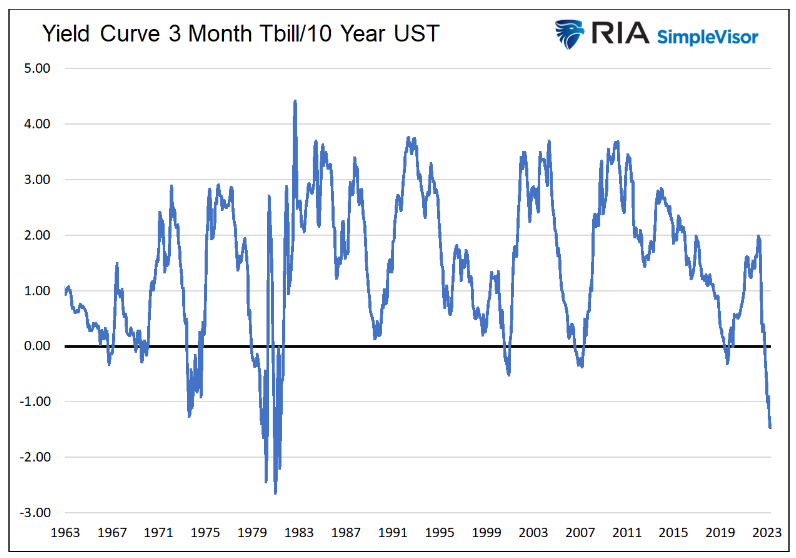
The Fed’s concern about U.S. banks dominated last month’s FOMC meeting. According to today’s release of the March 21-22 meeting minutes, the Fed was apparently so concerned over banking problems and the potential for an ensuing credit crunch that officials tempered calls for rate hikes...
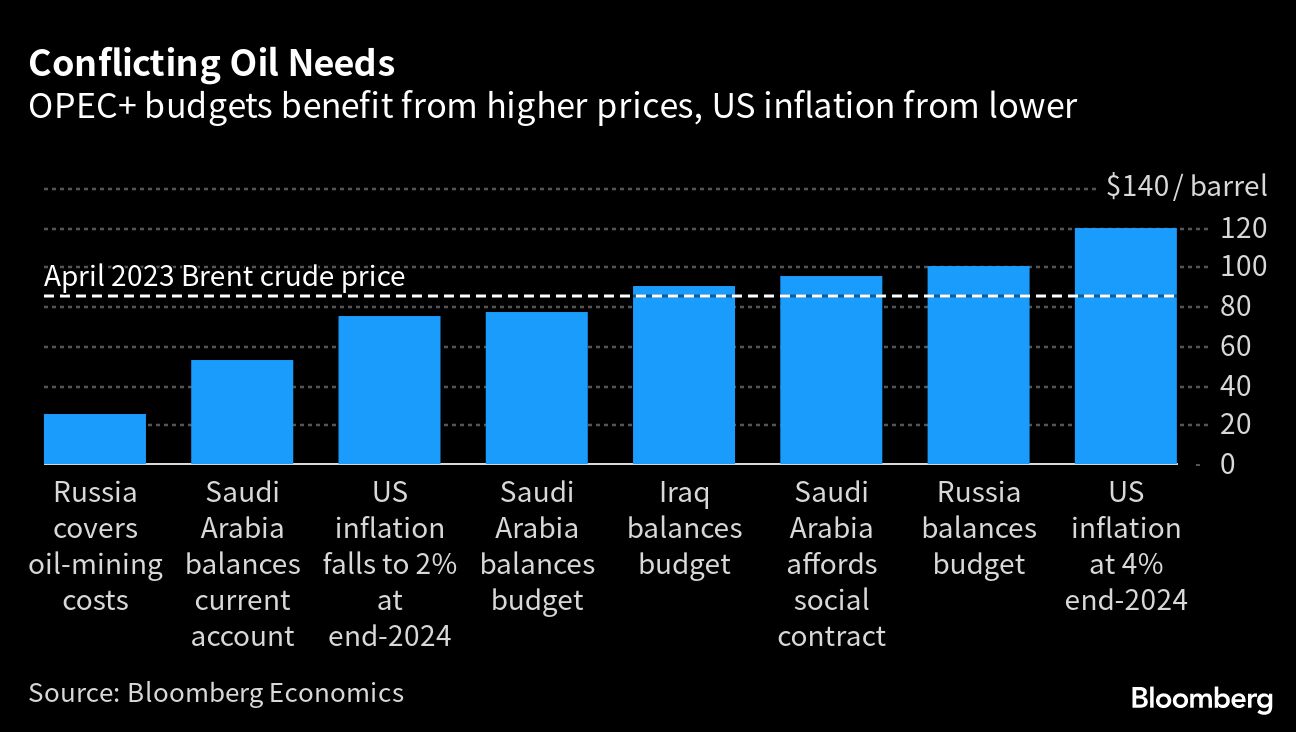
The Saudi-Russia oil alliance has the potential to cause all kinds of trouble for the US economy — and even for President Joe Biden’s re-election campaign. This month’s OPEC+ decision to cut crude output, for the second time since Biden flew to Saudi Arabia last summer seeking an increase, may be just the start.
The US power grid includes everything from 100-year-old hydro dams to brand-new batteries. It’s evolving as coal power diminishes, wind and solar rise and energy storage smooths out operations. But those changes are a shadow of what might come next.
Given market uncertainty and the risk of a US recession, is now the time for defensive stocks? Making a case for low-volatility, high-dividend equities with Franklin Templeton Investment Solutions’ Vaneet Chadha and Michael LaBella.
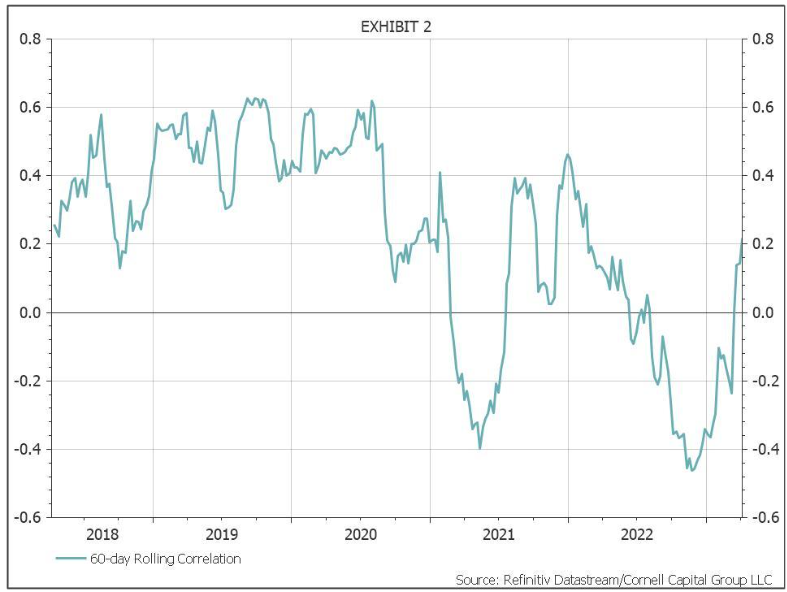
The lack of diversification benefits of government bonds in 2022 was painful for multi-asset investors. The sell-off in US Treasuries in particular was sharp, and we saw correlations versus stocks move well into positive territory.
March inflation data may put the Federal Reserve close to its terminal policy rate this cycle, if it hasn’t already reached it.
The stakes are high, and it appears likely that our deeply divided government is headed for another debt-ceiling showdown. Divided governments have typically been good for the markets; however, they often spell trouble when it comes to negotiating fiscal matters.
Although central banks may be near the end of the rate hike cycle, short-duration stocks may still be an attractive investment theme should interest rates remain at higher levels.
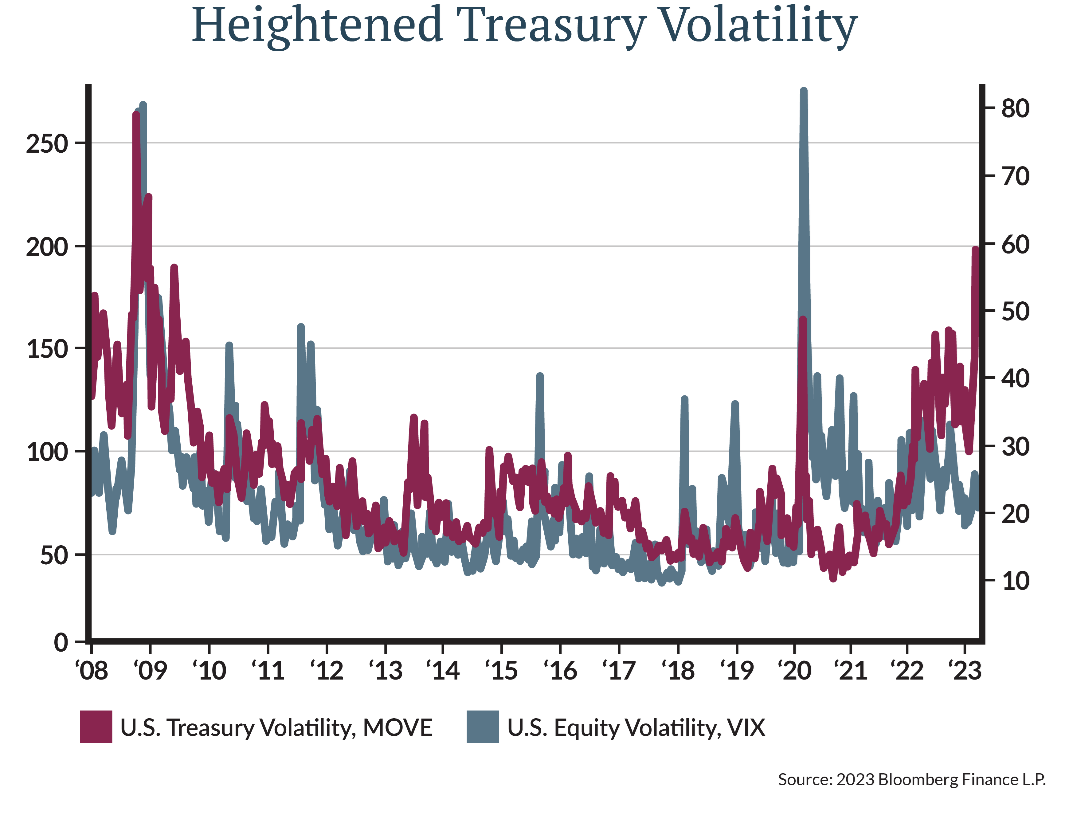
During his spring break, Johnson Financial Group Portfolio Manager Brian Schaefer had the time to read “A Gentleman in Moscow,” which got him thinking about the how the current market moves could impact the American experiment. In this investment commentary, Schaefer discusses the MOVE and VIX indexes and what they might say about the markets.
The International Monetary Fund has caused some consternation with the long-range forecasts in its April World Economic Outlook. It predicts that once the current bout of nasty global inflation abates, interest rates will return close to zero.
A key measure of US inflation showed hints of moderating in March, but likely not by enough to dissuade the Federal Reserve from raising interest rates again next month.
Why finding ways to break the tie to these variables is so important, and outline a few ideas for how to do it.
Hedge funds are reloading on bearish wagers on US equities, betting the latest market retreat will persist amid worsening economic data and corporate earnings.
Trading might be muted today as the market pivots, awaiting earnings and inflation data this week.
We introduce a tool for assessing how the market responds to news about the economy and about government monetary and fiscal policy.
Doug Drabik discusses fixed income market conditions and offers insight for bond investors.
We think dividend-income strategies can be effective across multiple environments, provided that they’re designed to tap into a wider opportunity set beyond traditional dividend payers alone.
As central banks wrestle with how to respond to volatile economic data and banking turmoil, while also fighting inflation, Franklin Templeton’s economists provided their perspectives on what’s next for economic growth, interest rates, inflation and fixed income markets.
Western countries have become increasingly wary of sharing technology with China, with the US and Netherlands recently imposing new restrictions on exports of semiconductors and the equipment used to make them.
Almost $1.5 trillion of US commercial real estate debt comes due for repayment before the end of 2025. The big question facing those borrowers is who’s going to lend to them?
The market bottomed last October despite ongoing concerns about inflation, higher rates, recessionary risks, and a banking crisis. While the media headlines and youtube podcasts are filled with “crisis” headlines, as noted in “Analysts Raise Estimates,” expectations for growth and earnings are rising.
The case for a central bank digital currency has many shortcomings.
Central banks accumulated gold at the fastest pace on record in the first two months of 2023. In January and February, central banks collectively bought a net 125 tonnes of the metal, the highest amount for the year-to-date period since banks became net buyers in 2010.
Volatility can be challenging but it also creates opportunities. In our view, rotating across sectors within the investment grade market is the most effective way to take advantage of price fluctuations and generate alpha.
Fifteen years ago, in 2008, the Federal Reserve started an experiment in monetary policy, switching from a “scarce reserve” system to one based on “abundant reserves.” This switch has created massive problems that are hitting not just the private banking system but the Fed itself.
There is a lot riding on the monthly jobs report, which comes out tomorrow. For the economy, more jobs are good: more workers, more wage income, more spending ability, and so forth. There’s no real downside.
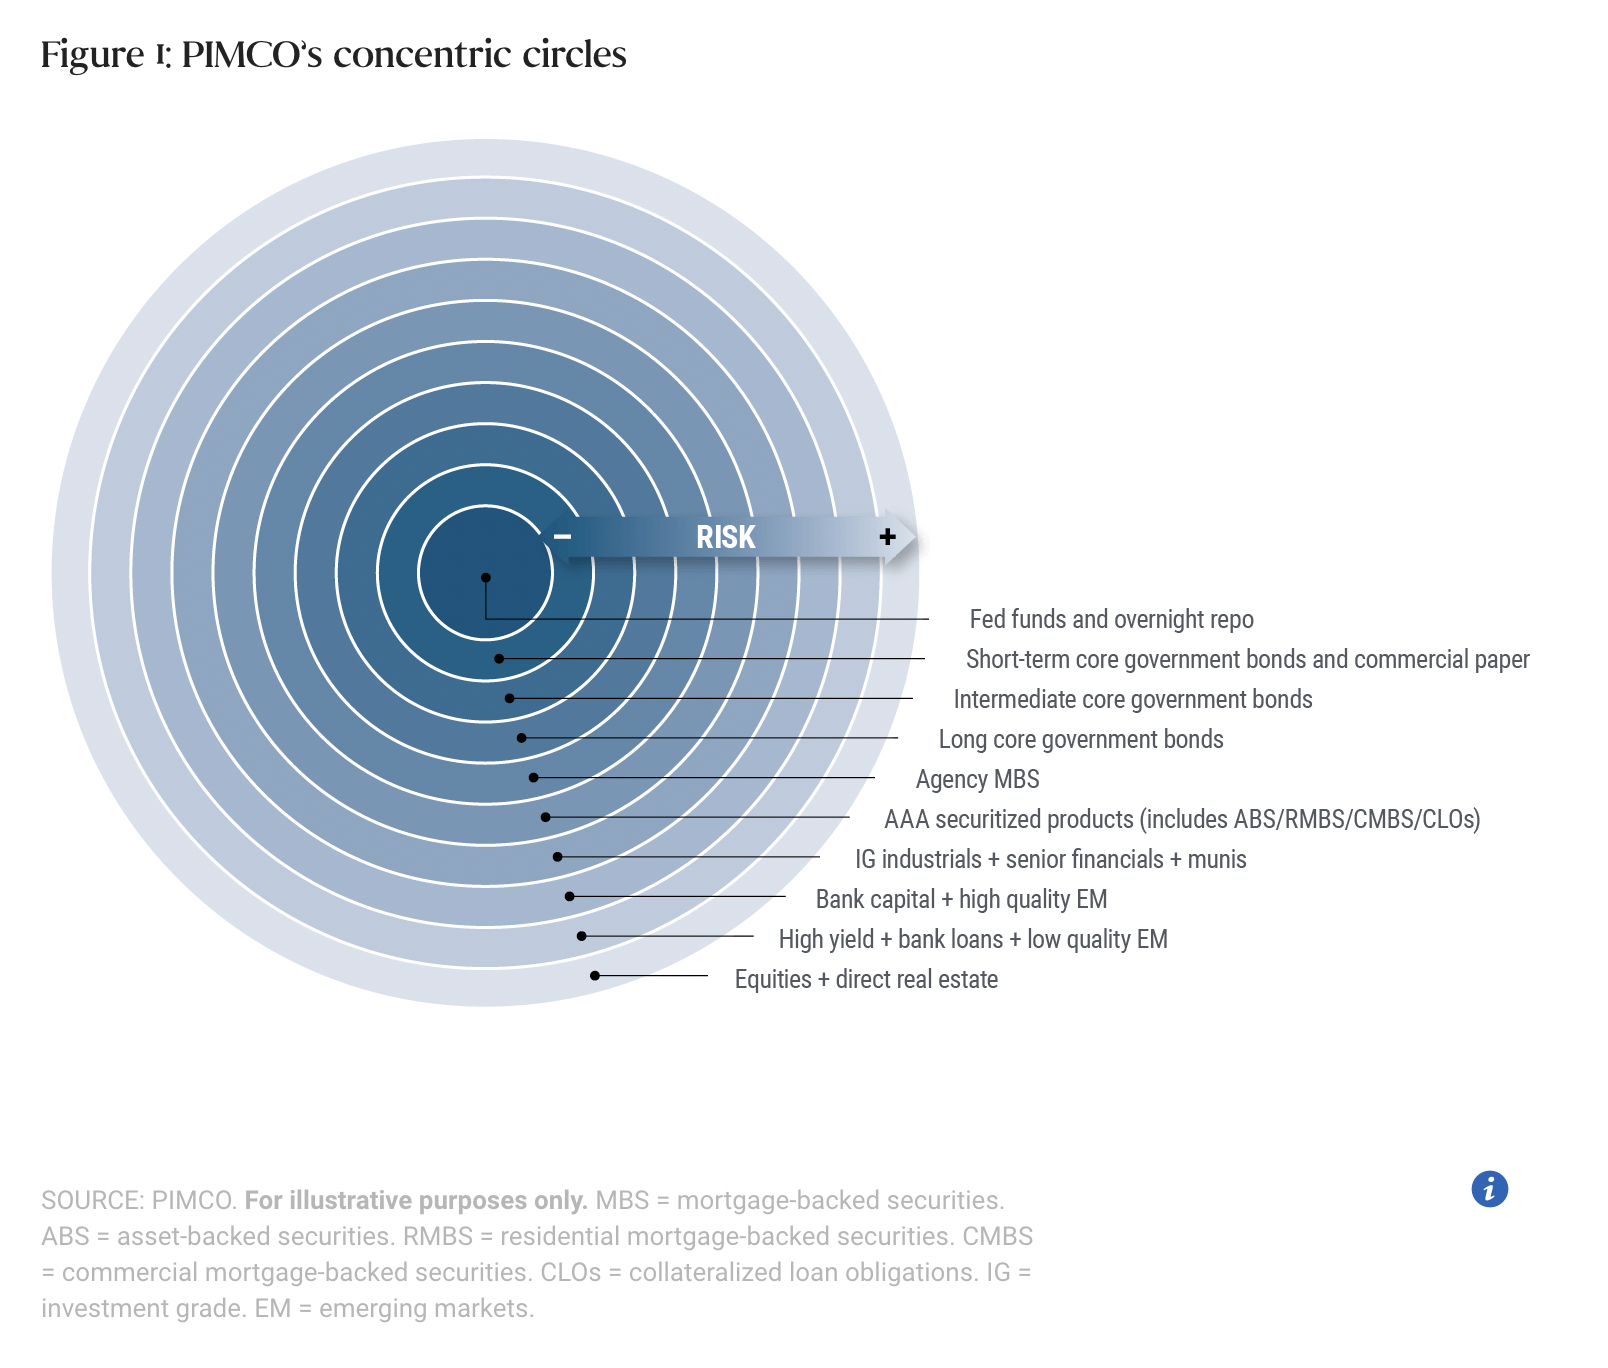
Safe and risky: the final frontier. These are the voyages of the retiree on her lifecycle mission: to explore strange new investments. To seek out safety and protect against inflation. To boldly go where no woman has gone before!
Bailouts of the banking system create social tension. Eventually, bailouts introduce so much risk into the system that failures and bailouts become too costly for society to bear. The government creates draconian rules to prevent them, which kills innovation and new business, and the result is a stagnating economy.
When banks started going belly-up, the reaction in bonds was emphatic. Two-year Treasury yields slid a percentage point over three days in March, the most since 1982.
“Thinking the Unthinkable.” What does that phrase bring to mind? To me it suggests a situation that has become so stressed you are forced to consider undesirable solutions.
I get many inquiries from bond investors on whether they should buy bills, notes, or bonds based solely on expected Fed policy.
Central Banks are on the verge of declaring the yearlong interest-rate hiking cycle over. The reason: Banks have taken the wheel and are pressing the brakes.
Rick Rieder and team argue that a major shift in market perception of growth, inflation and policy trajectories means investors should consider calling a "time-out" to reassess portfolios.
Everyone knows it by now: 2022 was not a kind year for investors, particularly balanced fund investors. There were no silver linings, no shelter from the storm; it seemed that no matter what levers you had in place to protect clients’ wealth, there was very little to cheer about on investor return statements.
In the face of banking stress and a hawkish Federal Reserve, stocks have advanced impressively so far this year, but narrow breadth doesn't bode well for continued strength.
Inflation regimes often coincide with changing political regimes and agendas, much of which stems from the rise of populism and fiscal dominance. As a result of decades of globalisation and rising wealth inequality, we may well be entering a new regime - one of higher inflation and higher inflation volatility.
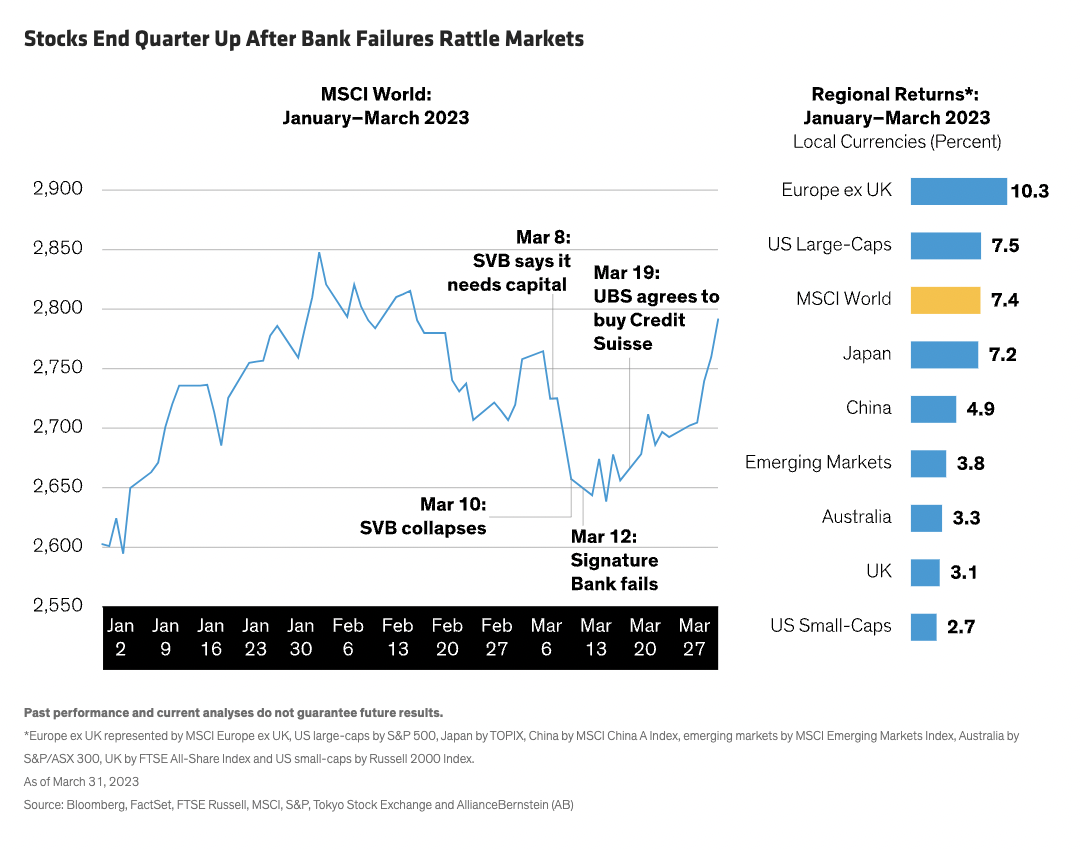
After a weak February, markets rallied in March. U.S. markets were up by low single digits, while bond markets were in the same range. International markets also showed modest gains, with developed markets about the same as the U.S. and emerging markets doing slightly better.
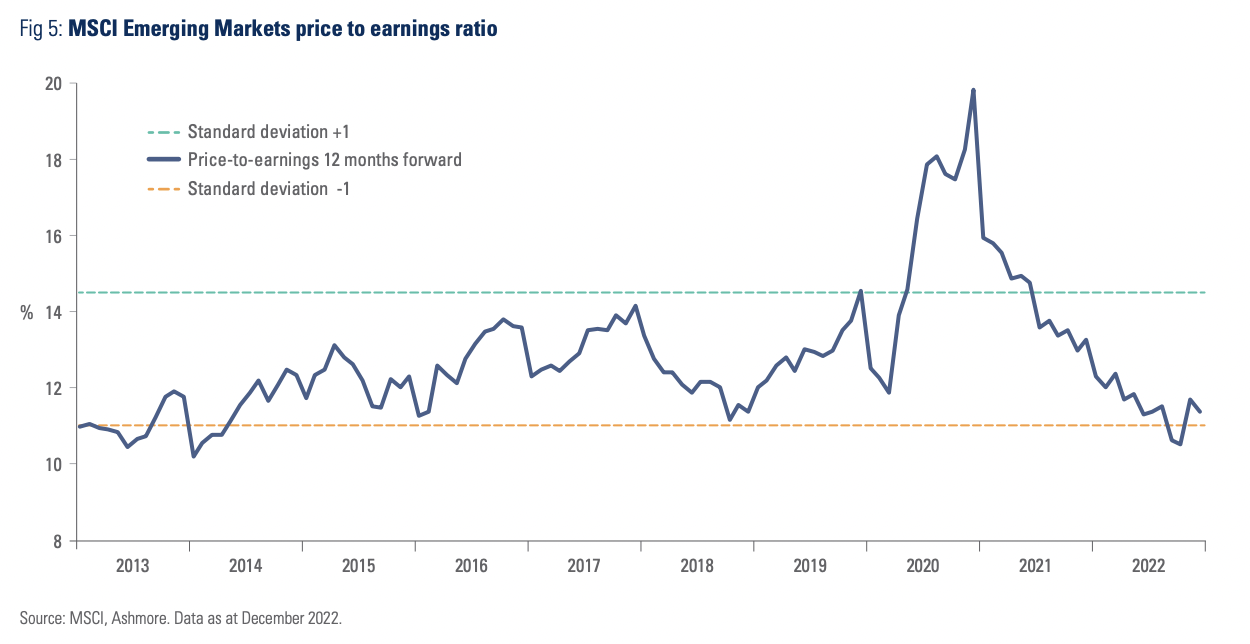
Emerging Markets (EM) have faced a challenging environment over the past five years, due to a series of global shocks that have triggered elevated market volatility and led the MSCI EM equity benchmark to experience its most protracted drawdown in history.
The US office market faces a tough road ahead. Corporate tenants are considering scaling back, higher interest rates are hurting valuations and many property owners face looming debt maturities that they may struggle to refinance.
CIO Larry Adam shares why his team's market and economic views are tracking more optimistic in light of current volatility.
Global equities were volatile in the first quarter, as turmoil in the banking sector jolted markets.
History suggests the lagged economic effects of tighter central bank policy are arriving on schedule, but any eventual normalizing or even easing of policy will still likely require inflation to decline further.
The Franklin Templeton Investment Solutions team examines the earnings outlook for 2023, and why it might make sense to be defensively positioned.
Asian equities are likely to extend their gains as the year progresses, boosted by the region’s relatively better growth prospects and a broadening economic recovery in China.
Jarred by daily double-digit moves in Treasury yields, bond investors are bracing for at least another year of rocky trading, abandoning hopes that in 2023 the market would return to normality.
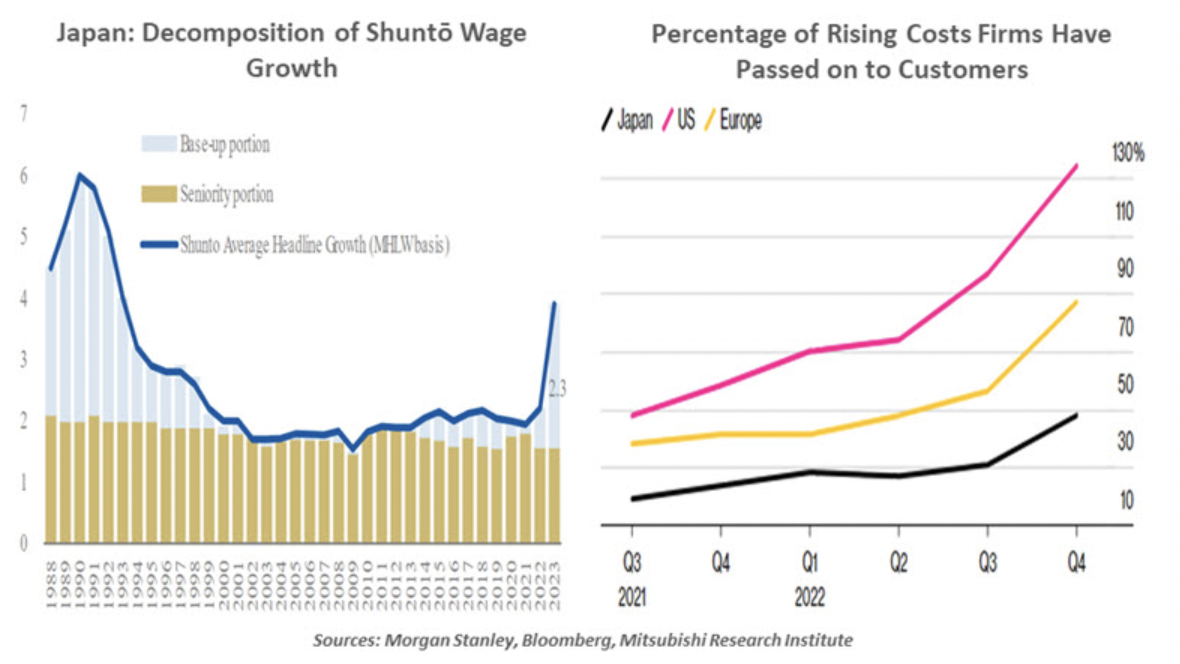
The risk of Japanese inflation getting out of control is not high.
As banks back away from credit creation, we think certain assets could reassert their leadership. In our Quarterly Strategy Report, we analyze the Credit Crunch.
A tricky situation is unfolding, making it rather difficult for the Federal Reserve Bank to honour earlier promises to gradually ease off in its ongoing fight against inflation.
If you were bullish for 2023…congratulations!
The Silicon Valley Bank collapse may be an extreme event, but it gives us a preview at a 100x magnification of what other banks are facing.