Are investors overlooking a “stealth bear market” hidden beneath the strength of the broader market?
The U.S. ETF market reached $16.4 trillion in AUM in August 2026, driven by record product launches and a defensive shift to Treasuries.
Direct venture investment rewards a rigorous, patient approach. The companies that generate exceptional returns tend to combine all three factors above: genuine growth momentum, clear category ownership, and strong institutional support.
The value of actively bringing the quieter partner into the conversation by turning toward them, making eye contact, and asking for their thoughts. Even if the answer is still a shrug, the question signals that their view belongs in the conversation.
Organizations are beginning to rethink how development projects are priced. One emerging approach is the use of a max-price software model. This establishes a predefined budget ceiling while allowing priorities to evolve throughout the project.
Chris Galipeau discusses high-conviction insights that go beyond media headlines.
Stock investors are caught between the pull of strong earnings and mounting macroeconomic risks, with key events carrying binary outcomes that argue for some protection.
I love ETF milestones and round numbers almost as much as I love watching football. There is something deeply satisfying about watching a fund hit a clean asset threshold. Crossing $500 million, $1 billion, or $2 billion in assets under management (AUM) is more than just a psychological victory. It signals real validation from financial advisors, provides greater liquidity, and lowers the risk of fund closure. Plus, as a fun bonus this week, our three featured funds all start with the letter B!
Healthcare automation startup Forus has raised $150 million at a $3 billion valuation just months after completing a previous funding round.
Around 2020, Apple Inc. Chief Executive Officer Tim Cook returned from a trip to Asia unusually energized about a new product category: foldable phones.
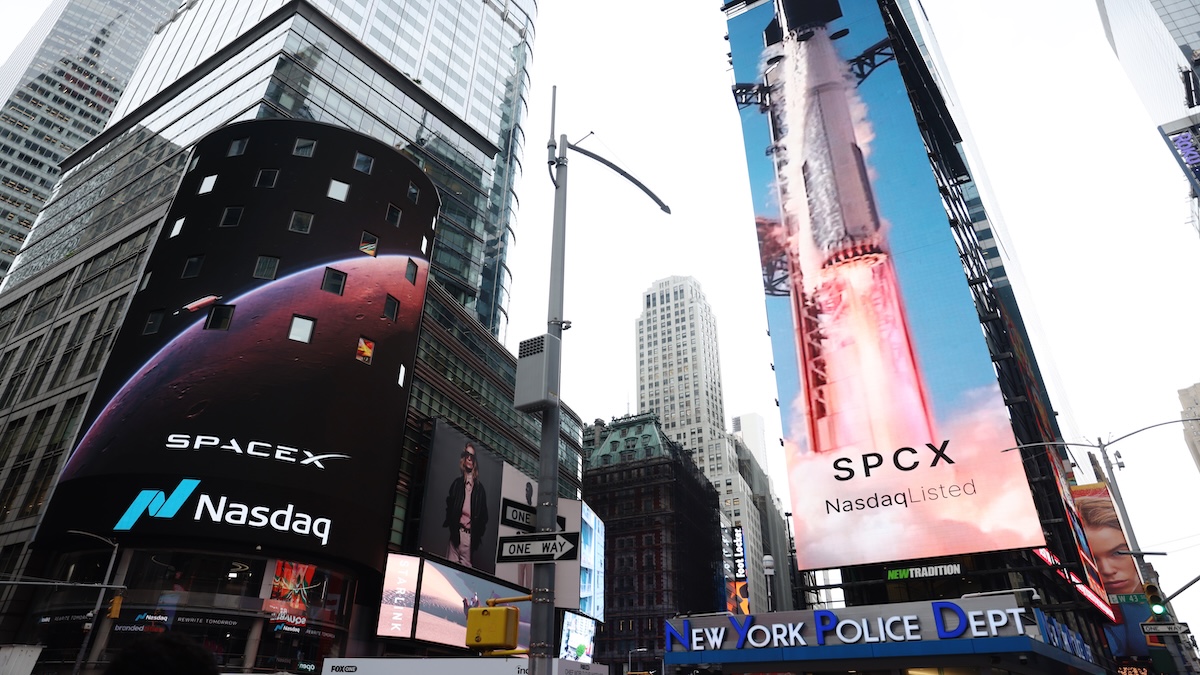
SpaceX’s stock has been stuck in a tight trading range recently, but a wave of new buying may soon arrive when the Nasdaq 100 Index goes through its quarterly rebalancing later this month.
A sudden reversal in momentum for previously high-flying shares of industrial companies over the past three weeks has some investors bracing for more pain ahead.
If you look deeply into a speculative bubble, you can already see the collapse. If you look deeply into a market collapse, you can already see the bull market. The road up and the road down are the very same road. Even so, aside from knowing that our investment position presently requires a safety net regardless of shorter-term conditions – we have utterly no opinions, preferences, or scenarios about the market outlook even a month or a quarter from now.
Before I discuss why I disagree with the “AI bears,” I want to state that I respect their opinions, have evaluated their concerns, and have simply derived a different set of conclusions. That is an important statement, because this particular group of “AI bears” includes some of the sharpest risk minds in the business, and they have been early to almost every warning that later mattered.
It's been 40 years since I began my career on Wall Street and the lessons I learned along the way from some all-time investment greats always hold true.
After a week of traveling abroad to meet with clients and discuss our outlook for the US economy and financial markets, we returned feeling the need to address a growing misconception, both in the United States and overseas, regarding the differences between the US and Chinese economies.
My goal with this letter will be to not interrupt your long weekend too much. But there are some things that are happening that are important. My basic thesis for quite some time has been that we are in a Muddle Through Economy, which I’ve always meant that to me the GDP will grow slightly south of 2% over time.
The “K-shaped” divide endures even as it evolves. Higher-income households keep benefiting from equity gains, home price appreciation, and solid earnings, while lower-income households face mounting pressure from elevated costs and tighter credit. But recent data suggest the story is becoming more nuanced.
Cerulli projects a $2 trillion surge in advisor-held alternatives over five years, as interval funds reshape how RIAs access private markets.
What if you could capture the potential gains of the S&P 500, but limit your losses if the market goes down? Or earn above-market income given the right stock market conditions? How about gaining some market exposure while protecting principal with FDIC insurance, up to applicable limits?
For the past six weeks, we’ve walked through the forces creating America’s K-shaped economy, housing, healthcare, education, wages, incentives, and the political consequences when enough people decide the system is not working for them. This week let’s look at the situation from a more optimistic angle.
Sift through the filings of pension funds and insurers around the world and one thing stands out: some of the biggest holders of US assets have little protection against a weaker dollar, leaving the currency at risk of steeper declines if sentiment suddenly turns.
Products and services often benefit from great marketing. A catchy commercial, headline, or gimmick can attract potential customers. Sometimes marketing can be so effective that customers seek or support an average or even inferior product.
More than a year after wildfires devastated Pacific Palisades, a nonprofit is advancing a plan to tap the public debt market to create housing in the slow-to-recover Los Angeles wealthy enclave.
After several challenging years, important parts of the health care sector appear to be reaching an inflection point. Policy uncertainty has weighed on pharmaceutical companies, constrained biotech funding has pressured the drug-development ecosystem and the normalization of pandemic-era has challenged select tool and device companies. More recently, however, several of these headwinds have begun to moderate.
Global fixed income and equity ETF strategies posted gains and saw inflows surge in August, even amid ongoing macroeconomic turbulence and elevated long-term borrowing costs. International equities maintained their year-to-date lead over U.S. stocks throughout the month, led by notable strength in emerging markets.
Stocks have enjoyed a powerful run off the spring lows and have largely shrugged off concerns around growth, inflation, higher interest rates, the effects of artificial intelligence (AI), geopolitics, and policy uncertainty. As the calendar turns to September, however, they are entering what has historically been, from a seasonality perspective, the most challenging month of the year for equities.
Kevin Warsh's Jackson Hole speech struck a decidedly hawkish tone and was arguably the clearest signal yet that the Federal Reserve is actively considering additional tightening. Markets responded by raising the probability of a September hike to roughly 60% and pricing approximately 60 basis points of cumulative tightening through the middle of next year.
With recent data weakening the case for an immediate increase in rates, markets have sharply pared expectations for near-term tightening, with a hike no longer fully priced before early 2027.3 This moderation in rate-hike fears has been supportive for gold.
The saying “May you live in interesting times” is becoming relevant in the bond market for all the wrong reasons. “Interesting” usually means “trouble.”
On Wednesday, September 2, State Street Investment Management announced the debut of the State Street SPDR UC Investments 90/10 Endowment Strategy Index ETF (UCBG). Notably, this fund was created through a collaboration between State Street and UC Investments, the investment arm of the University of California.
Wall Street dealers were already bracing for a potential record in September for high-grade US corporate bond sales, and recent surging yields may give the blue-chip companies even more reason to borrow now before funding costs rise further.
August 2026 was a blockbuster month for ETF acquisitions.
Anchoring is one of the most powerful—and underestimated—forces in financial decision‑making. Once an emotional label attaches itself to an idea, it becomes the lens through which people interpret everything that follows.
House poised to pass bill to avoid government shutdown, two new members set to join the House, Fed chair speech boosts rate hike possibility, and national debt hits $40 trillion.
Geopolitical headlines can quickly move markets, but investors do not need to predict every headline to identify potential opportunity. The more useful question is what governments, businesses and consumers are doing in response to a changing strategic environment, and which companies may benefit.
The month of August reminded many investors that the markets rarely move in a straight line. A combination of encouraging economic fundamentals, uncertainty in the bond market and renewed geopolitical turmoil led to increased volatility and shifting market leadership. But the underlying backdrop reinforced that the US economy continues to expand at a sustainable pace.
Interim data takes center stage, with Costco, Ford, Robinhood and Charles Schwab offering fresh reads on consumers, autos and retail trading
US Treasury Secretary Scott Bessent made waves with his recent announcement that the Treasury would at least double the size of its buybacks of long-term debt in the coming months. He argues that long-term yields do not reflect fundamentals, suggesting that the Treasury's intervention is aimed to restore proper market functioning.
Markets opened on a sour note on Monday after Treasury Secretary Scott Bessent unveiled “Operation Economic Outcast.” This initiative was to include sweeping sanctions against Iran and the networks that enable the regime to evade existing restrictions. Bessent did not explicitly mention Iran’s enablers, but many assumed China was the primary culprit.
The recent IPO of SpaceX and the anticipated IPOs of Anthropic and OpenAI are focusing attention on how to invest following a liquidity event. Here, we discuss several important decision points.
Record fixed income ETF inflows in August pushed year-to-date ETF totals past $1.4 trillion, with short-term bonds leading the surge.
Americans like to spend money, and they’re good at it. But they also feel kind of bad about it.
AI-driven scarcity is allowing companies perceived as lower quality to post the revenue growth, margin expansion and rising returns that investors associate with quality, lifting estimates, multiples and stock prices.
The high-yield market appears expensive at first glance. Spreads sit near the tight end of their historical range, which implies limited compensation for credit risk. However, spreads relative to their historical levels do not capture the full opportunity set of the asset class. Corporate fundamentals remain healthy, defaults are low, and the quality of today’s high-yield universe is higher than its long-standing reputation might suggest.
The backup in global yields since late February has reignited the debate over the potential knock-on effects for corporate borrowers, particularly through higher refinancing costs and weaker debt-servicing capacity.
Should the recent value rotation be viewed as a regime shift-driven change in market preference, or a simple reversal trade? We think there is a compelling case to be made for the former. In a regime of higher interest rates and stubbornly above-target inflation, the market is increasingly focused on capex intensity, free cash flow conversion, and the cost of capital.
Advisors who build a third-quarter planning call into their process tend to see fewer IRS notices land on their clients' desks. Tax season teaches clients to think about taxes once a year. The advisors who win their trust are the ones who think about taxes all year round.
An estimated $124 trillion is expected to transfer through 2048, including about $105 trillion to heirs. We have spent a great deal of time estimating the value that will transfer from one generation to the next. However, if advisors expect to maintain the value received, we should be equally interested in whether the value we provide in exchange is evolving with it.
As government bond yields across the world erupt, corporate credit has rarely looked calmer. Yet even in that market, about $1 trillion of bonds are telling a much different story.