Financial markets continue to grapple with a fundamental question: If inflation remains above target after years of restrictive monetary policy, is interest-rate policy still aimed at the right problem?
In this video The Most Powerful Growth Stock, Chuck Carnevale, co-founder of FAST Graphs and known as “Mr. Valuation,” examines NVIDIA through the lens of growth, valuation, financial strength, and long-term return potential. He explains why growth investing is still value investing when a company’s future earnings justify the price being paid.
There is more than one reason the 10-year Treasury yield is 5.23% today. Most importantly, the Fed has stopped anchoring interest rates at artificially low levels. Fear of inflation is likely another. However, both of those are related to the massive government debt the US has created.
I’m writing this week from London, the start of a four-country tour of Europe to see clients. I typically don’t have a lot of free time while on these journeys, but I did sneak away on the weekend for an economics field trip.
Retail investors buy corporate bond ETFs expecting steady coupons and ballast against stock market volatility. Traditionally, fixed-income portfolios were anchored by defensive issuers like banks, industrials and utilities.
A recent VettaFi webcast explored advice on navigating retirees' behavioral tendencies in decumulating assets in retirement.
Join Fidelity for a product due diligence session exploring how the Fidelity Yield Enhanced Equity ETF (FYEE) captures derivative opportunities in today’s unique market environment.
When during the calendar year should retirees take their required minimum distributions (RMDs)? Take the RMDs early and eliminate the chore? Wait until December to maximize tax-deferred compounding? Or spread the distributions throughout the year? Advisors often start with too narrow a view of what clients are trying to optimize.
Only 30% of Americans believe they’ll be able to retire comfortably — an amount retirement plan participants now estimate is $1.2 million, a recent survey by Schroders found. 33% of plan participants said that their credit card debt was higher than their retirement savings.
As bond yields have risen, mortgage rates are again facing upward pressure, extending the U.S. housing market's post-pandemic affordability challenges. Beyond mortgage rates, trends in wage growth, taxes, and insurance costs also continue to shape the affordability outlook.
Chris Galipeau discusses high-conviction insights that go beyond media headlines.
In the first quarter of this year, as the Strait of Hormuz closed and oil prices exploded, Berkshire Hathaway made a couple of moves that might have flown under people’s radars.It cut its stake in Chevron by roughly a third. Then it bought an airline.
The financial markets are navigating a storm. The Treasury yield sell-off intensified this week, pushing the 10-year Treasury yield up to an intraday high of 5.20%, its highest level since 2007.
I’m talking about the cash I have sitting here that I desperately want to get into the market. Earlier this year, I got a chunk of money from selling a house. I have no desire to own another home (that’s a story for another time.) Instead, I used some of the money to pay off some debt. The rest is just sitting in my savings account earning absolutely nothing.
A snowball effect of asset values can similarly empower wealth effects: the tendency for consumers to spend more as the value of their investments rises. Wealth effects are surprising at first glance: household investments may be illiquid and tend not to produce substantial cash flow. However, a rising net worth builds a consumer’s confidence in their ability to afford purchases.
The BlackRock Model Portfolio Solutions team made significant allocation shifts during the week ended September 24, 2026. The team recently managed over $300 billion and often causes shockwaves in the ETF industry.
Northern Trust Asset Management will move six mutual funds with $33 billion in assets into ETFs in early 2027, its first such conversions.
I propose that the question of whether now is an especially auspicious time to buy in general — or more incisively, whether properly allocated investors should have more, less, or the same TIPS exposure when rates are relatively high — is more nuanced.
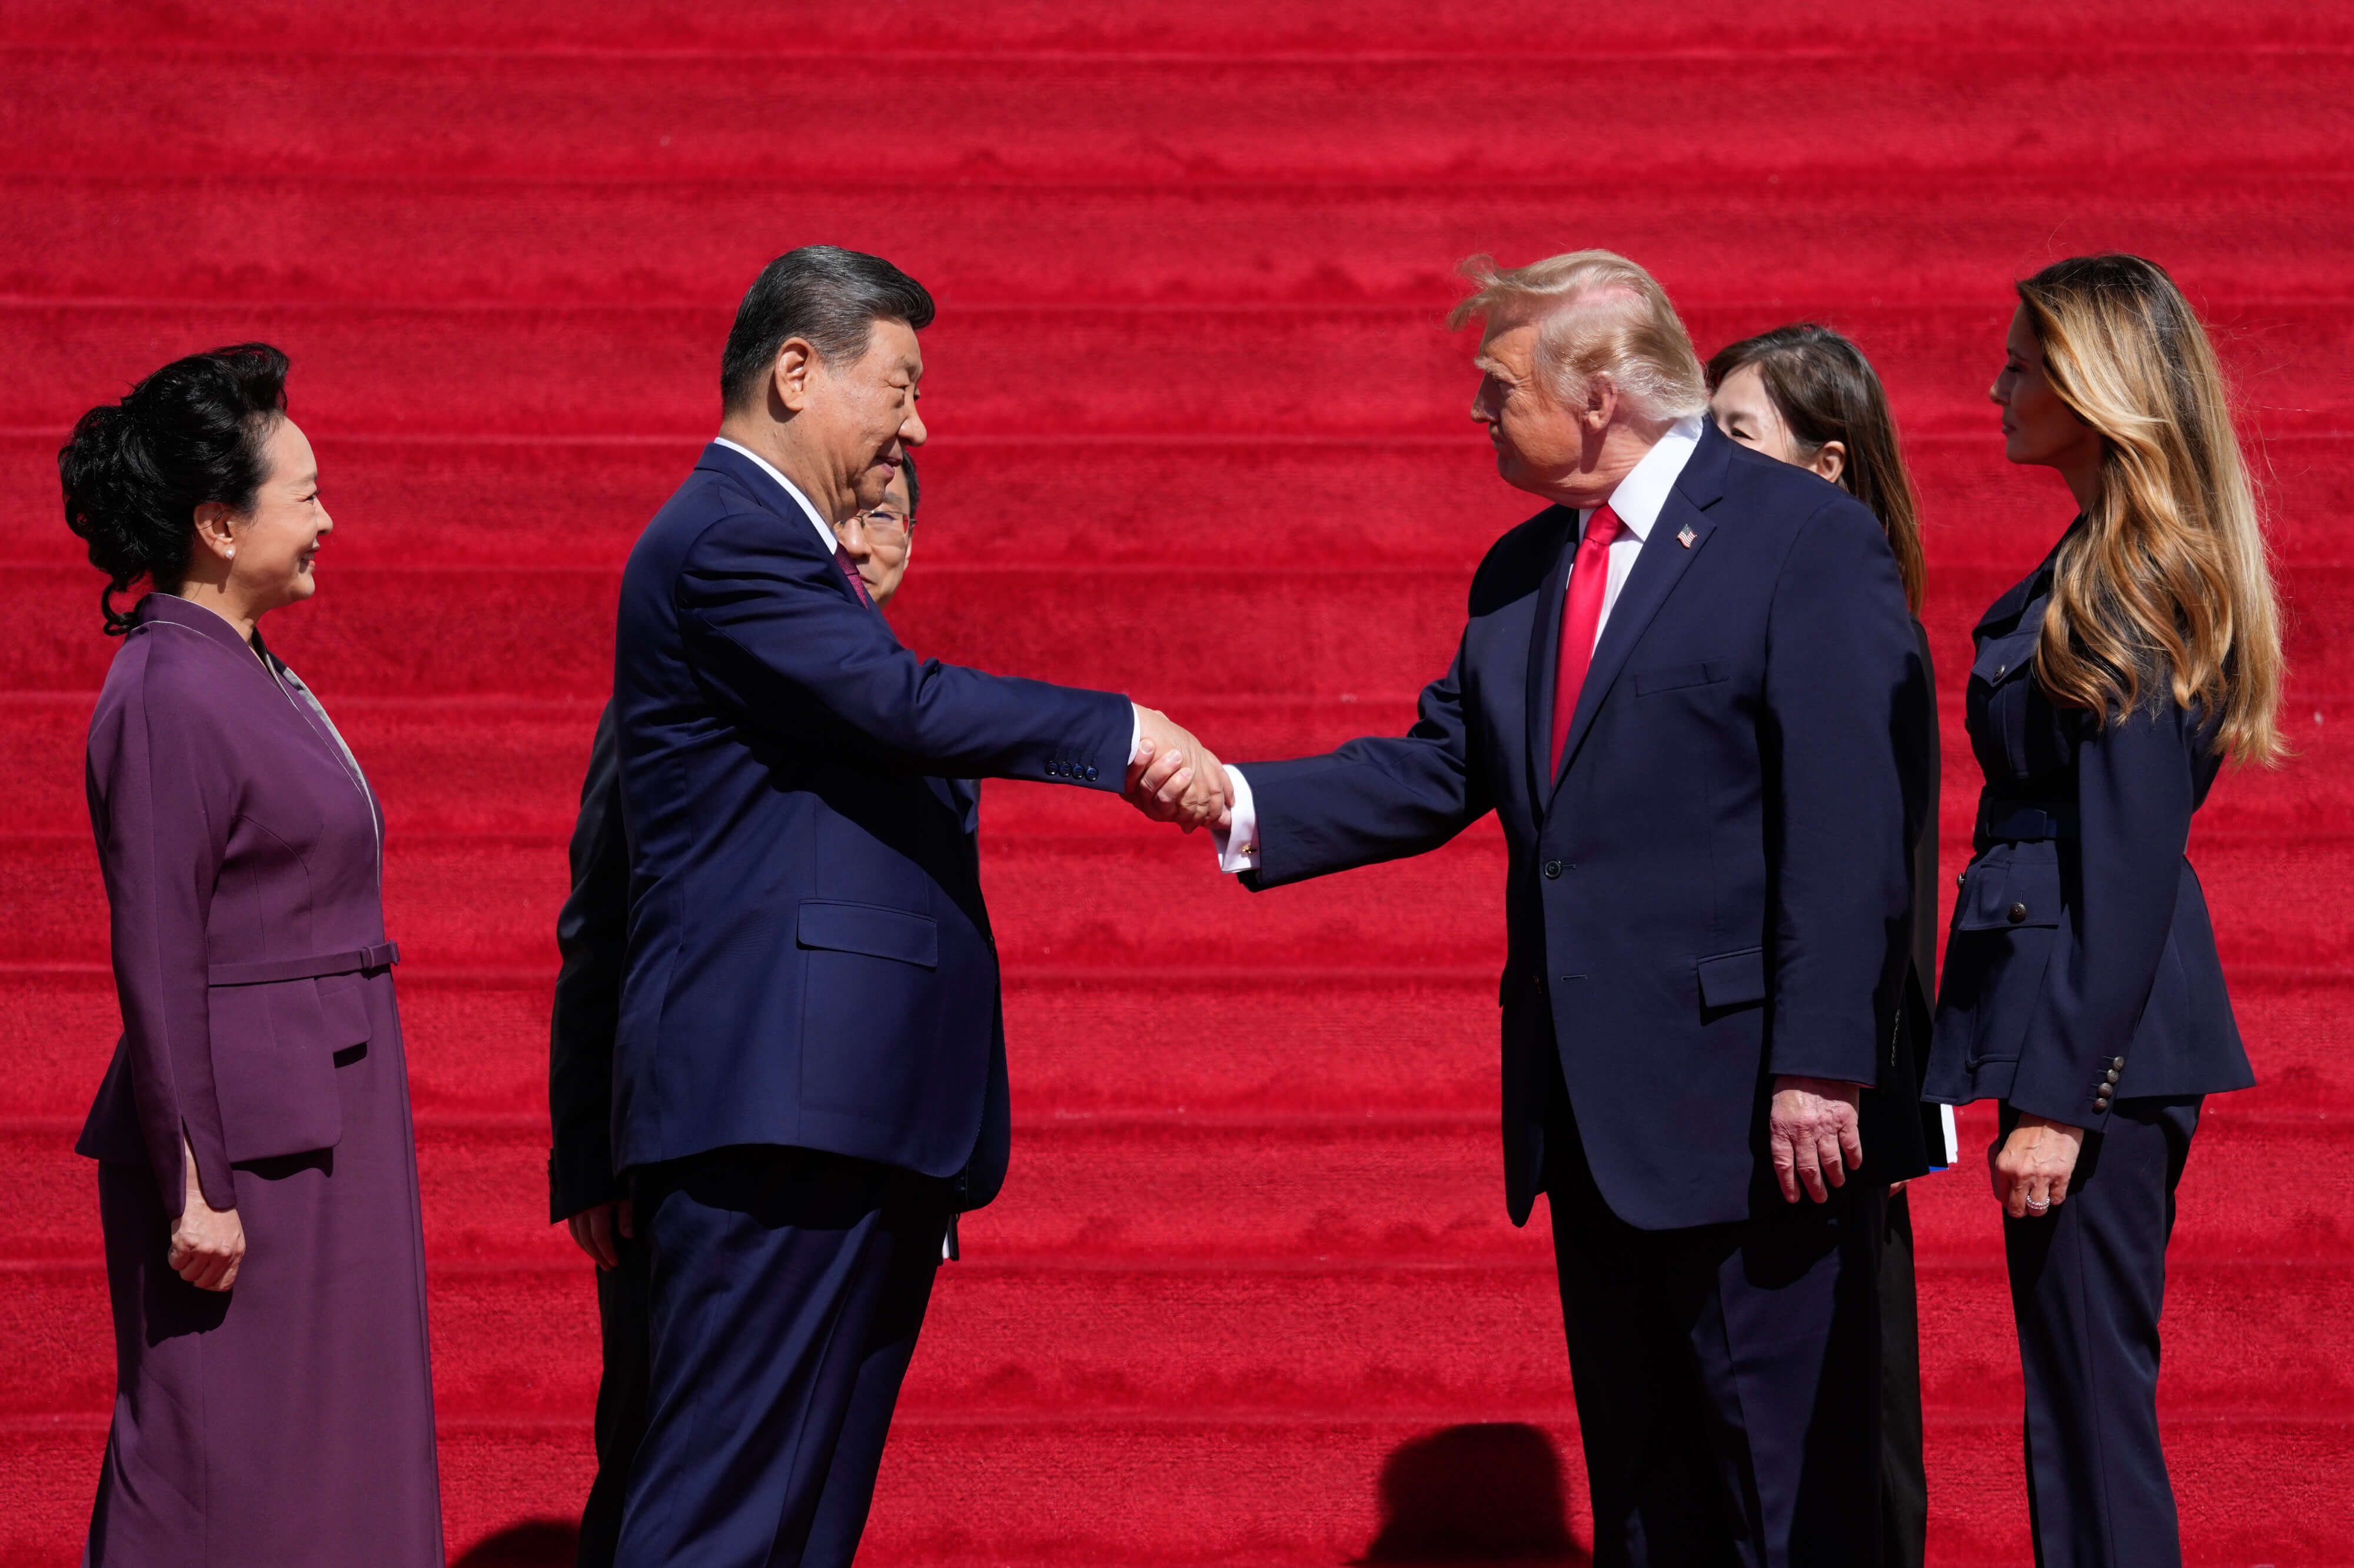
The US and China detailed a plan to cut tariffs on about $30 billion of imports from each country, taking a step toward fulfilling a key outcome of last week’s summit between Donald Trump and Xi Jinping.
A number has been making the rounds all year, and it’s misleading. The claim: roughly 13% of credit card balances are 90 days or more past due, the worst since 2008. Here’s the twist. That number is real, and it comes straight from the New York Fed.
The U.S. economy remains resilient despite headwinds including sticky inflation, trade instability and rising geopolitical tensions. State and local government tax revenues have followed suit and have posted solid growth, aided by robust equity market returns.
The S&P 500 has remained remarkably resilient in the face of mounting macro headwinds. Despite oil prices topping $100 per barrel, 10-year Treasury yields climbing above 5%, and a renewed shift toward tighter monetary policy, the index continues to hover near record levels.
Second-quarter earnings were strong, particularly in technology, but crowded ownership often determined whether good news was rewarded. The selloff in semiconductors arguably reflected crowded positioning and concerns surrounding the sustainability of the earnings boom. The net result: multiples compressed while earnings revisions held up.
Artificial intelligence (AI) leadership is no longer a developed-market monopoly. Emerging markets (EM) now have their own AI champions, and productivity gains may follow. For bond investors, we expect the implications to differ by country—driven by industry composition, capital intensity, digital infrastructure and speed to adoption.
The yield on the 30-year hit a multi-decade high this week, spiking amid continued fiscal and monetary concerns. The 30-year hitting 5.45%, its highest mark since 2004, comes amid an already busy year for bonds.
In September 2024 and June 2025, I wrote memos that were critical of governments’ attempts to override the laws of economics, based on my conviction that trying to do so is likely to prove ineffective and potentially harmful.
This week, there are a few things that we need to pay attention to: the large move in interest rates and what it means (and more importantly, what it doesn’t mean!); and the constant barrage of doom and gloom on energy and AI. Let’s jump in.
I do not know whether quantum computing is in that kind of window right now. Nobody does, and I am suspicious of anyone who claims certainty in either direction. What I can say is that the pattern-matching is uncomfortably familiar.
Last week we looked at the Federal Reserve’s inflation problem. This week, let’s look at the other half of its mandate: maximum employment.
The Facebook parent’s shares had jumped 36% in September through Thursday’s close following the release of its Muse personal AI assistant, which has risen quickly to the top of app charts and muffled concerns that heavy spending on AI won’t pay off. The stock is on pace for its best month since July 2013 and within striking distance of joining an elite group of companies worth at least $2 trillion.
Now the US is in a higher-interest-rate environment, and once again there is a lot of redefining going on. One change is that it’s finally good to be a saver again. The catch is that saving isn’t quite as safe as it used to be.
The US housing market has been stuck in neutral for nearly four years, with sales of new and existing homes plodding along at a historically slow pace. One explanation is that the average rate on a 30-year fixed-rate mortgage in the US passed 6% four years ago and has stayed above that ever since, creeping past 7% this week.
The exchange-traded fund (ETF) market is pacing toward a record-breaking year in 2026, driven by an unprecedented wave of new product launches and historic capital inflows.
Since ChatGPT was first released in 2022, the artificial intelligence (AI) trade has dominated US equity markets. Gains have been driven by three interrelated forces: enthusiasm for artificial intelligence, growing concentration in the largest technology companies and strong price momentum.
This year has presented no shortage of challenges for investors. Geopolitical conflict, trade tensions, rising energy prices, shifting interest rate expectations and an increasingly active political backdrop have each taken turns dominating the headlines. Yet despite these obstacles, the economy has continued to expand, corporate profits have marched higher and markets have climbed one wall of worry after another.
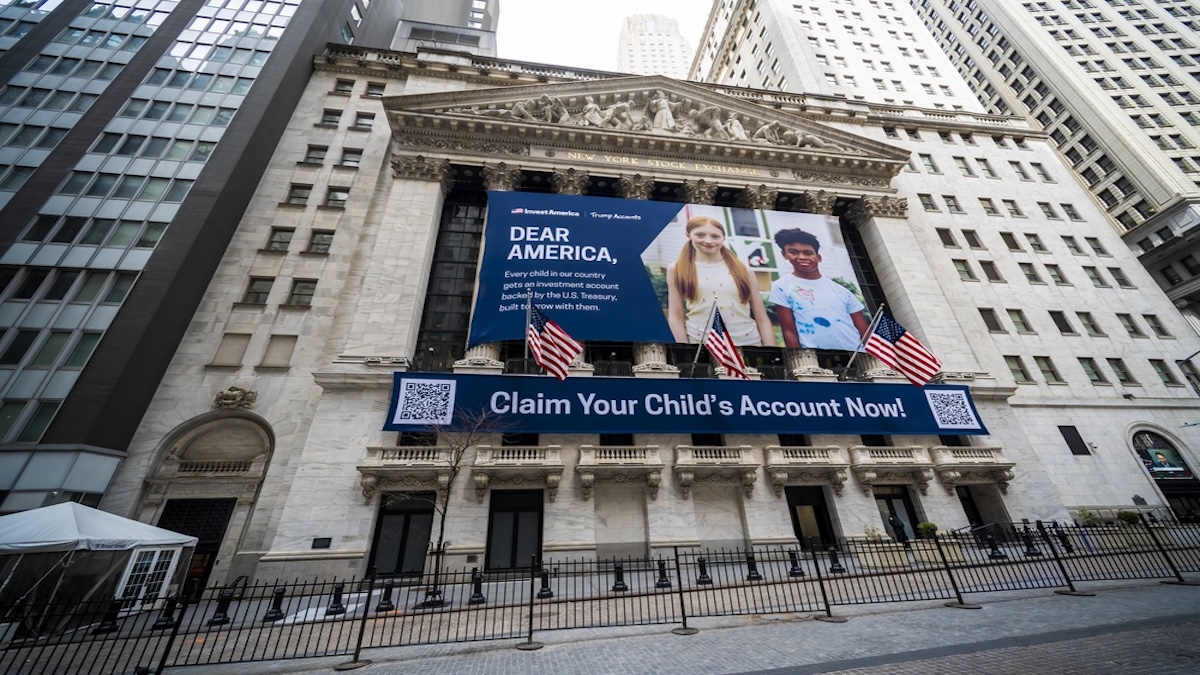
Trump Accounts are now available nationwide. Explore how the new tax-advantaged accounts work, who can contribute and key considerations for families evaluating their long-term savings options.
Confluence Investment Management offers various asset allocation products, which are managed based on “top down,” or macro, analysis. We publish asset allocation thoughts on a bi-weekly basis, updating the report every other Monday, along with an accompanying podcast.
AI has changed coding, mathematics, and weather forecasting. They all have a vast pool of available training data, rapid feedback, and clear right and wrong answers. These keep models moored to reality, not spiraling off to disaster as the result of compounding small errors.
Doshi said gold holding $4,000 during the correction and later rallying to $4,700 before last week's Fed rate hike strengthened his conviction that the broader gold bull market remains intact despite continued headwinds from the Iran war oil shock.
The Federal Reserve hiked rates, and we expect there are more to come. With a hawkish Fed and a resilient economy, long-term yields may stay elevated.
The U.S. economy has traveled farther than most forecasters expected. Strong household spending, healthy labor markets and continued business investment have kept the expansion on course.
The rise in Treasury yields has prompted a familiar set of explanations. Some investors have pointed to government borrowing and persistent inflation, while others have focused on the possibility that artificial intelligence will lift economic growth and interest rates.
Investment bubbles are inherently dangerous beasts. Like a natural Ponzi scheme, an investment bubble needs to draw in ever larger amounts of capital to keep it going. Nothing attracts capital like apparent success, so an inflating bubble that is creating fortunes for those who got in early will inevitably draw in capital. Unfortunately, this means the amount of money lost when the bubble bursts can outstrip the gains created on its way up.
Yields on the US’s longest-dated bonds climbed to the highest level in more than two decades, the latest milestone in a global selloff driven by inflation fears and concern about government debt burdens.
Cathie Wood is putting one of her investment funds on the blockchain for the first time, deepening her ties to the growing world of tokenized assets as Wall Street experiments with a new financial infrastructure.
The rush for the exits by wealthy investors in private credit funds is far from done. But even as the rich run away from direct lending, they aren’t abandoning alternative assets. Instead, they look to be chasing the next hot thing: infrastructure finance.
We know from recent history why this question feels so timely. Fixed income remains a foundational portfolio building block, offering low-correlated or uncorrelated diversification and downside risk mitigation. However, holding long-dated bonds in recent years has been notoriously painful.
The appeal of a portfolio of individual bonds for many investors are the known qualities that they can provide: a known stream of cash flow, a known redemption value, a known redemption date, and a known yield; all of which are locked in at the time of purchase.
LPL Research analyzes S&P 500 margin expansion, assessing how much is structural versus cyclical and what that means for future earnings forecasts.
It’s really starting to feel like autumn now. August PPI, CPI, and Retail Sales are in the books, the September FOMC meeting is out of the way, and we can now look forward to Jobs Week on Wall Street. Football is in full swing, and earnings season begins before you know it, with Pepsi (PEP) posting results on Thursday, October 8, followed the next morning by Delta (DAL).