Federal Reserve Chair Jerome Powell said the US central bank is prepared to raise interest rates further if needed and intends to keep borrowing costs high until inflation is on a convincing path toward the Fed’s 2% target.
As brutal as it’s been for US bond investors, the math is finally turning in their favor.
High interest rates begetting a recession was one reason many money managers were bullish on bonds after a bearish 2022. While the economy continues to run hot and a recession may not arrive, some suspect a bond bull market is still ahead.
It’s premature to call off a recession. Lower shelter costs will ease inflationary pressures. Treasury supply dynamics caught the market by surprise.
Federal Reserve Chair Jerome Powell signaled the US central bank is prepared to raise interest rates further if needed and keep borrowing costs high until inflation is on a convincing path toward the Fed’s 2% target.
Longer-dated US Treasuries – those with maturities of 5 years or longer – continue to struggle. At best, coupon payments are keeping investors relatively flat.
The drop in US stocks on Thursday despite a bumper report from Nvidia Corp. shows the rally this year is “exhausted” and portends more declines to come, according to Morgan Stanley’s Michael Wilson.
Markets seem to be coming around to our Franklin Templeton Fixed Income CIO Sonal Desai’s view that the Fed will have to keep interest rates higher for longer, but now runaway fiscal deficits pose further upside risk to yields in the long term, she warns.
Econ on the Road Labor, Consumers, Inflation & Data A Kotok Commute Conversation with: Cameron Dawson, CIO at Newedge Wealth, Dave Nadig, Financial Futurist at VettaFi, and Barry Ritholtz, CIO at Ritholtz Wealth Management.
If this is what a bad year for the dollar looks like, I'll take it. Widespread predictions of a significant retreat after a bumper 2022 haven't come to pass.
The holy grail of stock investing is buying great companies on the cheap. Stock picker Peter Lynch plied a variation of that strategy to fame and fortune in the 1980s using his so-called PEG ratio.
An abstract interest-rate metric is dominating discussions across trading desks ahead of the Jackson Hole symposium, with investors wondering if Federal Reserve Chair Jerome Powell will weigh in, and bracing for further declines in US Treasuries if he does.
The first six months of 2023 were full of surprises for investors, not the least of which was a Nasdaq surge of 32% — its best first half since 1983. The S&P 500 Index gained nearly 16% for the first half, powered by mega-cap stocks.
Interest rates are the penalty you pay for purchasing something today instead of postponing consumption until tomorrow. They are also the reward you receive for saving and engaging in delayed gratification.
VettaFi’s vice chairman Tom Lydon discussed the Amplify Online Retail ETF (IBUY) on this week’s “ETF of the Week” podcast with Chuck Jaffe of “Money Life.”
Central bankers generally believe in an abstract phenomenon known as the neutral real rate of interest, or r-star. It’s the inflation-adjusted rate that should prevail when the economy is balanced with price increases subdued and the labor market healthy.
The prospect of global interest rates remaining higher for longer is tipping the case for many investors to switch into bonds from stocks.
Investors are finally showing signs of losing their antipathy toward commodities.
In terms of manufacturing, value added, which is basically the value of the output minus the costs of the input, the U.S. produces almost twice as much as Japan, more than three times as much as Germany, and five times as much as India.
Several factors point to why this is an exceptional time to invest in small-cap stocks. Small-cap stocks tend to outperform after inflation peaks and in the aftermath of recessions. Small-cap valuations are at 20-plus-year lows relative to large-cap equities. Earnings revisions for small caps are stabilizing and beginning to outpace those of large caps. The M&A market is recovering, which historically correlates with improved small cap performance.
Entrenched long-term economic growth trends and low inflation, coupled with high and increasing leverage, all but ensure lower interest rates. This article defends that thesis and helps us better appreciate the bearish concerns weighing on bond traders.
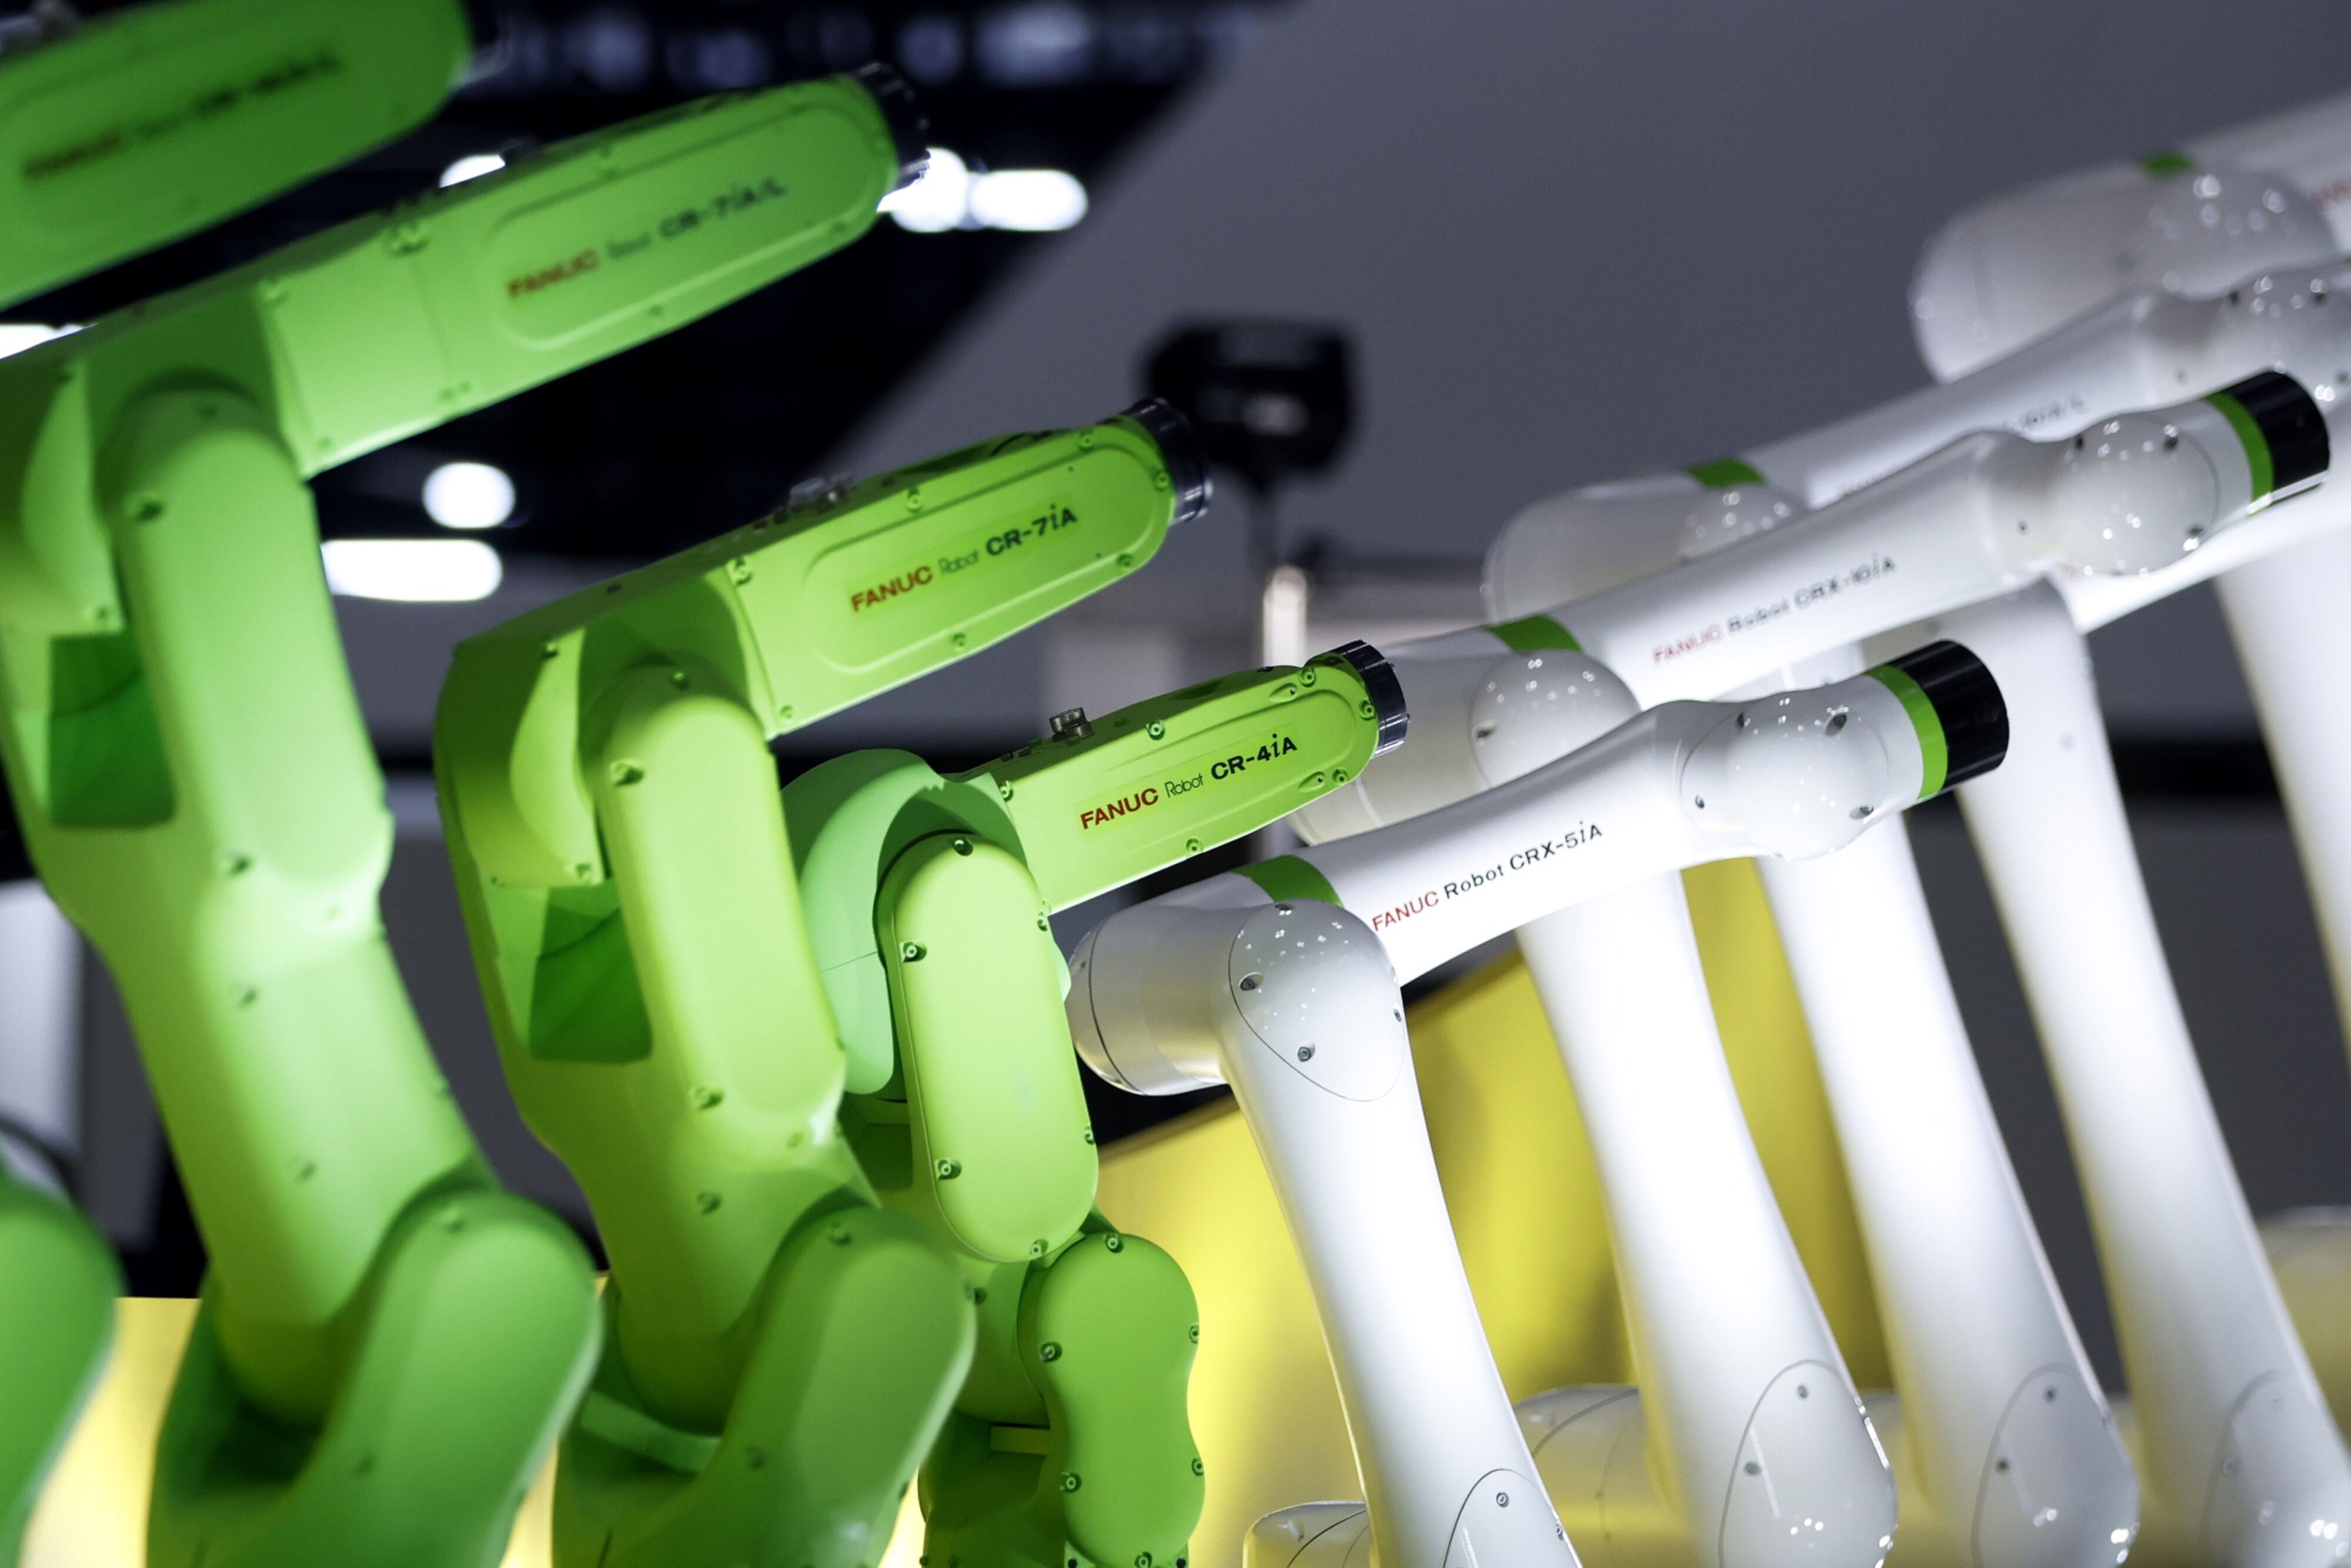
The Japanese factory automation and robot maker last month lowered its full-year operating income forecast by 24% because of a sharp slowdown in China and high inventories that could linger into next year. Its shares were quickly dumped and have continued to slide.
Since the beginning of 2022, the media has regularly warned a recession is coming.
Gold isn’t losing its allure, according to a dozen money managers who all told Bloomberg News they expect to maintain or raise their exposure to the precious metal in the coming 12 months.
Precious metals markets are extending their losing streak as the U.S. dollar pushes higher.
What’s going on with the markets and the economy? Long-term Treasury yields are up substantially since last Fall while the stock market, after a big rally, has stumbled so far this month. Meanwhile, the real economy appears to continue to chug along – even accelerating!
Better productivity is easing employers' burden of higher wages.
With the path of least resistance for stocks seemingly lower for now, key to watch will be a stabilization in interest rate volatility and clarity on the path of monetary policy.
With the Fed’s tightening on monetary policy and the constant threat of a recession looming, policymakers and advisors are closely monitoring economic indicators because the data can ultimately impact business decisions and financial markets.
The US bond-market selloff resumed Monday, driving 10-year yields to a 16-year high, as the persistently resilient economy has investors positioning for interest rates to remain elevated even after the Federal Reserve winds up its hikes.
The role of the human psychological cycle in driving stock and bond prices is well understood and pre-dates behavioural economics. There are elements that suggest we may be going through another period of ‘irrational exuberance’ as several long-term investors seem stuck in the mindset that ‘There Is No Alternative’ (TINA) to US equities.
Yields on 10-year Treasury notes have spent 18 sessions trading above 4% this year, but some doomsayers are ready to declare a permanent shift to a higher-yield regime. They attribute it to factors such as demographics, the looming clean-energy transition and large government deficits. And sure, that could be.
Who knew that the subject of US Treasury bond yields could inspire such passion? When, in late June, I argued that they were likely to move considerably higher than the then-prevailing 3.75%, I attracted some vehement pushback.
Interest rates are at 20-yr highs, yet unemployment is at 50-yr lows, core-PCE is near 30-yr highs, and Wall Street (and Fed) economic forecasts continue improving. What explains the disconnect between these unexpected outcomes and those expected by mainstream economic textbooks?
We have heard lots of commentary on the student loan repayment issues facing almost 44.5 million Americans. Some of these commentaries are correct but there are others that miss the mark.
U.S. companies broadly notched better-than-expected results in the second quarter, even as overall earnings growth for the S&P 500 saw a decline. Equity investor Carrie King sees more interesting developments beyond the numbers and posits one area that may be getting tired as another readies for a reawakening.
Whereas the U.S. is investing in new airport infrastructure and modernizing facilities to meet ambitious climate goals, European airports are choosing to combat emissions by restricting the number of flights.
If they’d been offered today’s economy a year ago – with inflation downgraded from emergency to mere headache, still-low unemployment, and growth that’s slowed without stalling – the world’s top central bankers would’ve taken it like a shot.
The Northern Trust Economics team shares its outlook for U.S. growth, employment, interest rates and inflation.
Equity traders reeling from the market’s worst stretch since February face some pivotal events in the days ahead, and a closely watched speech by Federal Reserve Chair Jerome Powell may not even be the biggest test of all.
Convinced a recession in the US was near, some of the world’s most prominent money managers loaded up on government bonds this year in a bold bet that would atone for the punishing losses suffered in 2022.
Government bonds or stocks? If you were picking an asset class to outperform over the next 18-24 months, which would you choose?
Approval of a spot bitcoin exchange traded fund in the U.S. is one of the most widely anticipated and delayed events in the roughly three-decade history of the ETF industry.
My last three letters reviewed Neil Howe’s new book about the Fourth Turning. Today we’ll look at another set of patterns observed by my friend George Friedman in the geopolitical realm. George’s view of how patterns shape countries is different but not inconsistent with Neil’s generational cycles.
We expect inflation and rates to remain higher than the last decade. We favor tech within growth and cyclicals within value.
Argentina’s leading presidential candidate, Javier Milei, has some unorthodox ideas about policy (he wants to abolish central banks), politics (he is libertarian) and pets (he has five cloned dogs). One of his proposals, however, is simple common sense: dollarizing Argentina’s economy.
All around the world, bond traders are finally coming to the realization that the rock-bottom yields of recent history might be gone for good.
Today was a disaster for Chinese economic data. In the table below, we can see that every single data point missed consensus expectations in the wrong direction. Activity undershot expectations across the board.
Return to office mandates are growing, but workers are hesitant to give up flexibility.
Monetary and fiscal policy are typically thought of as independent tools that central banks and governments use to manage the economy.