We understand that you can’t forecast the sequence of returns, but we CAN build a plan that survives a bad one. As Howard Marks puts it, you can’t predict, but you can prepare. These are the rules of engagement once you’ve crossed from saving into spending.
While the majority of advisors, 62%, still use an AUM-based fee model to charge clients, a growing number have said they now charge a retainer fee. In 2023, only 14% of advisors offering financial planning services said their compensation model was an annual retainer, while 38% said the same in the 2026 State of Financial Planning Fees study.
If you only looked at the price of gold in September, you’d be forgiven for believing the bull market had run out of steam. The yellow metal fell 6.3% during the month, and some in the financial press were quick to say it had failed as a safe haven.
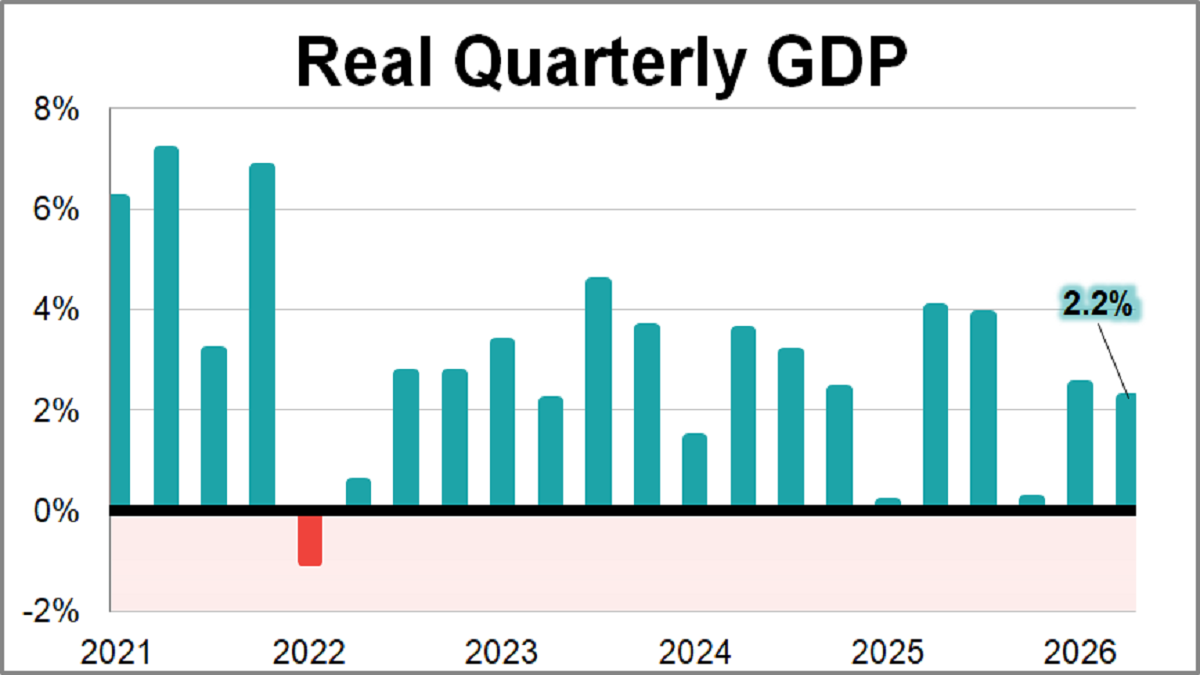
How’s the US economy doing in President Donald Trump’s second term? Going by the topline economic statistics, not too bad. Second-quarter gross domestic product was revised higher last week, to a 2.2% annualized rate from a previously reported 1.5%. At 4.2%, the jobless rate is consistent with an economy considered to be at full employment.
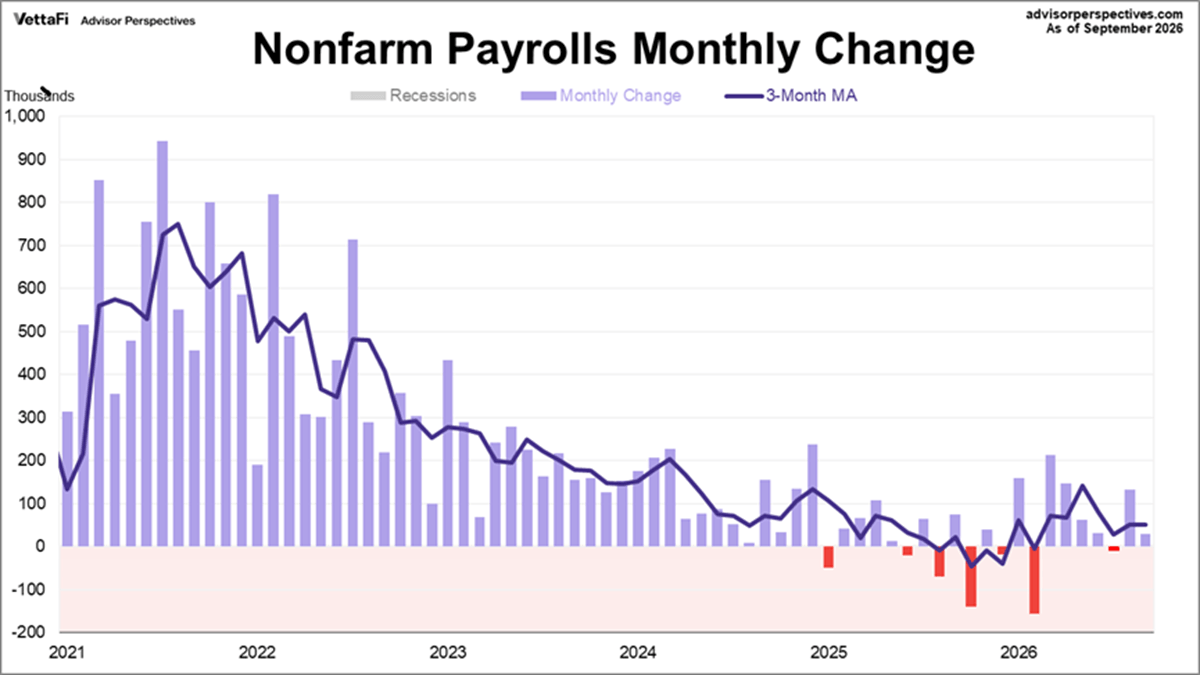
Today’s employment report reinforced a trend that has been evident across several labor market indicators: conditions in the goods-producing sector continue to improve after several difficult years, while hiring across the much larger service sector continues to soften.
Nvidia Corp. is on the verge of becoming the first company with a $6 trillion market capitalization as investors rotate back into the artificial-intelligence chipmaker after a disappointing start to the year.
Societal angst about AI continues to grow. Whether it’s concern about misalignment or potentially misdirected investment, the AI-may-be-bad narrative is gaining traction. In stark contrast, the AI trade in financial markets was alive and well in September of 2026.
Our real gross domestic product (GDP) forecast for 2026 is 2.5% (based on our Global Investment Management Survey) versus the Federal Reserve’s (Fed's) forecast of 2.2% and the Wall Street consensus of around 2%.
September’s fixed income sell-off marked a watershed moment for muni bond markets, delivering the steepest drawdown since the 2008 Great Financial Crisis. As benchmark yields spiked, prices across muni ETFs fell in tandem, and the volatility has not let up. This week, both 10-year and 30-year Treasury yields climbed to their highest levels since 2002.
The latest employment report showed that 29,000 jobs were added in September, compared to August's 133,000 gain. This figure was significantly lower than the projected addition of 89,000 jobs. Meanwhile, the unemployment rate increased slightly from 4.1% to 4.2%.
How much one needs for retirement is both a mathematical and emotional equation to solve. For both my clients and myself, enough is never enough because we fear a stock market plunge, inflation, or both (stagflation). But these four practical uses of TIPS provide near certainty of having enough to enjoy the rest of one’s life. Rarely do math and emotion each arrive at the same solution.
Today, TINA logic is less compelling. Risk-free five-year and longer Treasury notes and bonds yield over 5%, and investment-grade corporate bonds yield even more. At the same time, stock valuations sit near record levels, implying weak forward returns. The acronym that best describes today's market is TIGA (there is a good alternative).
Wall Street has spent weeks trying to make peace with the great bond selloff. Friday offered some short-lived relief — along with a warning about the damage from stubbornly high yields across investment strategies of all stripes.
The bond market took center stage through September with inflation, oil supply chains and the Federal Reserve performing as an ensemble.
Neither a borrower nor a lender be,” wrote William Shakespeare, who was one of history’s greatest authors but obviously ill-versed in economics. Without lending or borrowing, our modern economic society wouldn’t grow very much, AI or not.
T. Rowe Price has announced the launch of the T. Rowe Price Dynamic Emerging Markets Bond ETF (TDEM) on the Nasdaq today, the company said.
Recent bond market repricing has pushed municipal yields to levels not seen in decades and improved the potential risk-reward profile for fixed income. Here, we examine why municipals stand out, how supportive credit fundamentals shape the opportunity and why investors may benefit from extending maturities to lock in attractive tax-exempt income.
The Fed’s latest 25 basis point hike might represent a recalibration rather than tightening. Instead of focusing on the next hike, investors should watch broader financial conditions and the long-term trajectory for interest rates.
Market participants have been conditioned to expect clear Forward Guidance from Fed Chairs. Chairman Warsh has made it clear that Forward Guidance will be less under his leadership, but he has offered a very important qualifier that many have yet to grasp.
Today, we’re going to look at a lot of various data points and analysis, that when taken together give us a much clearer picture of the total world.
Emerging markets have significantly evolved in recent years and offer a more compelling risk/reward setup than in the past. From deeper local markets to world-leading companies, Emerging markets presents a stronger opportunity than geopolitical volatility suggests.
Softer U.S. inflation and labor data as well as more cautious comments from Federal Reserve officials shifted the rates outlook this week.
Municipal bond asset managers are finding opportunities in the rout that tore through markets this month, with cheaper valuations and the highest yields in years drawing investors.
In September, Vanguard ETFs overall recorded a mix of steady market performance, some volatility, and significant dividend distributions, with investors pouring substantial capital into its funds.
Fixed-income investors are being paid more to take risk than they have been in years, but not all opportunities are created equal. Higher yield levels, heightened volatility and growing differences across countries, sectors, industries and issuers are expanding the opportunity set. Dispersion is the raw material from which active returns are generated. Below are four ways investors can capitalize on it.
Midterm elections are increasingly taking over the headlines, and that includes coverage of markets. While inflation, rates, and geopolitics probably have more outright impact on portfolios, investors and market watchers still look to midterm elections as a major event.
Franklin Equity’s Grant Bowers discusses why a higher cost of capital does not change the capital expenditure outlook.
The sell-off in U.S. Treasury (UST) yields has continued pretty much in an unabated fashion In fact, multi-year high watermarks are being achieved throughout the fixed coupon maturity curve. The most widely followed development was the UST 10-year yield rising to its highest level since 2007.
Markets await a possible Fed rate hike as Congress weighs Trump's dividend proposal, a limited fall session, and a Senate vote on crypto regulation.
Yesterday’s cooler-than-expected PCE print finally gave the bond market a breather, pulling Treasury yields down from their brief 5.3% peak. For financial advisors, this recent whiplash brings fixed income duration conversations back to center stage — specifically, balancing the hunt for long-term yield with the safety of ultra-short cash alternatives.
Munis can fund local power, grid, water and wastewater infrastructure; most AI campus capital will be financed in non-municipal markets.
Explore how muni bond ETFs and targeted state funds can provide tax-efficient yields and strategic flexibility heading into 2027.
The Securities and Exchange Commission is proposing a series of moves to help expand retail investor access to private markets, so more individuals can access private equity, early-stage startups and other assets.
Assessing the wall of worry. Here, we assess the market's growing wall of worry, explain why these worries warrant attention, and justify our continued constructive intermediate-to-long-term stock market outlook.
Economic data from last week continued to paint a picture of a robust U.S. economy with an accelerating pace of growth. After a strong durable goods report showed business fixed investment continuing to rise on the back of ongoing AI data center buildouts, the Atlanta Fed’s GDP Now estimate for third-quarter real economic growth remained at an elevated 5 percent.
Some employer retirement plans allow after-tax contributions that can be converted to Roth assets. Learn how a mega backdoor Roth strategy works and key considerations for retirement planning.
From social media and AI tools to financial professionals and workplace resources, defined contribution (DC) plan participants are drawing retirement insights from an expanding portfolio of sources, according to our latest survey. But more content doesn’t necessarily mean better outcomes. We think plan sponsors are well positioned to help participants cut through the noise.
Yields have pushed higher with some points on the curve reaching yield levels not seen since the mid-2000s. While it is nearly impossible to pinpoint a specific catalyst for any move in the financial markets, below are a few of the factors that have helped push interest rates higher.
Higher-for-longer interest rates are forcing buyout firms to face facts. Struggling since 2023 to sell companies purchased in the long decade of ultra-cheap debt before the Covid pandemic, they’ve tried to placate investors with clever financial engineering to help keep some money turning over.
It’s a complicated economic environment to retire in, with high costs and significant geopolitical and policy uncertainty. Still, people want and often may need to retire. However, thanks to innovation in the asset management world, investors have an increasing array of options.
Given that the Federal Reserve raised interest rates earlier in September, inflation data that was already crucial has taken on a new meaning. These reports could now serve as a barometer for what is to come from the central bank.
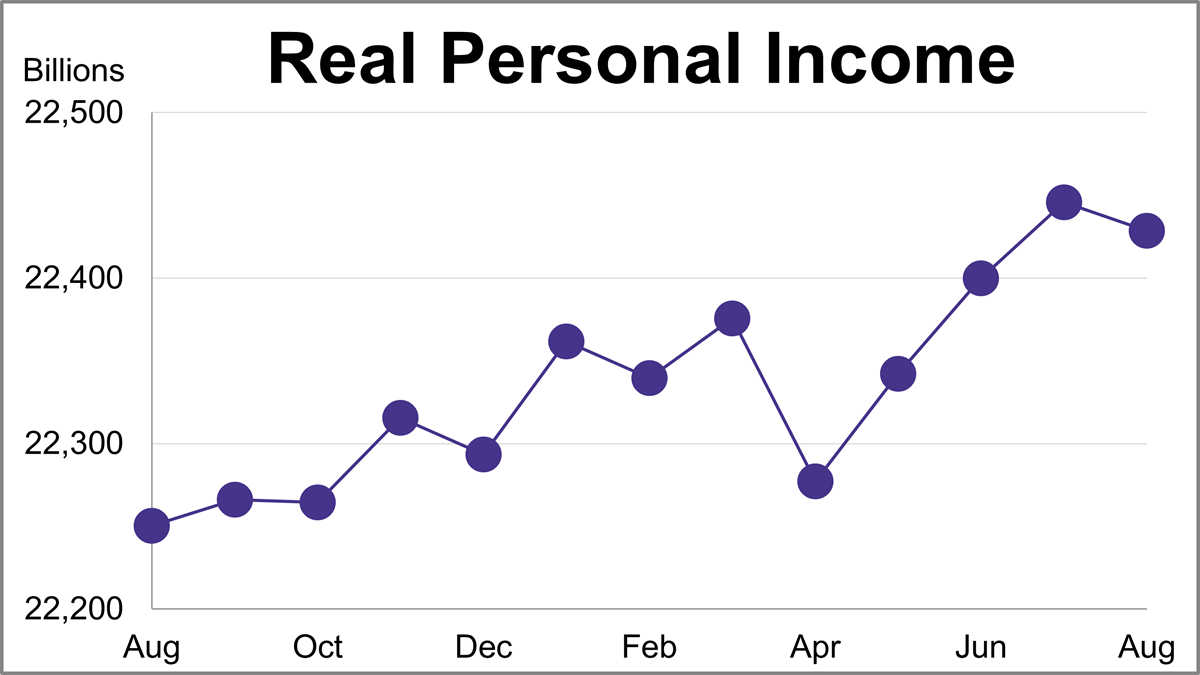
Personal income (excluding transfer receipts) was up 0.23% in August and was up 4.25% year-over-year. However, when adjusted for inflation using the BEA's PCE Price Index, real personal income (excluding transfer receipts) was down 0.08% month-over-month and up 0.80% year-over-year.
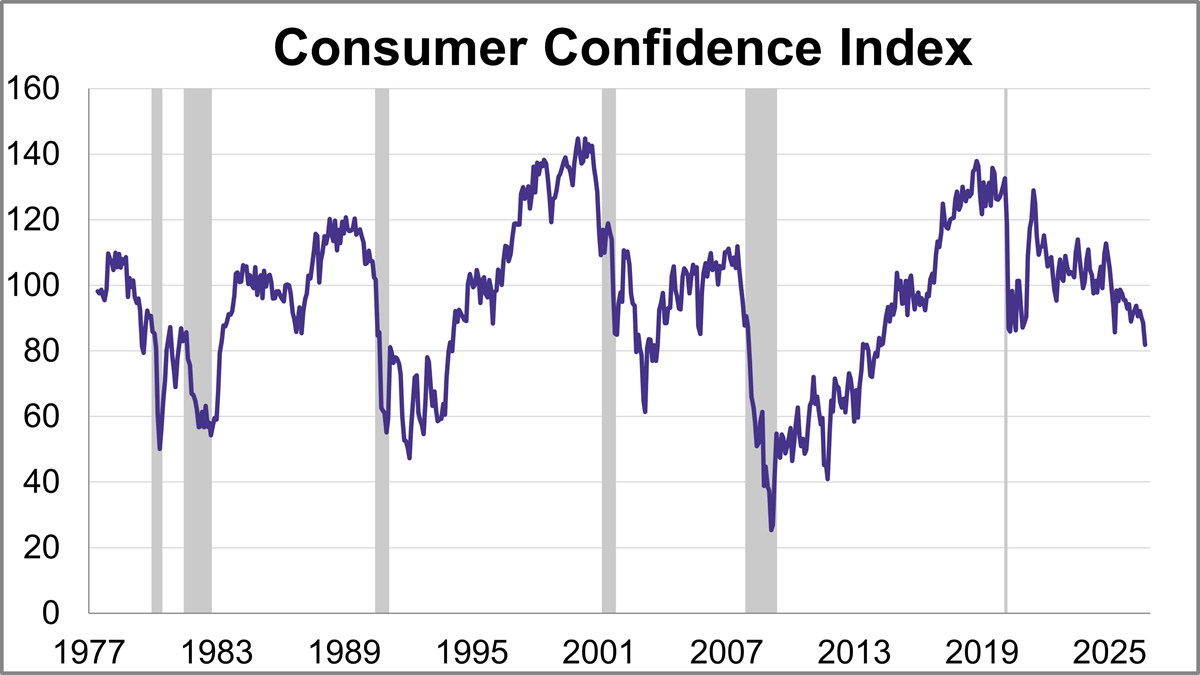
The Conference Board's Consumer Confidence Index® fell significantly more than expected in September, falling 6.7 points to 81.9. The index was far below the forecast of 89.2.
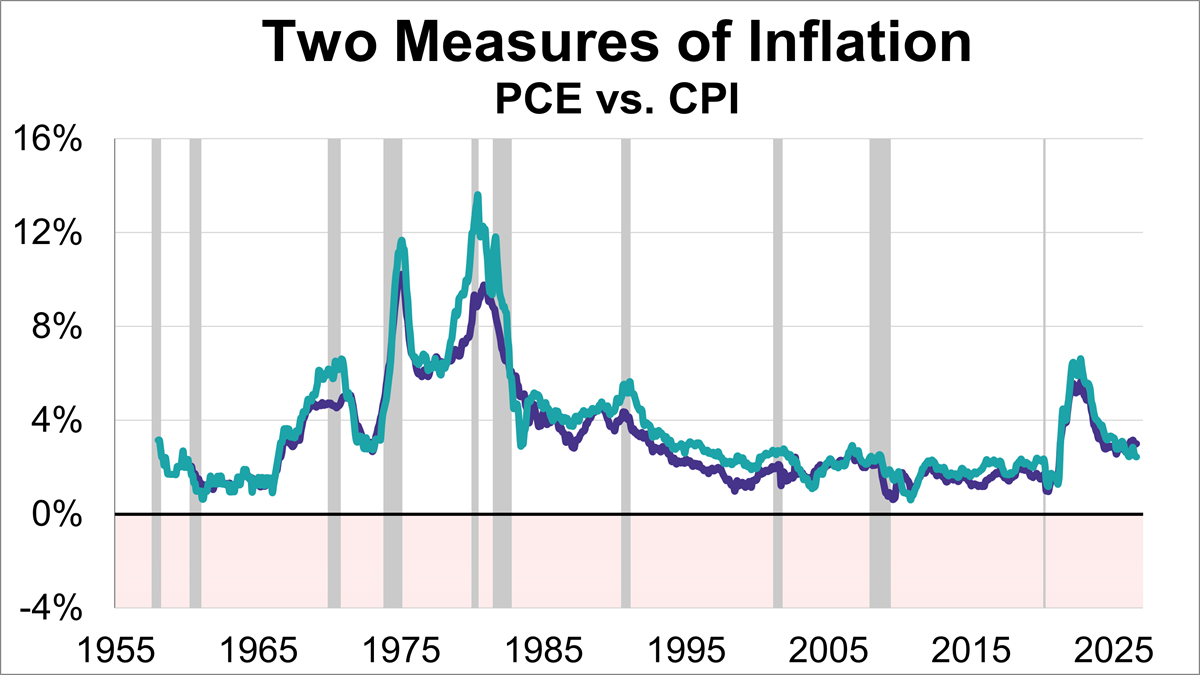
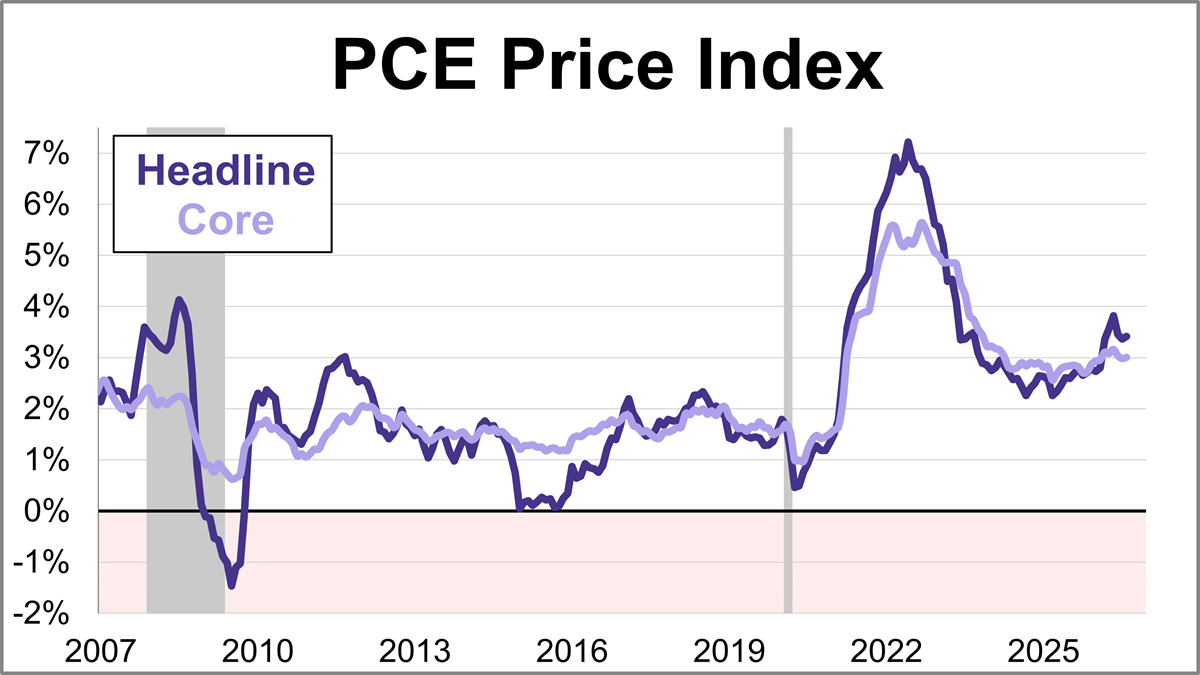
Inflation remains a hot topic, directly impacting everything from your grocery bill to interest rates. As of the latest data, two key inflation gauges — the Personal Consumption Expenditures (PCE) Price Index and the Consumer Price Index (CPI) — show that prices are still above the Federal Reserve's 2% target, with the core PCE at 3% and core CPI at 2.5%.
The Federal Reserve’s preferred inflation gauge, the core PCE price index, climbed 3% year-over-year in August. This marks no change from July's reading. On a monthly basis, core prices rose 0.2%.
Finance leaders can use agentic AI to boost budget visibility, develop more accurate forecasts efficiently, and find insights in data that would typically require extensive manual effort. With the right platform and a careful approach to governance, finance functions can start reaping the benefits of augmentation within months.
Stock-market risks are everywhere. But you’d be hard pressed to tell anything was wrong by looking at the surface of major US equity gauges.
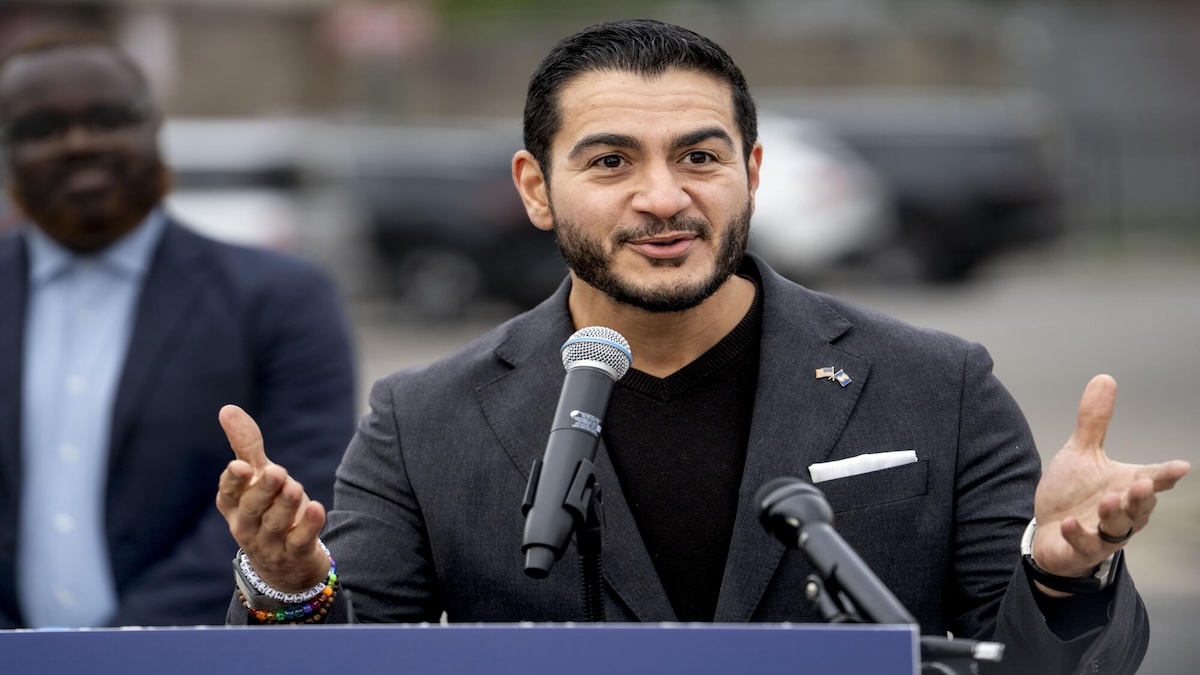
Abdul El-Sayed, the Democratic candidate for Senate in Michigan, has a simple pitch to voters. Imagine, he says, a health-insurance plan with “no premium, no copay, no deductible — just healthcare when you need it.” El-Sayed and other proponents call the idea Medicare for All.
Real GDP rose 2.2% in Q2 for the third estimate from the U.S. Bureau of Economic Analysis, which was a 0.7% increase from the previous Q2 advance and second estimates.
Bond markets continue to adjust to a more hawkish policy environment following the Federal Reserve’s recent 25-basis-point rate hike.