While don’t think of myself as being old, I can’t call myself young anymore. When I go to the gym, it takes me longer to stretch than to work out. People my age debate the best vitamin supplements, not the best burger joints. When I am asked for identification at the market, it isn’t to confirm I am old enough to buy beer; it’s to see whether I am eligible for a senior discount.
Narratives are almost always wrong: clever stories that explain the past and say nothing about the future. One may be right. AI may become the dominant technology of the century and render much of the present economy obsolete.
On July 24, China’s Ministry of Finance and State Taxation Administration announced that putting assets into an offshore trust, and earning income through one, are taxable events. The rate is 20%, and it applies not just when assets go in but also when they earn income and when the trust is wound down.
In light of accelerating global fragmentation and geopolitical conflict, many governments and businesses are investing in resilience. That imperative has coincided with the emergence of AI, a technology that can expand the frontier of what is possible. As a result, technology security is becoming a pillar of national economic security strategy.
An AI rendering of a 19th-century Jon Gray, complete with pitchfork, waistcoat and straw hat, flashed up behind the Blackstone Inc. president at a recent meeting with investors.
Earlier last week, a supertanker loading crude in the Gulf of Oman was fixed at $1.01 million a day for a voyage to Asia, with another deal reportedly agreed at $1.16 million.
Strong corporate earnings will be pivotal to hopes for a year-end rally in global stocks, as flare-ups in fears over inflation, bond volatility and artificial intelligence spending weigh on sentiment.
SpaceX investors are finally getting some reprieve after months of being whipsawed by volatility as the Elon Musk-led company’s stock breaks above the level it’s been stuck below since July.
Amid heated discussion of the astonishing (and also rather worrying) capabilities of artificial intelligence, investors are realizing that the underlying computing and energy infrastructure relied upon by OpenAI, Anthropic PBC and their ilk is much harder to construct than a chatbot prompt.
The economist Robert Solow’s famous 1987 adage about the computer age — it can be seen everywhere except the productivity statistics — also applies to generative artificial intelligence.
For decades, investors have used growth and value allocations as a foundational block of equity portfolio construction. The distinction has been intuitive and practical. Investors expected growth to provide exposure to faster-growing companies, often with higher valuation multiples and greater sensitivity to earnings expectations.
This year has marked another remarkable chapter for the global economy and financial markets. Investors have navigated no shortage of challenges, from geopolitical conflicts and trade tensions to elevated energy prices and shifting interest rate expectations. Yet despite these headwinds, the economy continues to expand, corporate earnings remain resilient and markets have steadily climbed the proverbial wall of worry.
In this month’s issue, AI, energy and robotics are creating new opportunities in emerging markets, but selectivity remains key as policy, cost and execution risks evolve.
Diversifying your portfolio across the globe will not completely insulate you from a bad year in equities, because global markets tend to rise and fall together. However, that diversification can help shield your retirement resources from the decline of any single country.
If you only looked at the price of gold in September, you’d be forgiven for believing the bull market had run out of steam. The yellow metal fell 6.3% during the month, and some in the financial press were quick to say it had failed as a safe haven.
Executives enter the earnings season with a bit of a swagger. They won't say it out loud, of course, but consider all the headwinds CEOs of companies big and small have faced in the last few years. First, it was imminent recession fears; then it was looming tariffs (followed by the shock of April 2025).
Oil fluctuated in jittery trading, as Saudi Arabia cut prices of its benchmark grade to Asia, the kingdom’s state producer warned about the risk of low stockpiles and as fighting in Yemen intensified.
The Fed’s latest 25 basis point hike might represent a recalibration rather than tightening. Instead of focusing on the next hike, investors should watch broader financial conditions and the long-term trajectory for interest rates.
Emerging markets have significantly evolved in recent years and offer a more compelling risk/reward setup than in the past. From deeper local markets to world-leading companies, Emerging markets presents a stronger opportunity than geopolitical volatility suggests.
Assessing the wall of worry. Here, we assess the market's growing wall of worry, explain why these worries warrant attention, and justify our continued constructive intermediate-to-long-term stock market outlook.
Globalization is being reorganized around security and resilience, creating uneven risks and opportunities across markets.
In the first quarter of this year, as the Strait of Hormuz closed and oil prices exploded, Berkshire Hathaway made a couple of moves that might have flown under people’s radars.It cut its stake in Chevron by roughly a third. Then it bought an airline.
Among the world’s top fuel-consuming nations, Japan is the most energy insecure. Its import-dependency ratios are scary: It buys overseas 99.9% of the oil it needs; 99.7% of the coal; and 97.8% of the natural gas.
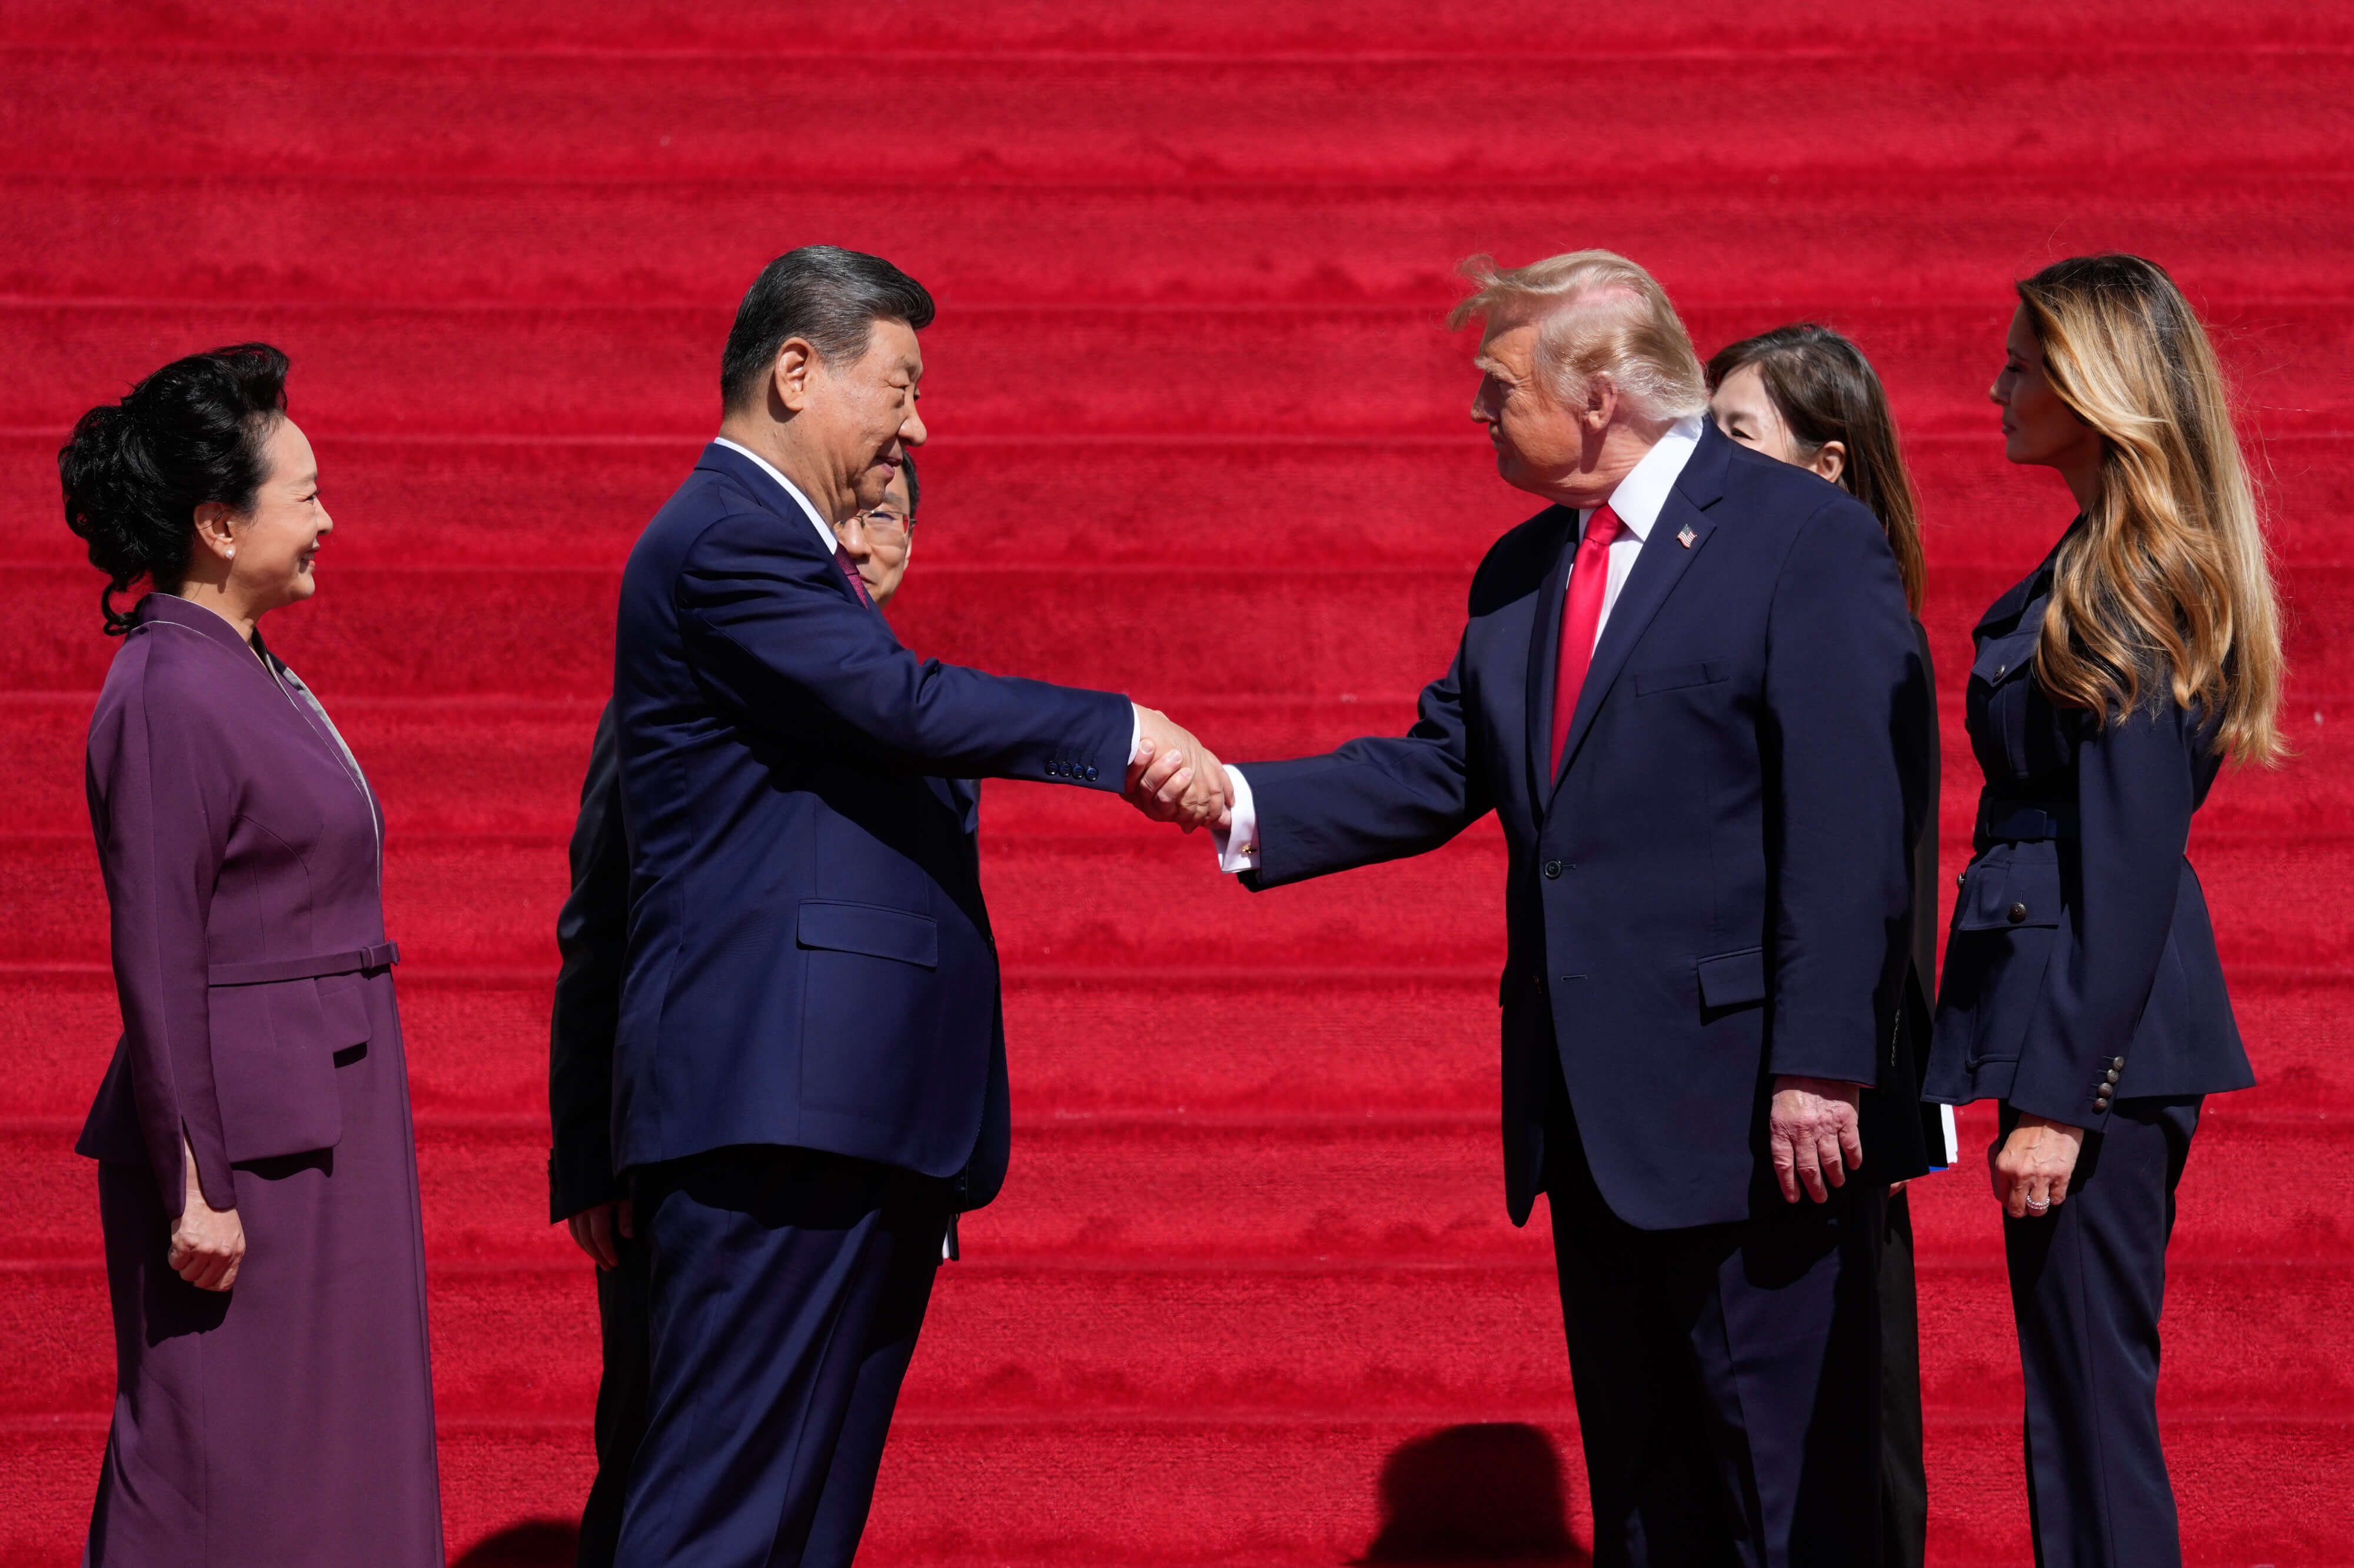
The US and China detailed a plan to cut tariffs on about $30 billion of imports from each country, taking a step toward fulfilling a key outcome of last week’s summit between Donald Trump and Xi Jinping.
The U.S. economy remains resilient despite headwinds including sticky inflation, trade instability and rising geopolitical tensions. State and local government tax revenues have followed suit and have posted solid growth, aided by robust equity market returns.
Artificial intelligence (AI) leadership is no longer a developed-market monopoly. Emerging markets (EM) now have their own AI champions, and productivity gains may follow. For bond investors, we expect the implications to differ by country—driven by industry composition, capital intensity, digital infrastructure and speed to adoption.
Asset owners want private-market exposure, but liquidity remains their biggest hurdle, an opening advisors can meet with public alternatives.
US stocks climbed as oil and Treasury yields pulled back from the recent surges ahead of data on inflation expectations.
This year has presented no shortage of challenges for investors. Geopolitical conflict, trade tensions, rising energy prices, shifting interest rate expectations and an increasingly active political backdrop have each taken turns dominating the headlines. Yet despite these obstacles, the economy has continued to expand, corporate profits have marched higher and markets have climbed one wall of worry after another.
Artificial intelligence (AI) technologies are developing faster than investors anticipated just a few years ago, fueling a popular narrative that AI will trigger widespread job cuts. Yet there’s little evidence to back this view. Instead, we find that AI is changing hiring patterns, altering skill requirements and shifting the mix of work performed within firms.
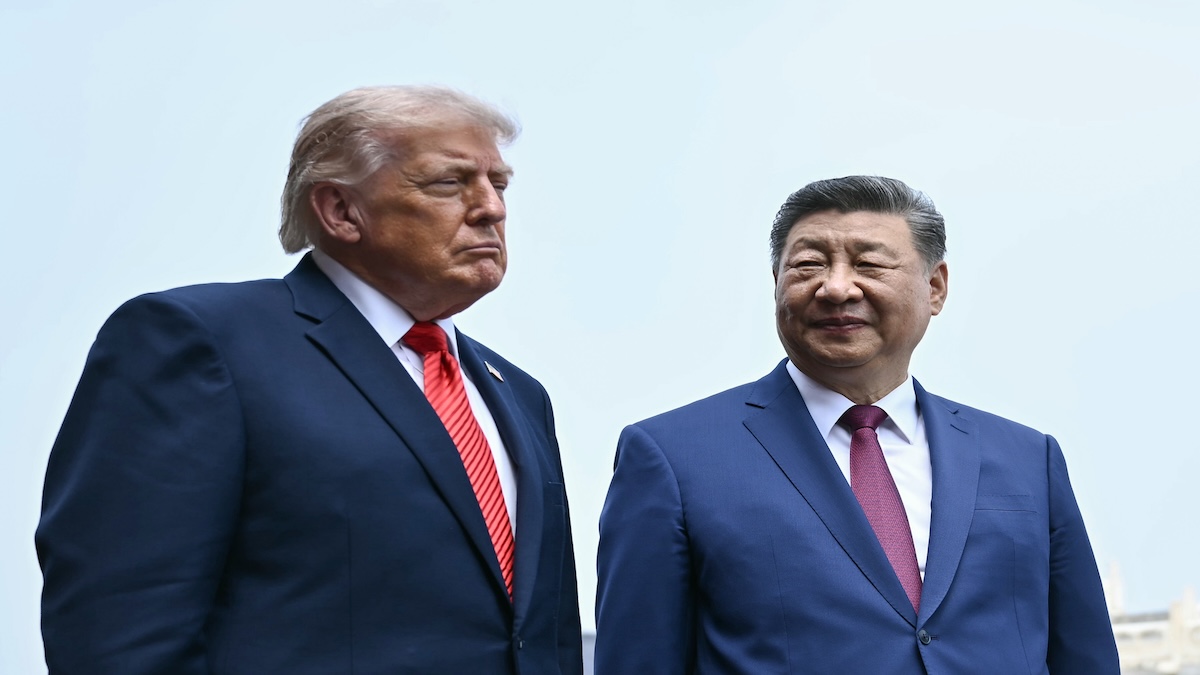
Xi Jinping and Donald Trump will sit down this week to hash out a plethora of thorny issues from trade to Taiwan. One thing both sides agree on: neither can afford to tap the brakes on AI.
Early this week, I was in Los Angeles at the All-In Summit along with about 4,000 others, including tech investors, money managers and entrepreneurs. The ticket wasn’t cheap, but it was well worth it.
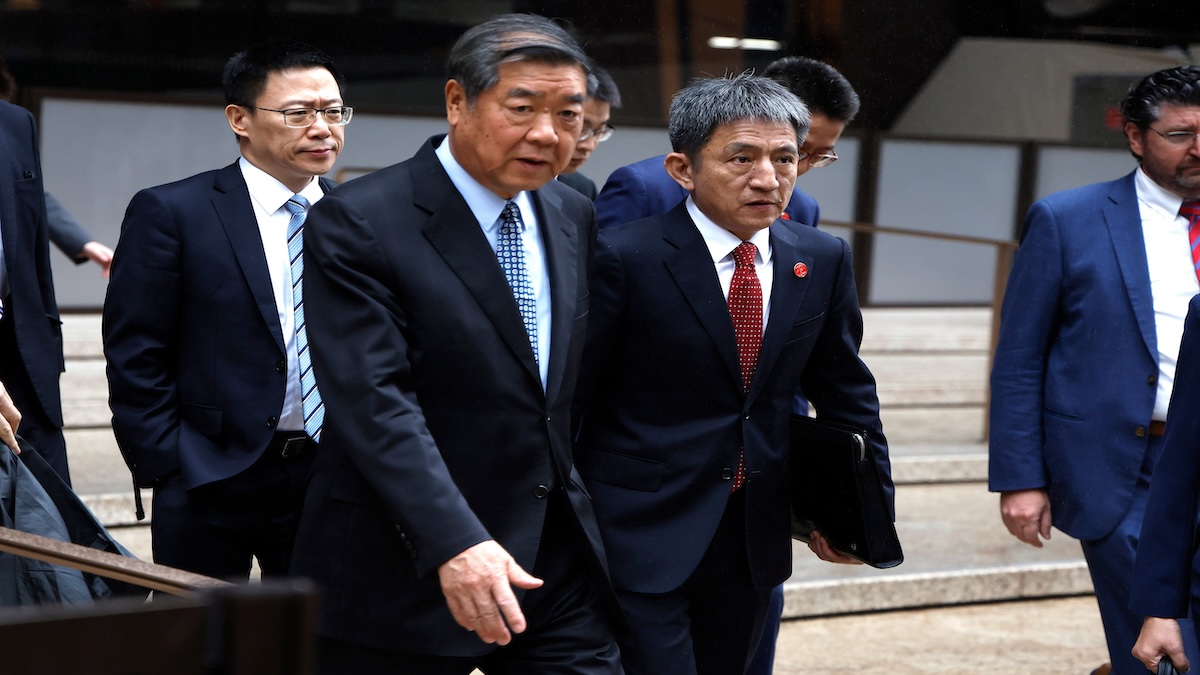
US and Chinese officials offered upbeat assessments of their talks on artificial intelligence, trade and investment, signaling a mutual desire to steady ties ahead of this week’s summit between leaders Donald Trump and Xi Jinping.
Janus Henderson Investors today announced two senior investment appointments that will further deepen the firm’s leadership across its global equities franchise.
The Federal Reserve raised interest rates this week, in part to reset consumer expectations on inflation. Their work is likely not done, as there is a negative surprise coming for many consumers, especially in rural America. Winter is coming, and that means the return of home heating bills. Depending on how you heat your home, your bills could be much higher this winter.
The Federal Reserve (Fed) made something clear this week that markets had been reluctant to accept. Apparently, the easing cycle isn't paused, it's over for now.
The recent global bond sell-off may be more than a temporary repricing. Rising government debt, persistent inflation risks and shifting economic expectations could keep longer-term yields elevated relative to the post-financial-crisis era.
Last week, the refining margin on European gasoil, the benchmark that sets the price of diesel and heating oil across much of the world, closed at roughly $94 a barrel over Brent crude, according to Bloomberg data. That figure is normally somewhere between $12 and $18.
China criticized warnings from leading US technology executives to put the brakes on artificial intelligence development and claims that Chinese progress posed a dire security threat to the world.
Equity markets generally moved lower as rising yields and energy prices created a more challenging backdrop. Higher yields can be particularly difficult for long-duration equities, where a greater share of expected cash flows sits further into the future.
Brent oil spiked to $105 a barrel as rising tensions in the Middle East heightened concerns over global supplies.
If you’re planning on driving anywhere this Labor Day weekend, be prepared to pay the highest gas prices ever for this time of year. The national average hit $4.14 per gallon on Thursday, an approximately 30% increase from last year, according to AAA.
To kick off our fourth season of the Alternative Allocations podcast series, I sat down with John Bowman, CEO of CAIA Association, to explore the massive changes underway across our industry. John and I discussed CAIA’s seminal paper “The World Rewired,” and the implications for private markets.
Around 2020, Apple Inc. Chief Executive Officer Tim Cook returned from a trip to Asia unusually energized about a new product category: foldable phones.
Emerging-market (EM) equities have benefited enormously from the global AI investment boom. But headline market gains show that EM leadership has become concentrated in a handful of mega-cap technology stocks. In our view, today’s EM benchmark is far less diversified than many investors assume, creating opportunities to seek differentiated sources of return.
Geopolitical headlines can quickly move markets, but investors do not need to predict every headline to identify potential opportunity. The more useful question is what governments, businesses and consumers are doing in response to a changing strategic environment, and which companies may benefit.
Most people experience transportation through roads and airports. Traffic jams on highways and delays at major hubs are familiar frustrations. But the world's most important transportation network lies largely out of sight.
San Antonio has been my adopted home for close to 40 years now. I’ve watched it grow through more than one boom cycle, but recent Redfin data suggests we could be looking at a bust.
A weaker U.S. dollar cycle is boosting the appeal of emerging market debt, creating a compelling case for investors seeking income and diversification at an opportune time for the asset class.
Something strange has been happening in America lately. The Wall Street Journal says this is the summer when the U.S. became “a nation of Luddites.” The Economist calls it “the Summer of Ludd.”