The equity market appears to be showing signs of broadening beyond technology.
The US Treasury on Wednesday maintained its guidance on keeping sales of longer-term debt unchanged well into 2025, despite newly installed Secretary Scott Bessent having criticized the issuance strategy of his predecessor before he was picked for the job.
Gold climbed to a fresh record high, as trade-war worries bolstered haven demand and there were continued signs of short-term tightness in the market.
After the trade war’s opening salvoes, tensions seem set to last for some time.
In the face of uncertainties, financial advisors are uniquely positioned to help their clients prepare for the unexpected. By leveraging innovative risk management solutions, advisors can help businesses gain the stability they need to weather today’s disruptions and build resilience for the future.
Despite still elevated domestic inflation, weak growth and inflation projected at target this year strengthen the case for further rate cuts.
Last week’s volatility in AI-related stocks shows markets are learning in real time about the transformation underway.
After this week’s FOMC decision to hold the fed funds rate unchanged, markets and analysts concluded that Federal Reserve members had changed their views on inflation.
Managers see mixed opportunities in emerging markets and a broadening opportunity set for small caps across global markets.
Investors plowed record cash into a pair of leveraged loan ETFs last week, in a high-conviction bet that the Federal Reserve will be slow to slash interest rates.
In this article, Russ Koesterich discusses why gold may continue to advance in 2025 despite a stronger dollar and elevated real rate environment.
The Federal Reserve made it clear on Wednesday that it’s not about to cut short-term interest rates again anytime soon, which is good news if you’d like to see the Fed live up to its goal of bringing inflation down to 2.0%.
What a week! Markets were rocked by a series of developments—from AI news that could reshape the tech sector, to the Fed’s policy stance, and the tariffs on Mexico, Canada, and China that could inject fresh uncertainty into global trade.
Tariffs could upend the U.S. auto and energy sectors.
We suspect many investors today think the “American Exceptionalism” they studied in high school or college no longer applies to the U.S.
Economic indicator SPDR S&P 500 ETF Trust (SPY) fell 1.01% last week while the Invesco S&P 500® Equal Weight ETF (RSP) was down 0.53%.
After repeatedly blasting Janet Yellen last year over her department’s strategy for issuing federal debt, it’s now up to Scott Bessent to make the call on sales of Treasuries, with bond dealers conflicted over what he’ll do in a pivotal release due Wednesday.
US bond markets are flashing a warning to US President Donald Trump that his move to unleash tariffs on top trading partners risks fueling inflation and stymieing growth.
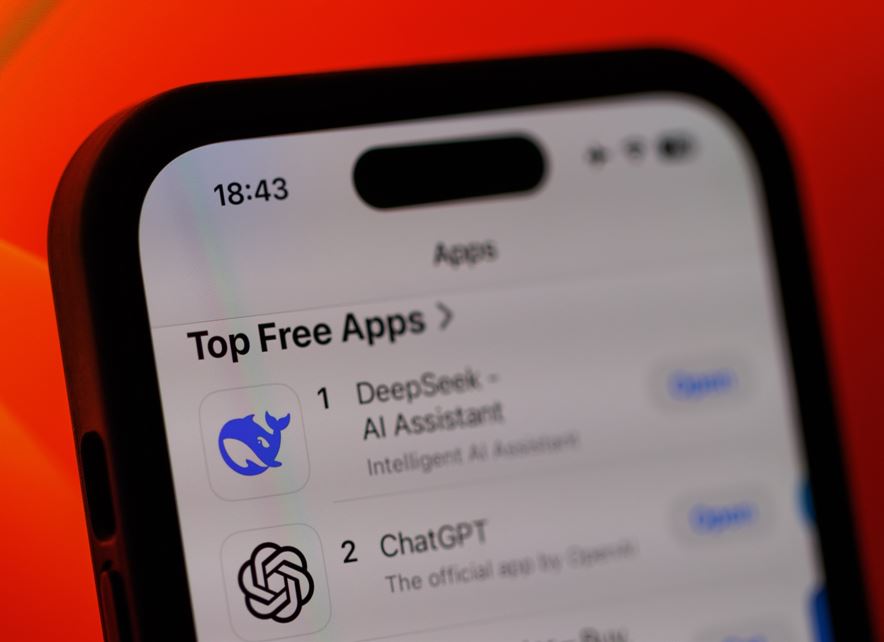
I recently asked DeepSeek to model the impact of artificial intelligence on US labor productivity growth.
A lot has changed since a new administration took charge on Jan. 20, so the Federal Reserve’s decision last week to maintain its policy rate might seem odd.
A surprise is a completely unexpected outcome. By definition, a surprise is improbable, and its occurrence is rare. It seems strange then to try to predict three of them every year.
Jeff and Ron Muhlenkamp discuss ongoing inflation and modest but steady GDP growth. In 2024 stock markets mirrored 2023, with AI-related tech companies driving growth, while long-term bonds yielded little.
For the first time since the Fed began cutting rates at their September FOMC meeting, the voting members decided to keep rates unchanged to begin 2025.
The fourth quarter was particularly volatile in fixed income markets, with U.S. government bond yields surging on worries over the rising fiscal deficit and the potential for inflation to reaccelerate.
After cutting rates at the past three meetings, it looks like the Federal Reserve has reached a plateau.
Following 100 basis points in rate cuts through the back half of 2024, the Fed started 2025 with a pause, placing itself in wait and see mode for the foreseeable future.
The higher yields they currently offer can be a benefit for income-oriented investors, but those yields reflect the additional risks they face.
Facing an uncertain outlook, the Federal Reserve holds rates steady and signals a watch-and-wait approach.
Looking back to 2024, global equity markets remained resilient despite a challenging final few weeks. U.S. equities led both annually and quarterly, buoyed by robust corporate earnings, supportive fiscal policies and market optimism following the Republicans’ red sweep in November.
A small band of Wall Street skeptics are moving to protect their credit portfolios against a market priced like nothing in the economy could possibly go wrong.
The stock market posted some noteworthy streaks of its own in the fourth quarter.
Investors may be at a crossroad in early 2025. US equities have recovered from the 2022 bear market with two exceptional years of +25% returns.
China’s efforts to steer between domestic and international growth challenges in 2025 could be good for bond investors.
Despite continued underperformance in 2024, the biotech sector enters 2025 with a brighter outlook driven by groundbreaking innovations like mRNA cancer vaccines and CRISPR-based therapies.
The first month of 2025 will soon be behind us. We’ve seen new inflation data and earnings season start to ramp up.
Economic indicators provide insight into the overall health and performance of the economy. They are closely watched by many.
Concerns about the outlook for Treasuries have fueled a resurgence of interest in the Magnificent 7 as a target for safe-haven flows.
In today’s post, we will examine the money supply represented by M2, the Federal budget deficit, the Fed’s previous adventures with QE, and the correlation to inflation.
Equity markets are facing a variety of headwinds, but the economy remains strong, and we believe there will be ample opportunities to invest in attractively valued quality growth companies in 2025.
Markets responded positively during Trump's first week in office, despite threats of tariffs on the three largest trading partners of the U.S. Are trade risks being dismissed?
Quality has become a popular buzzword in equity investing. But what does it really mean?
China will struggle to maintain momentum without addressing deeply-rooted problems.
You’ve likely heard the saying “when the going gets tough, the tough get going.” A similar principle can apply to investing: “when the going gets tough, stay in the market.”
Howard Lutnick, President Donald Trump’s nominee to lead the Commerce Department, offered a detailed defense of tariffs in his confirmation hearing, the clearest signal yet from a cabinet pick that the new administration is prepared to impose the levies on allies and adversaries alike.
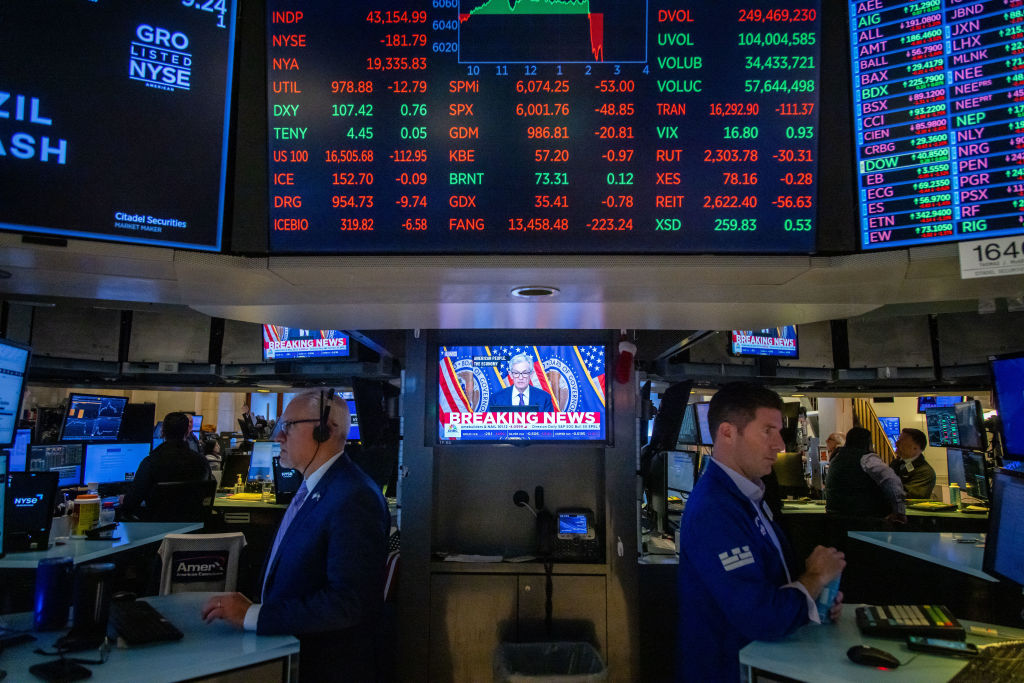
Federal Reserve Chair Jerome Powell said officials are not in a hurry to lower interest rates, adding the central bank is pausing to see further progress on inflation following a string of rate reductions last year.
US Treasuries were lower as traders parsed tweaks to the Federal Reserve’s policy statement regarding progress on the fight against inflation.
“Debanking” is about to get a lot of airtime in US politics, but be warned: This debate is a chimera. Crypto enthusiasts, culture warriors and banks all have dogs in the hunt, with each leaning on the others’ interests and narratives to advance their own.
Close scrutiny of the investment landscape reveals there is precious little room for the Trump administration to improve conditions for stocks. There is also room for current narratives to fall a long way.
During a rocky fourth quarter, strength in the financials sector was a unifying theme across global markets.
In our view, active investors face opportunities to outperform created by looming policy changes and the macro landscape.