Treasury yields have been falling for weeks. Yet inflation expectations remain high and recent growth data have been fairly strong—not a traditional backdrop for declining yields. What's happening?
Though the new US policy focus is on oil and gas, wider opportunities still beckon.
One of the most referenced valuation measures is Dr. Robert Shiller’s Cyclically Adjusted Price-Earnings Ratio, known as CAPE.
As daily headlines drive volatility, the market has avoided overreacting thus far.
High fiscal deficits from tax cuts and tariffs raised concerns about inflation. However, markets have since shifted their focus.
We view quarterly earnings season as a critical checkup on how markets are handling current challenges.
The notion of a US recession seemed remote just a few months ago, a mere blip on the radar of economic possibilities. More recently, however, that picture has started to change.
US stocks have been on a wild ride this week, and options traders expect more of that to come as traders assess the latest tariff developments and brace for Friday’s monthly jobs report.
Hiring at US companies slowed in February to the lowest pace since July, led by job cuts in the service sector and in regions of the US that were hit by severe weather.
Unlike most of the rest of the world, I will attempt to minimize all there is to say about the beginning of the next 4 years, as the persistent yack and what to make of it reverberates in all corners of the financial globe.
A holistic approach may help insurance investors navigate an expansive opportunity set.
In this primer we define small cap growth funds, provide practical suggestions on how to invest in them, and explain why we believe they are a strategically important asset class.
While investors were fixated on inflation data Friday, the most significant surprise came from the advanced trade balance, which posted an unprecedented $37 billion deterioration
February’s market turbulence saw investors pivot toward defensive strategies as policy uncertainty intensified, driving a broad market rotation from mega-cap tech stocks to bonds, gold, and international equities.
We detail some key factors driving the recent market volatility and provide our perspective on how we believe these events may unfold and impact the economy and financial markets.
Traders added to bets on interest-rate cuts from the Federal Reserve amid concern about the impact of US trade tariffs on global economic growth.
Alternative investments including hedge funds and real estate will disappear from the portfolios of pension funds and endowments over the next 10 to 20 years, well-known institutional investment consultant Richard Ennis concludes in a recent report.
We wrote in last month's letter that the U.S. stock market had to meet lofty earnings expectations to maintain its strong performance relative to global benchmarks, while the latter had a lower bar because of considerably cheaper valuation multiples and higher dividend yields.
Russ Koesterich discusses the risk of higher interest rates and the potential impact (both positive and negative) such a move could have on markets.
It’s not U.S. tariffs we need to be fixated on to gauge China’s economic growth trajectory but the ability of its leadership to rebuild confidence among entrepreneurs and consumers.
Eggs add to perceptions of high inflation.
Just recently, S&P Global released its 2026 earnings estimates, which, for lack of a better word, have gone parabolic. Such should not be surprising given the ongoing exuberance on Wall Street. Unsurprisingly, rationalizations justify illogic when too much money is chasing too few assets.
We understand that in the business world the word ‘monetization’ of a service a company provides has become one of the most important words as, if successful, this monetization increases the valuation of that company’s stock price.
The future is impossible to predict, but looking at the patterns around price/earnings ratios can provide some insight about what one might expect.
There’s an old Wall Street saying that “the stock market is not the economy.” That’s usually true. But, in this economic cycle, stock market gains have become an increasingly important driver of consumer spending, helping to fuel growth as other areas of the economy cool.
Today we are going to revisit that matrix updated through 2024. We will see what we got right and wrong, what further inferences we can now make and why I think it confirms my general shift in market strategy over the past few years.
President Xi Jinping heads into China’s biggest political huddle of the year with his economy finally getting back some swagger. Donald Trump’s rising tariffs will test Beijing’s ability to sustain that momentum.
For more than half a century, Warren Buffett has penned annual letters that chronicled economic and market shifts while underscoring Berkshire Hathaway's steady philosophy yet ever-evolving outlooks. With Buffett's 2024 letter freshly published, we take this opportunity to contrast his latest views with the remarkable continuity of his investment philosophy.
For some time now, there have been plenty of reasons to worry about Big Tech stocks. Stretched valuations after a big run up, heavy spending on artificial intelligence and lofty expectations for future growth. For months, though, none of it seemed to matter.
Despite GDP figures indicating continued expansion, weakening consumer confidence and persistent inflation concerns speak to uncertainty.
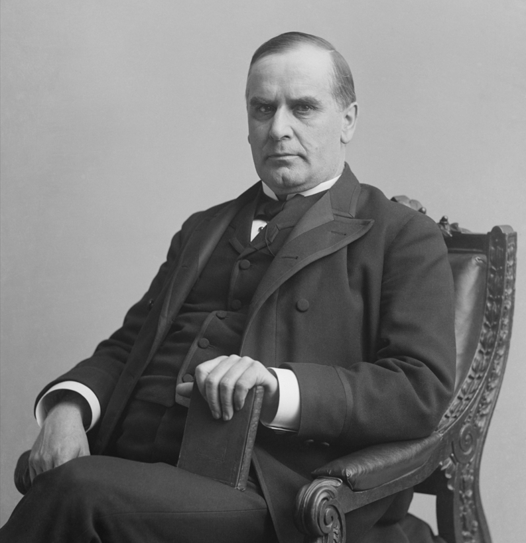
More than a century ago, then-Representative William McKinley pursued an aggressive tariff strategy that sought to protect American industry and reduce reliance on foreign imports. The McKinley Tariff Act of 1890 raised import duties to an average of 50%, one of the highest levels in U.S. history.
With major US policy change unfolding, flexibility across and within asset classes will be critical.
Portfolio Manager Andrew Mattock, CFA, explains the importance of assessing U.S. tariffs as a component among external variables that can influence, rather than drive, investment returns.
Looming U.S. and global policy shifts may potentially rattle markets, but a tactical and flexible approach could help investors navigate risks and opportunities regardless of how events play out.
Trade war fears and disappointing data have sparked a flood of defensive buying activity in consumer staples, utilities, and healthcare stocks.
We delve into the unprecedented level of equity risk investors are taking, the record-high uncertainty measures facing further impacts from deglobalization, and the benefits of maintaining a diversified portfolio through it all.
Investors in US government bonds are wrapping up their biggest monthly gain since July as the Federal Reserve’s preferred gauge of underlying inflation rose at a tepid pace in January.
President Donald Trump may have found a way to force the Federal Reserve to lower interest rates after all.
An aggressive U.S. tariff regime will come down hard on major economies.
The fourth quarter 2024 earnings season more-or-less wraps up this week with the final trickle of retailers coming in, as well as the highly anticipated report from Nvidia which was out yesterday afternoon.
Investor sentiment around small-cap companies is worse than it’s been in months. As it turns out, the mood isn’t much better inside their corporate boardrooms.
Investors hoping that Nvidia Corp.’s earnings would rejuvenate the artificial intelligence trade didn’t exactly get the report they wanted.
In the report, John Kerschner, Head of US Securitized Products & Portfolio Manager, and John Lloyd, Lead for the Multi-Sector Credit Strategies & Portfolio Manager, review the best-performing U.S. fixed income sectors of 2024 – what worked, what didn’t, and what it means for investors going forward.
If Trump tariffs Chinese, European, or Canadian products, those countries tend to enact counter-balancing tariffs on U.S. products. Such slows demand for goods and services between all parties, again a deflationary process.
The economy can grow through policy changes.
Senator Cynthia Lummis (R-WY) takes a pivotal role in shaping how America approaches cryptocurrency and blockchain technology.
A healthy jobs report should keep real estate traders appeased, but cautious optimism is warranted moving forward.
For the last five years, BP Plc has squandered its shareholders’ money. That’s why, forced by poor returns and the arrival of an activist investor, it finally “reset” its strategy on Wednesday.
The U.S. economy remains structurally productive. American Economic Exceptionalism is powered by innovation and labor flexibility.
Healthcare stocks were hurt by volatility from factors that include policy-related uncertainty, which hasn’t faded since the US election.