The 2026 U.S. midterms are rapidly approaching, with major implications. Muni bonds, in particular, may be impacted.
Investors should continue to treat bonds with caution even as the selloff bolsters the case for holding them in multi-asset portfolios, according to strategists at Goldman Sachs Group Inc.
What does Tina Turner have in common with a US Treasury bond? They both show that the meaning of safety is not always straightforward.
Advancements in technology, combined with significant stock market gains in recent years, have created a new set of opportunities—and challenges—for investors. For example, investors holding a concentrated position in a highly appreciated stock may face a difficult trade-off between the risk of a market downturn and the potentially significant tax cost of diversifying the position.
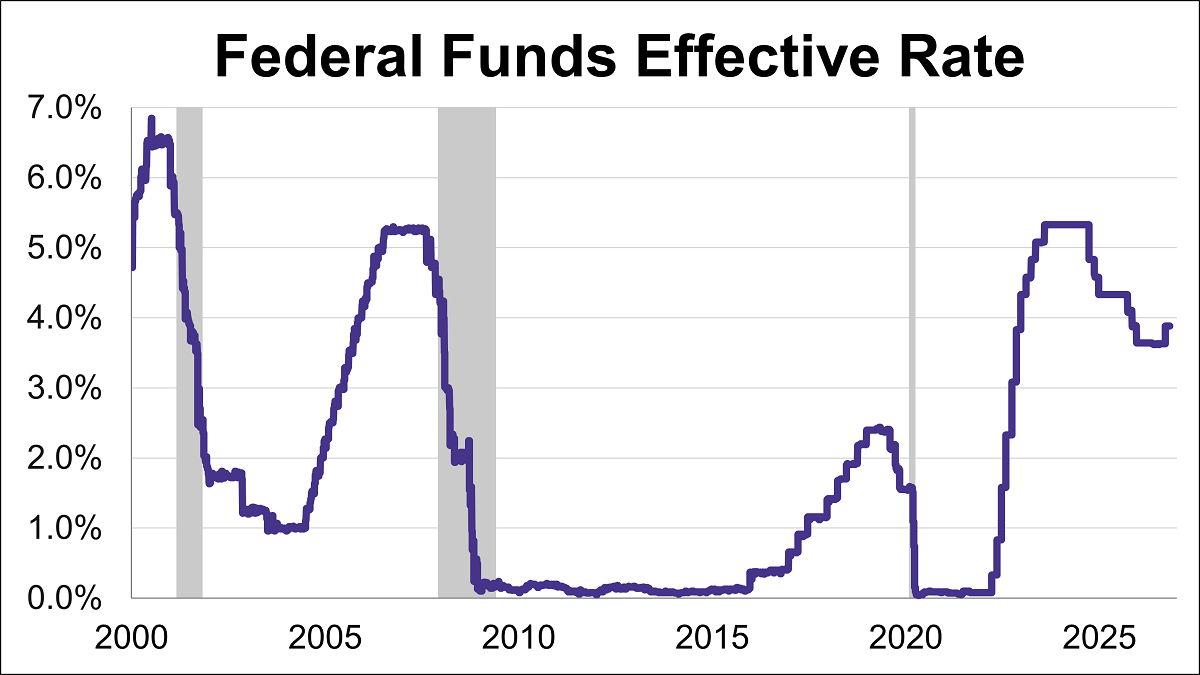
The Federal Reserve today unanimously decided to raise its short-term interest rate target by a quarter percentage point to a range of 3.75 – 4.00%, the first hike since mid-2023. The Fed made two key changes to the statement announcing its decision, declaring that “domestic spending has been resilient” and the rate hike “will support a timelier return” to the Fed’s 2% inflation target.
Fed policymakers unanimously voted to raise rates 25 basis points, the first hike since 2023, and vowed to fight inflation. Another hike is seen this year, but 2027 is in question.
The Federal Open Market Committee (FOMC) decided to raise rates by a quarter-point, bringing the new fed funds trading range to 3.75%–4.00%. The money and bond markets had been pricing in a potential rate hike at this gathering, and Warsh & Co. ultimately determined that such a move was warranted. That said, the ‘rate hike’ story does not end here.
The Federal Reserve concluded its sixth meeting of the year by raising the federal funds rate (FFR) by 25 basis points to a target range of 3.75%-4%.
Join Fidelity for an educational webcast exploring derivative income in today’s market environment.
Every single sector in the S&P 500 is expected to deliver earnings growth for the third quarter, the first time since 2021, when corporate America emerged from the pandemic slump, Bloomberg Intelligence data shows.
Last December we published Riding the Wave: The Anatomy of Booms & Bubbles. In it, we argued that the AI spending boom would continue through 2026 without tipping into ‘bubble’ mania, and that the right posture was to stay overweight stocks while favoring US assets. Nine months on, we think that call has aged well.
Single-stock leveraged ETFs were unusual when they first arrived in the U.S. market just four years ago. Today, it might be hard to find a stock without one. Issuers are aggressively pushing beyond megacap tech into niche equities, pre-IPO registrations, and even experimenting with leverage levels and frequency.
With so much attention focused on what the Fed might do at its policy meeting this week, it’s a good time to look back at history to get a sense of how stocks might respond should policymakers hike rates as the market now expects. LPL Research had been characterizing the rate decision as a coin flip until Fed Chair Kevin Warsh’s hawkish comments at the Jackson Hole meeting and the strong August jobs report.
From the 2020 pandemic to today’s oil shocks, we’re often reminded in recent years that inflation can flare up unexpectedly. We’ve also likely entered an era in which higher inflation may linger for some time. As a result, bond-heavy and income-oriented investors may need to shore up their inflation defense, which we think should combine strategic positioning with tactical maneuvering.
The Consumer Price Index (CPI) data for August was generally in line with expectations. However, a slightly hotter-than-expected core CPI reading buoyed expectations of a rate hike at the Federal Reserve meeting in September.
The August employment report was much stronger than expected and reinforces my view that the U.S. economy remains remarkably resilient. Payrolls increased by 162,000, above every estimate, while revisions added another 55,000 jobs to the previous two months.
A rate hike on Wednesday is now very likely but would also be unusual, and perhaps dangerous, at least as far as the past generation of monetary policy goes.
AI-driven healthcare innovation is creating strong investment opportunities by improving efficiency, expanding access, and delivering better patient outcomes.
A week of rising oil prices and higher interest rates sent stocks lower across the board as investors increasingly priced in the likelihood that the Federal Reserve (Fed) will begin a rate-hiking cycle at its September 16 meeting. Following the August Consumer Price Index (CPI) report, futures markets implied an 88 percent probability that the Fed will, or at least should, raise rates at next week's meeting.
Bond prices and interest rates generally move in opposite directions. When interest rates rise, the market prices of existing bonds typically fall. When interest rates fall, existing bond prices typically rise.
Join the experts at Sterling Capital for an educational webcast covering a unique corner of the fixed income market.
Discover how autocallables provide steady income and downside risk protection in volatile markets, and how autocallable ETFs can help.
I’ve written before about why the federal debt may be less dire than the headlines suggest, and I still think much of that argument holds. You cannot know whether a national crisis is coming. You can, however, assess the risk of a crisis for your own budget and take action to reduce that risk.
Anthropic PBC is pitching financial advisers on a version of Claude that blends the chatbot with financial analytics and risk management technology run by BlackRock Inc., Vanguard Group Inc. and other firms.
An essay from Anthropic PBC’s Dario Amodei saying artificial intelligence companies must “pace the frontier” has got the world talking about a slowdown in their most cutting-edge research. OpenAI’s Sam Altman and SpaceX’s Elon Musk publicly agreed with the post.
Treasury yields are closing in on an inflection point where, historically, stocks and bonds have reinforced losses in one another. That points to a regime shift of higher bond and stock volatility and wider credit spreads.
The future of retirement planning is not a new model replacing an old one, but a more holistic approach that blends rigorous analytics with important client input. Advisors who adopt this integrated model will find that it deepens client conversations, clarifies tradeoffs, improves long-term decision-making.
The latest inflation report points to a hard truth: The US is not going back to a 2% inflation rate anytime soon. At least not easily.
Periods like this can feel especially tense, with higher stakes and more urgent headlines. Yet over time, markets have shown they are forward-looking and resilient, absorbing uncertainty rather than freezing in it. While today’s geopolitical backdrop may feel unsettling, it fits a long history of disruptions that markets have ultimately navigated.
On September 2, TMX VettaFi Head of Research Todd Rosenbluth appeared on the Schwab Network to discuss ETF inflows nearing record highs in 2026 and the 50th anniversary of the first-ever index fund, the Vanguard 500 Index Fund. The fund’s ETF share class, which trades under the ticker VOO, is a bit newer, having launched in 2010.
Chris Galipeau discusses high-conviction insights that go beyond media headlines.
Most coverage of Trump Accounts treats them as a parenting question, or a discussion comparing them to 529s. For founders and business owners the analysis of them is slightly more nuanced.
Demand for fixed income ETFs hit a historic high-water mark in September. Investors and advisors turned to fixed income ETFs at a record-breaking pace, driving 2026 net inflows of $446 billion past all-time levels with months to spare. The massive tide of capital arrives at a critical juncture.
In our final chapter for this series, we will dig into that exact question. Unfortunately, there is good and bad news, and it can be summed up in a single sentence.
Last week, the refining margin on European gasoil, the benchmark that sets the price of diesel and heating oil across much of the world, closed at roughly $94 a barrel over Brent crude, according to Bloomberg data. That figure is normally somewhere between $12 and $18.
As policymakers adapt to new leadership, navigate a challenging geopolitical backdrop and contend with meaningful internal debate over the path of interest rates, the stakes remain high. Below, we discuss what to expect from next week’s Federal Reserve (Fed) meeting and provide perspective on the recent rise of Treasury yields to multi-year highs.
Attractive yields and resilient credit conditions are creating opportunities across fixed income, but uncertainty around inflation and interest rates makes flexibility, selectivity and disciplined risk management especially important.
According to new data from J.P. Morgan Asset Management’s 2026 Defined Contribution Plan Participant Survey, 73% of savers said they wish they could hit an “easy button” and fully delegate their wealth management.
As I go through the strengths and weaknesses of each model, my goals are to point out where the models are strong and to point out potential weaknesses such as conflicts of interest, which are important to be aware of in working with clients. Although we are all fiduciaries, financial incentives matter because we are all human. I know great advisors across all fee models.
Heading into the September 16 FOMC meeting, the debate over whether the Fed should raise rates or hold is heated. To help you appreciate the range of views, I present this article as a courtroom exercise. I will let the prosecution make its case for a rate hike, and the defense for a hold.
ETF share classes represent a structural innovation that combines the benefits of mutual funds and exchange-traded funds (ETFs) within a single pooled portfolio. This evolution expands investor choice, offering both ETF and mutual fund shares under a unified investment strategy.
Many market participants have highlighted how value investing is back as the equity market rally broadened out beyond high-flying growth names. However, taking an index-based approach to the value style requires looking under the hood. Not all value ETFs are created equally.
Market madness has never been hard to diagnose. It’s almost two centuries since Charles Mackay published Extraordinary Popular Delusions and the Madness of Crowds. Benjamin Graham pioneered value investing in the 1930s by inviting everyone to think of “Mr. Market” as a manic-depressive who makes mistakes that can be exploited.
America’s data center boom will need $110 billion to build 45 gigawatts of new power generation through 2030, according to an analysis by Moody’s Ratings.
The list of challenges confronting Wall Street piled up this week. Oil firmly above $100. Inflation refusing to disappear. A defiant bond market that all but dared Scott Bessent to bring more policy firepower.
China criticized warnings from leading US technology executives to put the brakes on artificial intelligence development and claims that Chinese progress posed a dire security threat to the world.
The bond selloff has driven a key Treasury yield to the verge of 5%, worsening angst from Wall Street to Washington about higher borrowing costs hitting the US economy.
For many investors, a 401(k) is simply a retirement savings account. For high-net-worth families, however, it can become a sophisticated planning tool that supports tax efficiency, wealth accumulation, and long-term legacy objectives.
Every few months, a new essay declares that the US debt trap has finally sprung. The latest one making the rounds from The Economist is well written and genuinely unsettling. It argues that Washington has borrowed so recklessly that the Federal Reserve no longer dares to raise interest rates. Doing so, the piece warns, would detonate the whole structure and send financing costs spiraling out of control.
Equity markets generally moved lower as rising yields and energy prices created a more challenging backdrop. Higher yields can be particularly difficult for long-duration equities, where a greater share of expected cash flows sits further into the future.