Treasury yields are closing in on an inflection point where, historically, stocks and bonds have reinforced losses in one another. That points to a regime shift of higher bond and stock volatility and wider credit spreads.
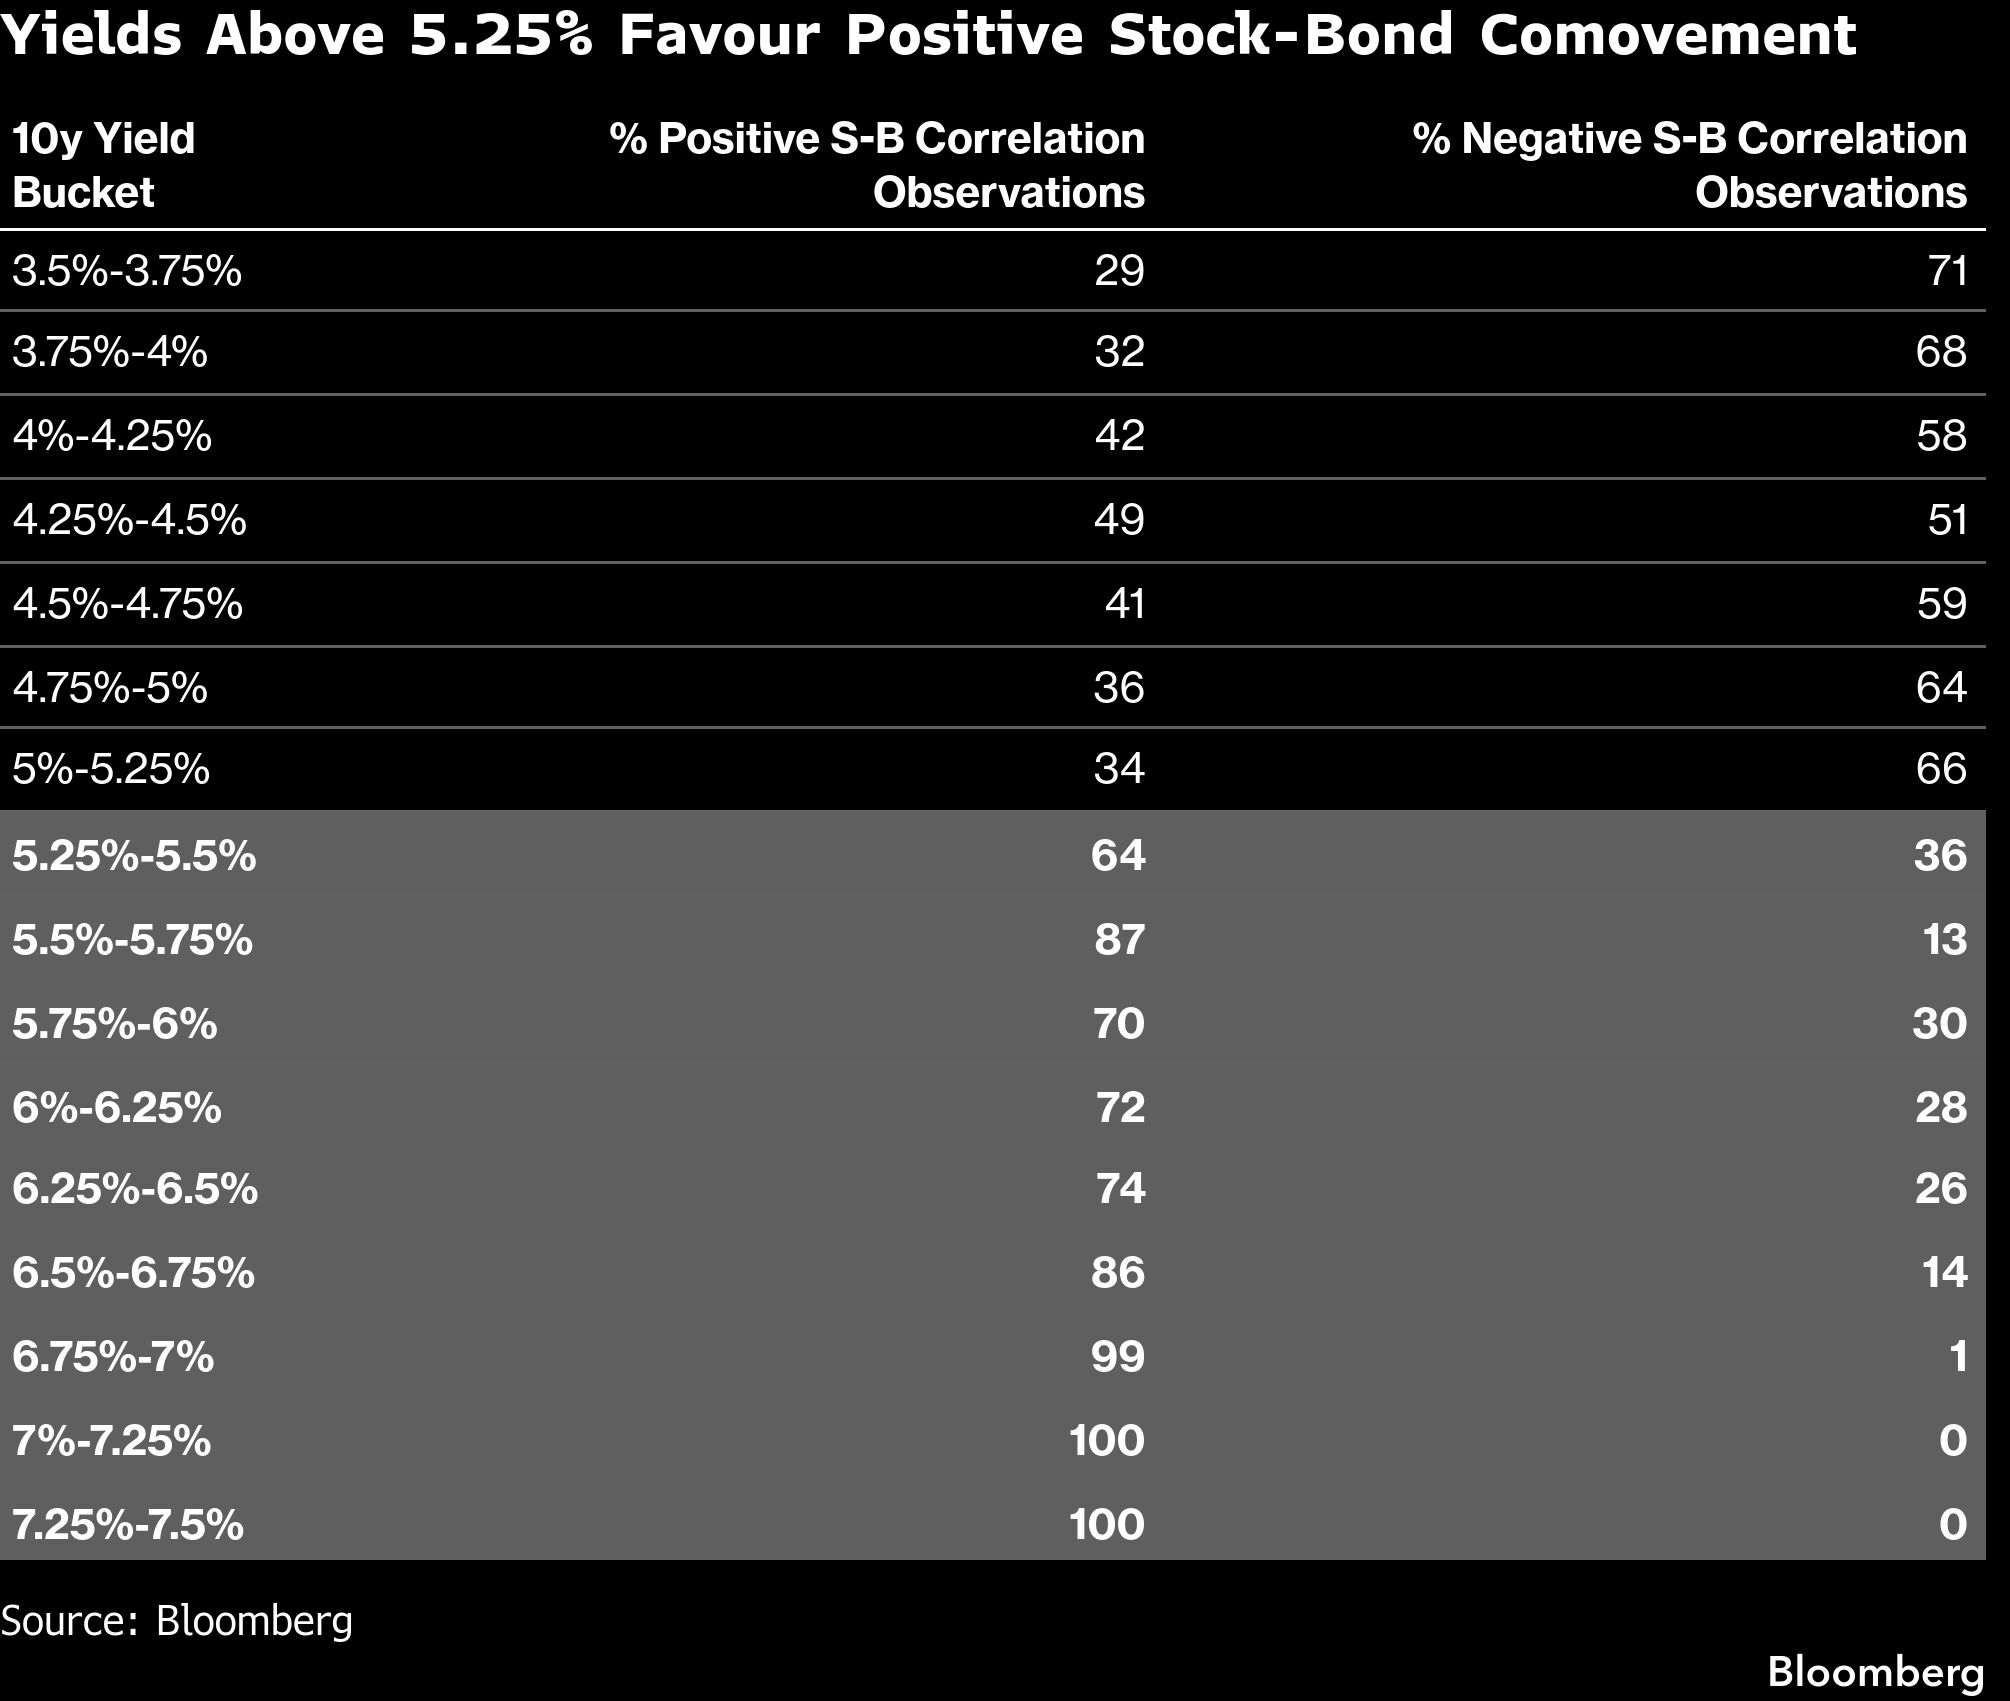
Lines in the sand are often a little too neat for reality, but when it comes to Treasuries there has been a stark change in regime when 10-year yields go much above 5.25%. After that point, the risks to bond volatility and hence stock vol and credit spreads markedly increase.
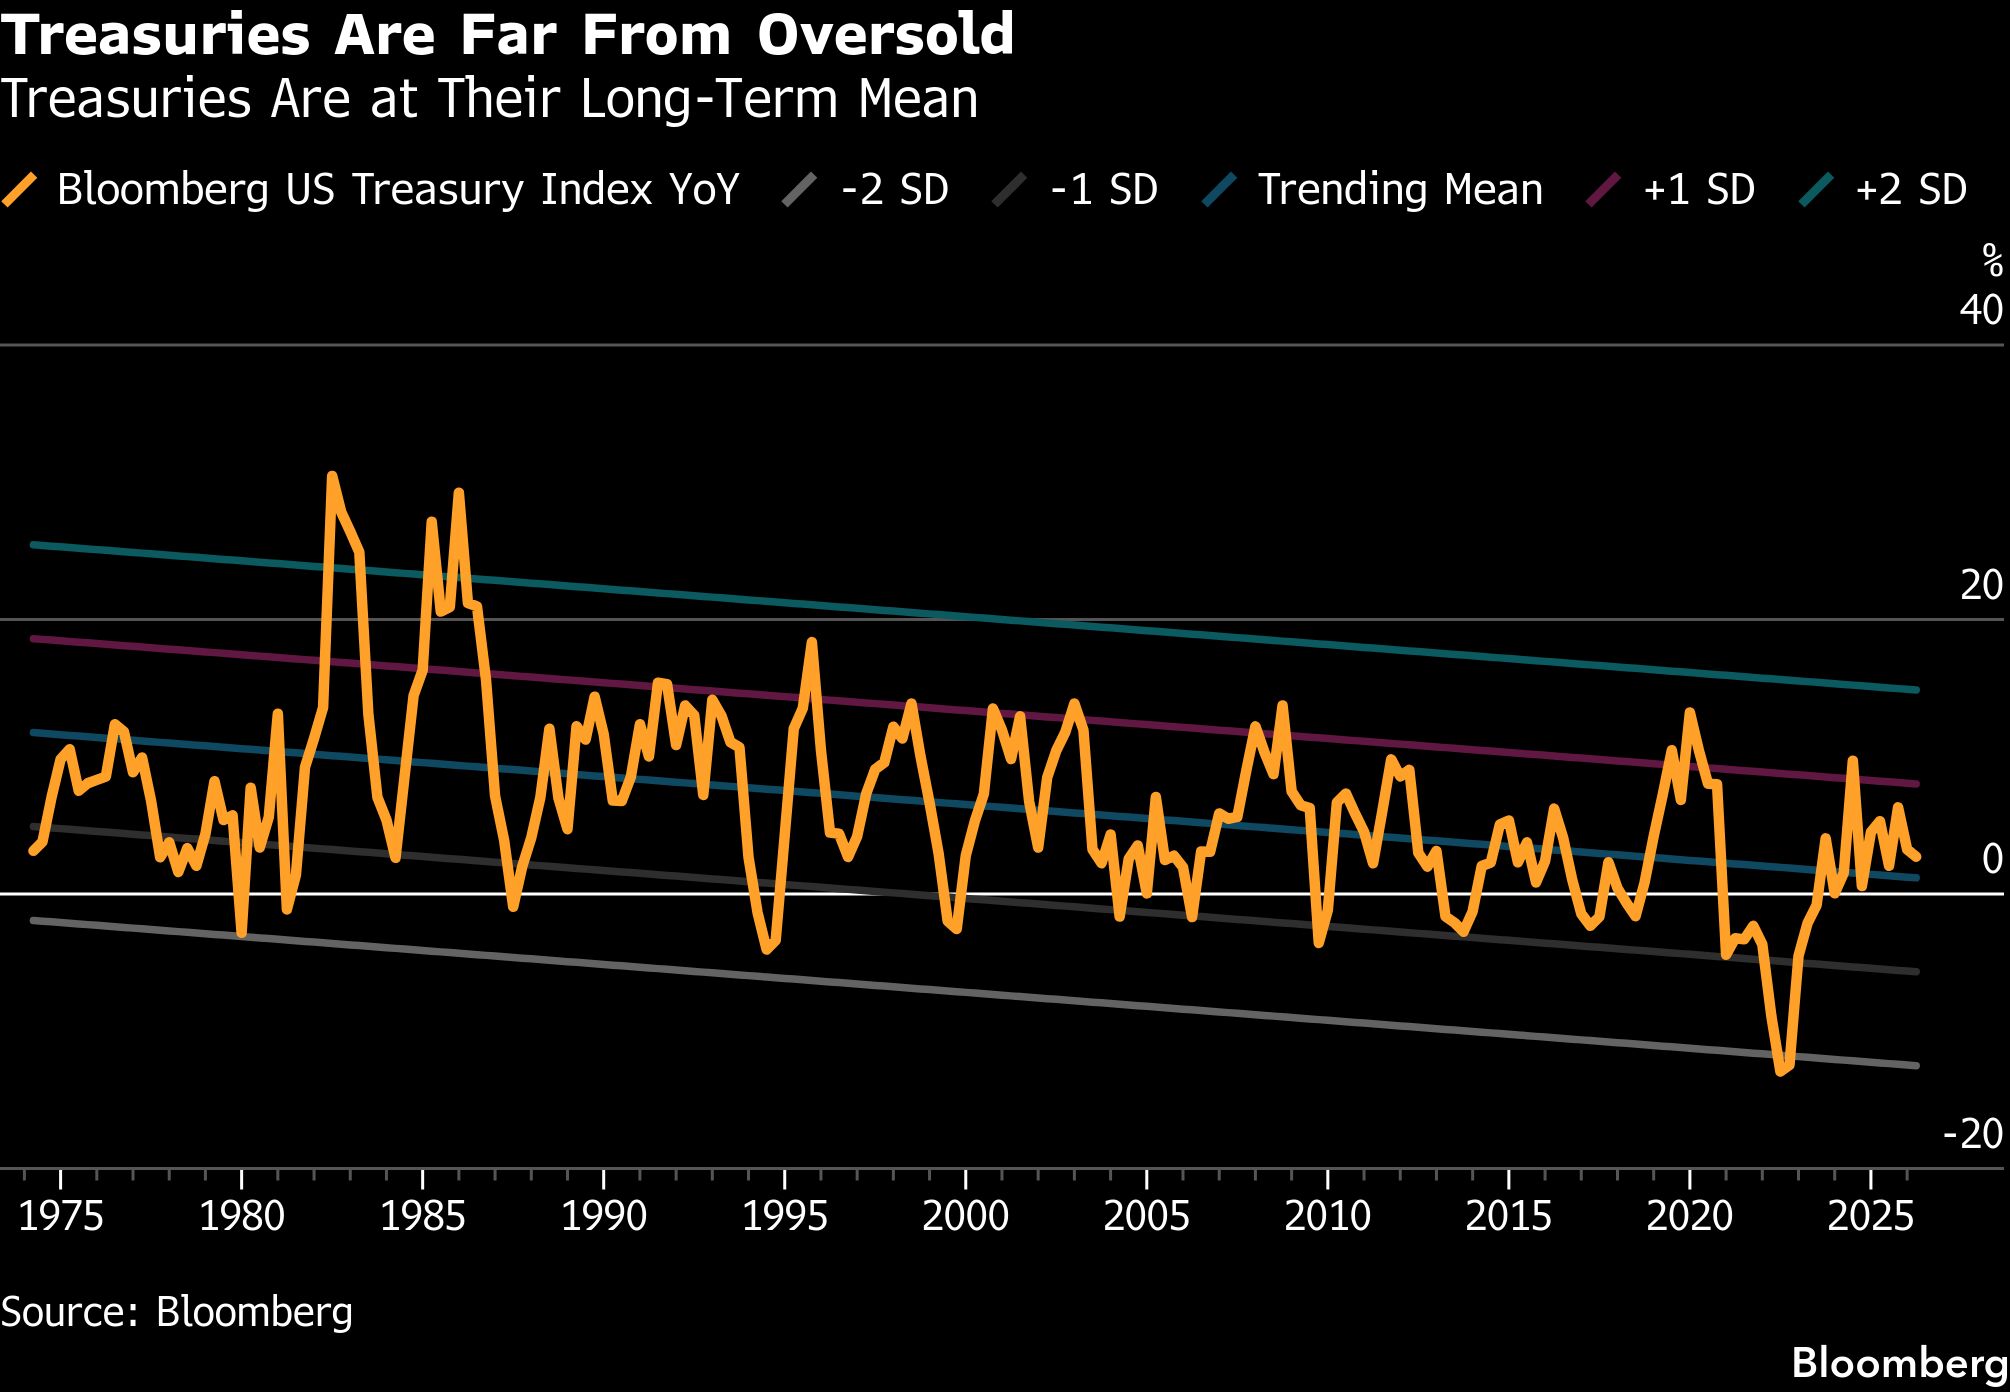
With 10-year yields rising above 5% this week the first question is: will they keep going? Yields may look stretched, rising to levels not seen since 2007 just today, but Treasuries are not yet oversold. Incorporating returns on capital and looking at prices, they are only back to their long-term mean on an annual growth basis.

Treasuries mean-revert, which means they oscillate around their long-term average (see chart above). They are back to that average, but they typically then overshoot. Treasuries could thus sell off more before they became materially oversold.
We’ll look at what’s driving yields in a second, but first let’s get to the crunch of this column: yields are closing in on a level where the stock-bond correlation has in the past almost exclusively been positive, ie both assets move in the same direction on average.
See more: Hike or Hold? Debating the Coming Fed Decision
There have been almost no instances when the correlation between the S&P and Treasuries is negative and yields have been over 5.25%. It’s rare you see a relationship so starkly outlined. (I use a longer-term correlation, two years of one-week changes, as this is more relevant to asset allocation.)
The stock-bond correlation was positive from 2022 until the end of last year while yields were below 5.25%, but it has been flat all of this year. It’s likely to go firmly back into the positive zone if yields keep rising.
That’s when bonds stop being a hedge for stocks, and Treasuries can worsen losses in equities.
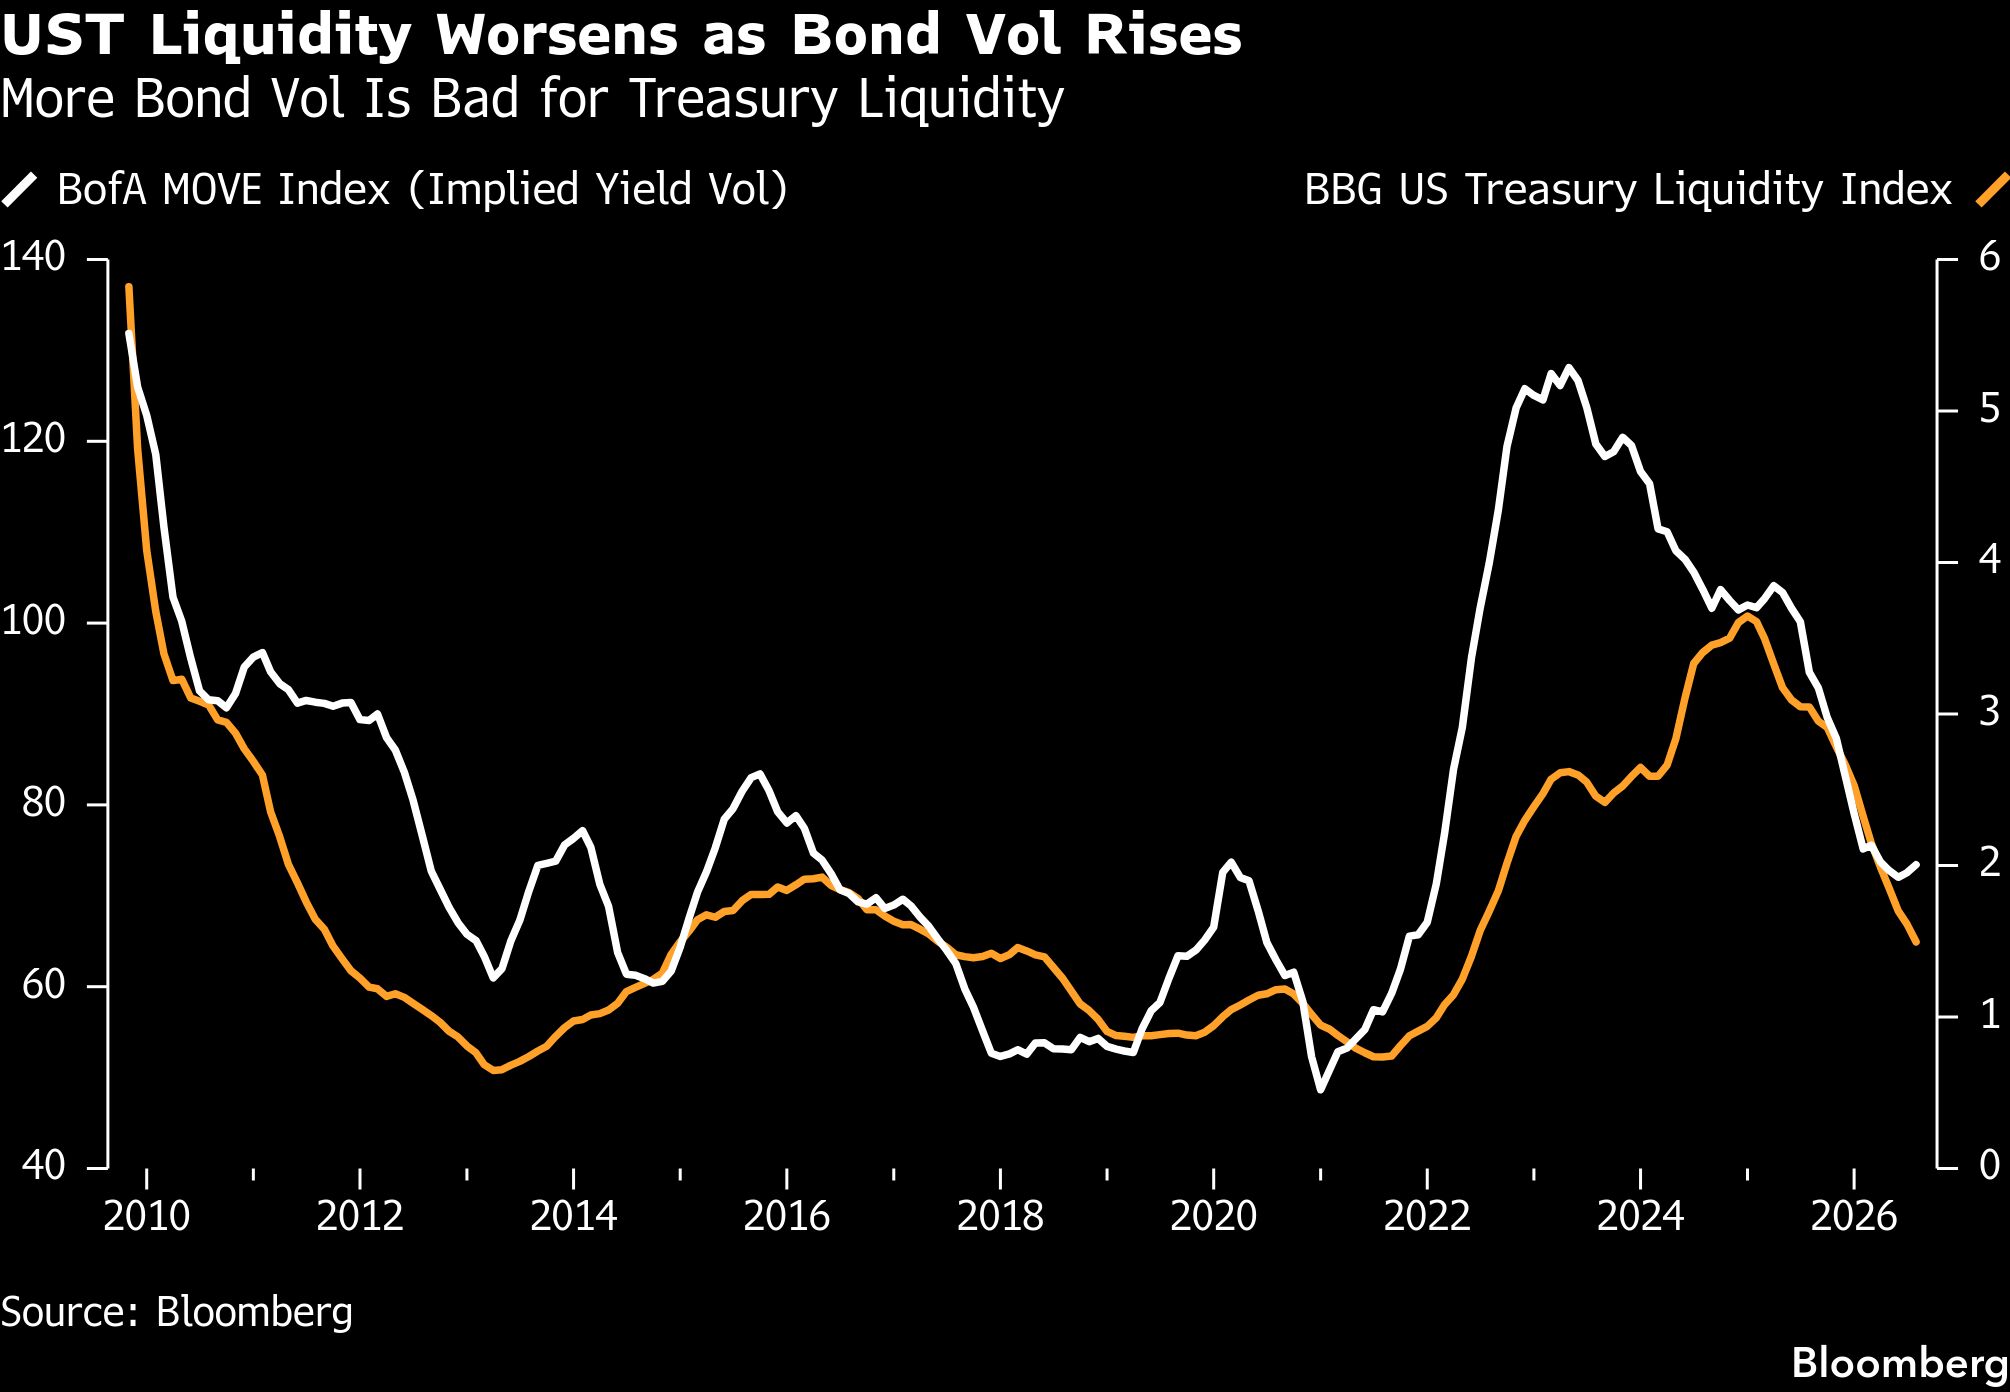
The first casualty is bond volatility. With Treasuries less desirable as a portfolio hedge, the marginal buyer becomes more price sensitive, leaving the market more sensitive to flow. Further, investors are more likely to seek option-based hedges for Treasuries, pushing up implied volatility.
The volatility of yields and the stock-bond correlation were inversely related during the NICE (non-inflationary, continuous expansion) decades of the 2000s and 2010s. That was when the stock-bond correlation was persistently negative and bonds were a reliable stock hedge.
But the norm over the greater sweep of history is for stocks to co-move positively with bonds. That’s because most of the time - and is the case today - a growth shock has been more likely to happen with an inflation shock, causing both stocks and bonds to sell off together. Bonds become a hedge of the decidedly counter-productive Texas variety.
A correlation of more than zero was largely the case in the 1990s and has largely been the case in this decade. In these periods, yield vol is positively related to the stock-bond correlation.
So we should expect bond vol to rise. That’s problematic for Treasury liquidity, the stated reason for the enhanced buybacks announced by the Treasury last month.
There will be other casualties as well. Equity-index volatility is unlikely to remain subdued if bond vol rises. Firstly, with stocks and bonds reinforcing losses (and gains), asset rebalancing flows will become more variable, boosting the VIX. Secondly, with bonds a less reliable hedge, hedging via equity-based options will rise, also supporting implied vol.
And a third channel is especially pertinent today: higher bond vol creates greater uncertainty on the discount rate used to value cash flows. One glance at record low stock-to-stock correlation highlights the negligible possibility that the market is pricing in single-factor risk, the most dominant of which for stocks is longer-term rates.
Ultra-low stock correlation has been dampening the pass-through to index volatility (ie the VIX) from single-stock volatility. The latter has eased back from the heights of the memory mania, but it would still give the VIX a healthy jolt if correlation rose.
Credit spreads won’t remain unscathed either. Low index volatility is one of the key factors holding them down. High-yield spreads and the VIX tend to move in lockstep as the latter is often an input to credit pricing models via the Merton framework.
A lot is therefore riding on the Treasury selloff being in its dying days. What would say otherwise though?
The news over the weekend that the AI labs want to pace model development is perhaps a convenient cover for pulling back on capex, which would be a kick in the shin for growth. But given the profusion of take-or-pay contracts for compute extending into next year and later, that might not be enough to trigger a rally in the nearer future.
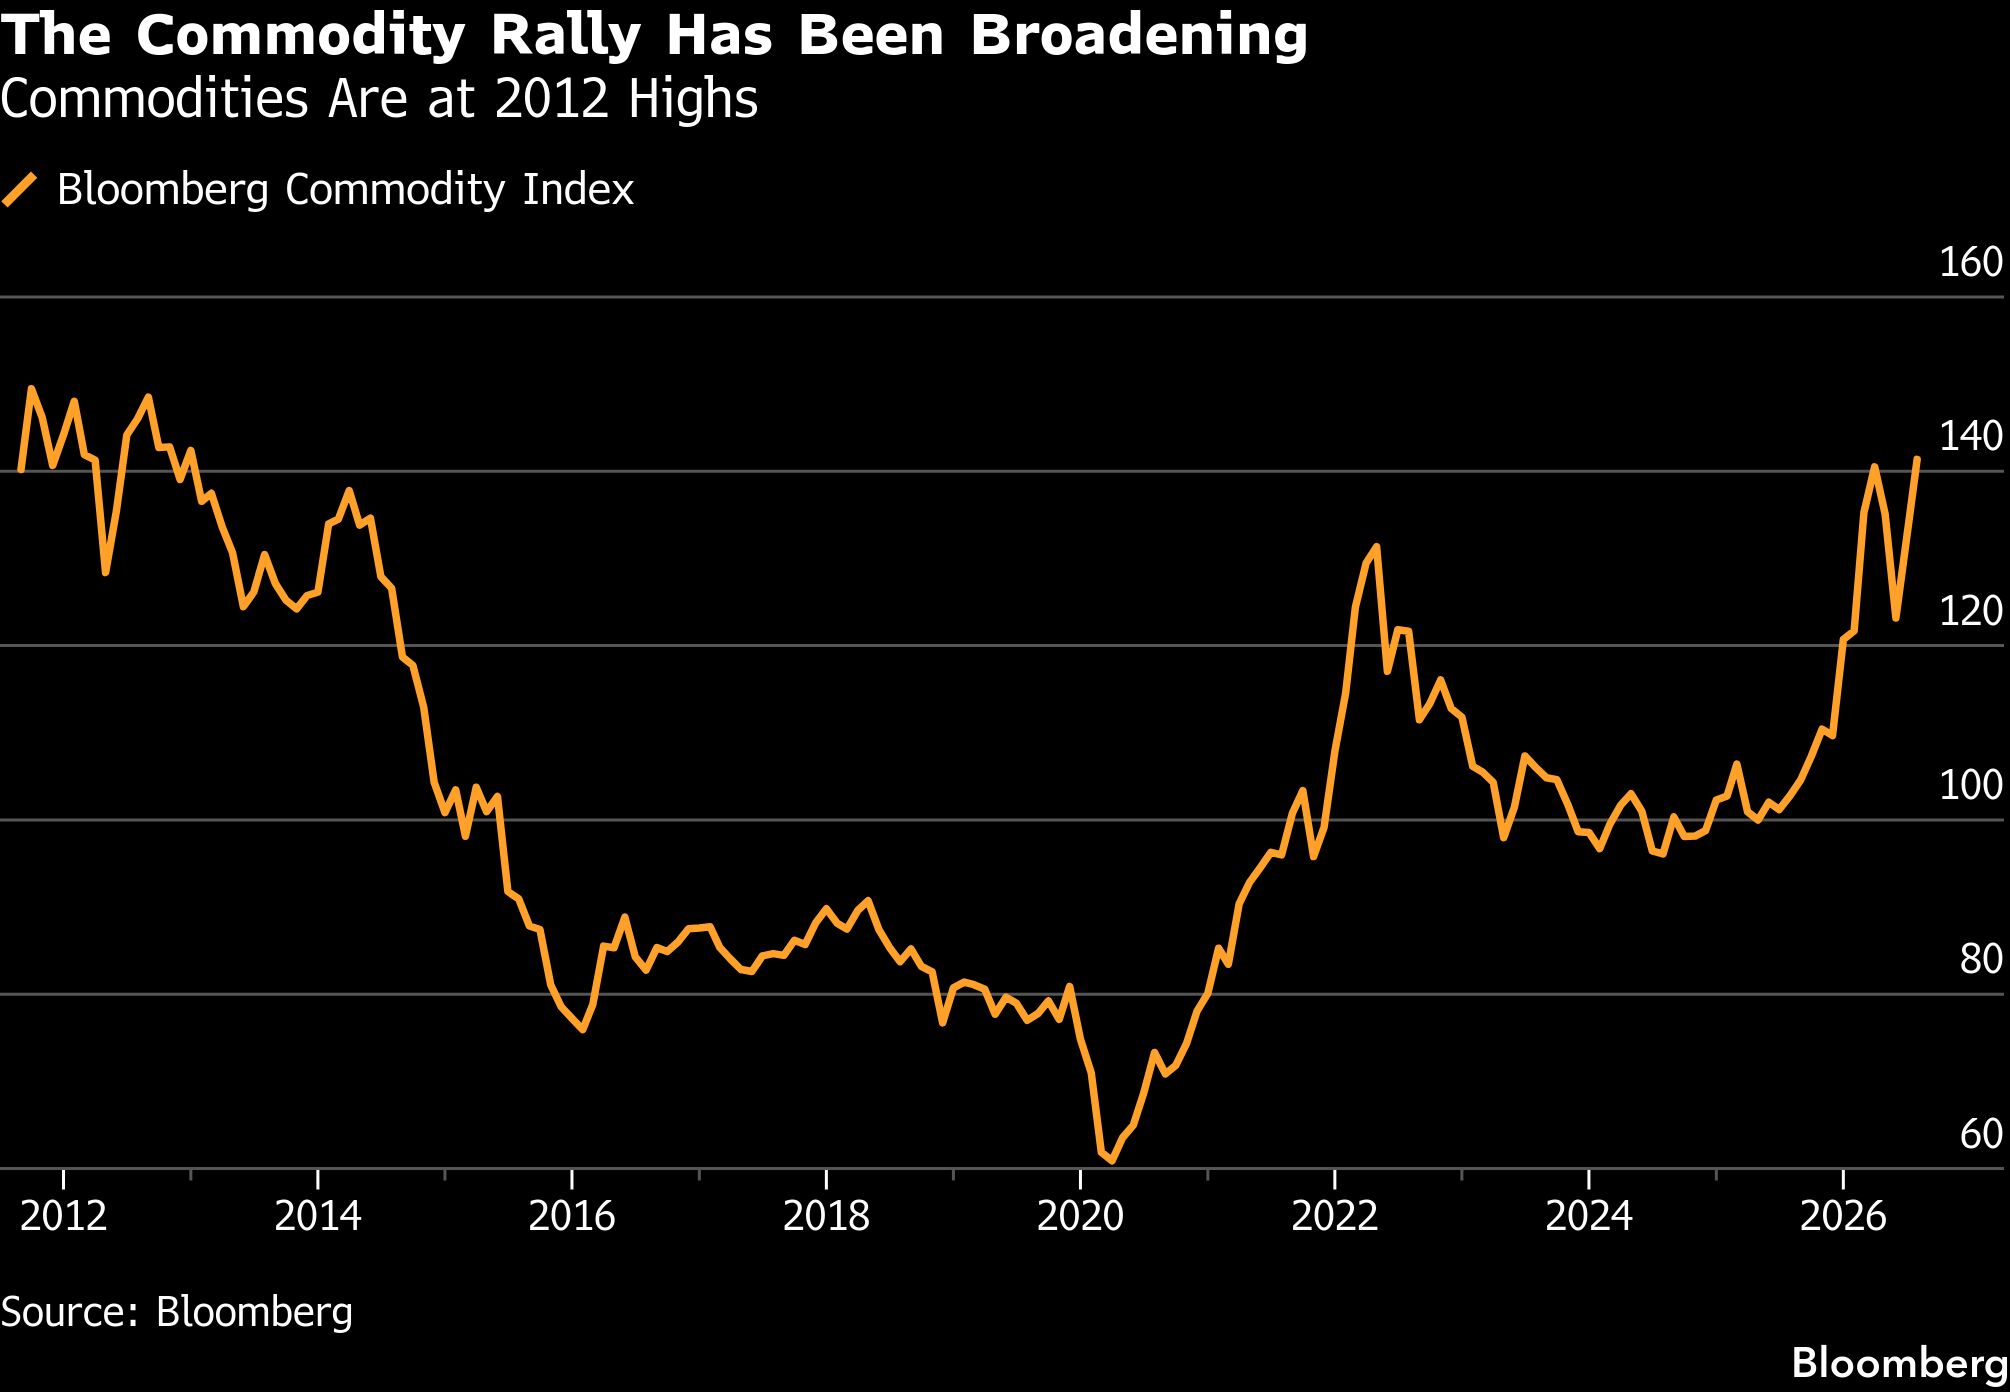
Real-money buyers or those hedging mortgage securities might come in if yields extend persistently above 5%. They have not so far, and anyway their impact may only be temporary. The commodity rally continues to gather pace, and energy and food supply disruptions in the Middle East and Russia aren’t getting any better. Inflation looks set to see a lull in the coming months, but structural price pressures are here to stay – a formidable tailwind for yields.
Nevertheless, it’s less likely anyone will want to step in in size ahead of Wednesday’s FOMC. Paradoxically, a rate hike could encourage Treasury buyers if it’s seen that the Federal Reserve is serious about vanquishing price pressures, although whether one hike is enough to to snuff out inflation is another matter. On the flip side, a rate hold could push yields higher.
Either way, Treasuries are near an inflection point. If 10-year yields go much above 5.25% for a reasonable length of time, trading conditions and asset prices will soon become very different.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Bloomberg News provided this article. For more articles like this please visit
bloomberg.com.
Read more articles by Simon White