While oil prices are likely to remain elevated in the near term, we do not view the current disruption as a lasting supply shock. A diplomatic resolution, or even progress toward one, should help bring prices lower by year-end. Although higher oil prices are a headwind, we believe both the economy and equity markets can absorb the impact with limited damage, as underlying fundamentals remain strong.
It’s no secret that college is expensive. And alongside mounting costs come almost as many strategies for mitigating them. When you need money to pay for college expenses, tapping your Roth IRA is one option you might consider.
Get ready each week with high-conviction insights that go beyond media headlines.
April showers came in the form of more inflows raining down on the exchange-traded fund (ETF) market last month. Assets under management (AUM) have now grown to a staggering $14.7 trillion for the year. That’s punctuated by year-to-date (YTD) net inflows of over $636 billion.
What a week this was! On Tuesday, I participated on a panel at the Bitcoin Conference in Las Vegas, where I discussed why Bitcoin miners have a head start in the race for AI compute.
When it comes to investing, it’s the Wild West out there. Our clients are hearing things from less scrupulous members of the financial services industry that appear true on the surface but are really aimed at separating people from their money.
The same forces that are straining the political marriage across the Atlantic are also creating a long‑term opportunity set in Europe. Advisors should position clients’ capital so that it benefits from that structural shift, while staying disciplined about quality, valuation, and risk.
The poor sentiment toward private credit funds has dragged down many high-quality BDCs, as well as weaker ones. The chaos and bad press surrounding private credit funds are not reasons to avoid BDCs. In fact, we think it’s a reason to consider them.
Robots are coming to the economy. It is inevitable, really, and there is nothing that will stop it. At some point in the not-so-distant future, robots will infiltrate every aspect of our lives, from office work and manufacturing to service work and trade skills, and even your home. Here are some numbers for you.
While the ETF leaderboard continues to be dominated by S&P 500 index-based products, there are many other success stories that are likely being missed. There are now more than 5,100 products for advisors, investors, and even analysts to keep up with. Let’s take a look at some funds that have sprouted in just the last few months.
The part of the bond ETF complex that’s growing fastest isn’t that part. It’s the active and outcome-oriented funds — multisector strategies, flexible income vehicles, securitized credit funds, options-overlay products — that charge 0.30 to 1 percentage point and promise more yield, less duration, or both. And the marketing pitch behind them quietly elides something important.
Like Treasuries and Treasury Inflation-Protection Securities (TIPS), municipal bonds betrayed their normally docile reputations in March as the conflict in Iran stirred increased volatility for normally subdued corners of the bond market.
It’s happening. California looks likely to put a “one-time” tax of 5% on wealth above $1 billion on the ballot in November, and polls suggest it could pass — despite opposition from some economists (not so surprising) and Democratic politicians (more so).
Chuck emphasizes that value, not price, is the key driver of successful long-term investing. Investors should avoid trying to time the market and instead focus on buying quality businesses at sound valuations. If a stock is undervalued, it may present a buying opportunity.
April showed us just how sensitive markets can be to a small number of powerful forces: energy prices, inflation and geopolitical risk. The conflict in the Middle East dominated headlines, with a ceasefire helping to steady markets even as energy prices remained elevated.
Although sentiment remains sensitive to headlines around the Strait of Hormuz and energy markets, Franklin Templeton’s Emerging Markets Debt team sees an asset class that has shown it can absorb shocks, even as renewed geopolitical flare-ups or a broader risk-off episode could still test markets.
Artificial intelligence might be the most transformative technology ever devised. Exactly how its effects will work through the economy is impossible to say, but serious disruption of one kind or another seems likely. Millions of jobs — in the end, maybe most jobs — could radically change, and many will disappear entirely.
In today’s market, income investors remain firmly focused on one objective: yield. With traditional sources of income still under pressure, demand for high-income ETFs continues to grow — especially those capable of delivering consistent monthly payouts.
Volatility ETFs have specific purposes to fulfill for investors -- so have they done so in a very volatile year?
Core aggregate benchmarks remain the bedrock of many fixed income portfolios but advisors are increasingly looking to income alternatives.
The stock market would love to see nothing more than the labor market holding up. Time and again, we find monetary policy having a beautiful, lagged effect in the jobless claims series. We are of the view that the cumulative 175 basis points of Fed rate cuts that hit the market in 2024 and 2025 is exactly what the labor market needs in 2026-2027. We will soon find out if manufacturing employment continued to mend in April.
The sharp rebound from the March lows has pushed most major equity indexes back to record highs. This upside momentum has been fueled in part by signs of de-escalation with Iran and growing expectations that the Strait of Hormuz could reopen soon.
Where should advisors and investors be looking to find the best opportunities in fixed income? Given the current macroeconomic picture, now is certainly a good time to consider shifting one’s fixed-income portfolio.
As widely expected amid rising oil, rates will remain 3.5% to 3.75%. However, four policymakers dissented. And Fed Chair Powell will stay as governor after his chairmanship ends.
In a recent (unscientific) Franklin Templeton social media poll, we asked investors what they felt was the biggest risk to the global economy over the next 12 months. Nearly half (45%) of respondents highlighted high oil prices as their greatest fear factor.
As multi-asset income investors, we seek to help a wide range of clients meet their income needs. The benefits of an income-centric approach are especially relevant for investors as they enter retirement – and that’s especially true today. We bring that to life with two case studies.
The rapid institutionalization of the $3 trillion private credit market has left many financial advisors racing to catch up. While the asset class was once a walled garden for pension funds, the mainstreaming of private debt requires a new level of diligence and education. The shift toward transparency is finally allowing advisors to look under the hood of these complex structures.
Treasury Inflation-Protected Securities, or TIPS, can help buffer a portfolio against inflation. However, it's important to understand their unique characteristics and complex nature.
Reaching age milestones triggers critical financial and tax-planning actions. This guide explores how specific ages impact decisions regarding Medicare, Social Security, charitable giving and retirement withdrawals, helping you navigate these milestones to optimize your long-term wealth strategy.
The long-term shift from traditional pensions to defined contribution (DC) plans puts employees in charge of their retirement savings—and needing help.
Now and then, advisors need to get a sense of how Americans of all ages approach retirement planning. Back in March, Fidelity Investments released its 2026 State of Retirement Planning Study. The report took a deep dive into how different age groups of Americans are viewing retirement preparations.
For the third consecutive policy gathering, the Federal Open Market Committee (FOMC) decided to remain ‘on hold,’ keeping the fed funds trading range at 3.50%–3.75%. This result was largely expected by the markets. Unfortunately for the Fed, the policymakers are in a challenging position of juggling incoming economic and inflation data as well as the uncertainties emanating from the Middle East war.
For much of the past few years, US Treasuries have failed to serve their traditional role as a sure-fire refuge from global market meltdowns.
A quarterly report providing an in-depth analysis of the global economic landscape, key drivers and insights into fixed-income markets for investors.
Here’s where I want to start, because this is the point that almost every government debt analysis, including the article we’re responding to, completely ignores. Government debt doesn’t disappear into a void. By definition, if the Government borrows capital from someone, that capital must flow somewhere.
Sentiment toward BDCs – funds that invest in small and midsize private U.S. businesses – has improved since early March. BDC bond spreads have stabilized and outperformed the broader investment grade (IG) index, suggesting credit investors are increasingly comfortable with downside risk.
On Friday, the Department of Justice announced it was dropping its investigation of the current Federal Reserve Chair Jerome Powell. Senator Thom Tillis was effectively blocking the nomination process from moving forward while the Department of Justice investigation of Powell was ongoing.
Global Head of Securitised Products John Kerschner and Portfolio Manager Ian Bettney from Janus Henderson’s Global Securitised Team examine how CLOs and other securitised credit have weathered recent volatility, and why selectivity and active management remain central to capturing opportunities across the market.
It’s a stressful investing landscape right now and investors are feeling it. Volatility, driven by a chaotic geopolitical landscape, has defined much of the market narrative this year — perhaps just second to everything AI. Although markets have marched steadily upward, a growing number of investors are making more defensive moves to adapt. In fact, recent data from VettaFi suggests downside protection ETFs are gaining significant traction.
Active ETFs are punching well above their weight in 2026. Despite representing just 12% of total ETF assets, actively managed funds have captured 40% of year-to-date flows, Todd Mathias, head of North America ETF product strategy at Franklin Templeton, told attendees at an April 27 roundtable discussion at the firm’s Manhattan office.
With the proverbial ceasefire negotiation can kicked down the road for the second time in a week, the U.S. and Iran remain in a stalemate over the Strait of Hormuz.
The defining feature of a Ponzi scheme is that it persuades investors to pay for future cash flows that, at least in part, don’t actually exist, while creating the impression that those cash flows imply an attractive return on the price investors pay. If we look carefully at the record valuation extremes in the equity market, and the wildly elevated profit margins that investors appear to view as permanent, we can already see the potential for difficult, even tragic outcomes for investors.
Every year, hundreds of thousands of life insurance policies lapse or are surrendered for cash. The policyholders walk away with whatever the carrier offers. Their advisors sign off. Their attorneys see nothing. And nobody asks the obvious question. Could this policy have sold for more?
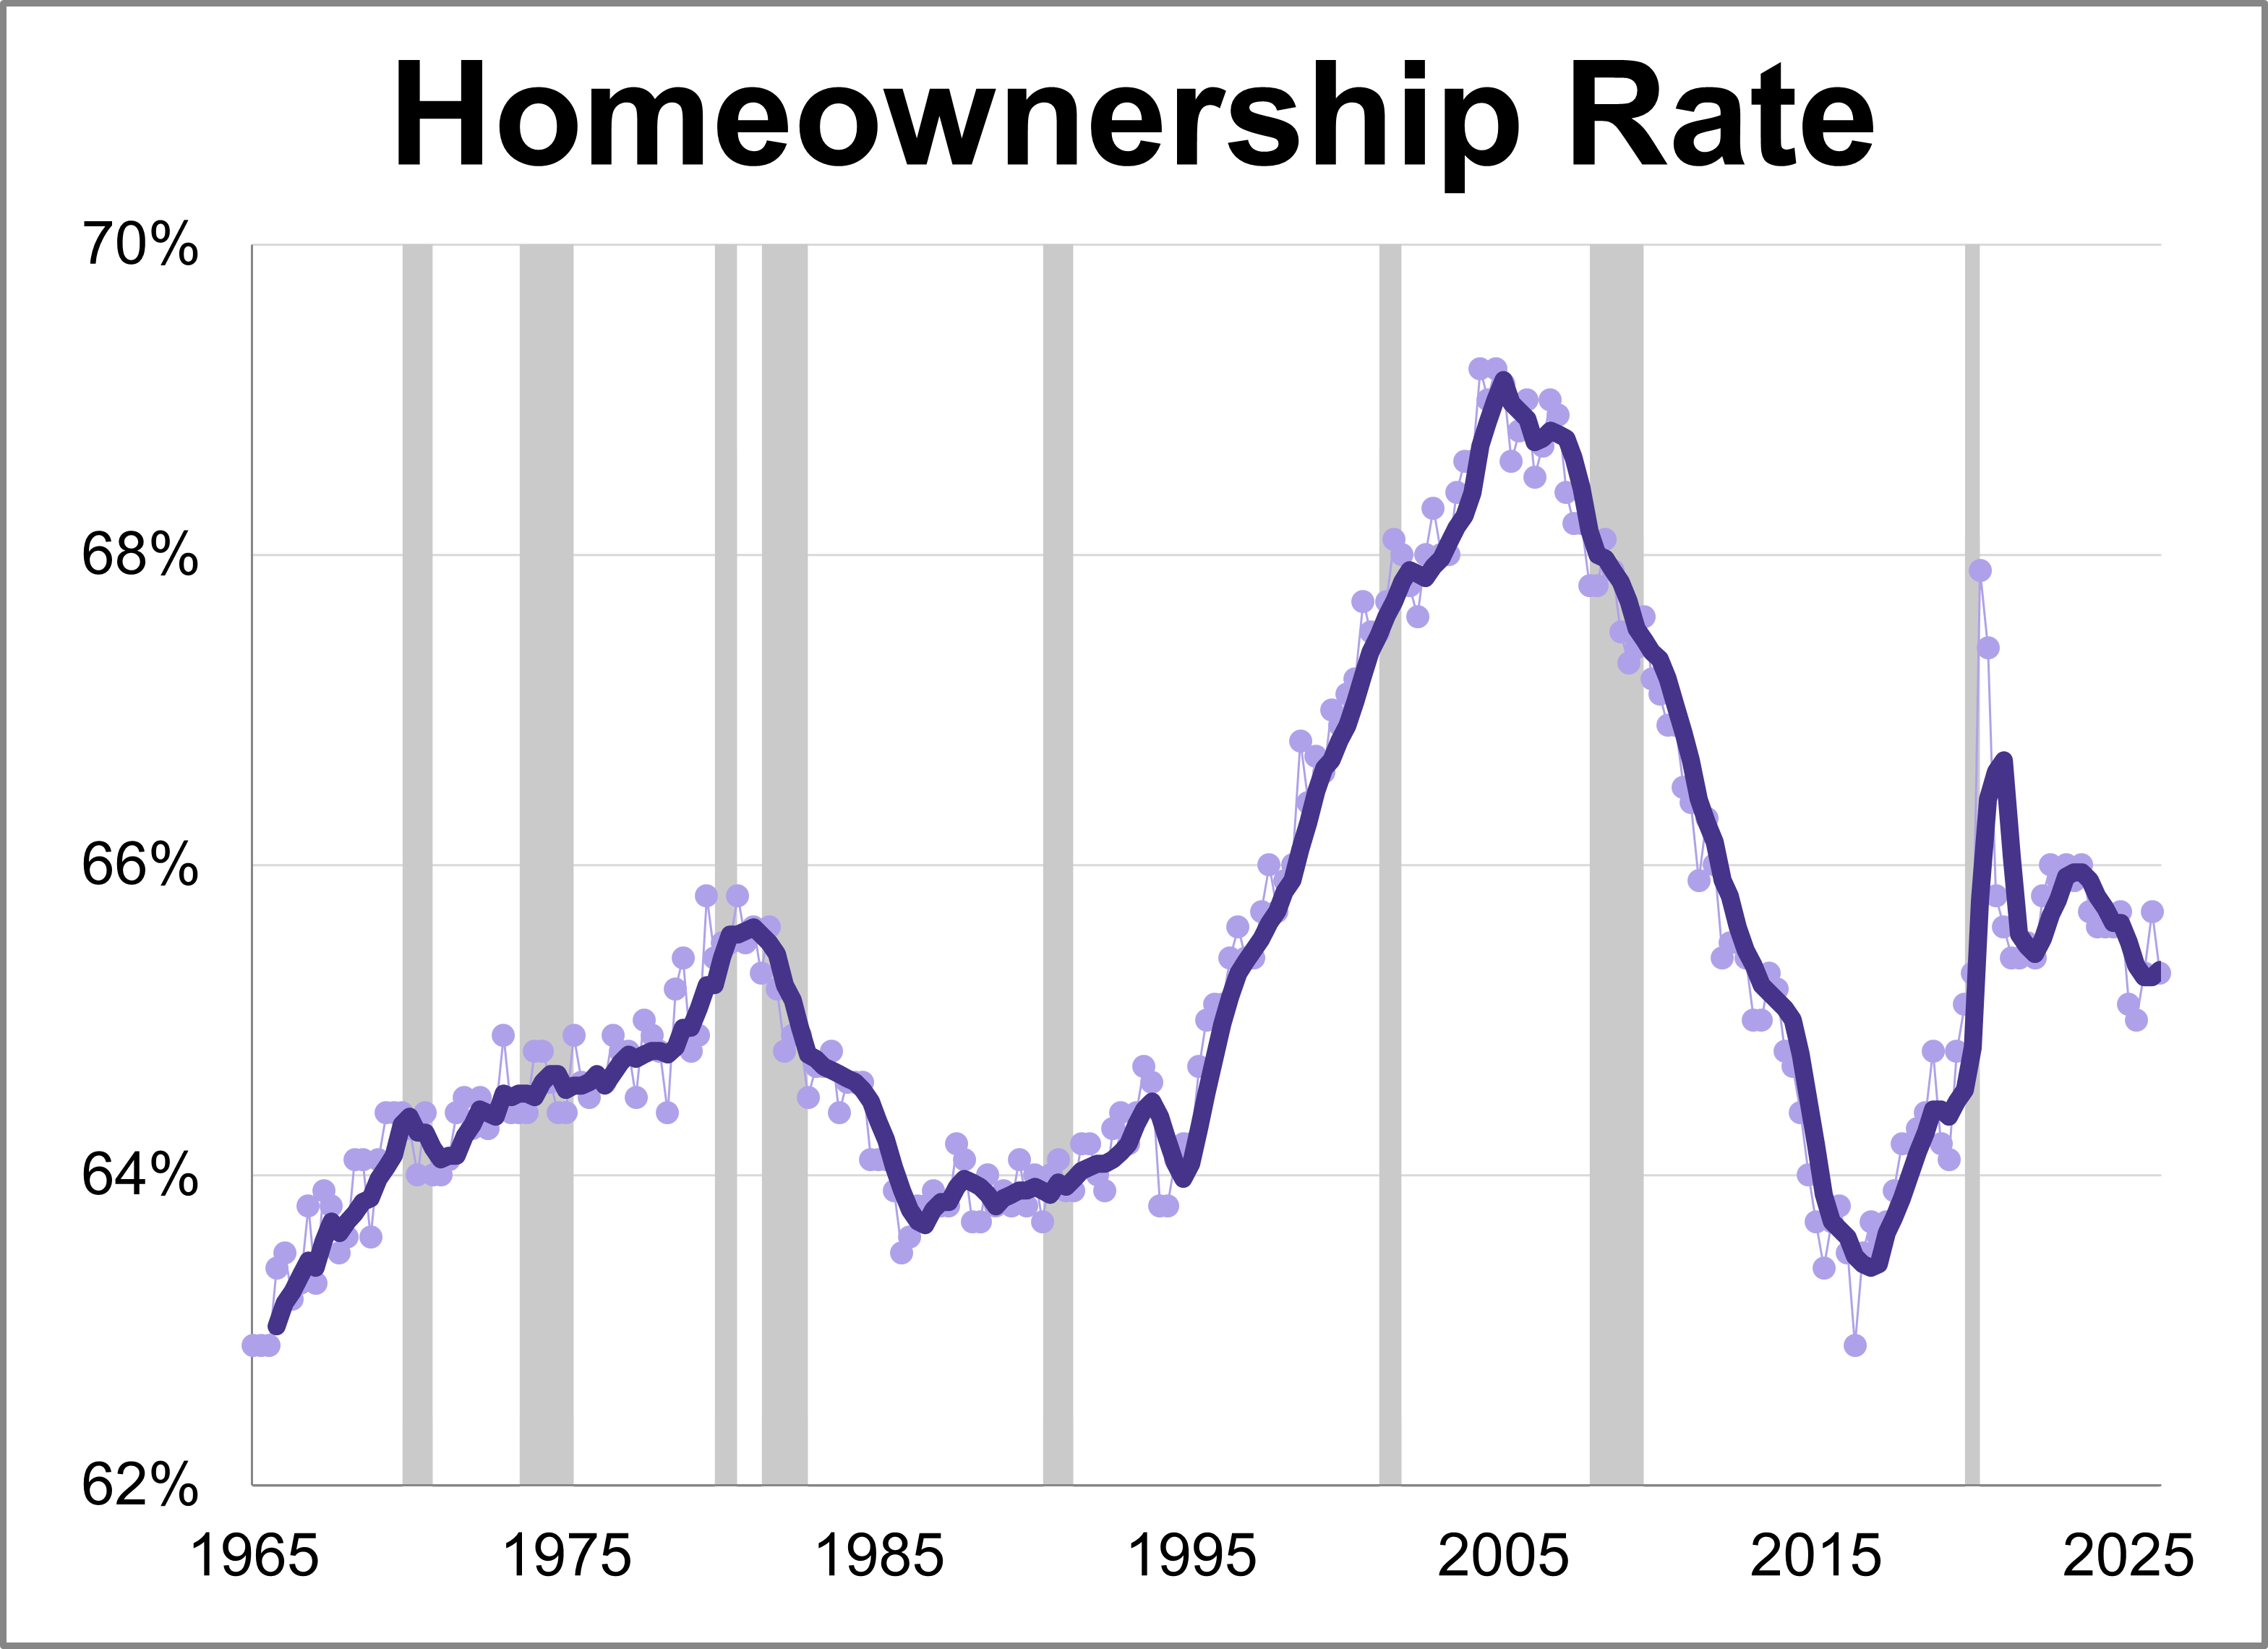
The Census Bureau released its latest quarterly report for Q1 2026 showing the latest homeownership rate is at 65.3%.
European stocks started the year much stronger than their US peers but the tantalizing prospect of the euro area clawing back some of its persistent gap in earnings growth, and the higher company valuations that come with it, looks to have slipped through its grasp again.
In elevated financial markets, risk is rarely eliminated. It is usually only relocated. During the run-up to the 2008 financial crisis, mortgage risk did not disappear. It was transformed, repackaged, and spread across the system in ways that made it appear safer than it was.
The “American Industrial Renaissance” is an investment theme investors and allocators alike have probably been pitched several times, or at the very least heard about. Supply chains for manufactured goods have evolved to become more complex, while U.S. manufacturing employment as a share of total employment has steadily declined, leaving policy makers to grapple with the ramifications of a shrinking manufacturing base.
Economic data released last week continued to highlight the same tension investors have been grappling with for months: moderating growth, inflation that remains “stuck” near 3 percent, and interest rates that remain the key swing factor for markets.
Markets continue to ebb and flow with every headline out of Iran and the Strait of Hormuz, but the most important message from the markets is resilience. Earnings season is off to a very strong start, with roughly a 75% beat rate, and the AI investment cycle continues to provide a powerful tailwind for equities.
It’s the big story so far in 2026. Alongside AI, geopolitical market volatility is creating dislocations for investors to target. While some are more immediate and some are longer term, the ETF wrapper offers strategies that can attack all kinds of sectors. In corporate bonds, for example, growing volatility could create opportunities.