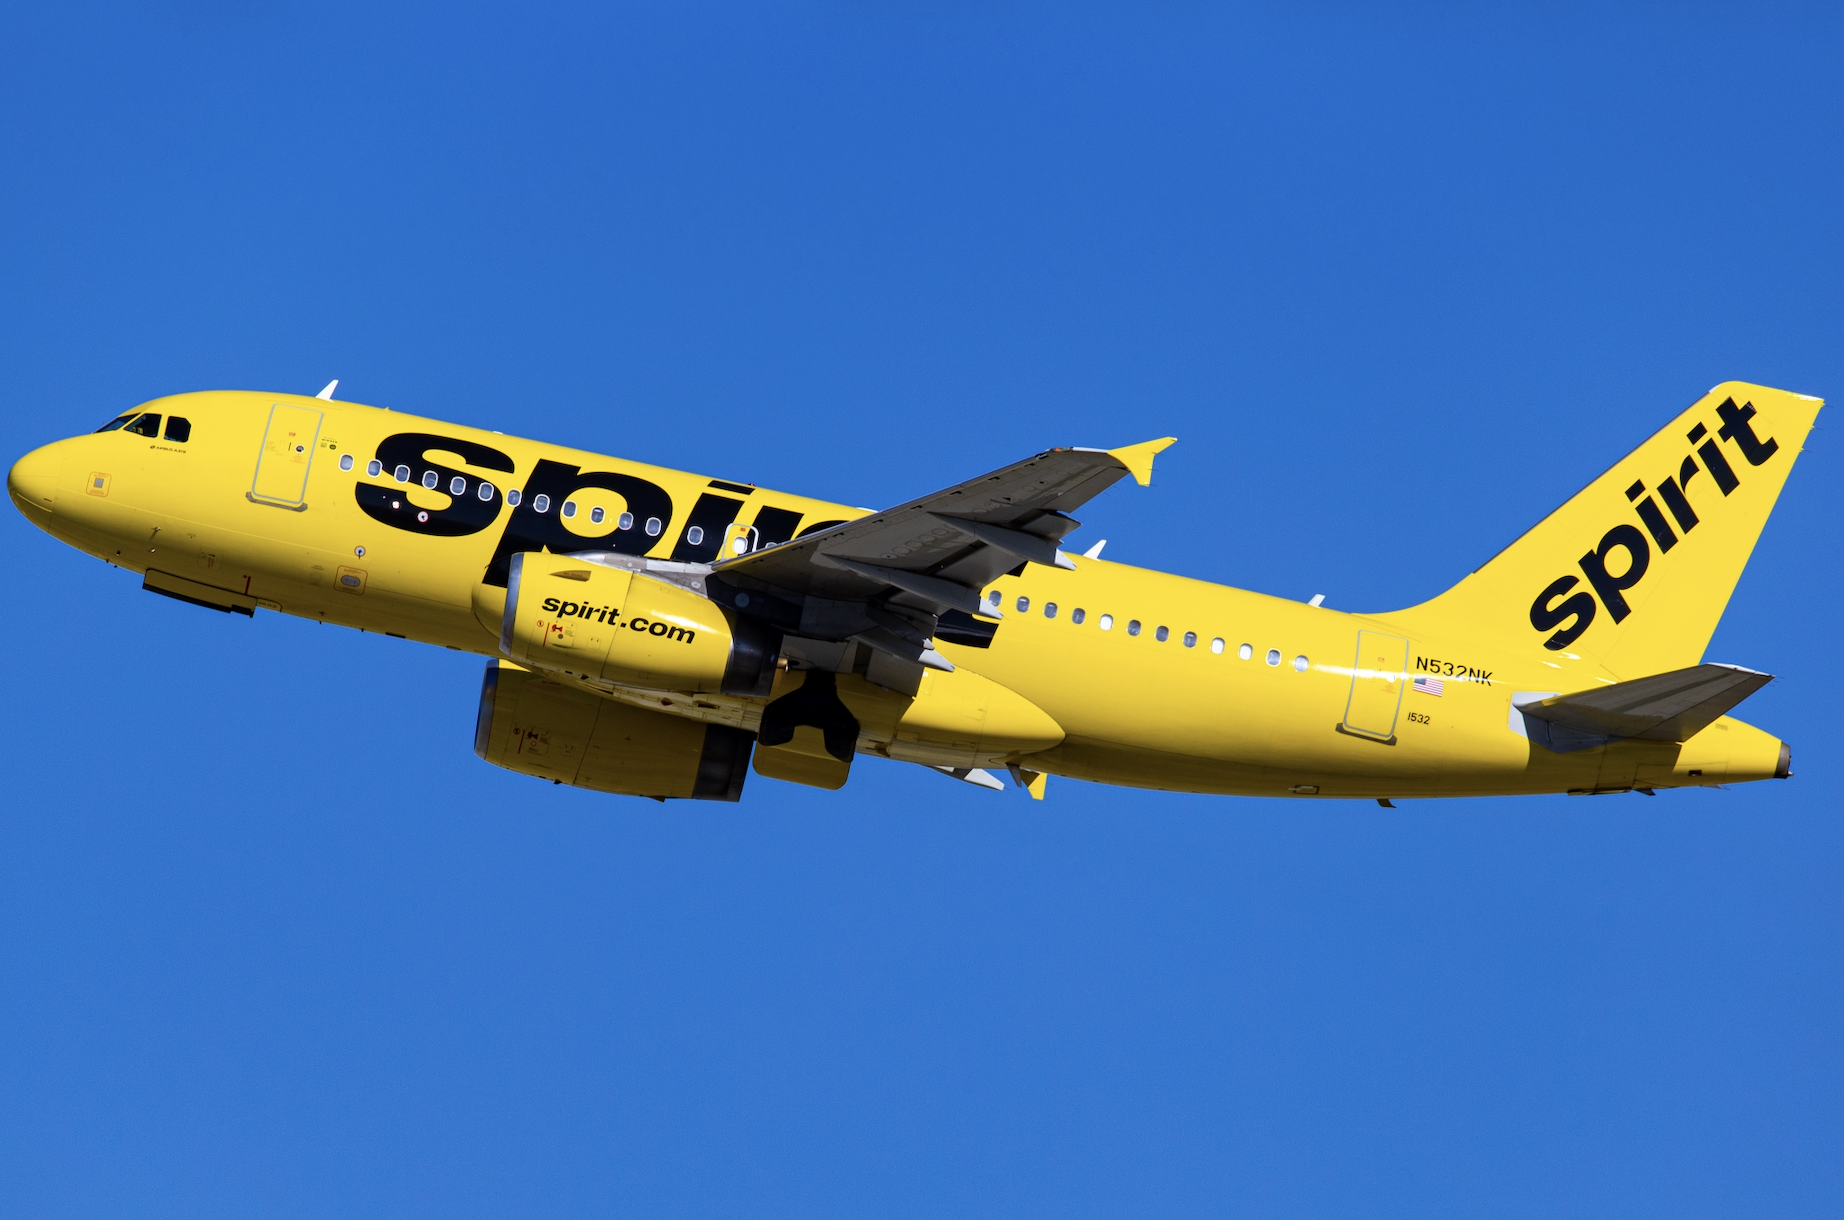
Despite the turbulence, the global LCC market remains an enormous force. Four of the world’s 10 largest airlines—Ryanair, Southwest, IndiGo and easyJet—operate on a low-cost model. The broader budget travel market is projected to exceed $315 billion by 2028, according to Statista.
The midstream energy arena, which includes master limited partnerships (MLPs), has long lured income-hungry investors. A new ETF amplifies that proposition. The MLP & Energy Infrastructure High Income ETF (MLPI) debuted last December. It’s generating buzz, helped by the White House’s rhetoric on bolstering American energy independence, which is viewed as a potential boon for MLPs.
With a better understanding of the derivatives and leverage that led to the GFC, we now explore private credit — a small “niche” financial sector, such as subprime mortgages — which is being called the next match to light a financial bonfire.
The world’s most important central banks will potentially hand investors fresh reasons to sell government bonds this week as policymakers find themselves forced to confront the risk of a war-driven inflation shock.
Like many of you, I am inundated with information. Most of it is not useful or repetitive. Today, were going to do something different. Rather than one theme, let’s look at various bits of data that I found interesting this week.
Back-and-forth developments over the weekend around the Strait of Hormuz have added near-term volatility to energy markets. That uncertainty is feeding into oil prices and reinforcing questions about how persistent energy-driven inflation pressures could become, particularly if disruption risks continue to ebb and flow.
Last week’s economic data was defined by conflicting signals from the consumer. While retail figures suggest resilience, sentiment levels have plummeted to record lows. Meanwhile, the S&P 500 continued its historic rally as markets prepare for the upcoming Fed decision.
The primary contagion risk is sector concentration. Software and tech-enabled services represent roughly 15-20% of direct lending portfolios. A meaningful portion of these loans also resides in the Broadly Syndicated Loan (BSL) market – the bedrock of CLO ETFs – leading to a software weighting of 12–18% in typical CLO collateral pools.
The index is on the verge of doubling for the first time in this bull market – currently up ~99% – a move that would take just under 3.5 years, slightly faster than the historical average of 3.9 years. While all sectors are in positive territory over this period, leadership has been narrow with only three – technology, communication services and industrials – posting gains above 100%.
Clients may love the relative safety of cash, but many advisors know those assets could do more. A multisector bond approach for example, offers plenty of rewards for those willing to dive in. The right ETF can give tax efficient exposure to the space, providing both yield and total return.
Even before the first active dual share class fund from Dimensional launched, active mutual funds and ETFs were already roommates rather than existing in separate silos. Ben Johnson, head of client solutions at Morningstar, revealed in a LinkedIn post that active managers are increasingly using ETFs as essential tools for building portfolios.
Global bond markets are heading for their worst week in a month as investors grow increasingly uneasy about a stalemate between the US and Iran.
The spring edition of our Investment Directions takes on a new look. As the weather heats up, our “summer body” of work embraces a slimmed down word count, Q&A format, and visualfirst approach – better for consuming on the go, or preferably, outdoors.
With policy changes creating more access to retirement savings plans, more workers are saving for the future. According to the Investment Company Institute, nearly 75% of households own some form of tax-advantaged retirement account such as a 401(k) or IRA.
Investors often view commercial real estate (CRE) through the narrow lens of the office sector. We think this office-only focus understates how broad the asset class is and its potential. Offices may face well-documented headwinds, but many other CRE segments appear more resilient.
Kevin Warsh's bid to become the next chair of the Federal Open Market Committee (FOMC) unfolded amid sharp political tension, legal uncertainty, and pointed questions about his independence from President Trunp. During a combative Senate confirmation hearing, Warsh sought to reassure lawmakers that he would not allow political pressure to dictate monetary policy, even as unresolved Justice Department investigation into current Chair Jerome Powell threatens to delay his confirmation and underscores broader concerns about the politicization of the central bank.
Markets are being pulled in multiple directions. Geopolitical tensions, questions around Federal Reserve policy and the rapid rise of artificial intelligence are all competing for investor attention.
Markets have long struggled to price geopolitical risk. Part of the issue is that each flare-up tends to be viewed as a one-off volatility jolt to be weathered and then faded once there is resolution.
Higher oil prices have both positive and negative effects on the municipal bond market. Investors may want to evaluate their concentration risk.
At this point, investors of all ages are well aware just how much inflation can cut into one’s spending power, whether it be for everyday expenses or big-time purchases.
The sheer complexity of exchange-traded funds (ETFs) using derivative-based strategies could have investors turning the other away. Instead, investors have been running towards them. The capital markets witnessed a surge in demand for these tactical ETF tools during the first quarter of 2026, making it a topical theme at the most recent Nasdaq-sponsored Asset Allocation Summit.
Volatility, tighter margins, and rising client expectations are prompting many Advisors to reassess whether their current broker-dealer or firm is still the best long-term fit. If you’re considering a transition, in this article we will discuss 10 essential questions to help guide your decision.
After years weighing how to dive deeper into private credit, JPMorgan Chase & Co.’s $4.3 trillion asset manager is committing to a strategy that will plow tens of billions of dollars into loans sourced by the firm’s commercial bankers.
Nearly two months into the conflict in Iran, global stock markets are staging a defiant rally. From the US to Taiwan and South Korea, a disconnect has emerged: while the geopolitical tensions remain high, equities are charging back toward all-time highs.
Concerns about the sustainability of U.S. fiscal policy have moved back into the investment spotlight. Over the past week, both multilateral institutions and prominent policymakers have raised warnings about the potential implications of America’s expanding debt burden for Treasury markets.
Each spring, the International Monetary Fund (IMF) releases its World Economic Outlook (WEO), a review of global growth, and the key challenges confronting the world economy. This year’s edition followed the Fund’s usual structure, but the circumstances underneath it had shifted. ]
It’s a busy macro stretch as company earnings reports come in fast and furious. A focus on real data and earnings may be a welcome development for investors wary of geopolitical headlines. The team at Wall Street Horizon will keep you up to speed with the latest trends, and you can access our industry-leading forward-looking corporate event data to stay ahead of markets.
Not only has infrastructure been devastated in key energy production zones, but other critical commodities like fertilizer have become much more expensive as well. It’s important for investors to respond, especially those at or near retirement. The right type of income ETFs can be that response.
Even in the event that the Middle East conflict eases and shipping resumes as usual through the Strait of Hormuz, it would likely take time for the global economy to normalize after one of the largest oil supply disruptions in decades.
When advisors and investors hear the terms “high yield” or “junk” as it relates to bonds, they understandably have some apprehension. After all, junk bonds carry elevated credit risk relative to their investment-grade peers. Hence the higher yields, which act as added compensation for the extra risk.
Fixed-income market sentiment was dominated by geopolitical headlines, particularly the conflict in the Middle East following disruptions to the Strait of Hormuz and rising oil prices, which contributed to renewed inflation concerns.
The U.S. market story this year has been a tug-of-war between sticky inflation, slower growth, and resilient risk appetite. For fixed-income investors, that mix has produced more narrative movement than the 10-year Treasury itself.
Amid rising college costs and mounting student debt, parents are looking for more ways to lessen the financial burden of higher education. Luckily, 529 college savings plans can help. These unique savings vehicles offer several tax breaks for parents as they save for their children’s future education.
While we are currently in a particularly grueling climb (including the war in Iran – a situation in which we will provide an update at the end of this piece), we cannot lose our long-term perspective. We want to take this piece as a summit in the middle of our hike; one where we can see a path through the trees and hills and clearly see four potential paths from here.
Vanguard is boosting its holdings of Treasuries, taking advantage of higher yields following the Middle East conflict to lock in rates and hedge against the risks of a potential growth slowdown.
Stocks are trading near a record high, signaling Wall Street is learning to cope with lingering geopolitical risks. Main Street is struggling to catch up.
Every prospect is different. They have different interests, different decision timelines, and different levels of engagement. Treating them all the same because your CRM can't segment effectively is leaving money on the table.
LPL Research examines the fixed income space as global bonds broaden yields and reduce U.S. concentration, offering diversified income and resilience via non‑U.S. developed and emerging markets.
As always, I hope you’re having a good 2026 and that all is well with you, my readers, and your family and friends. Here’s my latest.
While Russ acknowledges that the ongoing conflict in the Middle East has contributed near-term volatility, he also notes that these rising tensions are occurring against the backdrop of a solid U.S. economy.
The long-term care confidence gap is the difference between understanding the importance of a risk and consistently addressing it with clients. Advisors know, but they do not always say. The gap isn’t about intelligence or professionalism; it’s about the difference between technical knowledge and conversational leadership.
Early in my financial planning career, if a client told me they had a terminal diagnosis, every alarm in my head would go off. Before the meeting was over, I would have a to-do list that was three pages long.
Yes, much of the blame lies with energy prices, which surged due to the war in Iran. Still, the March reading of the Consumer Price Index (CPI) serves as a reminder of the work to be done to damp inflation.
Billionaire money manager Bill Ackman is giving away a stake in his firm to investors who support his latest hedge-fund launch. This looks like a good deal. And so it should: If you’re selling a fund in the form of an initial public offering, you have to dangle the prospect of a quick buck.
The history of the U.S. airline industry is really a history of consolidation driven by crisis. The pattern has been remarkably consistent. Historically, when an external shock has hit—a recession, a war, an energy spike—the weakest carriers have folded or been acquired, while the strongest have emerged leaner and more profitable.
Over the past few weeks, a rising tide of optimism has been gathering in the equity markets. This positive momentum reached a crescendo last week when Iranian Foreign Minister Abbas Araghchi announced that, in line with the ceasefire in Lebanon, the Strait of Hormuz would reopen for commercial vessels after being closed for approximately seven weeks beginning in late February.
Clearly the path to peace is not as easy as it looked last Friday when the easing in Middle East tensions, the reopening of the Strait of Hormuz to commodity flows, and the sharp retreat in oil prices calmed fears on the most immediate macro threat to equities.
The Q1 2026 earnings season has officially started, and the early results suggest a market that is largely defying the geopolitical fog we’ve discussed.
Get ready each week with high-conviction insights that go beyond media headlines.
Oil shocks hitting economies with weak demand and strained balance sheets are especially damaging. Firms cannot fully pass on rising costs, so margins shrink, layoffs increase, and investment falls. Tightening monetary and credit conditions would cause inflation to fade faster but job losses, failures, and fragile household finances to be much worse.