The economy is running bad inflation, and the bad kind is the temporary kind, which is precisely why the bond market refuses to panic.
Key Takeaways
- Inflation driven by supply shocks is “bad” inflation, and bad inflation is self-liquidating because rising income doesn’t support it.
- September headline CPI was 3.7% while core CPI was 2.6%. The gap is gasoline, up 34.2% over the year and now more than half of the monthly increase.
- Real wages have turned negative, and labor’s share of output just set its lowest reading since the series began in 1947.
- The 10-year breakeven sits near 2.3%. The market that gets paid to price inflation is not pricing an inflation problem.
Most of the argument about inflation right now is a fight between people using the same word for two completely different things. One side sees a 3.7% headline print and starts sketching a repeat of 1979. The other sees core running more than a point below it and declares the problem solved. Both are reading the same release. The distinction that matters is not how big the number is, but whether anybody’s income is financing it. That is the line between “good” inflation and bad inflation, and almost nobody draws it.
Good Inflation, Bad Inflation, And The Difference Nobody Makes
There is a general framework to inflation, and it is older than any of us. Prices can rise because buyers are bidding for scarce goods with money they’ve actually earned. Or prices can rise because the cost of producing something has jumped for reasons unrelated to demand. An oil embargo will do it, as we saw in the 1970s. So does a shuttered Strait of Hormuz, a new tariff schedule, or a pandemic that takes half the world’s shipping capacity offline for eighteen months.
This is an important point for the “debasement” crowd, whose narrative overlooks the underlying fundamentals.
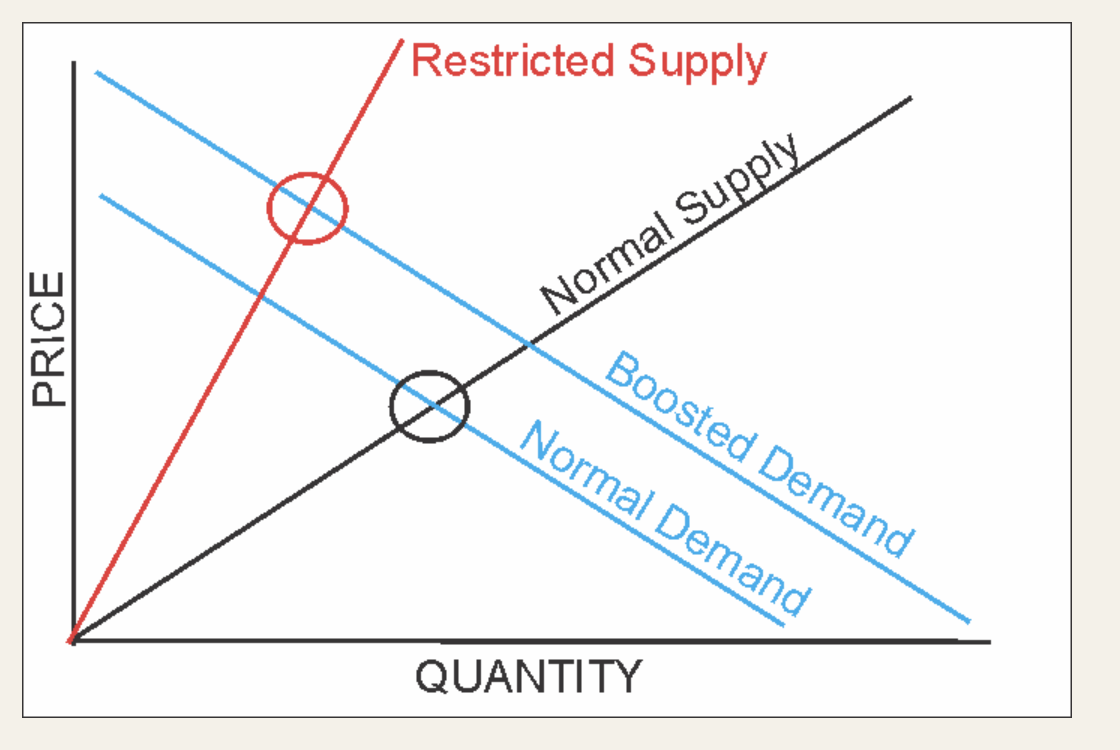
“The following economic illustration is taught in every ‘Econ 101’ class. Unsurprisingly, inflation is the consequence if supply is restricted and demand increases via monetary interventions.”
However, there is a very important distinction to be made about inflation. The first type is the “good” kind of inflation, and it is genuinely good. Demand pushes prices up; firms book wider margins; tight labor markets funnel those margins into paychecks, and the higher paychecks fund the higher prices. The loop closes and becomes self-reinforcing because every leg of it is paid for by real output.
The second kind, the “bad” kind of inflation, closes nothing. A tariff is a tax, just like an oil shock is a tax. Somebody’s cost went up, and the money has to come out of a budget that did not grow. Every dollar of that price increase is a dollar not spent somewhere else. Bad inflation doesn’t create the income that pays for it, so it destroys the demand that supports it. Such is the mechanism behind the oldest saying in commodities: “high prices cure high prices.”
Think of it this way. A group of people drives the same way to work every day. Half get a raise, the other half doesn’t. The city decides to put a toll booth on the road they drive to work; each year, that toll rises. Both groups have an increasing number draining their bank accounts each month. However, only one group has sufficient compensation to continue using the toll road. The group without the compensation raise is eventually forced to stop using the toll road; traffic falls, and the operator cuts the toll to win them back.
See more: Equities: On Hikes and Highs
What The September Print Actually Says
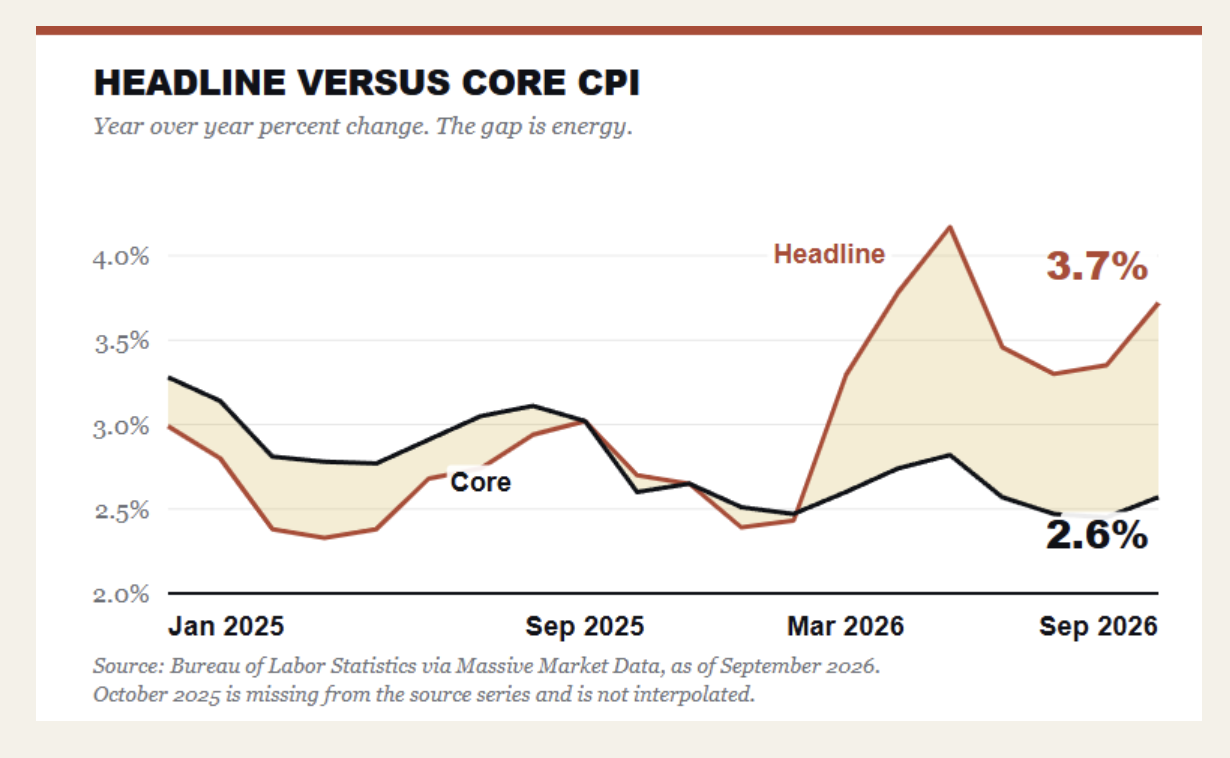
Let’s review the recent August data to see what the message, versus the narrative, actually is. The headline CPI came in at 3.7% year over year in September. Core came in at 2.6%, a tick higher than August. Read that pair again, because it is the whole argument. The gap between them widened from nine-tenths of a point to one and a tenth, meaning the headline accelerated roughly three times faster than the core.
That gap suggests a very different narrative than what the media suggests. Gasoline rose 9.1% in the month alone and 34.2% over the year, and the BLS attributes over half the entire monthly increase in the all-items index to that one category. Energy overall is up 20.4%. Meanwhile, core goods, where a genuine demand boom would show up first and loudest, rose 0.7% over twelve months, sitting exactly where it was in August. Shelter ticked up to 3.2%
Now the part I owe you, because I set a test in advance. Core ticked up, shelter ticked up, and services’ less energy reached 3.1%, which would eventually prove me wrong. One month of tenths is noise rather than a trend. It is also the first month this year that those three moved the wrong way together, and core goods holding flat at 0.7% is why I am not moving yet, because that is where a demand boom announces itself first, and it has not.
Headline CPI pulled further away from core in September. The shaded area is the spread, and the spread is energy. Source: BLS via Massive Market Data, September 2026.
I’ve been making this argument since June, when I wrote about why the May 4.2% headline was an oil story rather than a demand story. To wit:
“A 4.2% headline that is three-fifths gasoline is not the same animal as a 4.2% headline driven by wages, rents, and services broadening.”
Four months later, the composition has not changed. What has changed is that the evidence against the demand-pull story got considerably stronger.
Labor Just Set A 79-Year Low
The most important evidence comes from the labor market. If this were the “good” kind of inflation, workers would be capturing some of it. They are not.
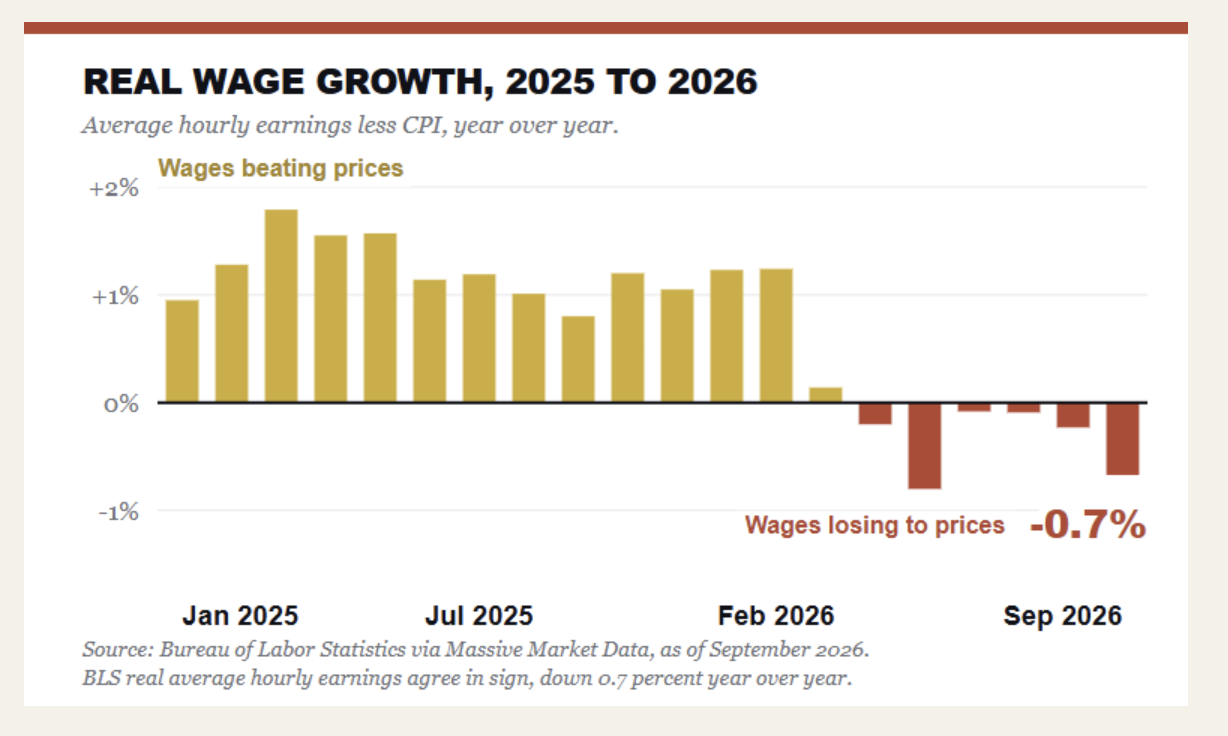
Real average hourly earnings fell 0.7% over the twelve months through September, more than double the August decline. Nominal wages rose 0.1% on the month against a 0.6% CPI print, so purchasing power went backward at the fastest pace of the year. Run the same calculation off average hourly earnings and CPI, and you land in the same place. Real wage growth is near -0.7%, down from over 1.5% as recently as last spring.
In April 2026, real wage growth crossed below zero and hit its weakest reading in September. The gold bars represent the months when wages grew faster than prices. The red bars are months when they didn’t. Source: BLS via Massive Market Data, August 2026.
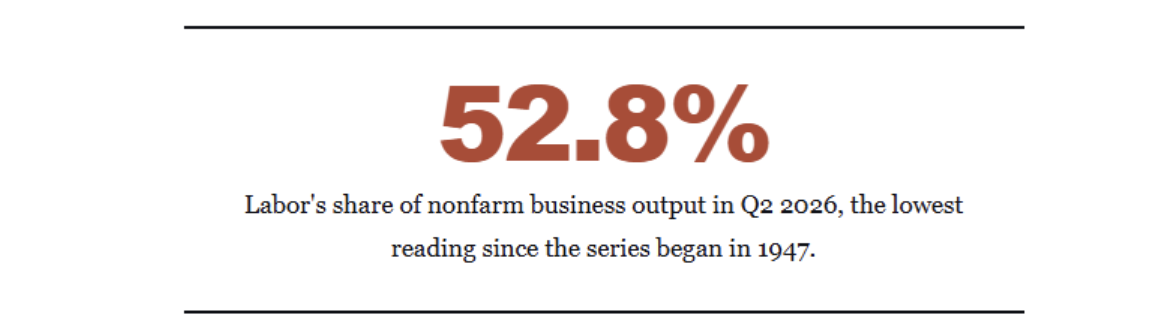
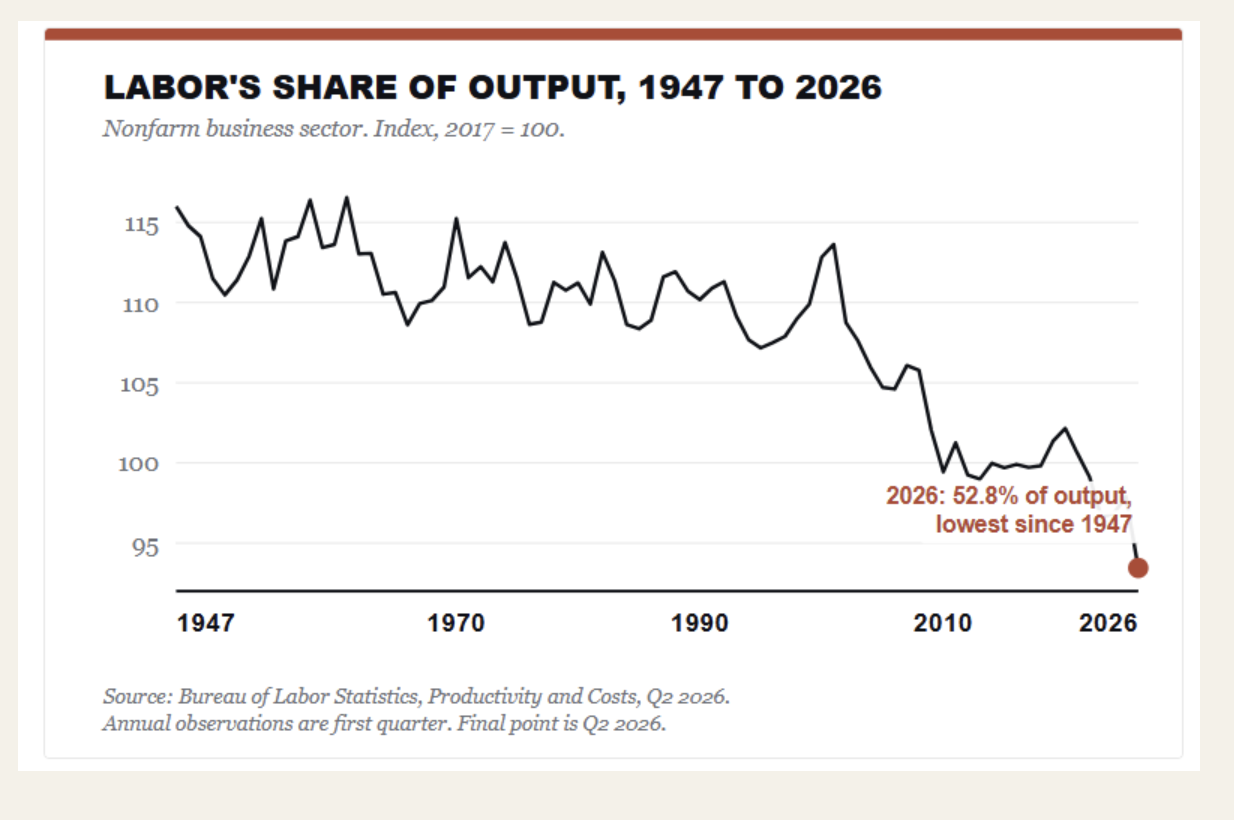
Then there is the one number that everyone simply overlooked. In the second quarter, labor’s share of nonfarm business output fell to 52.8%. The Bureau of Labor Statistics flagged that as the lowest level in a series that begins in the first quarter of 1947. Read that again. There have been 79 years of data, 2 dozen business cycles, 4 major wars, the Volcker shock, the China trade shock, and the pandemic. Despite all that, in what is supposed to be an economic boom, we just set a record low.
Here is what it looks like graphically. This is not what an inflationary boom looks like.
Labor’s share of output has been falling for a quarter century and just made a series low. Good inflation requires this line to rise. Source: BLS, Productivity and Costs, Q2 2026.
Stop and notice that in the chart above, this is not a 2026 event. The erosion in labor runs back to the early 2000s, long before “artificial intelligence” or “surging debt.” The last two years have simply accelerated the numbers. With respect to the inflation question, the timing matters most. A price level that is rising while labor’s slice of output hits an all-time low is the textbook signature of cost pass-through rather than demand-pull. In this environment, corporations are fixated on protecting profit margins, while workers are absorbing the difference.
The economic activity surveys tell the same story if you take the time to read past the headlines. The ISM services printed 54.9 in September, with new orders easing to 59.8. That reads like a demand boom until you see prices paid at 74.0, the highest since July 2022, while the employment index has not exceeded 50.1 in three months. Steady orders, hot input costs, flat payrolls. When respondents were asked what was driving those costs, fuel came up about twice as often as anything else.
Where The Inflation Bulls Have A Point
As always, we need to examine both sides of every argument, as the inflation bulls do have a valid point.
The strongest one is the AI buildout. Memory is genuinely scarce; its scarcity is genuinely caused by capital spending, and the producer price index for storage devices has climbed 23% since the end of 2024, while import prices for computers and parts are up 37%. J.P. Morgan’s research team puts the memory shock at 0.2% to 0.4% on core inflation. That is capex-driven price pressure; it is real, and it did not come from an embargo. However, that scarcity will eventually reverse. As with oil prices, high prices eventually curtail demand.
The second argument is that tariffs are a policy choice, not a weather event. That is a true statement, and a tariff regime that stays in place for years produces a price level that stays elevated for years. Calling that “transitory” is a semantic trick. I can’t argue with that. A permanent tax produces a permanent price. However, the current tariffs were not enacted by Congressional legislation, which would make them more permanent. In this case, they were enacted through executive order, which means the next Administration can repeal them quickly.
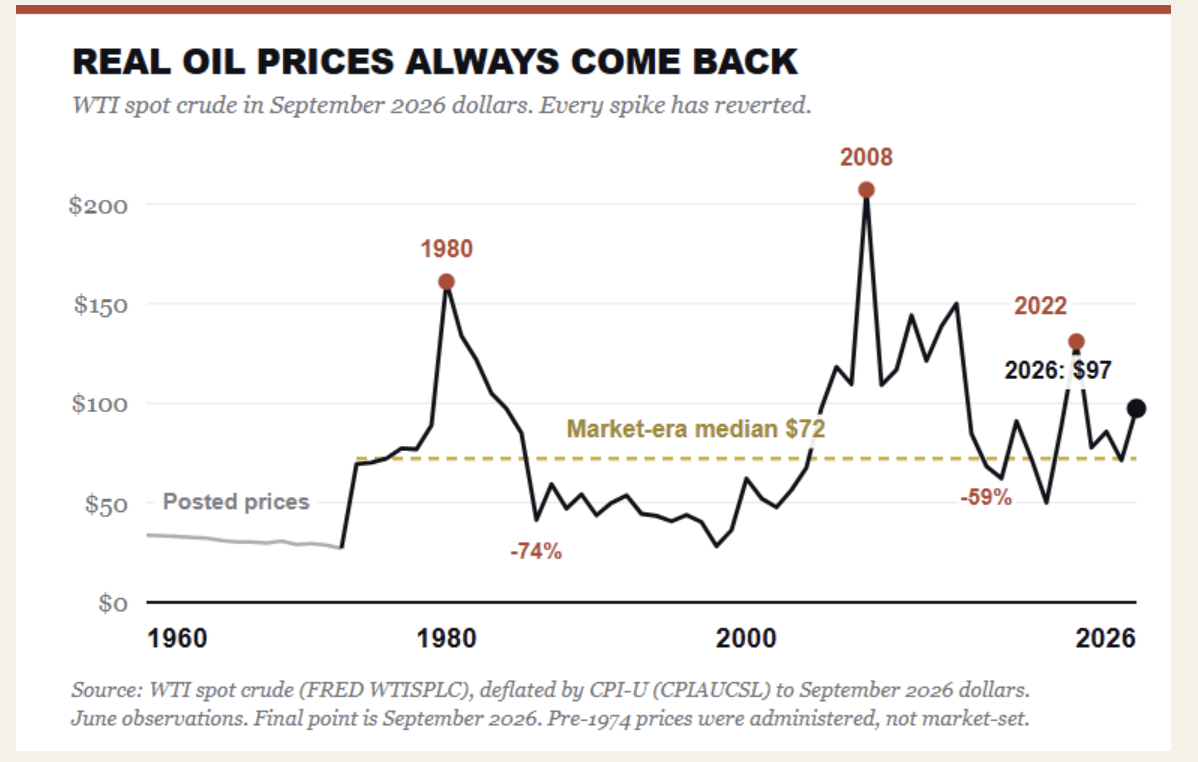
The third is that energy is not reliably mean-reverting on any schedule you can trade. Geopolitics doesn’t run on a calendar. However, high oil prices, as shown in the chart below, reliably mean-revert over time.
Those are all sound and valid arguments, but there is a problem with all three, though. Every one of them describes a SUPPLY constraint. A memory shortage is, by definition, a shortage. Call the tariff what it is: a tax. And the Middle East risk is a supply risk. None of them creates the income that pays the higher price. All three fail the same test: gasoline fails, and a more flattering story doesn’t change what the bill does to a household budget.
Why Bad Inflation Cures Itself
“Inflation is inflation. My grocery bill doesn’t care about the taxonomy.”
That is a fair statement. The pain from inflation is the same either way, and when you are staring at the number on the gas pump, the squeeze on household budgets happens regardless. Just because it happens to be the academically preferable kind, the household budget just doesn’t care. However, the taxonomy isn’t about how it feels, but how it ends, and bad inflation ends in a way the good kind never does.
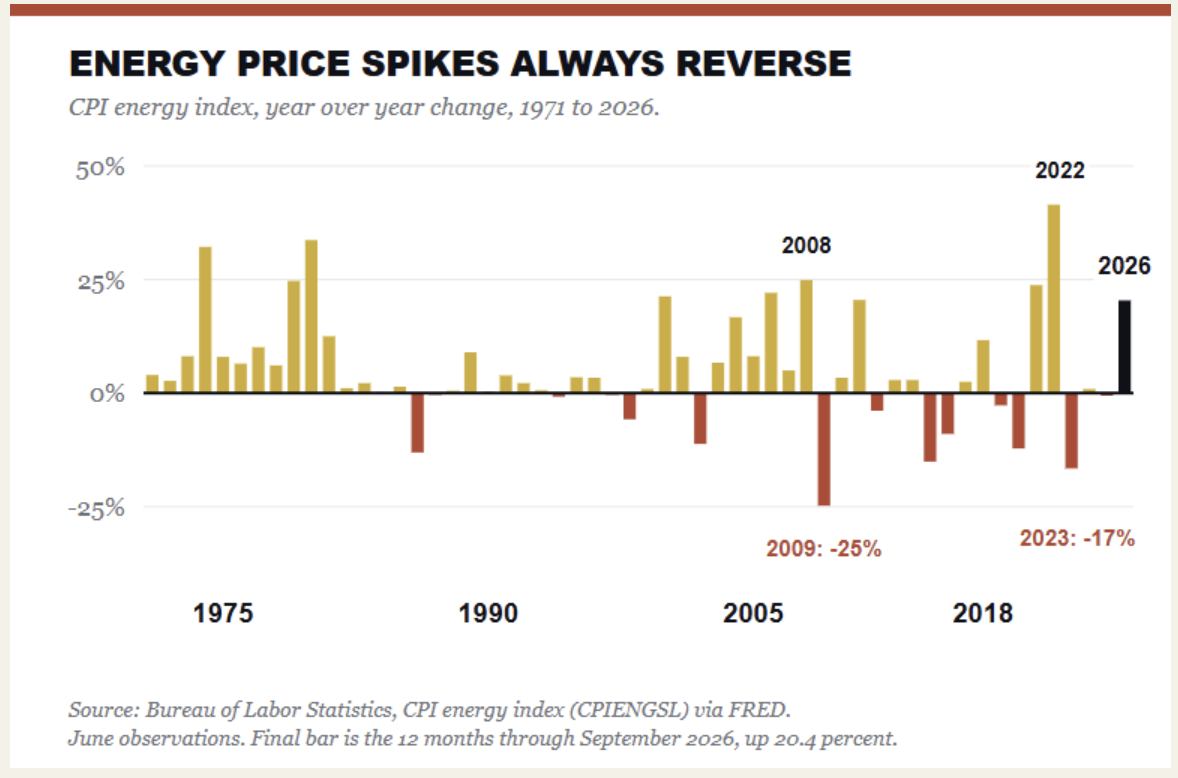
Every major energy spike since 1971 has reversed within one to two years. The 2008 spike gave way to a 25% collapse. The 2022 spike gave way to a 17% collapse. Source: BLS, CPI energy index via FRED, through September 2026.
Notably, look at what happens after every spike on that chart. In June 2008, energy jumped by more than 24%, then subsequently fell by 25% over the following year. In June 2022, energy surged by 41.5%, then only to fall by 16.6% by 2023. Every period from the 1974 and 1980 shocks, the 2000 run, and the 2015 collapse is the same. The pattern repeats itself because it has to, since “demand destruction” is not an economic theory; it’s just arithmetic. The current reading of roughly 20% sits well inside the range that has always reverted.
Such is why the bond market refuses to panic. The 10-year breakeven inflation rate is 2.33% as of October 13, and the September monthly average was 2.36%. That number has barely moved all year, holding a range of roughly 2.24% to 2.44% while headline CPI swung from 2.4% up to 4.2% and back to 3.7%. The one market that gets paid to be right about inflation looked at an 180-basis-point headline swing and didn’t blink. It then watched September print three-tenths hotter and tick down.
Critically, this is where the case from the “Persistent Purveyors Of Doom” gets confused with itself. Yes, bond yields are elevated, and the bears point at that as vindication for their case. The 10-year sits near 5.1% and the 30-year above 5.55%. But if you decompose it, the rise is due to real yield and the term premium, not inflation expectations, because expectations have been pinned near 2.3% for 18 months. Since early September, the long bond has added about 30 basis points, while the breakeven has given up 3. The bears are right that the long end is repricing. They just have the wrong reason.
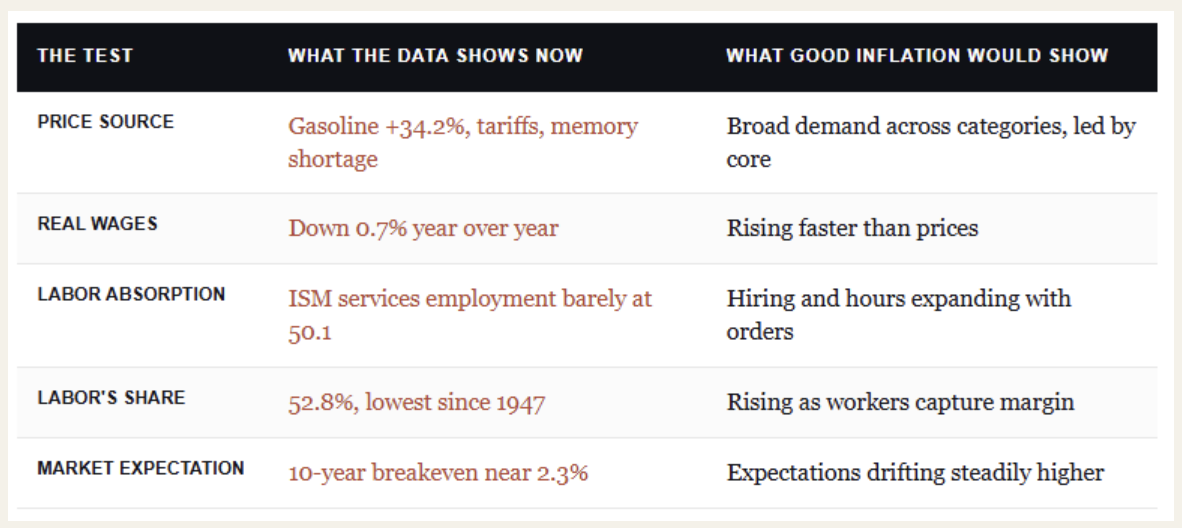
Five tests, and five answers pointing in the same direction, which all bring to mind a rule to live by.
“When every strategist on television agrees that inflation is structural and yields only go up, the setup is usually pointed the other way.”
What This Means For Portfolios
Will bad inflation cure itself on a schedule you can put in a calendar? No. Demand destruction takes quarters, not weeks, and an energy shock can persist long enough to cause real damage as it resolves. Such is the frustration of running a process that works in quarters for clients who measure in weeks. But will it resolve without the Fed having to break something? On this evidence, probably yes, and that is a very different portfolio than the one the inflation-forever crowd is selling.
It argues for duration, which is the position I laid out in my discussion about wage growth as a leading inflation indicator. Since then, the real wage data has reinforced that positioning. Investors who bought commodity-linked exposure as an inflation hedge may have the wrong trade. The reason is that commodities would hedge the one kind of inflation that has historically unwound. However, quality equities with pricing power beat the debt-heavy cyclicals that need a nominal boom to work. Most notably, watch the labor data rather than the CPI headline. Labor is where the answer lives.
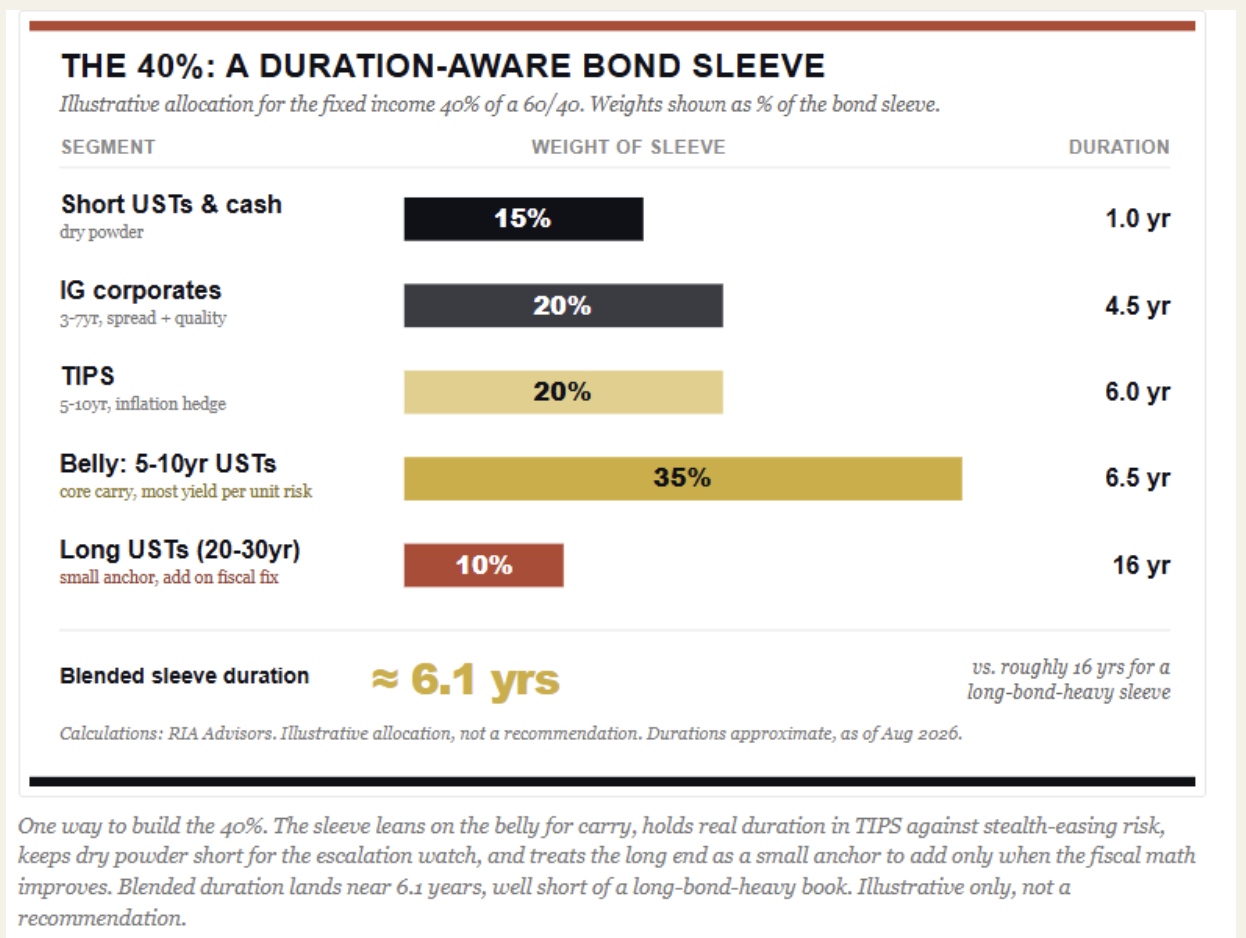
In the current environment, as laid out in the “Druckenmiller Warning,” an effective bond sleeve would look something like this.
Here is what would change my mind, stated plainly so you can hold me to it. If core services excluding shelter reaccelerate, if the Employment Cost Index turns up, if real hourly earnings cross back above zero, and the quits rate rises, then the wage loop is closing, and this inflation became the durable kind while I was arguing it wasn’t. Watch those four. I’d rather be corrected by data than by a client’s statement.
The thing to fear was never that prices would keep climbing. It’s that they’ll stop climbing because nobody can afford them anymore, and labor’s share of output has been telling us for twenty-five years exactly which of those two we’re heading toward.
Sources & Notes
- U.S. Bureau of Labor Statistics, Consumer Price Index, August 2026, released September 11, 2026. Headline 3.4% year over year, core 2.4%, gasoline +27.4% year over year, energy +16.3%, core goods +0.7%, shelter +3.0%.
- U.S. Bureau of Labor Statistics, Real Earnings, August 2026. Real average hourly earnings down 0.1% on the month and 0.3% over twelve months.
- U.S. Bureau of Labor Statistics, Productivity and Costs, Second Quarter 2026. Labor share 52.8%, described in the release as “the lowest level in the series, which begins in the first quarter of 1947.” Nonfarm productivity +1.4% annualized in Q2 and +2.2% over four quarters.
- Institute for Supply Management, Services PMI, August 2026: headline 55.4, new orders 60.9, prices paid 72.6, employment 47.8. Respondent commentary cites tariffs and the conflict in the Middle East.
- Federal Reserve Bank of St. Louis, 10-Year Breakeven Inflation Rate (T10YIE), 2.36% as of September 11, 2026. Monthly series from Massive Market Data show 2.29% for August 2026 and a range of 2.24% to 2.44% across 2026.
- U.S. Treasury constant maturity yields via Massive Market Data, September 9, 2026: 10-year 4.83%, 30-year 5.28%, 2-year 4.43%.
- J.P. Morgan Global Research, on the AI-driven memory shortage. PPI for storage devices +23% since end-2024; import prices for computers and parts +37%; estimated 0.2%-0.4% lift to core inflation.
- Replication note per house practice: the real wage series plotted above was rebuilt from BLS average hourly earnings and CPI rather than taken from the BLS real earnings release. The rebuilt series shows -0.26% year-over-year for August, compared with the release’s -0.3%. The difference is rounding and the release’s use of CPI-U seasonal detail. Both agree on sign and direction, and the argument does not hinge on the third decimal place.
- Data note: the October 2025 CPI observation is absent from the source series and has been left as a gap rather than interpolated.
- Prior RIA analysis referenced: May Inflation Print: Why the 4.2% Headline Is an Oil Story (June 13, 2026) and Wage Growth As A Leading Inflation Indicator (July 3, 2026).
Lance Roberts is a Chief Portfolio Strategist/Economist for RIA Advisors. He is also the host of “The Lance Roberts Podcast” and Chief Editor of the “Real Investment Advice” website and author of “Real Investment Daily” blog and “Real Investment Report“. Follow Lance on Facebook, Twitter, Linked-In and YouTube Customer Relationship Summary (Form CRS)
Join RIA Advisors and elevate your career within a deeply experienced team focused on innovation. Our collaborative environment is built on a foundation of advanced technology and effective investment models, designed to enhance your ability to serve clients and grow your practice. Benefit from a supportive culture that encourages professional development and fosters a forward-thinking approach. By joining our team, you’ll be part of a group dedicated to excellence and continuous improvement, empowering you to focus on building meaningful client relationships and pursuing your business ambitions. Discover the advantages of working with our accomplished advisory team by starting your conversation today.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© Real Investment Advice
Read more commentaries by Real Investment Advice