KEY POINTS
The Bond Market Took the Wheel
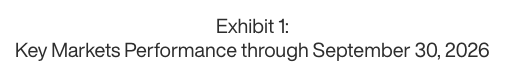
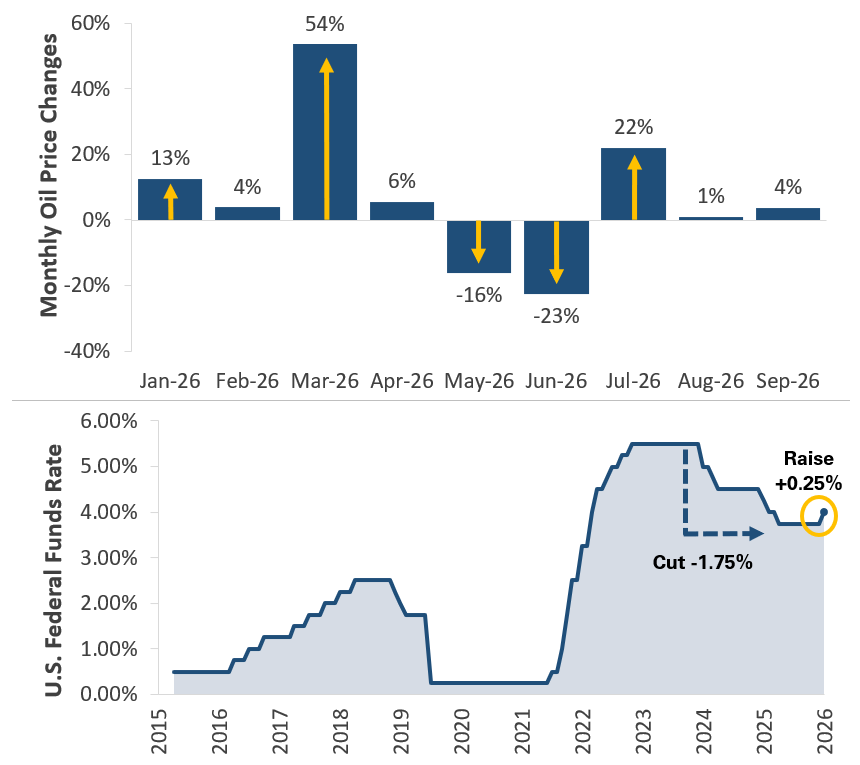
- Oil prices topped $100/bbl in September. Crude jumped 30% in Q3 amid supply concerns, and in our view remains the swing factor for future Fed rate hikes into year-end.
- The Fed hiked interest rates. The Fed’s first rate increase since 2023 came with a signal of one more, which suggests we are entering a “higher for longer” rate period (even if the Fed stops hiking).
- Yields soared as the 10yr Treasury moved above 5%. The 10-year Treasury closed above 5% for the first time since 2007, and across Treasuries, corporates and municipals, high-quality yields are the most attractive in over a decade.
- Market breadth narrowed (again). The S&P 500 set a record high, while small caps fell nearly 8% as diversification benefits dampened amid a shift back to the largest companies; we suggest holding diversification steady rather than chasing the leaders.
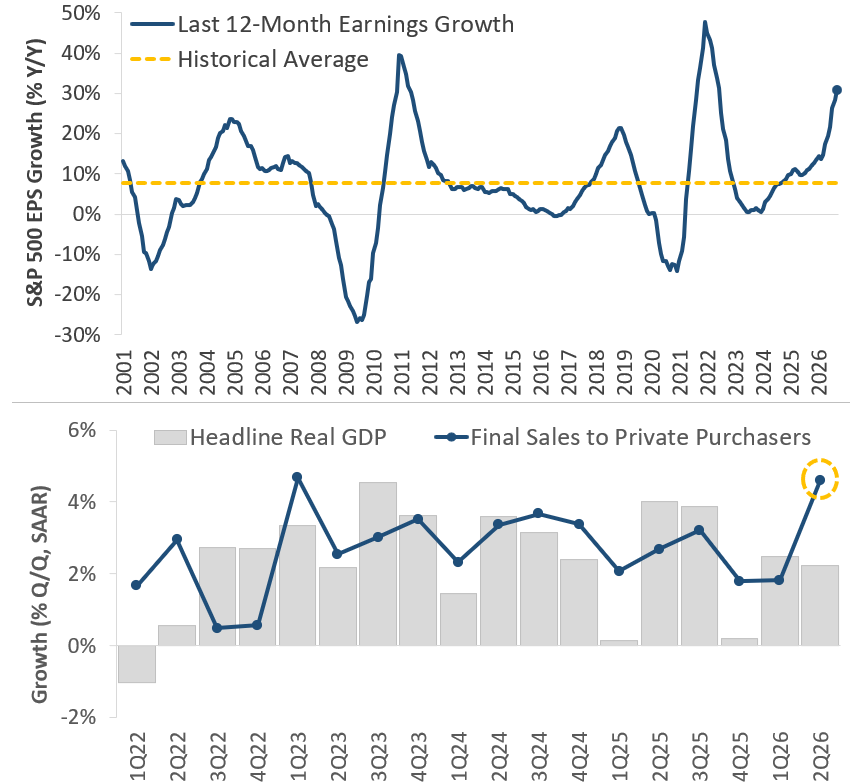
- Earnings delivered and remain the market’s backbone. S&P 500 profits are up nearly 30% over the past year, which has helped stocks largely absorb the impact of higher rates.
Rates and the Midterms Take Center Stage
This quarter was anything but normal. The broadening rally we highlighted in our Q2 2026 market recap narrowed once again, as volatility pushed investors back toward the safety of the market’s largest companies. Accelerating geopolitical uncertainty ahead of the midterms, combined with the ongoing fallout from the Iran War, kept investors on edge throughout the quarter. Oil prices remained volatile as the Strait of Hormuz continued to be largely closed, and crude crossed $100 again by mid-September, pushing the Federal Reserve to raise rates for the first time since July 2023.
For investors, what made this quarter even more unusual is where the pain showed up. In Q1 the oil shock hit stocks; in Q3 it hit bonds. The 10-year Treasury yield climbed from 4.4% to 5.3%, the broad bond market lost 3.5%, and municipal bonds fell 6.3%. These types of movements in portfolio “hedges” and “protection” are what test investors’ discipline around being “diversified,” as equity, despite all its volatility, remains up 12% on the year (while nearly all classes of fixed income are down).
See more: Economic/Market Commentary: 6 Charts We’re Watching in Q4 2026
In our view there is still plenty to be optimistic about. First, rates are rising on the back of a strong economy and an oil-driven bout of inflation – not because there is runaway inflation that we are trying to catch up to. Second, although painful now, we expect inflation will pass as energy prices (ultimately) normalize. And third, the economic strength underneath all the volatility and headlines looks durable as S&P 500 profits are growing, unemployment has held in a tight 4.1% – 4.3% range since March, and households and businesses are still spending.
And as a silver lining, the surge in yields has created a genuine opportunity for investors holding cash that need income: high-quality bonds now offer yields above 5% that can be locked in for years rather than reset every time the Fed moves (more on this in Timely Topics).
As we think about the final quarter of the year, there are two things on our minds.
- What happens to rates from here. The Fed signaled one more hike this year, but in our view the case for it is weaker than that signal suggests. Core inflation, which strips out food and energy, has held near 2.5%, which tells us most of the pressure is coming from oil rather than the broader economy. And as of this writing, the September jobs report showed hiring slowing sharply, with just 29,000 jobs added and July revised to a loss. We think the Fed is closer to the end of this hiking cycle than markets fear, with oil (i.e. Iran) as the deciding variable. If the Strait reopens and crude falls, we think the case for a second hike fades quickly.
- The midterm elections. On November 3, voters will decide control of the House and Senate, and we think this election carries more risk than markets are pricing. As of this writing, Democrats look poised to gain seats, though we’d describe it less as a “blue tide” and more of a blue undertow, with the gains coming from voters unhappy with the status quo and looking for change. History offers comfort to the optimists: since 1946 the S&P 500 has averaged a gain of roughly 16% in the six months following a midterm election, and going back to the late 1930s it has been higher 12 months later about 95% of the time.
Our approach heading into November and year-end reflects both outcomes. We are reviewing hedging strategies for a post-election environment, recognizing that hedges carry costs and tradeoffs and that any changes depend on each client’s circumstances and tolerance for risk. At the same time, we suggest using today’s yields to put excess cash to work in high-quality bonds, which pay a real income in either scenario. Longer term we remain constructive on equity markets, as earnings continue to deliver, but are cognizant that near-term rates and political risk will keep volatility elevated.
TIMELY TOPICS
The 10-Year Treasury Crosses 5%: What It Means for Bonds
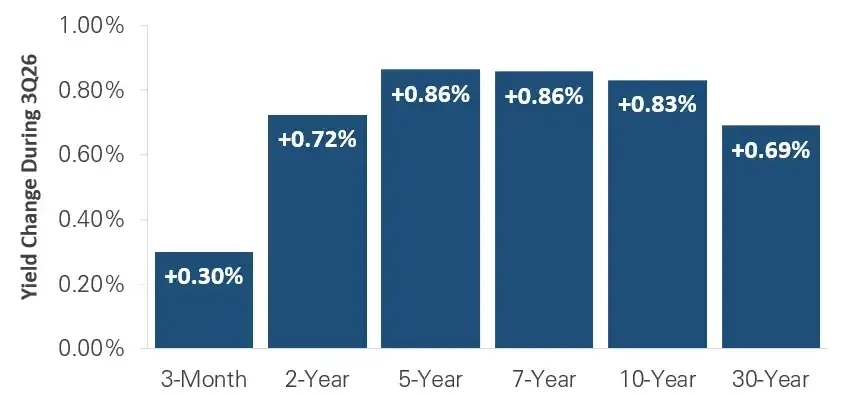
On September 25 the 10-year Treasury closed above 5% for the first time in 19 years. Yields rose across the entire curve, with the 5-, 7-, and 10-year each up more than 0.8%, right in the intermediate range most bond portfolios own. The drivers all pointed the same way: a strong economy, $100 oil, a hiking Fed, and federal debt that just passed $40 trillion.
While prices of fixed income went down, yields went up, and the broad bond aggregate now yields 5.6%. Cash has paid well too, but cash yields reset the moment the Fed changes direction, while a bond bought at 5% keeps paying 5% (until maturity). There’s also a timing angle: in a typical midterm cycle, Treasury yields have drifted lower in the months after the vote as policy uncertainty fades, which argues for locking in today’s levels rather than waiting.
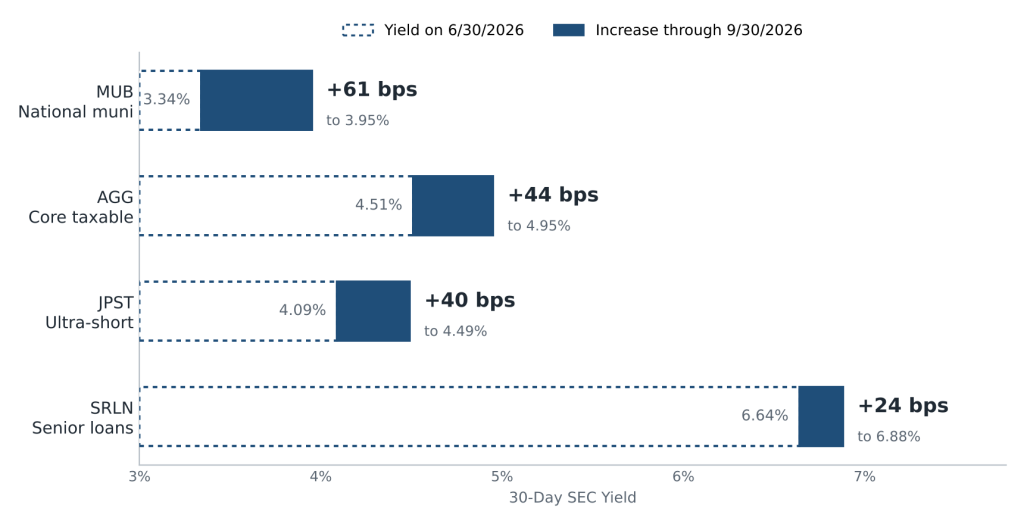
In the current environment we see the biggest opportunity in municipal bonds. Munis sold off harder than taxable bonds this quarter (-6.3% versus -3.5% for the Aggregate), which pushed their yields up faster (see Exhibit 5). The muni index now yields 4.5%, which works out to a tax-equivalent yield above 7.5% for investors in the top federal bracket, well above what taxable bonds of similar quality pay. For high earners holding bonds in taxable accounts, that is the most compelling after-tax income high-quality bonds have offered in years, and residents of high-tax states like California can add state tax savings on top through state-specific funds.
We suggest portfolios use this move rather than run from it, gradually extending excess cash into high-quality intermediate bonds, leaning on munis in taxable accounts, and staying selective in high-yield, where the weakest borrowers are already showing strain. It changes the equity math too. At 19.1x forward earnings, the S&P 500’s earnings yield of about 5.2% is now roughly level with the 10-year, which makes the bond allocation a genuine competitor for capital for the first time in a long while.
Q4 2026 Investment Outlook: What to Watch
The fourth quarter will likely bring more volatility as markets weigh the path of interest rates, the midterm elections, and the durability of corporate earnings. Yet underneath these uncertainties, the economic backdrop remains relatively resilient, and we continue to see opportunities across both equities and fixed income.
For investors, the opportunity created by higher bond yields may prove to be one of the more important developments of 2026. We favor selectively extending duration, emphasizing high-quality fixed income and tax-efficient municipal bonds where appropriate, while maintaining disciplined equity exposure and evaluating hedges around near-term risks.
If companies keep delivering through higher borrowing costs, we think the record highs will continue to be earned. But with a contested election a real possibility, we’d rather be prepared for both a sharp rally and a sharp drawdown than bet on either (see Stu Strasner’s recent piece on a Midterm Election Like No Other).
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Please read important Defiant Capital Group disclosures here.
© Defiant Capital Group
More Municipal Bonds Topics >