Where The Bears Are Right
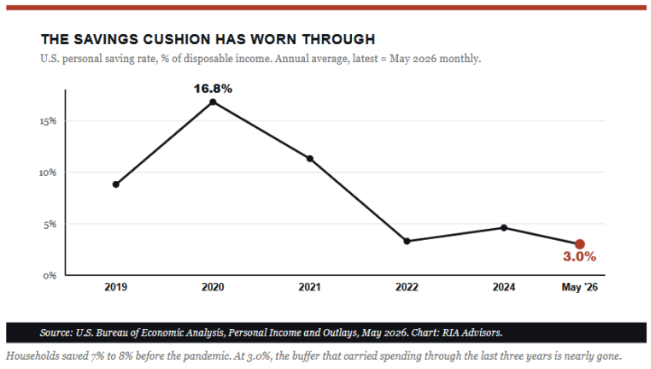
I readily admit that the bearish case has a valid point. They state that aggregate data lags current realities. Therefore, by the time the Fed’s quarterly report confirms a broad deterioration, the damage is already done. Furthermore, a 3.0% savings rate means the marginal household has no shock absorber left.
If you then layer on a labor market that ran soft through the summer, with June and July payrolls revised down to 31,000 and 21,000 before August rebounded to 162,000, you have the setup for spending to roll over faster than the smoothed data will admit.
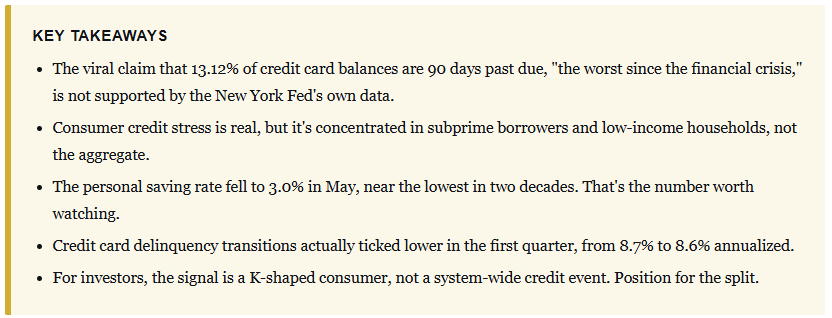
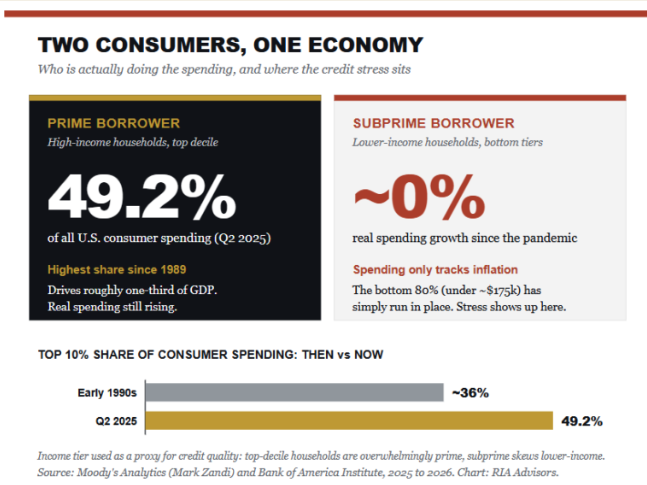
Those are all valid points. However, here’s the problem with treating it as today’s reality. It’s a forecast about tomorrow, not a reading of the current tape. The same case was made in 2023 and again in 2024. Each time, behavior beat feelings and spending held firm. I’m reasonably confident the low-end consumer market will continue to deteriorate from here. I’m far less confident it will drag down the aggregate over the next two quarters, because the prime borrower, who does most of the spending, is still in good shape.
What Consumer Credit Stress Means For Investors
So what do you actually do with this information?
- Stop trading off the scary screenshot. A K-shaped consumer calls for a scalpel, not a sledgehammer. The businesses exposed to the bottom third of the income distribution, dollar stores, subprime lenders, buy-now-pay-later names, and lower-end restaurants, are where the stress shows up first and hits margins hardest. That’s a real and specific risk you can underwrite.
- Respect the split rather than betting the whole book on one side. Higher-end consumer names and companies serving households with intact balance sheets are a different animal. Positioning for a total consumer collapse has been a losing trade for three years running. So has assuming everything is fine. The trade is the divergence itself.
- Lastly, keep the real watchlist in front of you. Not the meme number. Watch the savings rate, the subprime delinquency trend, the quarterly New York Fed report, and retailer margin guidance through earnings season. We covered the deeper split between what households say and what they do in our look at the consumer sentiment disconnect, and in the piece on record retail inflows. The through line is consistent. Behavior beats feelings, and primary data beats viral charts.
The bottom line is this. The consumer credit stress story deserves your attention, but only the true version. A 3% savings rate indicates the cushion is thin, and the low end is exposed. The New York Fed data tells you this is a distribution problem, not a solvency crisis, at least for now. The moment the prime borrower starts slipping in the quarterly print, the calculus changes, and that’s the number that will tell you when to lean out.
If this raises questions about how your own portfolio is positioned for a two-speed consumer and a softening labor market, that’s the conversation we have with investors every day. Our process starts with your complete financial picture, not just your investment account. Schedule a complimentary portfolio review, and let’s pressure-test your exposure together.
Questions This Article Answers
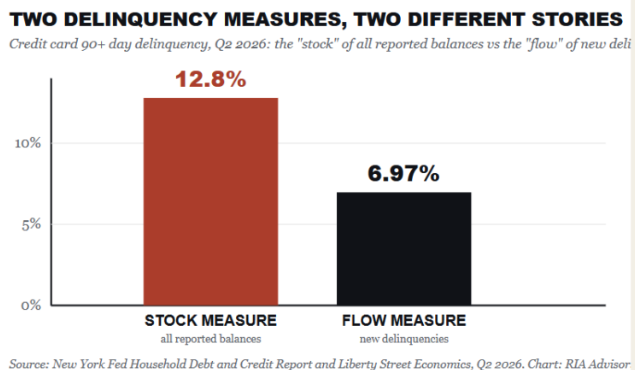
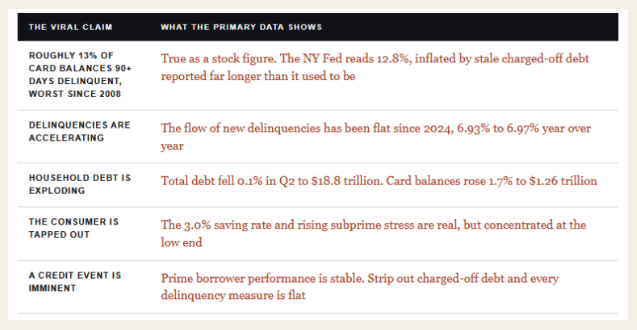
Are credit card delinquencies really the worst since 2008? Only by one measure. The New York Fed’s “stock” delinquency rate, which counts all reported balances 90+ days past due, hit 12.8% in Q2 2026. That measure is inflated by old charged-off debt that lenders now report for far longer. The “flow” of new delinquencies, a better read on current stress, has been roughly flat since 2024 at just under 7%.
What’s the difference between stock and flow delinquency? The stock measure is the share of all outstanding balances currently marked delinquent, including stale charged-off debt. The flow measure is the amount of debt that goes bad each quarter. The flow tells you how households are doing right now, and the Fed’s own economists say it’s the more accurate gauge of current repayment behavior.
Is the U.S. consumer actually in trouble? Part of it. The stress is concentrated in subprime and lower-income households, where the 3.0% saving rate leaves no cushion. Prime borrowers, who account for most spending, are still in good shape. It’s a K-shaped consumer, not a system-wide credit event.
What should investors watch instead of the viral chart? The flow delinquency rate, the subprime delinquency trend, the quarterly New York Fed report, the personal saving rate, and retailer margin guidance. Those tell you when the stress is spreading from the low end into the prime borrower, which is the turn that actually matters for portfolios.
Sources
- New York Fed. Household Debt and Credit Report, Q2 2026, released August 11, 2026.
- New York Fed Liberty Street Economics. “How Distressed Are Consumers? Reconciling Diverging Credit Card Delinquency Measures,” Lee, Mangrum, Scally, Sinha, and van der Klaauw, August 11, 2026.
- U.S. Bureau of Economic Analysis. Personal Income and Outlays, July 2026, released August 26, 2026.
- U.S. Bureau of Labor Statistics. Employment Situation, August 2026, released September 4, 2026.
- Moody’s Analytics (Mark Zandi). Consumer spending by income cohort, Q2 2025, as reported by Bloomberg, September 16, 2025. Note: Some economists have since questioned whether the 49.2% figure overstates the concentration.
- Bank of America Institute. Consumer Checkpoint, 2026 monthly releases.
Lance Roberts is a Chief Portfolio Strategist/Economist for RIA Advisors. He is also the host of “The Lance Roberts Podcast” and Chief Editor of the “Real Investment Advice” website and author of “Real Investment Daily” blog and “Real Investment Report“. Follow Lance on Facebook, Twitter, Linked-In and YouTube Customer Relationship Summary (Form CRS)
Join RIA Advisors and elevate your career within a deeply experienced team focused on innovation. Our collaborative environment is built on a foundation of advanced technology and effective investment models, designed to enhance your ability to serve clients and grow your practice. Benefit from a supportive culture that encourages professional development and fosters a forward-thinking approach. By joining our team, you’ll be part of a group dedicated to excellence and continuous improvement, empowering you to focus on building meaningful client relationships and pursuing your business ambitions. Discover the advantages of working with our accomplished advisory team by starting your conversation today.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.










