FOURTH QUARTER 2026 ASSET ALLOCATION OUTLOOK
- We expect no recession over our three-year forecast period, with near-trend GDP growth.
- Economic growth continues to be driven by business investment.
- Inflation will likely remain above the Fed’s long-term target but without further acceleration.
- We expect a cautious Federal Reserve, with inflation limiting the pace and magnitude of future policy easing.
- Geopolitical tensions will remain elevated, contributing to periodic market volatility.
- Elevated valuations among select mega-cap companies, alongside improving earnings prospects across broader segments of the market, should encourage a gradual rotation toward a wider set of equity leaders.
- International developed market equities remain and we introduce allocations to domestic small and mid-caps, given our expectations for a broadening market.
- Gold continues to serve a diversification role in the portfolios.
See more: Your Clients Don’t Want a Market Update. They Want to Know You.
ECONOMIC VIEWPOINTS
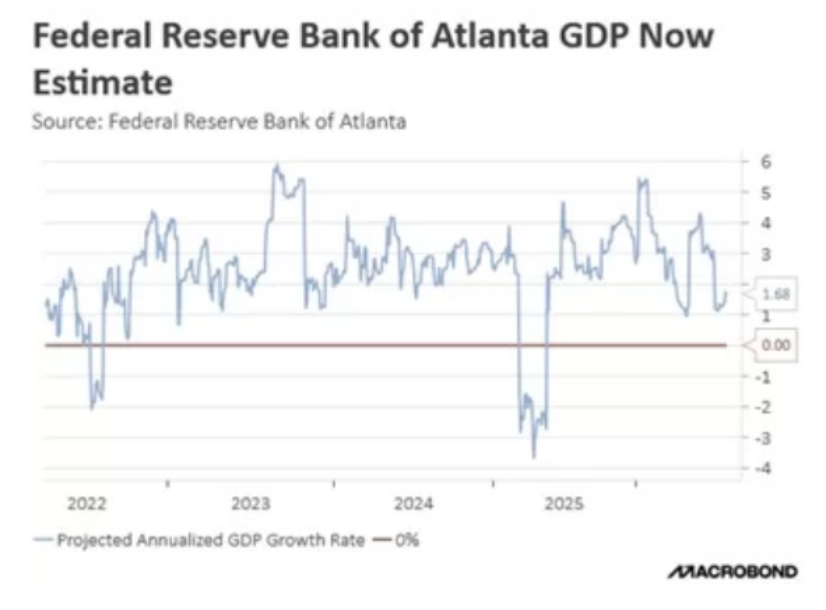
The economy appears to be settling into a new equilibrium. Economic growth has moderated to a sustainable pace. While inflation has picked up over the last few months, there does not seem to be a fundamental shift in the underlying trend. At the same time, monetary policy remains in neutral to restrictive territory. Against this backdrop, our base case continues to call for moderate economic growth over our three-year forecast period. While the pace of expansion has slowed from the exceptionally strong growth experienced earlier in the cycle, the US economy remains structurally sound. Business investment remains supported by secular themes including artificial intelligence (AI), infrastructure investment, and domestic manufacturing, while consumer spending remains positive, albeit pressured among lower-income cohorts. The Atlanta Federal Reserve’s GDPNow estimate continues to point toward positive economic growth, reinforcing our expectation that the economy is expanding at a pace closer to its long-term trend.
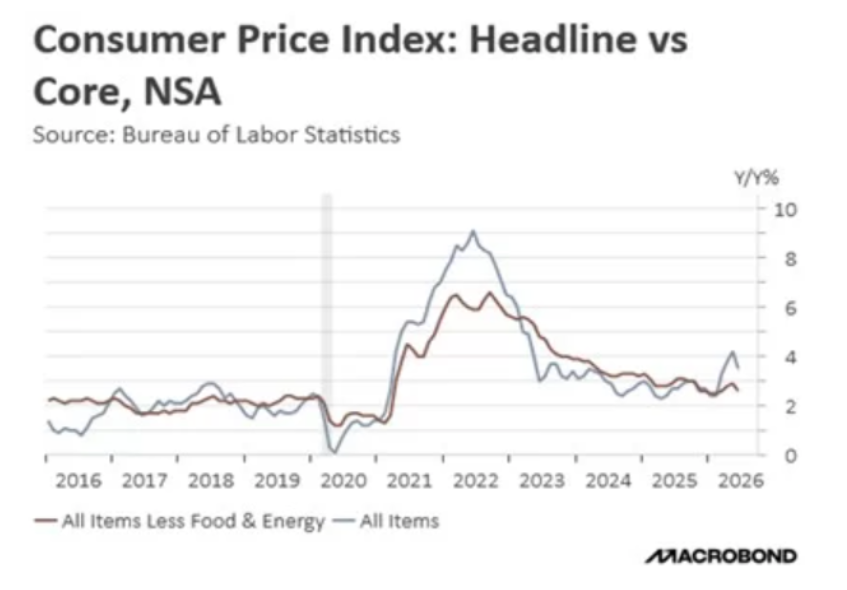
Inflation has moderated substantially from the highs reached in 2022, but we believe further progress toward the Fed’s target will become more difficult, and we expect inflation to stabilize in a range of approximately 2.5% to 3.5% over the next three years. Ongoing factors such as persistent fiscal deficits, supply chain reconfiguration, and elevated geopolitical uncertainty are likely to keep underlying inflation above the Fed’s 2% target. While we do not expect inflation to accelerate significantly from its current trend, we acknowledge that ongoing wars and tariff uncertainty may result in short-term spikes in inflation.
STOCK MARKET OUTLOOK
Over the past several years, equity market returns have become increasingly concentrated among a handful of mega-cap technology companies, largely reflecting investor enthusiasm surrounding AI and its transformative potential. We still expect that AI will remain a powerful driver of long-term productivity and corporate profitability; however, we also believe the market has already capitalized much of AI’s future value into a narrow group of companies, leaving less room for future valuation expansion. As AI-related investment translates into broader capital spending, productivity improvements, and corporate earnings across the economy, we expect market leadership to widen beyond its current concentration. We’re already seeing this broadening underway as the equal-weighted S&P 500 outperformed the cap-weighted index by over 400 bps YTD (13.4% vs. 9.3%, respectively). We are not signaling the end of the AI theme, rather we anticipate the next phase of the cycle will be characterized by broader participation across sectors, market capitalizations, and investment styles, creating a more favorable environment for diversified portfolios.
Our equity positioning reflects this forecast as we added to small and mid-cap equities, where risk appropriate, but also remain constructive on US large caps. Given our market rotation expectations, our lower-risk portfolios take on a heavier value tilt, while higher-risk portfolios are more evenly balanced between growth and value. Sector positioning remains focused on areas we believe are supported by long-term secular trends and attractive valuations. We continue to favor energy and industrial companies, both of which stand to benefit from ongoing infrastructure investment, domestic manufacturing, reshoring initiatives, and increasing capital expenditures. This quarter, we replaced our Aerospace & Defense holding with one that uses an equal-weighted methodology, which we believe offers greater participation in rising global defense spending, commercial aerospace demand, and supply chain investment, while reducing concentration risk in the largest market cap companies. We continue to hold dividend-oriented ETFs as dividend income can serve as a reliable cushion in the higher-volatility environment we are forecasting. Within small and mid-caps, we focus on holdings with a quality or dividend focus.
The longer-term trends of a polarizing world and US dollar softness could support foreign investments by encouraging capital diversification and enhancing returns on overseas assets for US-based investors. Foreign investments may also benefit from more attractive relative valuations, improving earnings breadth, stronger fiscal and industrial policy support abroad, and the potential for capital to rotate away from highly concentrated US markets. Our international developed market exposure includes a broad-based holding plus several targeted positions. We continue to hold positions in global metals & miners, international small cap value, and separate Europe and Asia-Pacific-focused ETFs. This quarter, we exited the standalone position in gold miners as these equities typically exhibit higher volatility than physical gold. In the Aggressive Growth portfolio, we also initiated a small allocation to emerging markets. Although emerging markets continue to face geopolitical and policy risks, we believe improving global manufacturing activity, attractive relative valuations, favorable long-term demographic trends, and the potential for a weaker US dollar over our forecast horizon create an attractive opportunity for long-term investors.
BOND MARKET OUTLOOK
The current fixed income environment presents a more balanced opportunity set and may offer meaningful income while providing diversification benefits during equity market volatility. Rather than relying primarily on falling interest rates to generate returns, we believe investors can benefit from today’s attractive starting yields, allowing a greater share of total return to come from income over price appreciation. This reinforces our preference for high-quality fixed income as a core portfolio allocation, with a measured approach to interest rate risk. We expect the yield curve to remain positively sloped, with the potential for some flattening if tighter monetary policy pushes short-term yields higher, while longer-term yields remain anchored by growth expectations.
We have modestly increased exposure to shorter maturities, positioning the portfolios to benefit from current higher yields while preserving flexibility should interest rates or credit conditions evolve differently than expected. We continue to favor sectors that offer attractive risk-adjusted return potential without significant exposure to credit risk. We maintain overweight allocations to US Treasurys and agency mortgage-backed securities (MBS), where valuations remain attractive. MBS continue to offer compelling income opportunities, supported by favorable cash flow characteristics and limited extension risk. We remain cautious toward investment-grade corporate bonds despite their recent strong performance. Credit spreads continue to trade near historically tight levels, offering limited compensation for assuming additional credit risk, while elevated issuance — particularly from companies financing AI and other large-scale capital investment — could put upward pressure on spreads over time.
OTHER MARKETS
We retain gold across all strategies, though we’ve modestly reduced our allocations. Despite the decline in gold prices, we continue to view gold as an effective store of value and a hedge against inflation, geopolitical uncertainty, and currency diversification. This recent pullback is likely due to a combination of profit taking and anticipation of rising interest rates with investors seeking investments with higher yields. Over our three-year forecast period, we expect foreign central banks to continue diversifying a portion of their reserves away from the US dollar and into gold, providing ongoing support for the asset class. We exited our platinum position during the quarter, reallocating capital to equity markets where we believe the expected risk-adjusted return opportunity is more attractive.
For more news, information, and analysis, visit the ETF Strategist Content Hub.
Read the full report
Asset Allocation Fact Sheet
Originally posted on ETF Trends
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
These reports were prepared by Confluence Investment Management LLC and reflect the current opinion of the authors. Opinions expressed are current as of the date shown and are based upon sources and data believed to be accurate and reliable. Opinions and forward-looking statements expressed are subject to change. This is not a solicitation or an offer to buy or sell any security. Past performance is no guarantee of future results. Information provided in this report is for educational and illustrative purposes only and should not be construed as individualized investment advice or a recommendation. Investments or strategies discussed may not be suitable for all investors. Investors must make their own decisions based on their specific investment objectives and financial circumstances.
© Confluence Investment Management
More Asian/European Markets Topics >