Q3 2026: Borrowing From the Future
Membership required
Membership is now required to use this feature. To learn more:
View Membership Benefits
Key Takeaways
- The future economy now sets the price of money. AI capital spending, government borrowing, and today’s economy draw on one pool of savings. This quarter the largest borrower got its way and everyone else paid more.
- Gains were narrow and losses were broad. The 10-year rose 85 basis points in a steady, unanticipated trend. A handful of AI companies carried the indices; most stocks and every bond category fell.
- The AI buildout is a capitalist trap. Every participant is acting rationally and none can stop. Traps like this end in a bust or in regulation.
- The Fed’s dual mandate is also the electorate’s. Inflation hurts everyone; marginal growth helps a few.
- Conservative portfolios had the hardest quarter but are better positioned. Rising rates did the damage; yields above 5% are now the base for forward returns.
Executive Summary: One Price for Money
Narratives are almost always wrong: clever stories that explain the past and say nothing about the future. One may be right. AI may become the dominant technology of the century and render much of the present economy obsolete. We said last quarter that this is the most future-weighted market in history. This quarter the future showed up in the price of money.
Read more: 2 Fixed Income Solutions for Navigating Bond Instability
There is one market for capital, with rates set globally – a Texas data center, a Treasury auction, and a French mortgage compete for lenders. When a borrower large enough to matter believes its project will return far more than any cost of capital, everyone else pays more. Hyperscaler spending is approaching $1 trillion per year and still accelerating, financed increasingly in the bond market, while Treasury borrowing runs near six percent of GDP. The 10-year yield rose 85 basis points to 5.29%, the largest quarterly increase since 1994, mostly in real yields. The future economy is setting the cost of capital for today’s economy with little input from today’s economy.
Stocks absorbed it because earnings rose faster than prices – one of the most positive market indicators for the quarter. However, the gains belonged to a few AI companies as most stocks were flat or down and every bond category fell. Broadly bad and narrowly great, with surging yields, is the hardest environment for a diversified investor, and the conservative investor’s dilemma we have described for three years played out.
Market Performance: Broadly Bad, Narrowly Great
The story of the quarter is fixed income. Equities were mildly positive in most regions; bonds were negative everywhere, with the losses concentrated where investors keep the money they cannot afford to lose.
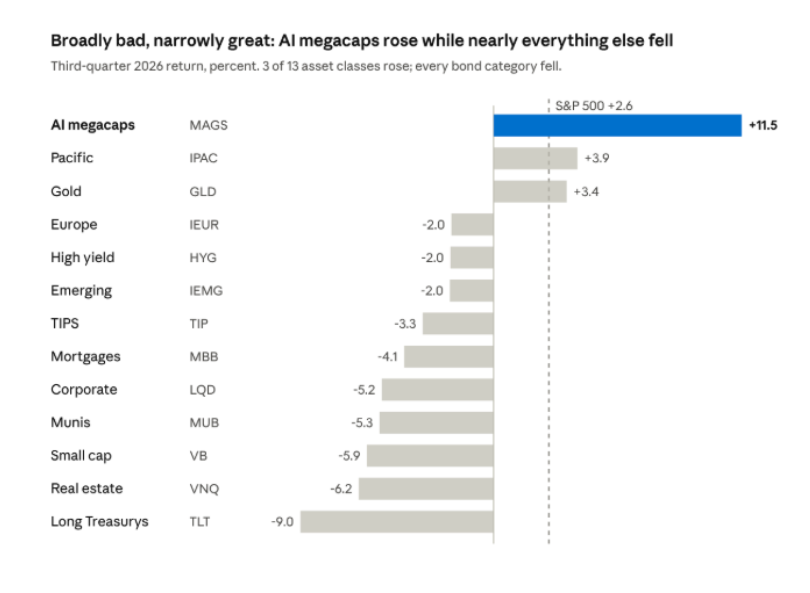

The yield curve underwent a major shift upwards. The 2-year by 74 basis points to 4.88%, the 10-year by 85 to 5.29% (crossing 5% for the first time since 2007) and the 30-year to 5.6%, a level last seen in 2002. Long Treasurys lost the most. Investment-grade credit did worse than Treasurys as spreads grew while high yield held up better on higher income and lower rate sensitivity. Municipals underperformed taxable bonds longer duration compounded with additional pressure on yields from record September issuance. Notably, these shifts were not accompanied by significant volatility – yields rose steadily all quarter, a trend rather than a shock.
Global equities gained 1.3% and the S&P 500 2.3%, but the gains were narrower than the headline. U.S. mega-cap technology stocks returned 11.5% on AI-related earnings; large-cap value was flat; small caps declined. Energy led as oil moved back above $100; utilities fell with every other long-duration asset. Pacific equities gained 3.9% on Japan. Europe and emerging markets each declined about 2%; within emerging markets, China’s large technology companies fell while domestic A-shares rose. The U.S. market’s split, AI against everything else, now runs through every region.
Diversifiers were the quarter’s other story. Gold gained 3.5%, managed futures gained nearly 13%, market-neutral strategies more than 7%, and bitcoin rose sharply, while REITs, the private-equity proxies, and momentum did not help. Alternatives built to be different from the core market such as the first three were positive; those that resemble markets in a different wrapper were not.
Economic Insights
Two AI Risks, Not One
The first AI risk is direct: investors own claims on a technology whose future profitability remains uncertain. That exposure extends beyond technology stocks into semiconductor-producing countries, utilities, and real estate. This is best thought of as a new risk factor with pervasive exposure among stocks and markets.
The second is capital displacement. A large new source of investment demand can raise financing costs for unrelated businesses. The buildout competes for power, land, construction, and specialized labor. These costs arise before AI replaces a worker or disrupts a business. Avoiding AI stocks does not avoid them.
This helps explain how AI-linked equities and rates can rise together. A company expecting unusually high returns may continue investing at higher borrowing costs while businesses with more modest opportunities postpone expansion. AI’s share of investment can increase even if higher rates slow its own spending, as other industries cannot afford the cost of capital.
The effects differ across regions and businesses. Parts of Europe, smaller companies, and REITs may face higher costs without higher revenues. But the division need not persist as companies outside the infrastructure race can adopt AI and benefit from cheaper technology later. Building the future and using it are different investments.
Keynes and the Competition for Capital
Keynes’s prescription for government borrowing was simple: borrow and spend when private demand is weak, step back when it is strong. Governments follow the first half but rarely the second. Today, there is substantial investment on both sides with the two largest pools of capital demand the world has known are bidding at once – technology companies backed by seemingly limitless private capital, and a U.S. government issuing debt at a record pace. Keynes would advise government restraint. That fight dislocates the ordinary workings of the economy and is why real yields accounted for over 80% of the yield increase in a quarter and why Europe and small caps fell while the AI market rose.
The late-1990s internet buildout coincided with federal surpluses. This was largely serendipitous, but the internet was built without having to outbid the Treasury for capital (arguably some pain would have been avoided with a higher cost of capital for some dot-coms). The AI buildout is the first modern technology boom that has to compete with government spending.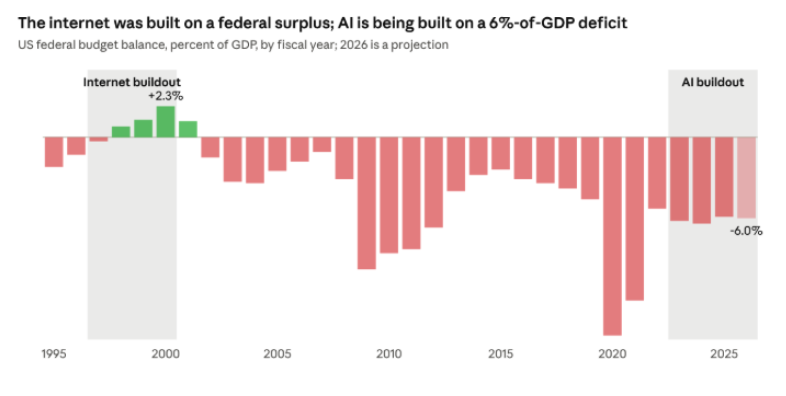
The Capitalist Trap
The AI buildout is a capitalist trap: every participant is behaving rationally, but every participant would be better off acting differently, but can’t due to competition.
Large tech firms (e.g. Google) were faced with the choice of spending billions on AI solutions, or watch AI erode its core business. They hand other firms (e.g. Nvidia) a large share of their free cash flow at prices inflated by their own competition. The model labs (e.g. Anthropic) are one level down in the same trap: a lab that stops training loses share to one that does not, so every lab spends everything on an endless race. The lenders are trapped too. More than $200 billion of long-term debt has been issued this year for data centers. Skeptical lenders are outbid and left lending at lower rates, so the marginal cost of capital is set by the most optimistic lender. Even nations and investors are in it: neither the United States nor China can let the other win, and a manager who owns too little AI risks losing clients.
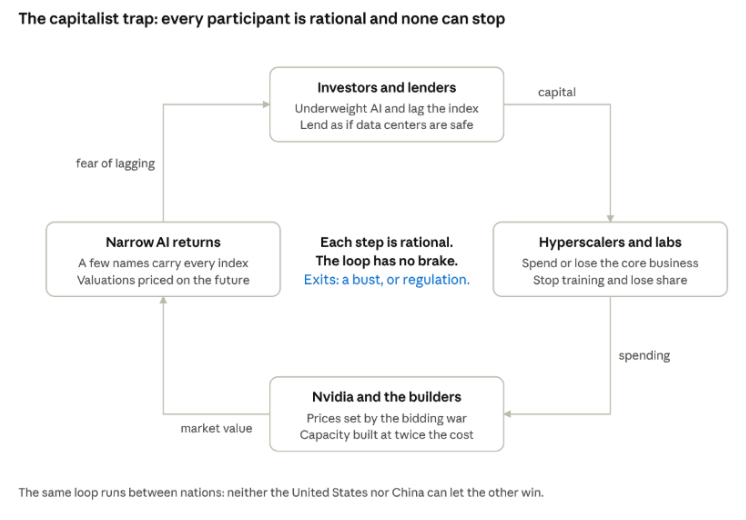
The trap is dangerous because competition for scarce resources massively inflates buildout cost. A house built when construction costs are too high loses value when costs normalize, because a more modern house can then be built for less. The market is rewarding unusually inefficient investment, and a latecomer buying capacity at normal prices could surpass the early participants who overpaid. If model progress plateaus, a cheaply financed lab with a nearly-as-good model could take the inference business from the labs that spent trillions and their market cap with it. Capitalist traps end in a bust or in regulation, and there is little will to regulate this one. That leaves the bust, or the possibility perennially promised “this time is different.” A long-term portfolio needs to be built for either outcome.
The Fed’s Mandate Is the Voters’ Mandate
It is hard to predict an election (and the market implications of the outcome are uncertain), so we rely on markets for information. Notably, prediction markets show a significant probability of a change of control in Congress. The primary reason is prices, with gasoline particularly visible. Against that backdrop the Federal Reserve raised rates a quarter point in September, to 3.75% to 4.00%, its first increase in three years, with headline CPI at 3.4% and core CPI at 2.4%. Challengingly, the Fed’s true fight is more with inflation expectations than core inflation.
The Fed’s dual mandate is also the politicians’ mandate. Anyone who wants to stay in office needs a healthy economy, but voters are still angry about prices. Inflation hurts everyone while incremental growth helps a few. By focusing on inflation the Fed is doing its job and, as it happens, what the electorate wants. This may explain why the administration has grown quieter about rates. This Fed is more willing to raise than expected, more transparent than feared, and succinct but not silent. Therefore, the dawning understanding of the Fed is one reason the rise in rates was extraordinary but orderly. It also confirms a regime – before the pandemic, shocks were deflationary and bonds were free insurance. Now the shocks are inflationary, AI adds structural price pressure, and investors must find more costly insurance elsewhere.
Market Insights
A Few Stocks Often Drive the Market
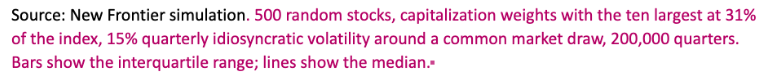
Many quarters evoke a narrative where a handful of stocks account for most of the market return. But this is merely arithmetic and will always be true when the market return is near zero. An index return is a net figure: many stocks rise, many fall, most cancel, and a small residual remains. When the net return is small, its few largest contributors will always appear to explain most of it. If the S&P 500 returns 2.3% and the top ten contributors add to 4%, they “explained” 170% of the return, even if the 500 returns were random numbers. In a simulation of 500 random stocks with today’s weights, the ten largest contributors to a 2 to 3% quarter explain about 120% of it on average.
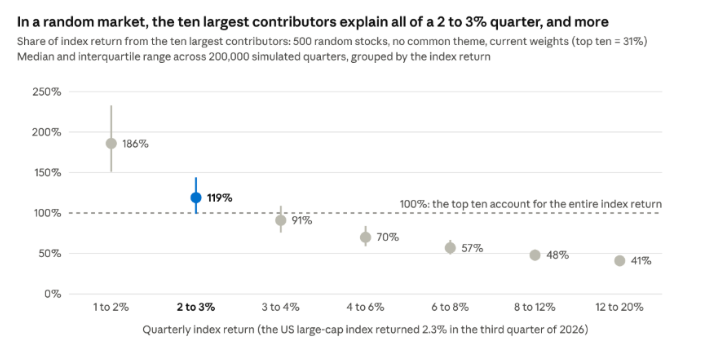
What is genuinely different now: the largest companies are enormous and move together, so their weight and correlation drive the market; and the winners share a theme a person can name (AI). A highly concentrated market driven primarily by a single factor challenges investors by distracting them from long-term risks and drivers of return.
Two Markets, One Company
The stock and bond markets price the same companies, and recently they disagree. In the bond market the relationship between risk and return is intact: small risky companies pay wide credit spreads and the largest pay little above Treasurys. The stock market differs: the large companies the bond market treats as safest have delivered the highest returns, and the companies it charges the most have delivered the least, even after adjusting for leverage. One hypothesis is causal where cheap debt lets giants grow, while costly credit slows others. The alternative hypothesis is stock and bond investors think about risk differently, and the two markets can carry opposite risk premia for a long time before one is proved wrong. A risk exists because corporate credit has been calm for years but if borrowing costs rise far enough to break the AI buildout, capital runs back to Treasurys and the damage lands on credit, and spreads show no concern about that at all.
What We Learned About Alts
For a core portfolio, alternatives need be less correlated to the economy and to core markets, but many popular “alts” are not. Illiquidity does not make a core asset an alternative – private equity and credit have the same economic exposure as their liquid cousins and a non-traded REIT priced once a quarter is the same asset with less liquidity. The quarter identified alternatives that are structurally different: managed futures, market-neutral strategies, gold, and bitcoin. While alts can’t guarantee return any more than other assets, they managed to offer return in a quarter when bonds offered no protection.
China
The case for China is unchanged and uncomfortable. Chinese labs produce open-source models nearly as good as the frontier at a fraction of the cost, and China may earn returns comparable to the U.S. at a lower price. The counterargument is one of our oldest themes – investors may not always capture economic growth. Examples abound – BYD dominates electric vehicles without a trillion-dollar valuation while Foxconn builds the iPhone and Apple keeps the margin.
China also faces a choice it did not want. With a slowing domestic economy and a shock to global oil supply, China is forced to reduce consumption to prevent economic slowdowns in the economies of international markets it relies on. China has little option but to be the benefactor, importing less oil, exporting cheap goods, cheap models, and capital. Ironically, China’s managed economy cannot escape a capitalist trap.
Europe
Europe has faced the secondary costs of the AI investment boom without capturing comparable benefits. High external borrowing costs have added to fiscal pressures, with ECB rate hikes and higher French government bond yields highlighting vulnerabilities from elevated debt and weak growth. Unlike the US, Europe lacks AI investment to boost growth.
Over time, however, AI’s economic benefits may shift beyond model providers toward businesses adopting AI to improve productivity and profitability. This diffusion could favor Europe’s rich, diversified economy, allowing it to capture more of AI’s economic value without leading the infrastructure buildout. Today, exposure to diversified European corporate credit may compensate for lower expectations of European equities.
Look Ahead
We do not forecast, but portfolios have to evolve with the environment. The cost of capital is being set by the future economy and is a risk to be managed, with yield picked up where it is relatively cheap, and with the stock-bond covariance treated with caution. Cash and short Treasurys, floating-rate notes, covered-call income, and a few alternatives are earning places in portfolios that for a decade had no use for them.
The other risk is uncertainty itself. Risks are always present, but today’s risks are unusually weighted in the future, dependent on how the AI economy will play out. Conventional investing is not going away. Today’s economy still has to feed, house, power, insure, and transport everyone, and the companies that do it are cheaper than a year ago. For conservative investors the quarter was painful, but the starting point is promising with yields above 5% as the basis for forward bond returns.
The surprise that would matter is a plateau in model progress, which would turn the capitalist trap into a repricing of the market. Long term portfolios need to survive this scenario.
Conclusion
The third quarter was the one in which the future economy stopped being an abstraction and started setting prices. AI capital spending bid up the cost of money, governments kept borrowing, and bonds delivered the largest losses. Stocks absorbed it thanks to extraordinary earnings, and a handful of companies carried the indices while the median stock fell.
The narratives will change by next quarter; the mechanics will not. There is one price for money, and the future is setting it. Our job is not to guess the future, but to own enough of the future to participate in it, and enough of the present to not depend on an unknown future.
For more news, information, and analysis, visit the ETF Strategist Content Hub.
Originally posted on ETF Trends
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Disclosures
New Frontier Advisors LLC (“New Frontier”) is a federally registered investment adviser based in Boston, MA. This content is intended solely for the use of investment professionals and should not be distributed or relied upon by retail investors or the general public. It is provided for informational and discussion purposes only and does not constitute an offer, solicitation, or recommendation to buy or sell any security or engage in any investment strategy. This commentary is not intended for use as a primary basis for investment decisions and is not intended to meet the objectives or suitability requirements of any particular investor.
The information presented in this commentary is believed to be accurate at the time of publication but may be subject to change without notice. No representation or warranty is made as to its continued accuracy or completeness. The investment adviser has no obligation to update this commentary to reflect changes after the date of publication.
Any forward-looking statements or projections are based on current assumptions and expectations and are subject to known and unknown risks and uncertainties. Past performance is not indicative of future results, and investing involves risks, including the potential loss of principal. Diversification may not protect against market risk. Before investing in any investment portfolio, the investor and Financial Advisor should carefully consider the investor’s investment objectives, time horizon, risk tolerance, and fees.
Past performance does not guarantee future results. As market conditions fluctuate, the investment return and principal value of any investment will change. Diversification may not protect against market risk. There are risks involved with investing, including possible loss of principal. Financial instruments discussed here may not be suitable for all investors.
For Investment Professionals Only.
Membership required
Membership is now required to use this feature. To learn more:
View Membership Benefits