The Federal Reserve’s recent decision to raise its benchmark interest rate may prompt investors to review not only their portfolios, but also their long-term financial plans. Because many financial planning strategies are influenced by IRS-published interest rates, changes in rates can affect the relative attractiveness of certain strategies. In this higher interest-rate environment, investors may want to consider several planning opportunities that could help support their broader financial goals.
These are the two key IRS interest rates that influence financial planning:
Applicable Federal Rate (AFR). The IRS publishes three applicable federal rates each month: a short-term rate of up to three years, a mid-term rate of more than three years and up to nine years and a long-term rate for loans exceeding nine years. These are based on average market yields for US Treasury securities of comparable maturities.
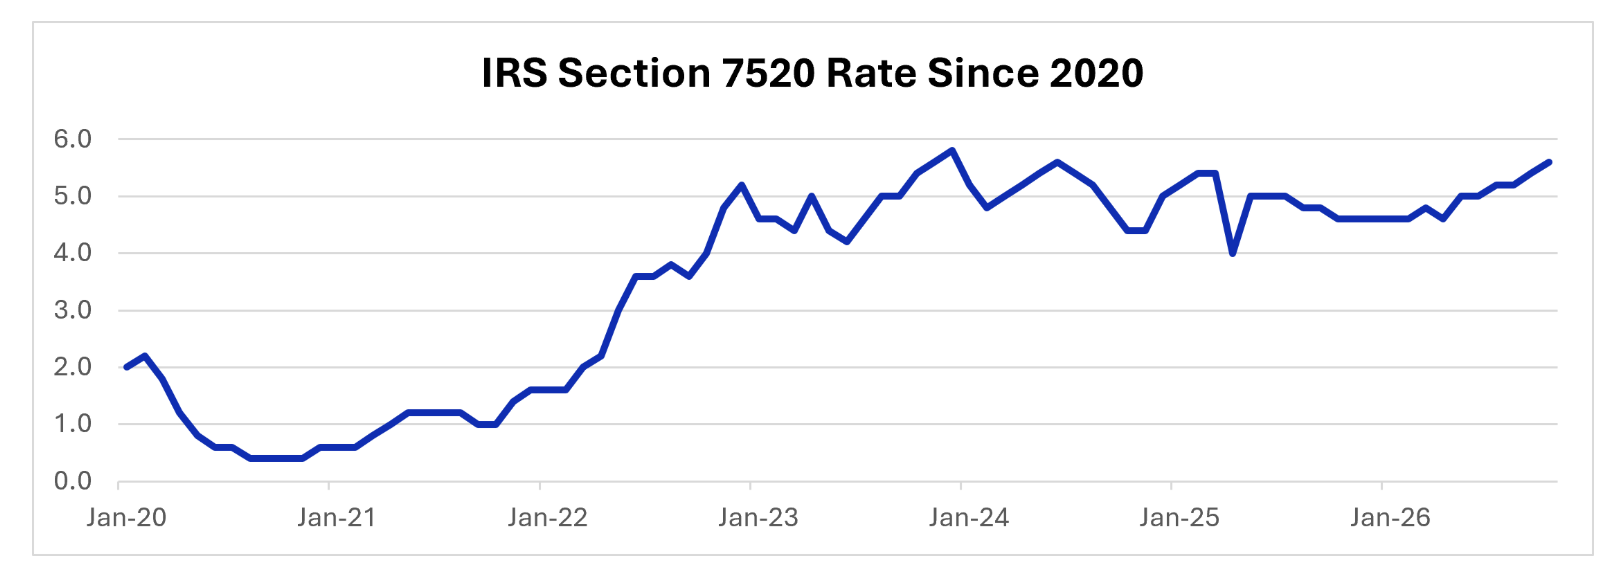
IRS Section 7520 rate. Published monthly, this rate is equivalent to 120% of the applicable federal mid-term rate, rounded to the nearest two-tenths of 1%. The rate is often referred to as the “discount” or “hurdle” rate for determining the value of certain property interests in split-interest trusts, including charitable trusts and Grantor Retained Annuity Trusts (GRATs).1 As of October 2026, the 7520 rate is 5.6%.
See more: Anatomy of the Private Credit Market
Interest rates can have a significant impact on the outcome of certain financial planning strategies. Consider the impact of rising interest rates on a Grantor Retained Annuity Trust (GRAT). Over the trust term, the grantor receives annuity payments based on the value of the assets initially transferred to the trust and the applicable IRS Section 7520 rate. At the end of the term, any remaining assets that have appreciated beyond the 7520 rate (referred to as the “hurdle rate”) can pass to the beneficiaries with little or no federal gift and estate taxes. When structured properly, a GRAT can be an effective wealth transfer technique. However, the amount of wealth ultimately transferred can vary dramatically depending on the prevailing interest rate. Consider this hypothetical example:
- GRAT is funded with $2 million in assets
- Assets within the trust grow at an annualized growth rate of 8%
- The GRAT term is three years
- Following the end of the GRAT term, the amount of wealth transferred to heirs through the GRAT strategy will differ depending on the IRS Section 7520 interest rate
2% IRS Section 7520 rate = roughly $268,000 transferred to heirs
4% IRS Section 7520 rate = roughly $180,000 transferred to heirs
6% IRS Section 7520 rate = roughly $90,000 transferred to heirs
Source: Franklin Templeton research. Hypothetical example for illustrative purposes only. Actual results will vary based on investment performance, trust structure, prevailing interest rates and other factors.
A GRAT is an example of a planning strategy that generally becomes more favorable when IRS Section 7520 rates are lower. Conversely, other financial planning strategies may become more attractive in a higher-interest rate environment.
Strategies to Consider as Interest Rates Increase:
Charitable Remainder Trust (CRT). With a CRT, the donor or other noncharitable beneficiaries, such as heirs, receive payments from the trust for a specified period or for life. Any remaining assets are ultimately distributed to the charitable organization. Because the IRS Section 7520 rate is used for calculating the present value of the charitable remainder interest, a higher rate can generally result in a larger charitable income tax deduction, assuming other factors remain unchanged.
Qualified Personal Residence Trust (QPRT). This strategy allows an individual to transfer a residence to an irrevocable trust while retaining the right to live in the home for a specified term. At the end of the trust term, the residence passes to the beneficiaries, typically outside of the grantor’s taxable estate, assuming the grantor survives the length of the trust term. Transferring the residence into the trust results in a taxable gift, albeit reduced since the individual retains the right to live in the residence for a length of time. Because the prevailing IRS Section 7520 rate is used to determine the value of the retained interest in the residence, higher rates will generally result in a lower taxable gift when the QPRT is established.
Tax-loss bond swap strategy. Investors who own bonds in taxable accounts may consider exchanging existing holdings for newer, higher-yielding bonds as interest rates rise. If the original bonds have declined in value, selling them may generate a capital loss that could potentially be used to offset capital gains elsewhere in the portfolio. The strategy may also be implemented using mutual funds or ETFs that hold bonds, although investors should carefully consider the underlying holdings and investment objectives before proceeding. Investors should also be mindful of the tax wash-sale rules when implementing a tax-loss bond swap. The replacement investment should not be substantially identical to the security sold, which may be achieved by selecting bonds with different issuers, coupons, maturities or other characteristics. Because the application of the wash-sale rules can be complex, investors should consult a qualified tax professional before proceeding with this strategy. For additional information, see IRS Publication 550, Investment Income and Expenses (https://www.irs.gov/publications/p550).
Seek Guidance
There may be other general financial planning considerations in a rising interest-rate environment. For example, higher rates may provide opportunities for retirees and other investors seeking to generate income stream—an objective that may have been more challenging during periods of historically low rates. The impact of higher interest rates can vary significantly based on an investor’s goals, financial circumstances and overall portfolio. Investors should consult with a financial professional to evaluate how these and other considerations may apply to their individual situation.
Bill Cass, Director of Wealth Planning
Endnotes
- Grantor Retained Annuity Trust (GRAT): An irrevocable trust into which a grantor transfers assets while retaining the right to receive fixed annuity payments for a specified period. At the end of the trust term, any remaining assets generally pass to the designated beneficiaries.
WHAT ARE THE RISKS?
All investments involve risks, including possible loss of principal.
Any information, statement or opinion set forth herein is general in nature, is not directed to or based on the financial situation or needs of any particular investor, and does not constitute, and should not be construed as, investment advice, forecast of future events, a guarantee of future results, or a recommendation with respect to any particular security or investment strategy or type of retirement account. Investors seeking financial advice regarding the appropriateness of investing in any securities or investment strategies should consult their financial professional.
Franklin Templeton, its affiliated companies, and its employees are not in the business of providing tax or legal advice to taxpayers. These materials and any tax-related statements are not intended or written to be used, and cannot be used or relied upon, by any such taxpayer for the purpose of avoiding tax penalties or complying with any applicable tax laws or regulations. Tax-related statements, if any, may have been written in connection with the “promotion or marketing” of the transaction(s) or matter(s) addressed by these materials, to the extent allowed by applicable law. Any such taxpayer should seek advice based on the taxpayer’s particular circumstances from an independent tax advisor.
Important Information
This material is intended to be of general interest only and should not be construed as individual investment advice or a recommendation or solicitation to buy, sell or hold any security or to adopt any investment strategy. It does not constitute legal or tax advice. This material may not be reproduced, distributed or published without prior written permission from Franklin Templeton.
The views expressed are those of the investment manager and the comments, opinions and analyses are rendered as at publication date and may change without notice. The underlying assumptions and these views are subject to change based on market and other conditions and may differ from other portfolio managers or of the firm as a whole. The information provided in this material is not intended as a complete analysis of every material fact regarding any country, region or market. There is no assurance that any prediction, projection or forecast on the economy, stock market, bond market or the economic trends of the markets will be realized. The value of investments and the income from them can go down as well as up and you may not get back the full amount that you invested. Past performance is not necessarily indicative nor a guarantee of future performance. All investments involve risks, including possible loss of principal.
Any research and analysis contained in this material has been procured by Franklin Templeton for its own purposes and may be acted upon in that connection and, as such, is provided to you incidentally. Data from third party sources may have been used in the preparation of this material and Franklin Templeton ("FT") has not independently verified, validated or audited such data. Although information has been obtained from sources that Franklin Templeton believes to be reliable, no guarantee can be given as to its accuracy and such information may be incomplete or condensed and may be subject to change at any time without notice. The mention of any individual securities should neither constitute nor be construed as a recommendation to purchase, hold or sell any securities, and the information provided regarding such individual securities (if any) is not a sufficient basis upon which to make an investment decision. FT accepts no liability whatsoever for any loss arising from use of this information and reliance upon the comments, opinions and analyses in the material is at the sole discretion of the user.
Franklin Templeton has environmental, social and governance (ESG) capabilities; however, not all strategies or products for a strategy consider “ESG” as part of their investment process.
Products, services and information may not be available in all jurisdictions and are offered outside the U.S. by other FT affiliates and/or their distributors as local laws and regulation permits. Please consult your own financial professional or Franklin Templeton institutional contact for further information on availability of products and services in your jurisdiction.
Issued in the U.S. by Franklin Templeton, One Franklin Parkway, San Mateo, California 94403-1906, (800) DIAL BEN/342-5236, franklintempleton.com. Investments are not FDIC insured; may lose value; and are not bank guaranteed.
You need Adobe Acrobat Reader to view and print PDF documents. Download a free version from Adobe's website.
CFA® and Chartered Financial Analyst® are trademarks owned by CFA Institute.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© Franklin Templeton
More Financial Planning Topics >