Washington's inflation fight and Beijing's growth problem are pulling the global economy in opposite directions — and investors are repricing both at once.
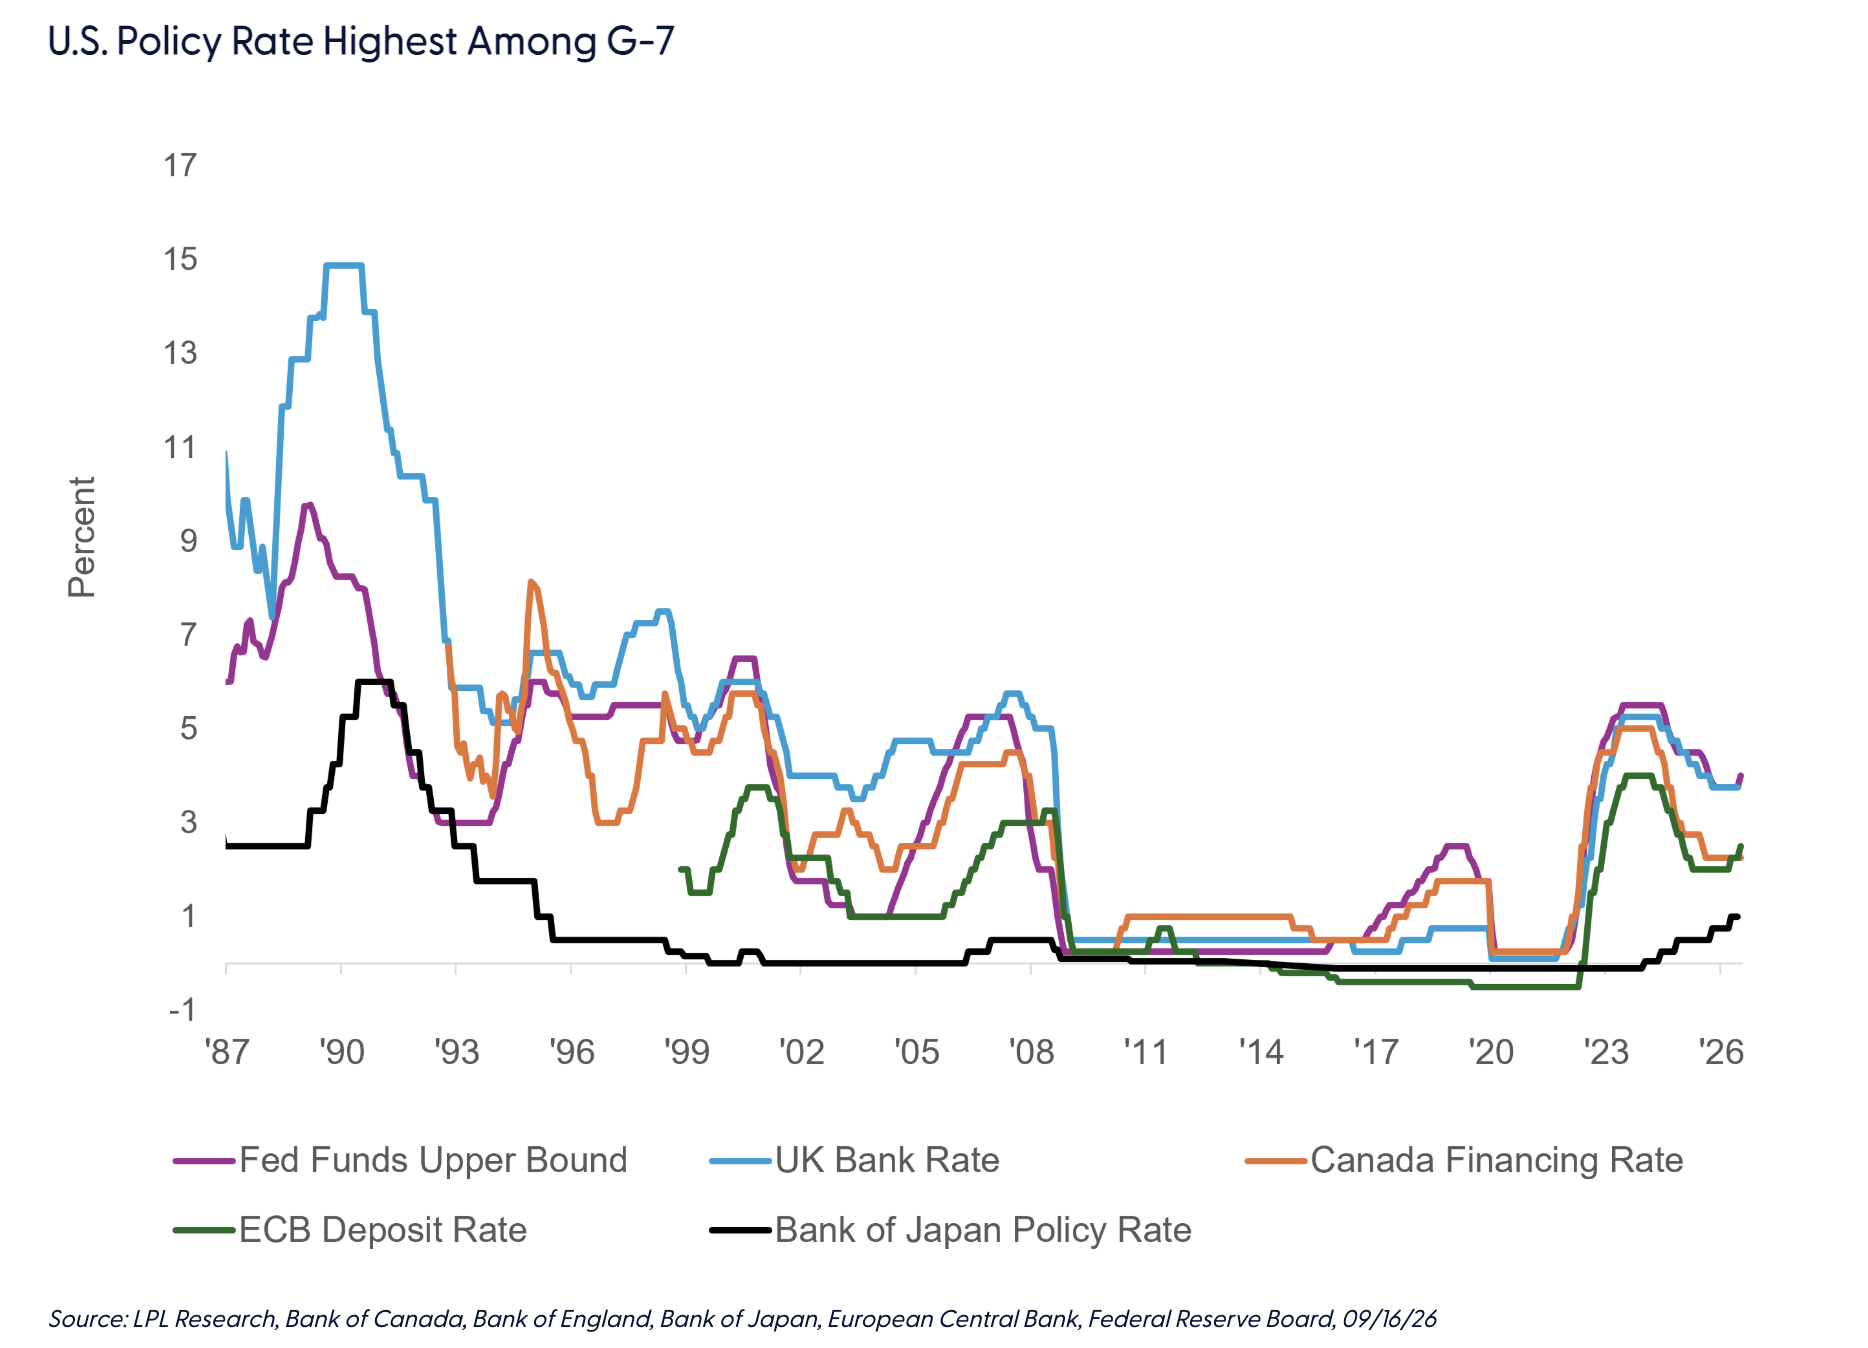
The Federal Reserve (Fed) made something clear this week that markets had been reluctant to accept. Apparently, the easing cycle isn't paused, it's over for now. The Federal Open Market Committee (FOMC) voted unanimously to raise the benchmark rate by 25 basis points to a target range of 3.75–4.00% — its first hike since 2023 — and the dot plot now shows 16 of 18 officials expecting at least one additional increase before year-end, with the median rate forecast drifting up to 4.1%. The path of policy embedded in the Summary of Economic Projections leaves little room for a cut before 2028.
That is a remarkable shift in posture, and it rests on an economy that keeps powering forward. Fed officials revised growth projections higher for the remainder of 2026 and again for 2027, when the economy could expand 2.4%. Labor markets are expected to stay tight, with the unemployment rate holding at 4.1% for the next several years. Ordinarily that combination would be cause for celebration, but not this time.
With supply constraints still binding, officials marked core inflation higher, to 3.4% for the full year. The monthly path offers more hope than the annual figure. December could print near 2.9% if oil markets settle down. Hawkish overtones run through the entire summary of projections.
Fed Chair Kevin Warsh and the committee are building a reputation for having a laser focus on defeating inflation. Given the circumstances, the committee delivered what was needed, and markets absorbed it remarkably well. The debate from here is less about the direction of future inflation than magnitude. We expect inflation to improve as geopolitical conflicts wane, but we still have a strong economy elevating demand contributions to inflation.
See more: 3% Real TIPS Yields: Boring but Valuable
China's Hot and Cold Economy
Beijing faces the mirror image of Washington's problem. Where the U.S. economy is running too warm to cut, China's is running in two directions at once.
The latest data showed weak China retail sales alongside hot industrial output — a widening imbalance in which export and industrial activity remain resilient while consumption, property, and private investment continue to weaken. AI-driven exports have been strong enough to relieve pressure on Beijing to launch a large-scale stimulus package, even as domestic demand deteriorates. Whether officials use that breathing room to punt on stimulus altogether is an open question.
Late September or October could bring Chinese officials to a decision point on full scale stimulus. The likely outcome is a shift in fiscal policy from neutral to supportive over the coming months, aided by faster bond issuance and infrastructure spending — enough, potentially, to spark a meaningful move in risk appetite for China exposure.
The Stimulus Drip Begins
The early signs are already visible, and they're arriving alongside a possible thaw in trade relations.
Washington and Beijing are reportedly weighing reciprocal tariff cuts on roughly $30 billion of trade ahead of next week's leaders' summit. Even a modest agreement would lift global trade flows and improve risk sentiment on both sides of the Pacific.
Meanwhile, Beijing is quietly supporting growth through less visible channels. A firmer yuan fixing and a big liquidity injection from the People's Bank of China show policymakers are focused on stabilizing financial conditions while growth momentum stays uneven.
The complication is oil. Middle East tensions are pushing crude higher and draining fuel inventories across Asia. With Chinese gasoline and diesel stocks falling, refiners could throttle back operations, and Beijing could revisit fuel export restrictions, adding another layer of uncertainty to global energy markets.
The Common Thread
That last point is where the two stories converge. The same geopolitical conflict inflating energy prices is also what's keeping the Fed hawkish and what's squeezing Chinese refiners. Warsh's committee has conditioned its inflation outlook on oil markets settling down, and Beijing's fiscal calculus runs through the same variable.
For investors, that argues for holding two views simultaneously. In the U.S., the case for duration keeps getting pushed out, and the burden of proof now sits with anyone arguing for cuts. In China, structural problems haven't gone away, but easing trade tensions and steady policy accommodation improve the backdrop for equities, with advanced manufacturing, technology, and export-linked sectors best positioned if the growth outlook keeps shifting.
Conclusion
Yesterday’s Fed decision sets up a fascinating policy dynamic heading into the upcoming Bank of Japan (BOJ) meeting later this week. Chair Warsh's hawkish tone sent the Bloomberg Dollar Spot Index up 0.5%, its best single-day move in three months, with traders now fully pricing in three additional Fed hikes by mid-2027, which may be overdone if inflation can improve by next year. The BOJ, meanwhile, is widely expected to deliver its own 25 basis point hike when it concludes its two-day meeting tomorrow.
The tension here is that a hawkish Fed and a tightening BOJ are pulling in opposite directions on USD/JPY: a stronger dollar from continued Fed hikes competes directly against a yen that should appreciate as the BOJ normalizes. With USD/JPY sitting around 155 heading into the BOJ decision, the net move will hinge on whether the BOJ signals an accelerated pace of hikes. A faster BOJ tightening cycle risks pushing global bond yields higher as Japanese investors repatriate capital in search of better domestic returns, a spillover that could amplify pressure across fixed income markets. For China, the picture is complicated. A persistently strong dollar from an extended Fed hiking cycle narrows Beijing's room to ease monetary policy without risking capital outflows and yuan depreciation — a particularly uncomfortable constraint given that China's domestic economy is already showing strain.
Jeffrey Roach guides the overall view of the economy for LPL Financial Research and has over 20 years of experience in investing and economics.
Important Disclosures
This material is for general information only and is not intended to provide specific advice or recommendations for any individual. There is no assurance that the views or strategies discussed are suitable for all investors. To determine which investment(s) may be appropriate for you, please consult your financial professional prior to investing.
Investing involves risks including possible loss of principal. No investment strategy or risk management technique can guarantee return or eliminate risk.
Indexes are unmanaged and cannot be invested into directly. Index performance is not indicative of the performance of any investment and does not reflect fees, expenses, or sales charges. All performance referenced is historical and is no guarantee of future results.
This material was prepared by LPL Financial, LLC. All information is believed to be from reliable sources; however LPL Financial makes no representation as to its completeness or accuracy.
Unless otherwise stated LPL Financial and the third party persons and firms mentioned are not affiliates of each other and make no representation with respect to each other. Any company names noted herein are for educational purposes only and not an indication of trading intent or a solicitation of their products or services.
Asset Class Disclosures –
International investing involves special risks such as currency fluctuation and political instability and may not be suitable for all investors. These risks are often heightened for investments in emerging markets.
Bonds are subject to market and interest rate risk if sold prior to maturity.
Municipal bonds are subject and market and interest rate risk and potentially capital gains tax if sold prior to maturity. Interest income may be subject to the alternative minimum tax. Municipal bonds are federally tax-free but other state and local taxes may apply.
Preferred stock dividends are paid at the discretion of the issuing company. Preferred stocks are subject to interest rate and credit risk. They may be subject to a call features.
Alternative investments may not be suitable for all investors and involve special risks such as leveraging the investment, potential adverse market forces, regulatory changes and potentially illiquidity. The strategies employed in the management of alternative investments may accelerate the velocity of potential losses.
Mortgage backed securities are subject to credit, default, prepayment, extension, market and interest rate risk.
High yield/junk bonds (grade BB or below) are below investment grade securities, and are subject to higher interest rate, credit, and liquidity risks than those graded BBB and above. They generally should be part of a diversified portfolio for sophisticated investors.
Precious metal investing involves greater fluctuation and potential for losses.
The fast price swings of commodities will result in significant volatility in an investor's holdings.
This research material has been prepared by LPL Financial LLC.
Not Insured by FDIC/NCUA or Any Other Government Agency | Not Bank/Credit Union Deposits or Obligations | Not Bank/Credit Union Guaranteed | May Lose Value
For Public Use – Tracking: #1176967
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
More Alternative Investments Topics >