Executive Summary
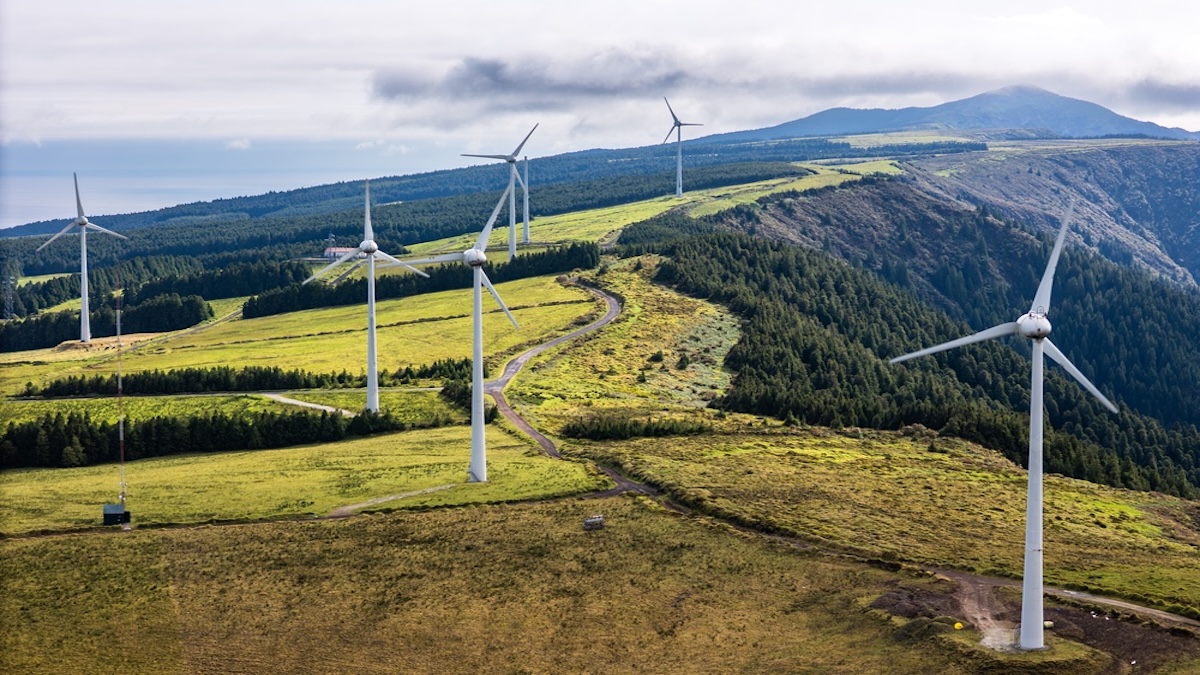
The phrase “energy transition” has served as a useful political and cultural shorthand, but it has become a misleading framework for capital allocation. We believe the operative investment lens within energy transition for the current decade should include “energy addition.” This represents a structural expansion of total global energy supply across all technology categories simultaneously, driven not by ideological preference but by the convergence of three powerful forces: geopolitical realignment, the electrification demands of artificial intelligence (AI) infrastructure and a renewed political imperative around affordability and reliability. Global energy demand grew by 1.3% in 2025, and electricity demand surged by nearly 3%.1 Every major energy source grew, but at sharply different rates. Low-emissions sources supplied nearly 60% of incremental energy demand, and solar photovoltaic (PV) was the largest single contributor. These data show that decarbonization is occurring within an expanding global energy system. This paper argues that investment opportunities are now distributed across multiple technology categories and time horizons, and that portfolios calibrated to a simple transition story risk misallocating capital in ways that could prove costly across each of those horizons. The analysis that follows is explicitly non-partisan; neither the fossil fuel industry nor renewable energy advocates hold a monopoly on the structural dynamics now reshaping global power markets.
The Multi-Horizon Investment Framework
The central claim of this paper is straightforward: The energy system of the current decade is operating in a capacity-addition cycle, within a transition cycle. Total energy demand is growing in absolute terms. Electricity demand is growing faster than overall energy demand. The capital requirements to meet that demand across generation, transmission, distribution and efficiency span multiple technology types, multiple geographies and multiple time horizons. And the current environment does not attach to energy in the abstract—it attaches to power that is simultaneously available, dependable, affordable, politically acceptable and location-matched to where demand growth is actually occurring.
This framework maps naturally to three investment horizons. The short cycle—with the fastest capital deployment and nearest return realization—encompasses data center power infrastructure, grid equipment and demand-side efficiency, most of which are in active procurement and can absorb capital productively within existing market structures. The medium cycle encompasses natural gas infrastructure, nuclear fuel supply and services, and critical minerals development, where investment decisions made today will determine supply availability in the range of three to 10 years.
The long cycle encompasses transmission capacity, large-scale generation development and industrial decarbonization, where decades-long asset lives require foresight on both the demand trajectory and the regulatory environment across multiple investment horizons.
Franklin Templeton’s research and portfolio construction capabilities are specifically suited to hold all three of these horizons simultaneously. The firm’s global presence—across equity, fixed income, real assets and alternatives—enables analysis that is not constrained by a single-asset-class or single-geography focus. Its depth of research across macroeconomic, geopolitical and sector-specific variables positions it to navigate the analytically demanding intersection of energy security, technological change, affordability, politics and climate risk management that defines the investment landscape of the current decade. The energy addition thesis is, ultimately, a thesis about the breadth and duration of a structural capital deployment cycle. Across that cycle, the investors best positioned will be those whose analytical frameworks are as broad and as durable, as the forces driving it.
See more: Should Inflation Defense Be Strategic or Tactical? Both
Endnotes
- Source: “Global Energy Review 2026: Key findings.” International Energy Agency. (2026).
WHAT ARE THE RISKS?
All investments involve risks, including possible loss of principal.
Commodity-related investments are subject to additional risks such as commodity index volatility, investor speculation, interest rates, weather, tax and regulatory developments.
International investments are subject to special risks, including currency fluctuations and social, economic and political uncertainties, which could increase volatility. These risks are magnified in emerging markets.
Any companies and/or case studies referenced herein are used solely for illustrative purposes; any investment may or may not be currently held by any portfolio advised by Franklin Templeton. The information provided is not a recommendation or individual investment advice for any particular security, strategy, or investment product and is not an indication of the trading intent of any Franklin Templeton managed portfolio. Past performance does not guarantee future results.
WF: 12468811
Important Information
This material is intended to be of general interest only and should not be construed as individual investment advice or a recommendation or solicitation to buy, sell or hold any security or to adopt any investment strategy. It does not constitute legal or tax advice. This material may not be reproduced, distributed or published without prior written permission from Franklin Templeton.
The views expressed are those of the investment manager and the comments, opinions and analyses are rendered as at publication date and may change without notice. The underlying assumptions and these views are subject to change based on market and other conditions and may differ from other portfolio managers or of the firm as a whole. The information provided in this material is not intended as a complete analysis of every material fact regarding any country, region or market. There is no assurance that any prediction, projection or forecast on the economy, stock market, bond market or the economic trends of the markets will be realized. The value of investments and the income from them can go down as well as up and you may not get back the full amount that you invested. Past performance is not necessarily indicative nor a guarantee of future performance. All investments involve risks, including possible loss of principal.
Any research and analysis contained in this material has been procured by Franklin Templeton for its own purposes and may be acted upon in that connection and, as such, is provided to you incidentally. Data from third party sources may have been used in the preparation of this material and Franklin Templeton ("FT") has not independently verified, validated or audited such data. Although information has been obtained from sources that Franklin Templeton believes to be reliable, no guarantee can be given as to its accuracy and such information may be incomplete or condensed and may be subject to change at any time without notice. The mention of any individual securities should neither constitute nor be construed as a recommendation to purchase, hold or sell any securities, and the information provided regarding such individual securities (if any) is not a sufficient basis upon which to make an investment decision. FT accepts no liability whatsoever for any loss arising from use of this information and reliance upon the comments, opinions and analyses in the material is at the sole discretion of the user.
Franklin Templeton has environmental, social and governance (ESG) capabilities; however, not all strategies or products for a strategy consider “ESG” as part of their investment process.
Products, services and information may not be available in all jurisdictions and are offered outside the U.S. by other FT affiliates and/or their distributors as local laws and regulation permits. Please consult your own financial professional or Franklin Templeton institutional contact for further information on availability of products and services in your jurisdiction.
Issued in the U.S. by Franklin Templeton, One Franklin Parkway, San Mateo, California 94403-1906, (800) DIAL BEN/342-5236, franklintempleton.com. Investments are not FDIC insured; may lose value; and are not bank guaranteed.
You need Adobe Acrobat Reader to view and print PDF documents. Download a free version from Adobe's website.
CFA® and Chartered Financial Analyst® are trademarks owned by CFA Institute.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© Franklin Templeton
Read more commentaries by Franklin Templeton