It’s all right to pass on Anthropic PBC’s initial public offering.
That may sound odd because investors never need to chase hot IPOs and probably shouldn’t. Buy the broad market, ignore the companies that occasionally come and go and watch with amazement as your money compounds.
But this IPO feels different to many people. Artificial intelligence threatens to displace jobs and upend companies and possibly entire industries, and Anthropic is among those leading the charge. If the AI lab turns out to be one of the few left standing amid the wreckage, the thinking goes, it would be financially foolish not to have a stake regardless of any misgivings about the technology.
The hunt for a doomsday hedge may explain the contradiction at the heart of Anthropic’s debut: It’s the biggest and possibly most oversubscribed IPO ever despite widespread skepticism and anxiety about AI and fears of a speculative bubble. “Almost like the last chopper out of Saigon,” as one investor told the Wall Street Journal.
Nevertheless, there are plenty of good reasons to sit this one out. For one, investors already have indirect exposure to Anthropic through many of the big technology companies that are investors. Amazon.com Inc. and Alphabet Inc., which together make up 9% of the S&P 500 Index, will collectively own 28% of Anthropic after it goes public. That alone gives investors in the broad US stock market a roughly 3% stake in the AI company.
And that exposure is set to grow. After pricing its IPO at $83 a share on Wednesday night, Anthropic will be one of the US’ most valuable companies with an initial valuation of $1.5 trillion (on a fully diluted basis), which means investors will get another big helping of its stock through index trackers and actively managed funds. Anthropic, like SpaceX, will have to clear some hurdles before it’s invited to the S&P 500, although that may work in investors’ favor. Stocks often slump after they go public, allowing investors to scoop them up at a discount. SpaceX is down about 30% from its post-IPO high.
See more: Anthropic ETFs: Private Markets, Perpetual Futures & More
At any reasonable portfolio weighting, Anthropic is unlikely to have a meaningful impact on investors’ returns unless it’s a massive home run. Some companies have delivered that kind of performance, notably the big tech companies that now dominate the stock market, including Nvidia Corp., Amazon and Alphabet. The difference is that those companies were worth a fraction of Anthropic’s expected IPO valuation when they came to market — in Nvidia’s case, just 0.04%. Anthropic would have to be worth several quadrillion dollars to deliver a comparable payoff. It’s more likely that most of the money to be made in Anthropic has already been pocketed for the foreseeable future.
That is, unless Anthropic hoards all the profits. Don’t count on it. The problem with outsized profits is that they attract competition, which is arguably Anthropic’s biggest vulnerability. It wasn’t that long ago that OpenAI’s ChatGPT was the only chatbot anyone had heard of. Anthropic’s Claude has made inroads because large language models have shallow moats: They’re relatively easy to replicate, and brand loyalty is limited. Just ask Dario Amodei, who left OpenAI, where he helped lead research on GPT-2 and GPT-3 before founding Anthropic in 2021. What happened to OpenAI could easily happen to Anthropic.
The proliferation of open models is a preview of their coming ubiquity. Anthropic will soon have numerous competitors worldwide, including in China. Look at the fight Chinese electric-car manufacturers are giving Tesla Inc. — a business at least as complicated as developing LLMs.
Anthropic’s advantages are its infrastructure and distribution partnerships with other tech giants, including Amazon and Alphabet. But those relationships can endure only if everyone wins. The moment Anthropic becomes more rival than teammate, those partnerships will quickly unravel, especially because Amazon and Alphabet have AI ambitions of their own.
Windfall profits also attract regulation, although lawmakers don’t need any more reason to rein in AI. Amodei is practically begging Congress to intervene, fearing that bad actors or autonomous chatbots will use AI to unleash cyberattacks or bioterrorism or to disrupt the economy. Midterm voters around the country passed numerous resolutions to ban, cap or slow the development of data centers. All that points to slower growth ahead.

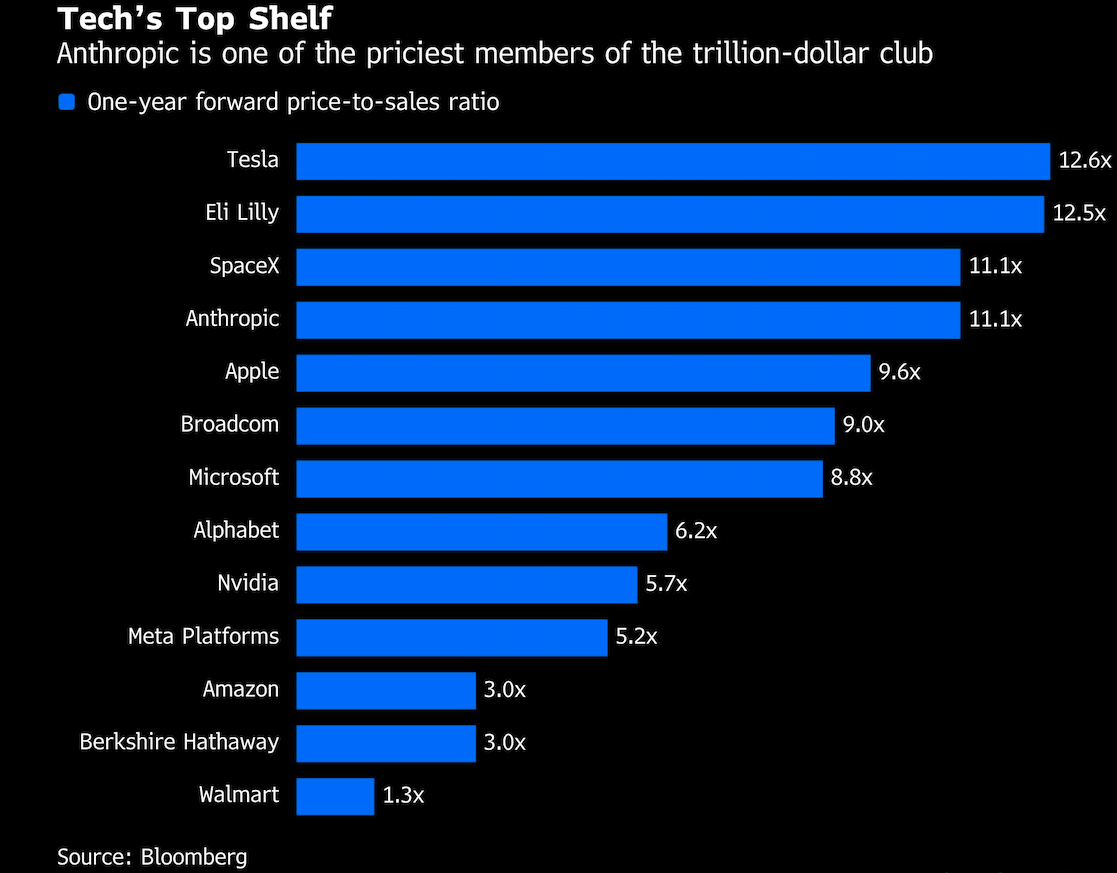
Those headwinds don’t seem to bother Anthropic’s lofty valuation. The company is expected to trade at around 11 times next year’s revenue, placing it among SpaceX and Tesla as one of the most expensively valued companies worth $1 trillion or more. Amazon, Alphabet, Meta Platforms Inc. and Nvidia can be had for nearly half that valuation or less. And ironically, they stand to make more money if Amodei gets his AI slowdown because it would put the brakes on AI spending and extend incumbents’ competitive advantage. That’s even more reason not to own more Anthropic than a market-weighted portfolio would provide.
Whether investors are motivated to own Anthropic out of greed or fear, they’ll have plenty of it. No need to ask for seconds.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Bloomberg News provided this article. For more articles like this please visit
bloomberg.com.
More Wealth Management Topics >