Stock-market risks are everywhere. But you’d be hard pressed to tell anything was wrong by looking at the surface of major US equity gauges.
The S&P 500 Index is about to end the third quarter exactly where it began. The Nasdaq 100 Index, after briefly plunging into a correction, has since shrugged off rising bond yields and risks to the artificial intelligence trade. The Cboe Volatility Index, or VIX, is well below the 20 level that often signals market stress.
Chalk it up to a violent rotation in which rising and falling stocks and sectors are largely balancing each other out, keeping the broader market steady. This gap between index-wide calm and single-stock chaos is nothing new for traders, but lately it’s grown extreme, reaching the widest level since the height of the dot-com crash in 2000, data compiled by Macro Risk Advisors show.
To Dean Curnutt, chief executive of the firm, the possibility of the broader market falling victim to a big macro shock is a risk hiding in plain sight — and one that Wall Street traders aren’t positioning for. A potential selloff in AI hyperscalers and chipmakers could fuel a rout, forcing the whole market to move together as one.
“If a few hyperscalers pull back on AI spending tied to data-center debt concerns as yields rise, that would be awful for the stock market already on fragile footing,” said Curnutt, who is urging clients to use of VIX calls and call spreads for protection against any drawdowns. “You don’t buy flood insurance rooting for your home to flood. You gotta play defense here.”
As the calendar flips to October — historically the most volatile month for US stocks — Wall Street is grappling with a series of risks, from the durability of the artificial-intelligence trade to the threat of higher interest rates amid sticky inflation.
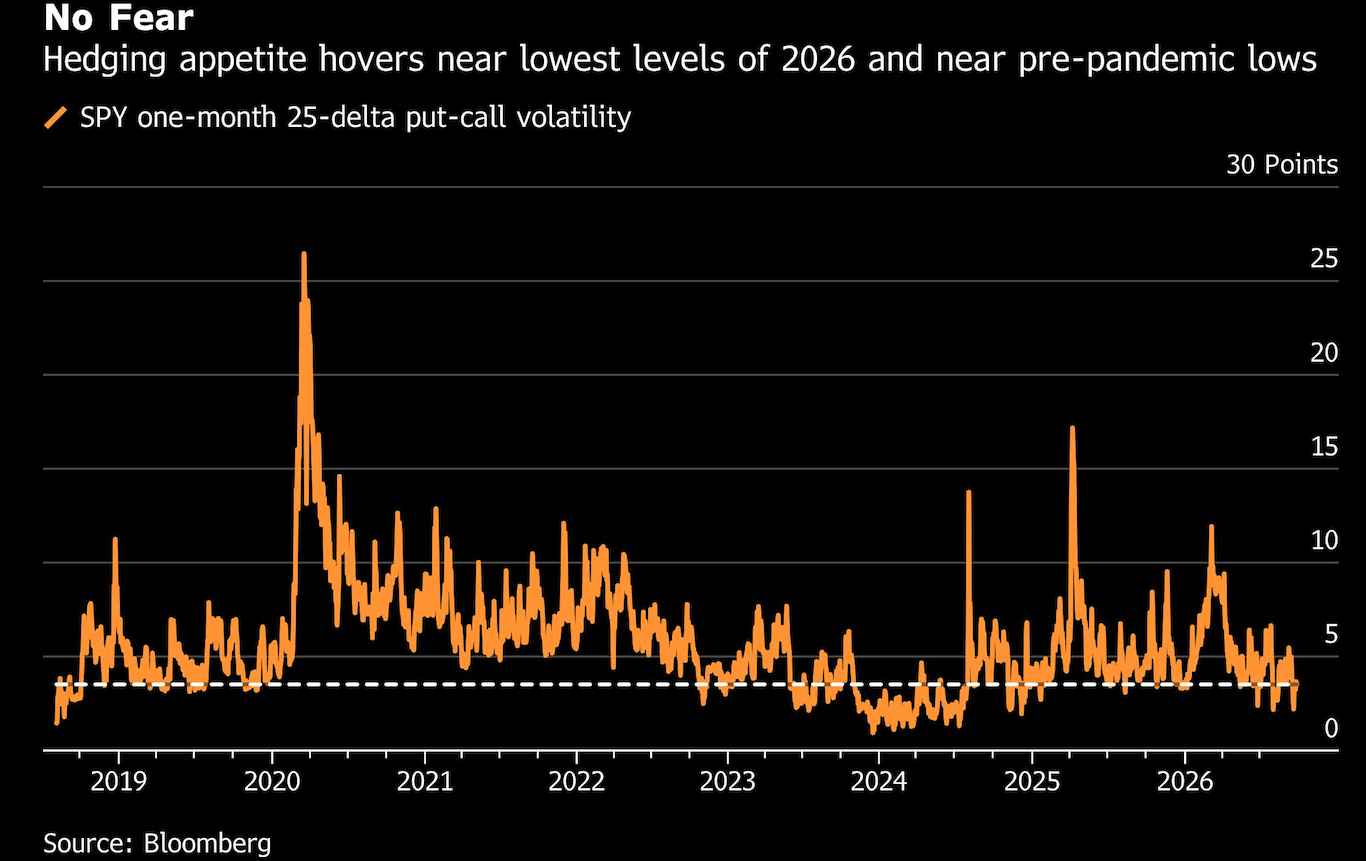
Optimism that the US and Iran are getting close to ending the war coupled with strong economic data at home have pushed traders to offload their hedges and load up on upside calls. A one-month, 25-delta put-to-call skew on the S&P 500 is sitting in the bottom-fifth percentile of observations, according to Mandy Xu, head of derivatives market intelligence at Cboe Global Markets Inc. The 500-member gauge opened 0.3% higher on Wednesday, while the Nasdaq 100 traded up 0.5%.
The appetite for risk is equally pronounced on a single-stock level. Roughly 40% of the top 100 stocks in the S&P 500 are trading with an inverted call skew — a sign of extreme bullishness, Xu said. With JPMorgan Chase & Co. kicking off earnings season Oct. 13, Xu sees the scope for single stock volatility to rise even more relative to index volatility, particularly against a backdrop of higher rates, which have historically been a catalyst for more stock dispersion, she said.
“Given how depressed index volatility is with the lack of hedging activity, it suggests a potential for a sharper pullback in the broader stock market in the coming weeks and months on any negative, unexpected headline or catalyst,” Xu said by phone.
Bulls, for their part, are taking solace in the data showing economic growth remains resilient to geopolitical jitters, elevated bond yields and persistent inflationary pressures. When earnings season kicks off in about two weeks, S&P 500 companies will likely show a third consecutive quarter of profit expansion above 20%. That would be the first such instance since 2018, excluding the Covid-19 fueled rebound, Bloomberg Intelligence data show.
Besides the upcoming reporting season, traders are bracing for a number of potentially market-moving events, from the jobs print on Friday, to the consumer price index report on Oct. 14 and an interest-rate decision on Oct. 28.
That leaves stocks in a vulnerable position to any surprises, given that investors are betting on few fireworks in the next couple of days. Should that calculation misfire, the return of volatility may interrupt the stock market’s streak of calm.
The S&P 500 is projected to swing just 0.7% in either direction when the latest jobs report gets released on Friday, in line with the average realized move on labor-report days in the past 12 months, options-market data compiled by Citigroup Inc. show.
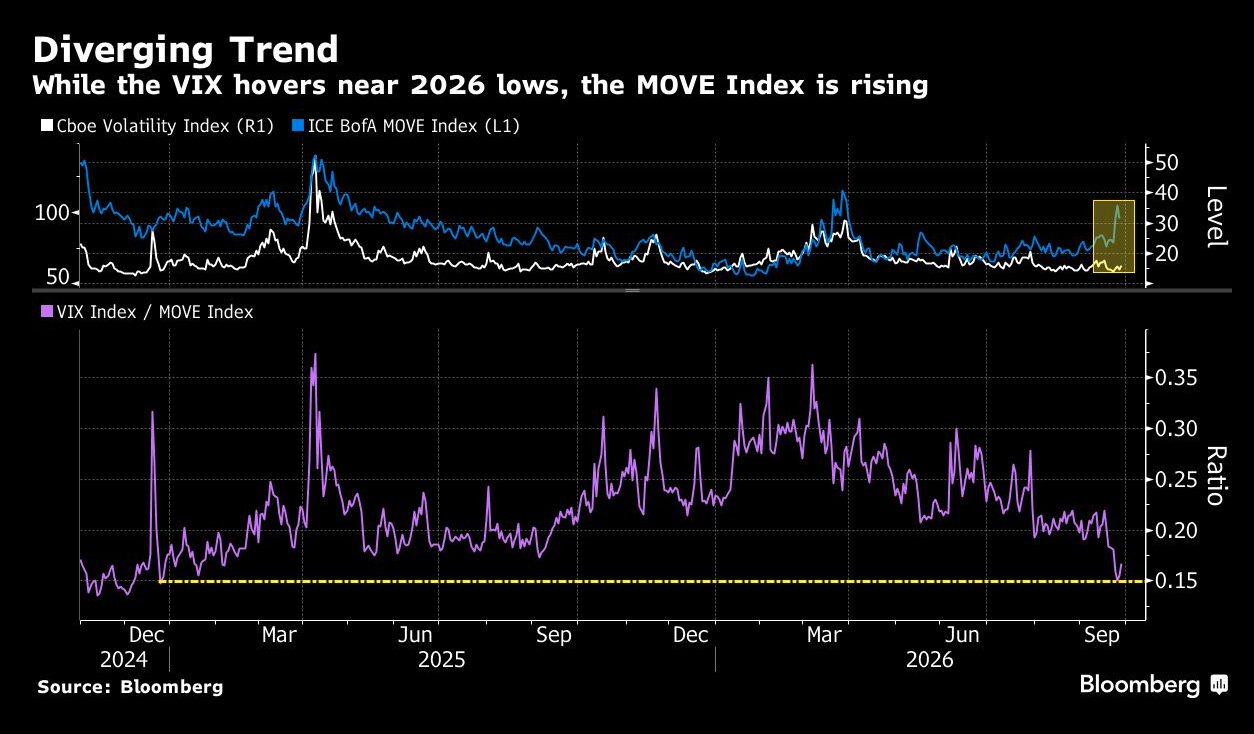
There’s also a growing divergence in volatility in the stock and bond markets. The VIX, which measures expected price swings in the S&P 500, is sitting around 16. Meanwhile, the ICE BofA MOVE Index, the bond market’s version of the VIX, spiked to as high as 104.58 last week, the highest level since the Middle East turmoil in late March. That’s signaling the bond market is bracing for volatility to stay elevated.
As a result, the ratio between the two is hovering near the lowest level since late 2024. All of which means traders are staring anxiously at fixed-income markets for an early read on when volatility in the S&P 500 could resurface again.
“Rates and stock valuations are appropriate for the level of growth in the economy,” said Scott Ladner, chief investment officer at Horizon Investments, whose firm is snapping up companies tied to AI infrastructure while dumping rate sensitive small-capitalization companies. “But all of this hinges on earnings growth continuing to deliver.”