At least once a year, regardless of market conditions, some investment bank or another announces that it is “redefining” investing. I remember attending a presentation way back in 2019 at which a senior banker argued that, after nearly a decade of low bond yields, the standard 60/40 portfolio (60% stocks, 40% bonds) needed to be rethought. After a long song and dance, his “redefinition” amounted to putting some riskier assets in the bond portfolio to goose returns.
Now the US is in a higher-interest-rate environment, and once again there is a lot of redefining going on. One change is that it’s finally good to be a saver again. The catch is that saving isn’t quite as safe as it used to be.
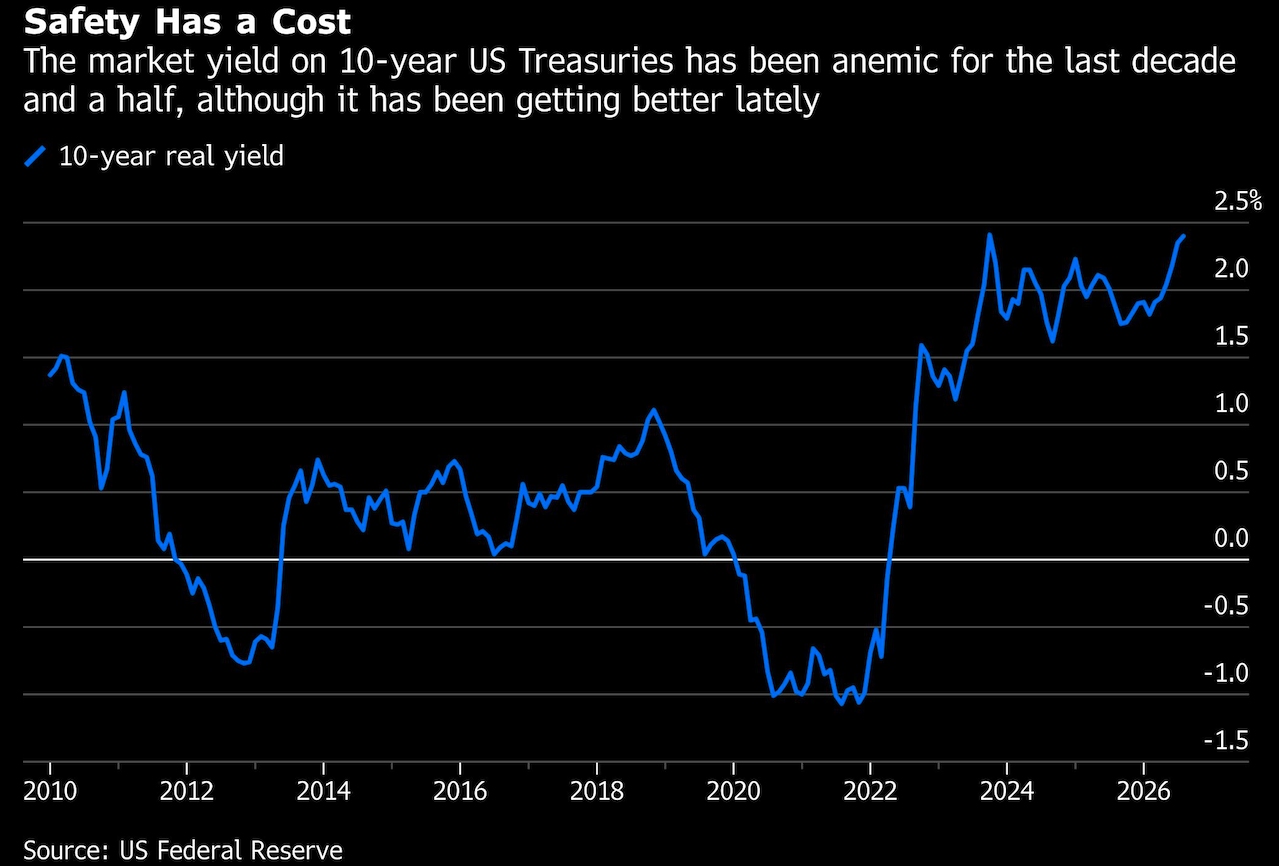
Don’t get me wrong — if you were in the stock market the last 30 years, that was pretty great too, except for the financial crisis and the pandemic, and a few corrections here and there. But you could get great returns if you took on that risk. A safe portfolio, meanwhile, paid nothing — near zero interest on a bank account, money market funds, even Treasuries. It was less than nothing after you accounted for inflation. In that environment, savers had no choice: Either take on risk or lose money.

A 60/40 portfolio is supposed to be a split of risky and non-risky assets. It’s a hedge that balances risk and reward. Safety costs money, in terms of forgone returns, and during the 2010s those costs were high. So if savers simply wanted to preserve their spending power, they had to take more risk. That banker from 2019 can call it whatever he wants, but all he was doing was changing the 60/40 portfolio to the 75/25 portfolio.
See more: Has the Bond Market Already Done the Fed's Job?
Now interest rates are not only higher, with the yield on the 10-year US Treasury note dancing around 5%, but they may also be higher for longer. And that means people don’t need to pay so much — that is, forgo as many gains — for a safer asset.
Some say the 60/40 portfolio is over because while bonds pay more, their correlation with stocks is not reliably negative. But that misunderstands what the portfolio is meant to do. It was never about diversification, or assets that move in different directions as the market rises and falls. The risky-asset part of the portfolio should already be diversified.
The purpose of the 60/40 portfolio has always been to balance safe and risky returns. Not to pick on that 2019 banker again, but he might want to redefine his redefinition of the investing paradigm, because with higher yields, the 60/40 is back.
That said, the meaning of “safety” has changed. Consider another low-risk asset that just got cheaper: annuities that offer a guaranteed income. Higher rates make them less expensive because they are based on bond prices. But annuities may not be as safe as they appear, since many of the investments that finance them, such as private credit, are not so safe.
One reason that private markets got so big is that investors were chasing higher yields in a low-rate environment. Now that they can get a high risk-free rate, they have less need for opaque sources of fixed income. With less demand and more expensive leverage, some risky assets may start looking less attractive. These markets may face an overdue reckoning — and so will annuities that invested in them.
As always, there is no free lunch in finance. Maybe investors can now get a 5% yield on a safe asset, but that’s in the context of a riskier environment. Bond yields are higher in part because there is more risk. Inflation, too, may be higher, or at the very least there is more uncertainty about where it is headed, and that in turn means more uncertainty about real bond returns. All the increased government debt also adds to the uncertainty about the bond market.
The bottom line: Expect more volatility, and less predictability, for bond funds. Correlations — with stocks or any other asset class — will also be less stable. Investors who are looking for truly safe assets will have a harder time finding them. Safety pays now, but only because it has become a little less safe.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
Bloomberg News provided this article. For more articles like this please visit
bloomberg.com.
Read more articles by Allison Schrager