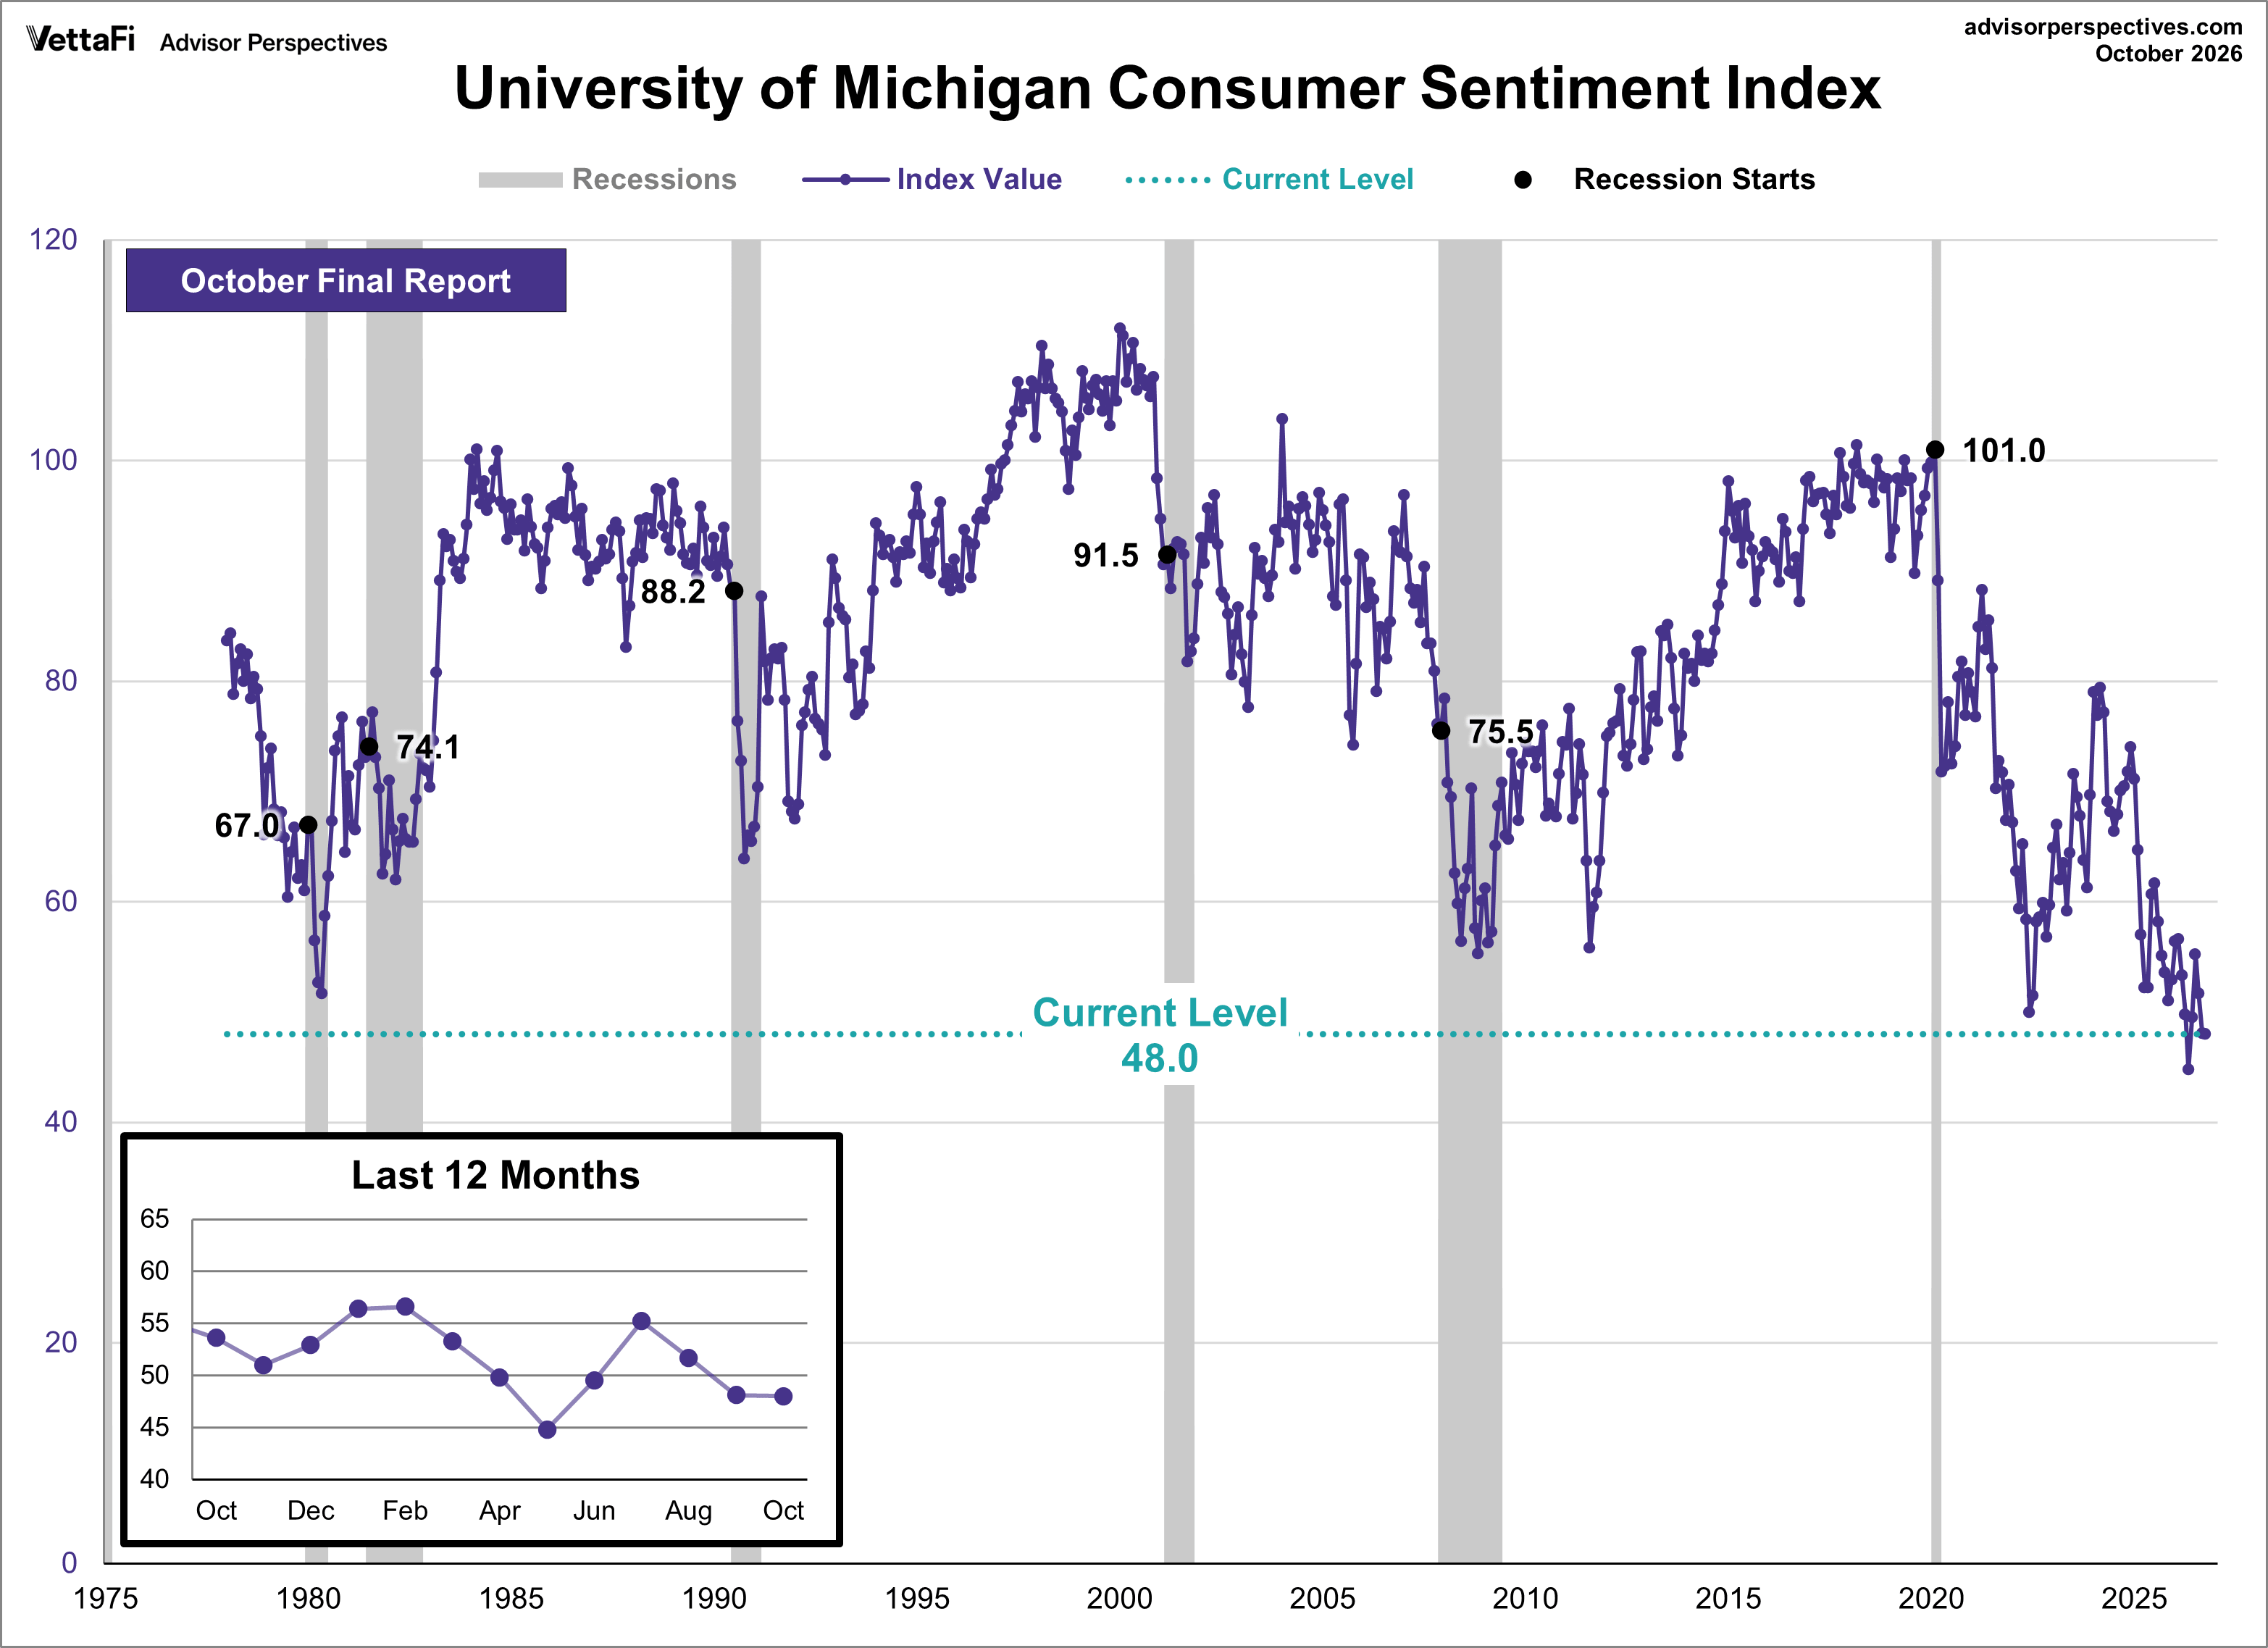
Consumer sentiment falls in October to a five month low. The final October reading for the University of Michigan Consumer Sentiment Index came in at 48.0. This marks a 0.2% (0.1 points) decrease from September. Consumer sentiment sits 10.4% below where it was a year ago and is currently below the 1st percentile in the series' history.
Key Takeaways
-
The University of Michigan Consumer Sentiment Index final reading fell to 48.0 in October, a 0.2% decrease from September.
- The Current Economic Conditions Index fell 8.3% to 46.7, while the Consumer Expectations Index rose 5.4% to 48.8.
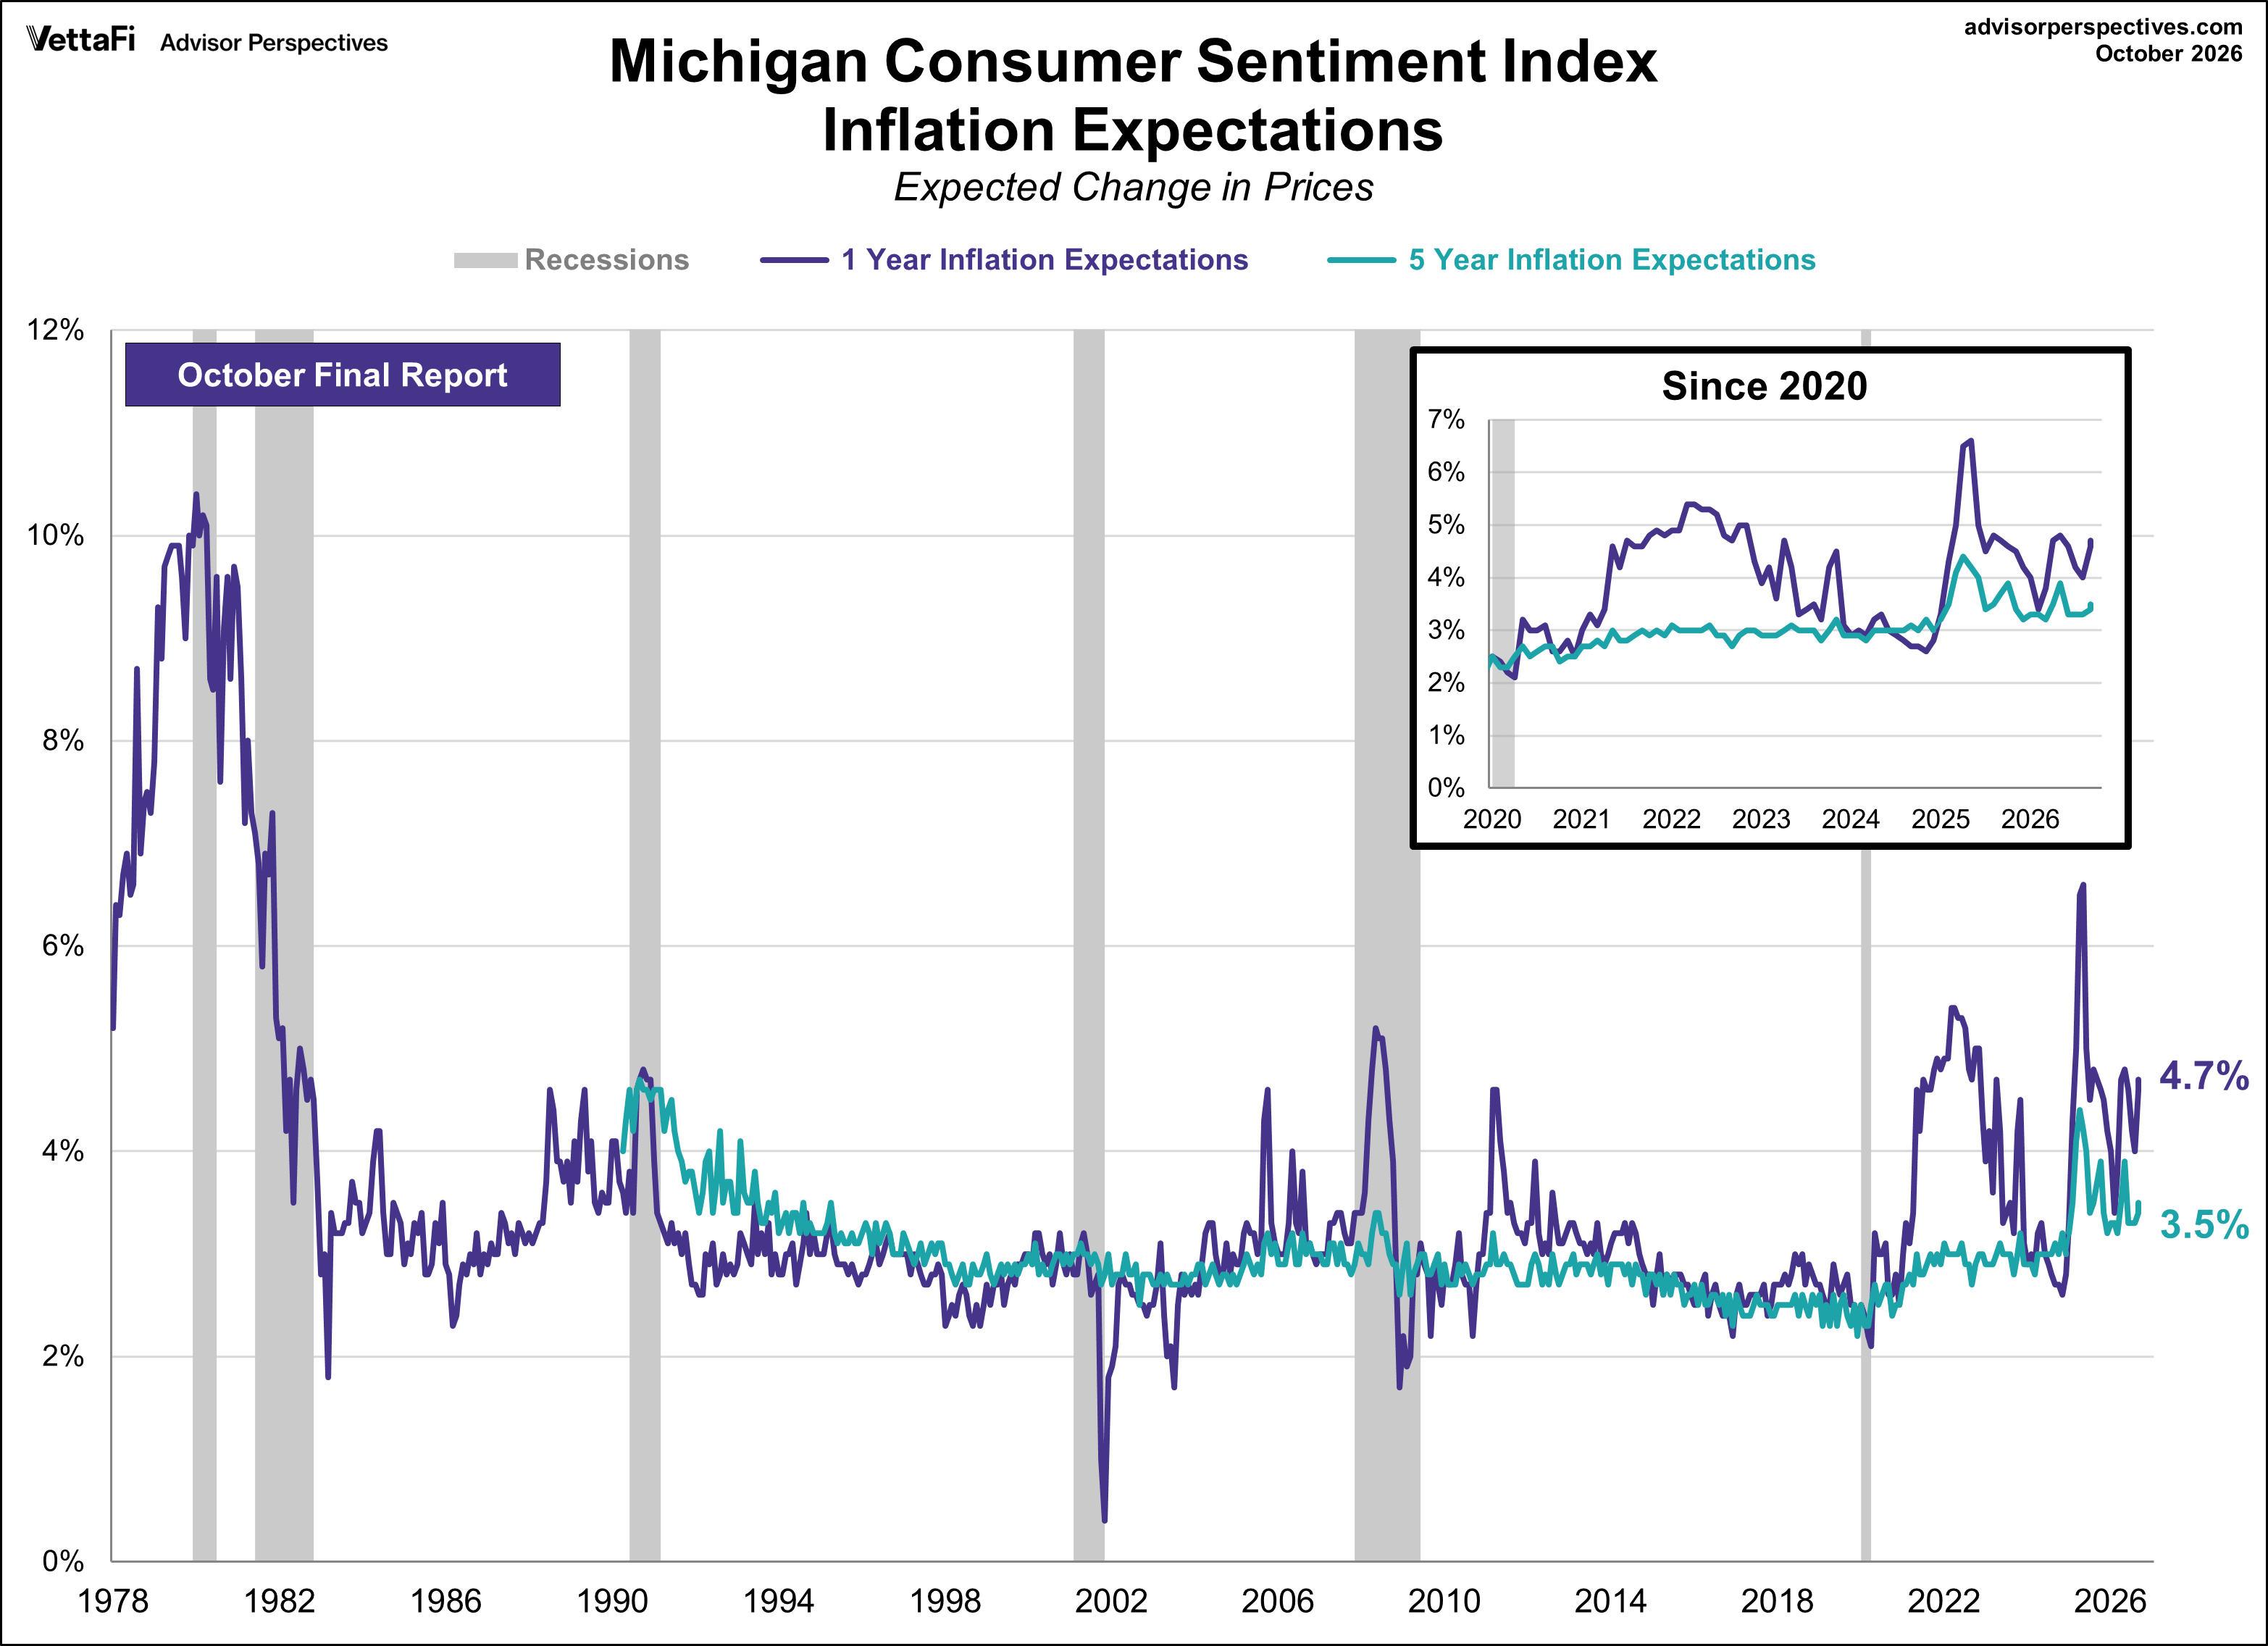
- Year-ahead inflation expectations increased from 4.6% to 4.7% from September.
Joanne Hsu, the director of surveys, made the following comments:
Consumer sentiment held steady this month, registering a scant one-tenth of an index point below September. Increases in sentiment among Republicans and Democrats were balanced by declines among independents. While year-ahead business conditions improved about 14%, they stand 16% less than last October’s read. This month’s decline in the Current Conditions subindex was driven entirely by buying conditions for durables, which plunged 18% on the basis of higher interest rates and rising concerns about the affordability of such purchases. Purchasing power continues to dominate consumer views of the economy. Sentiment is now 10% below a year ago and 15% less than February, just prior to the Iran conflict.
Background on the University of Michigan Consumer Sentiment Index
The Michigan Consumer Sentiment Index is a monthly survey of consumer confidence levels in the U.S. with regards to the economy, personal finances, business conditions, and buying conditions, conducted by the University of Michigan. There are two reports released each month; a preliminary report released mid-month and a final report released at the end of the month.
The chart below provides a long-term perspective on this widely watched indicator. We have highlighted the index's value at the start of each recession. The current level of 48.0 is below the index's value at the start of all six recessions since its inception.

To put today’s report in historical context, consumer sentiment is currently 42.6% below its average reading of 83.6 (arithmetic mean) and 41.7% below its geometric mean of 82.3, based on data dating back to 1978.
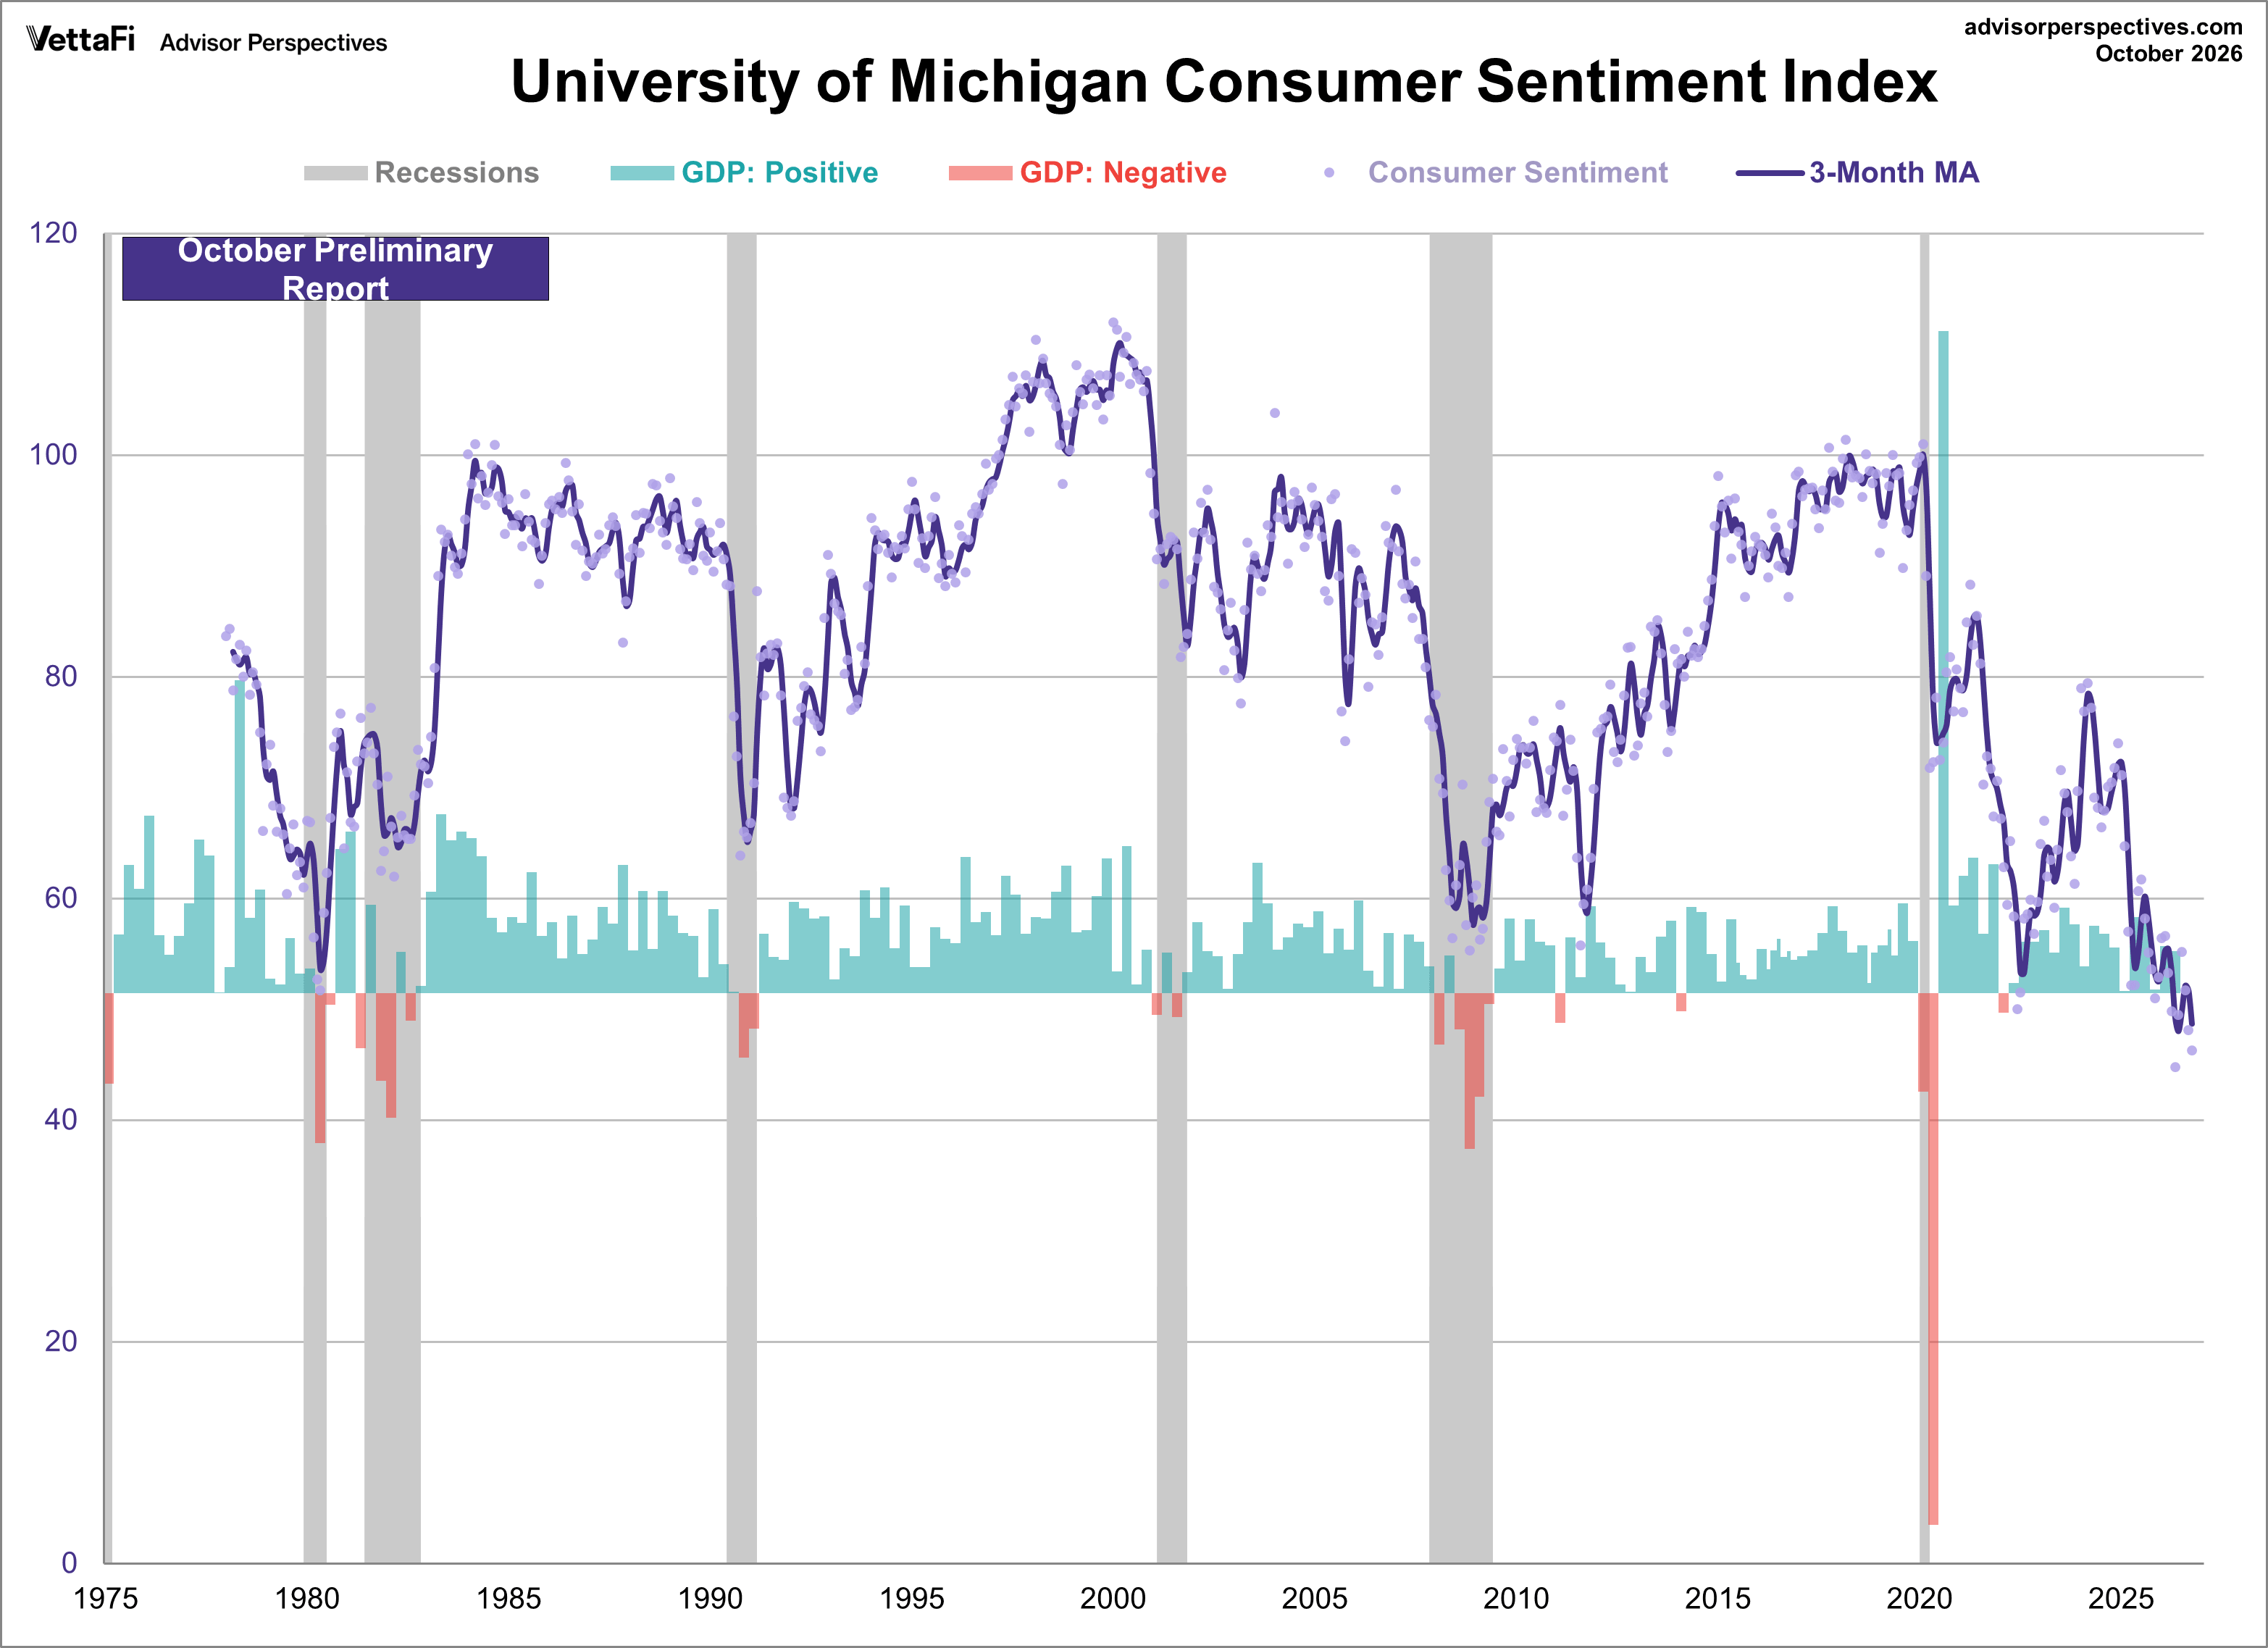
To visualize the volatility and its impact on the broader economy, the following chart includes a three-month moving average and real GDP. Historically, prolonged periods where the moving average remains at these depressed levels have closely correlated with negative GDP growth (the red bars below).
The Political and Presidential Lens of Consumer Sentiment
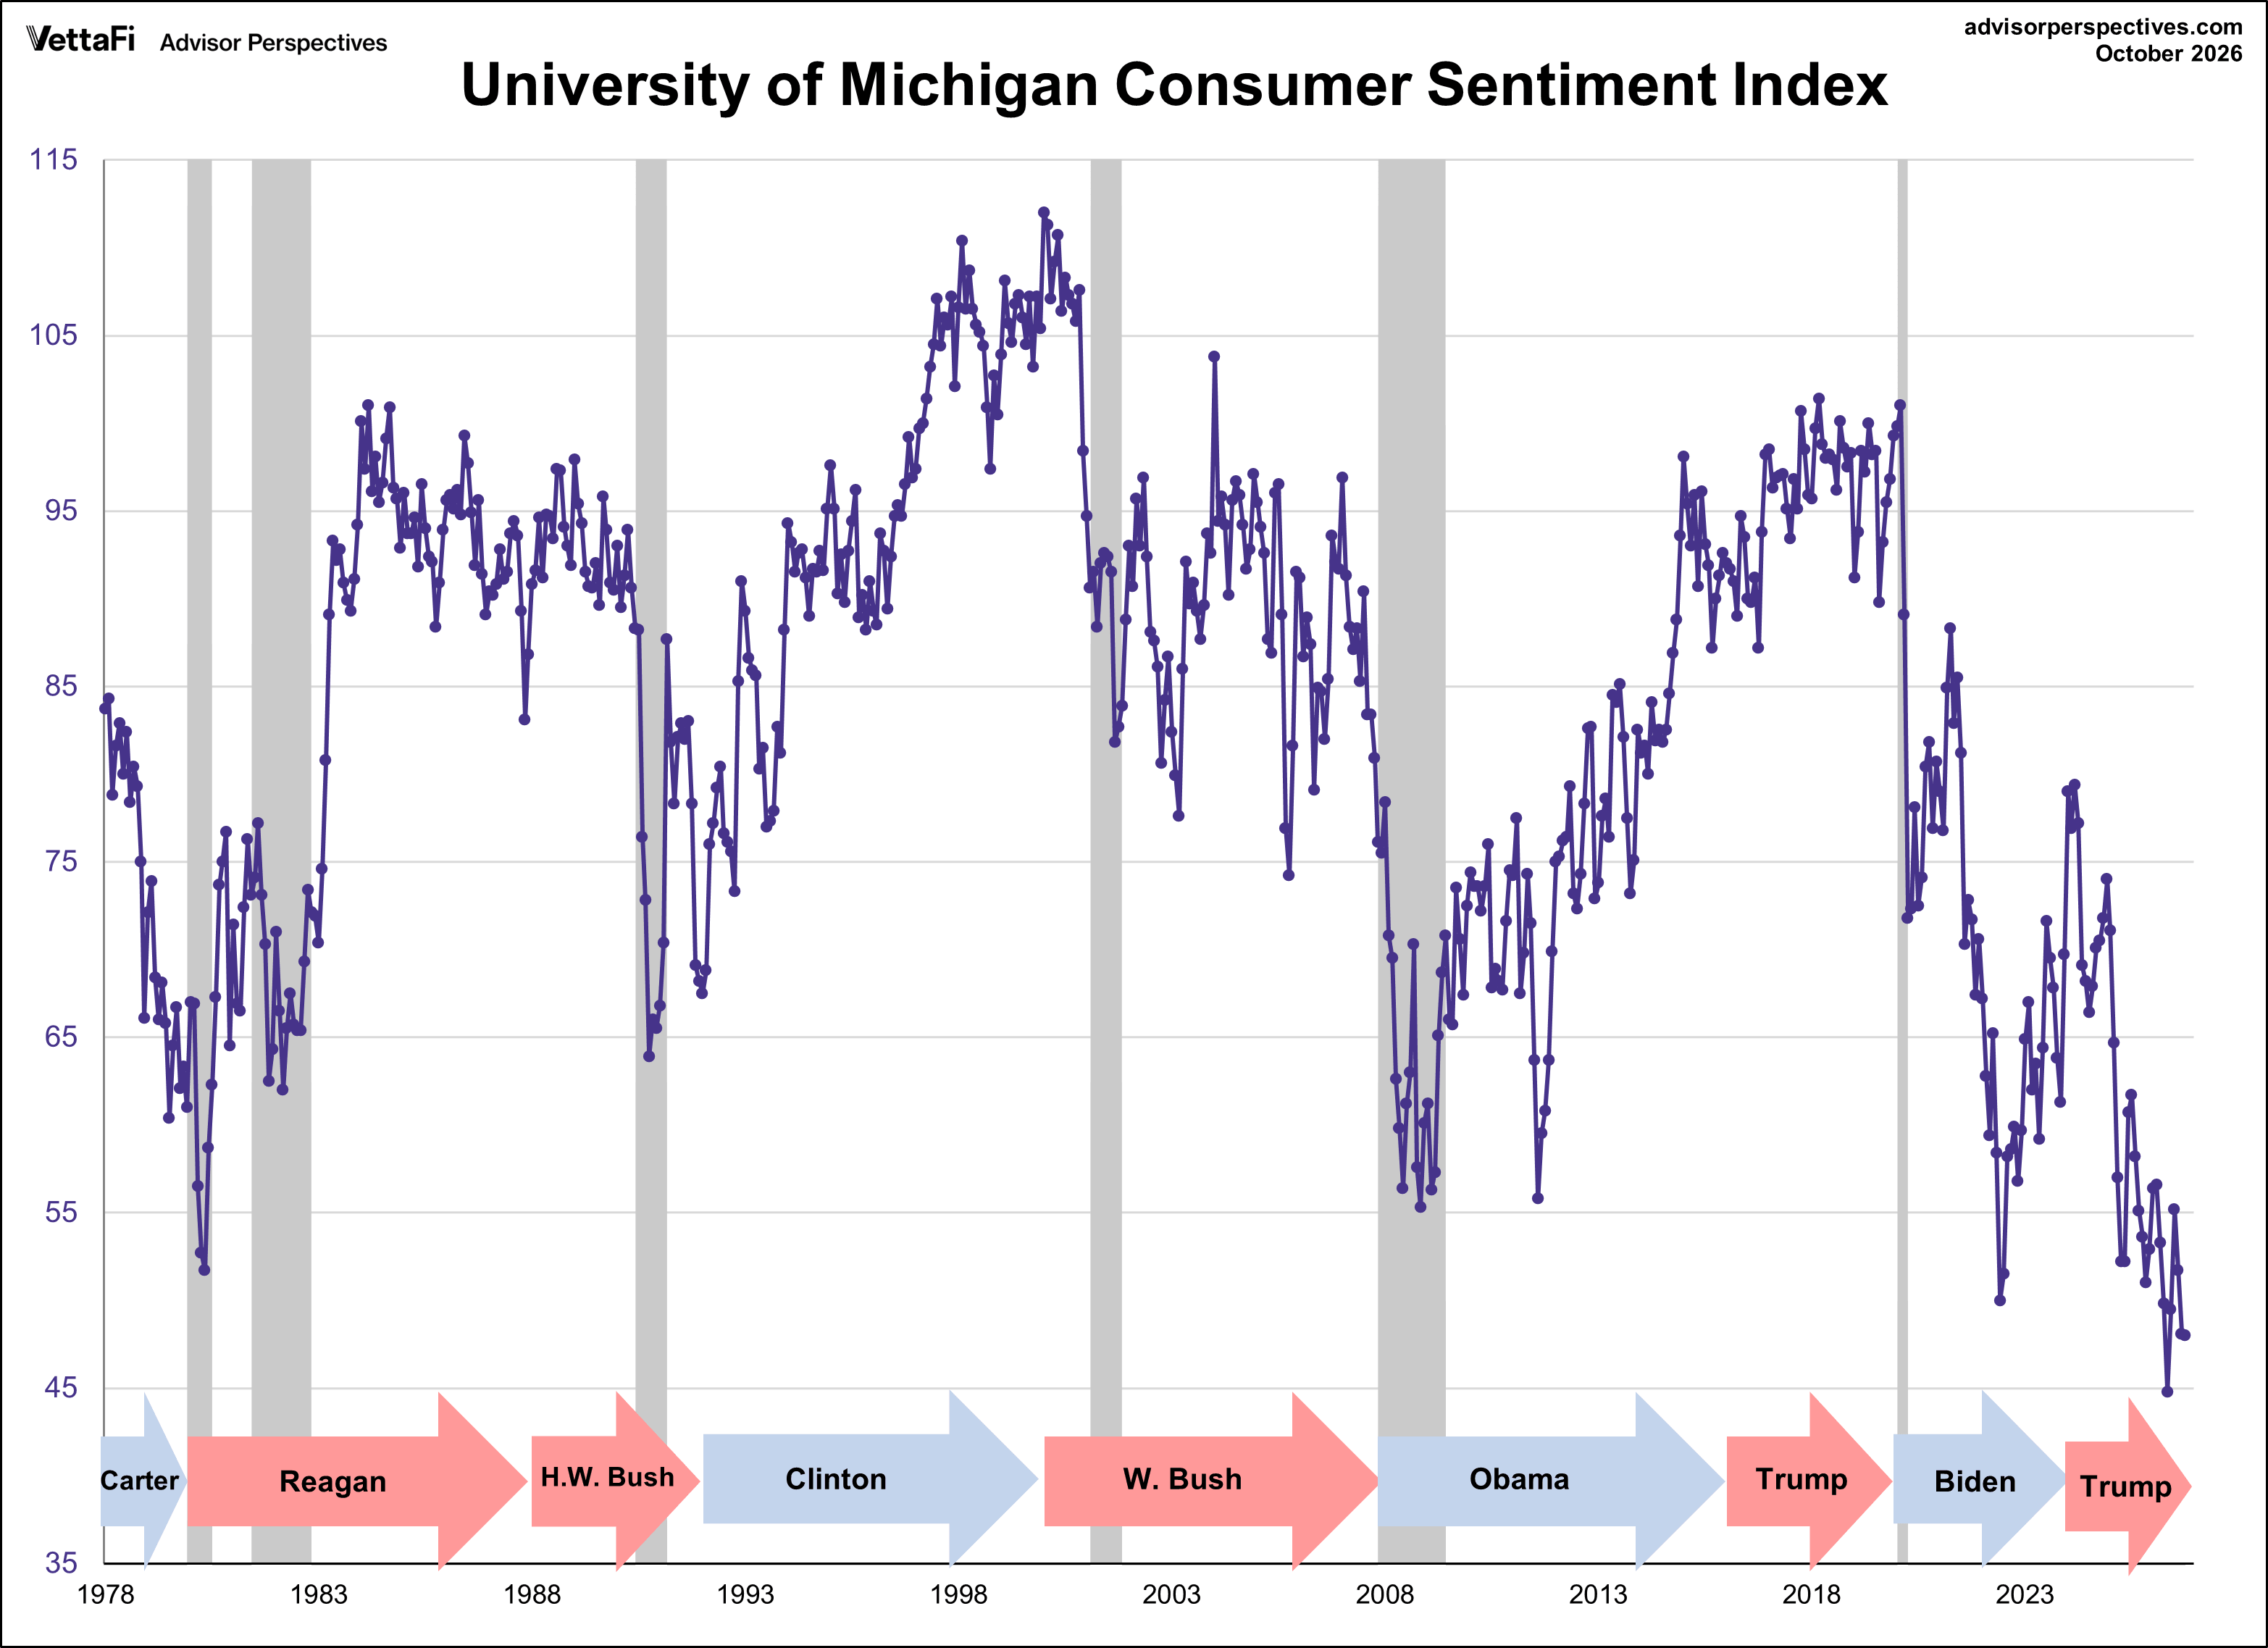
Each month, the survey results highlight sentiment within each political party. Sentiment is often viewed through a partisan lens, but the data shows that sentiment has fluctuated both positively and negatively under both Republican and Democratic administrations. As the chart below illustrates, the current "plunge" is a rare moment of bipartisan agreement, with declines seen across the political spectrum as energy costs hit every household.
University of Michigan Consumer Sentiment Index: Components
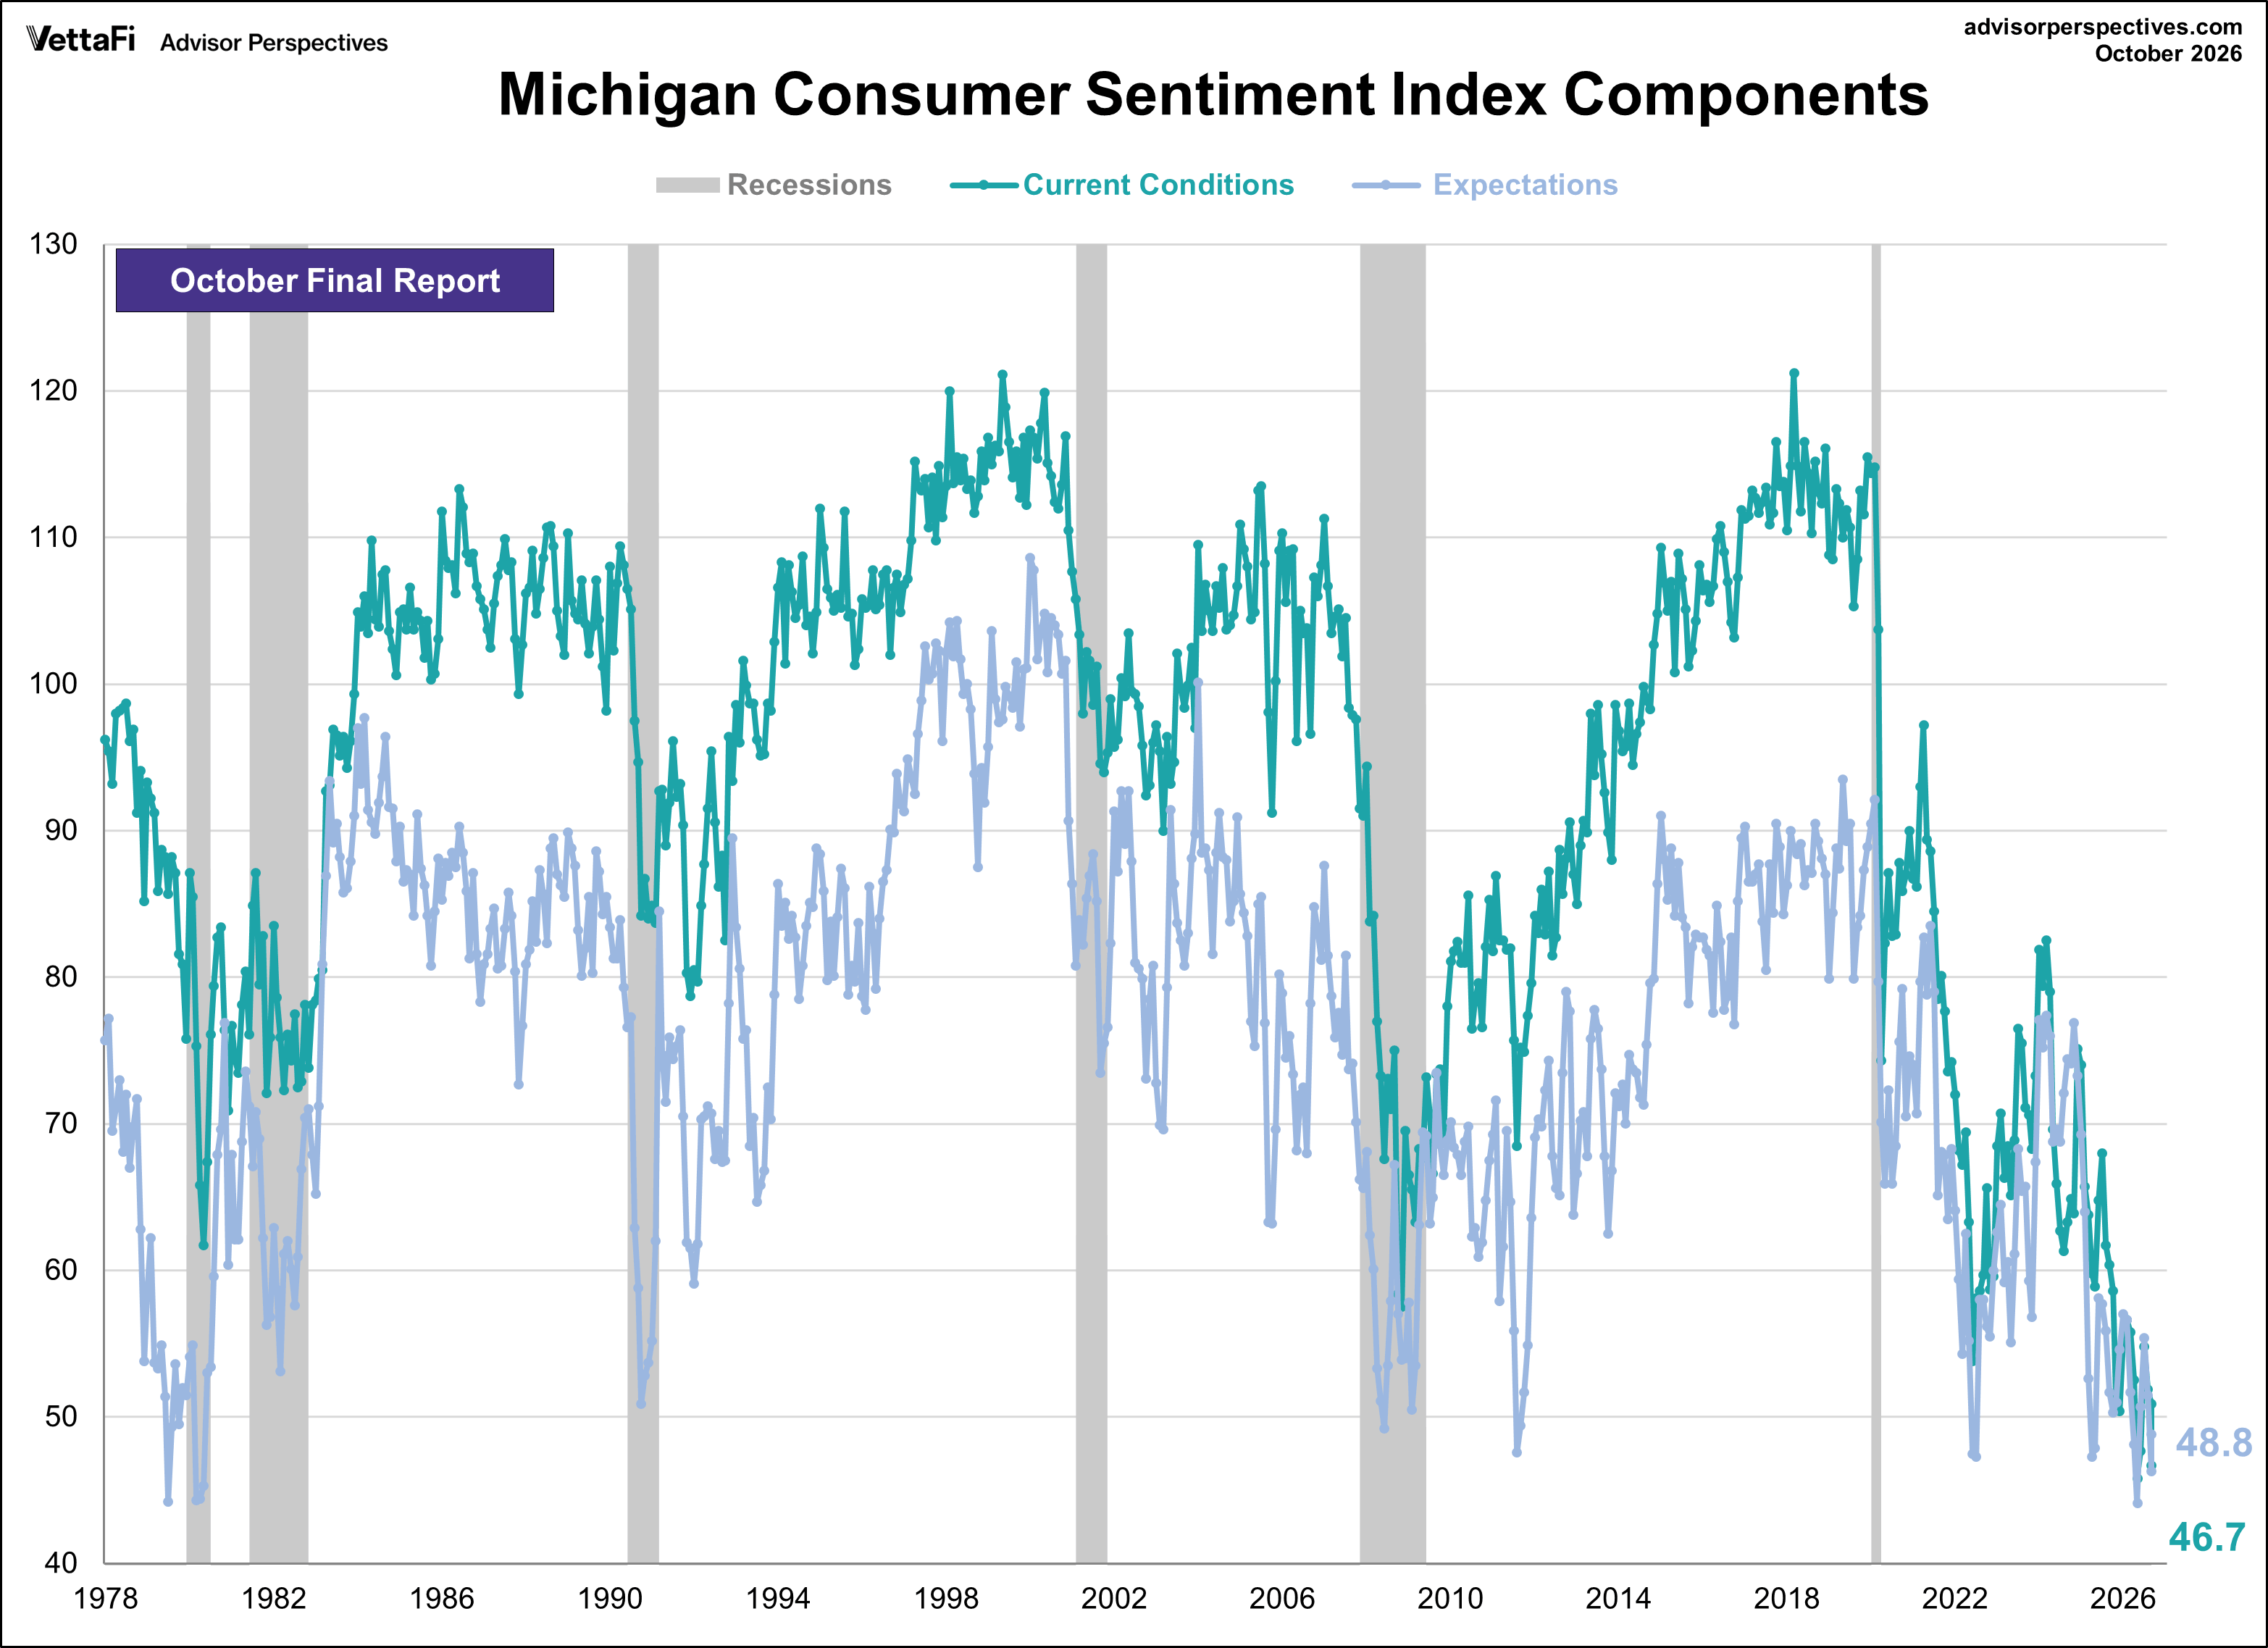
The Michigan Consumer Sentiment Index consists of two sub-indexes: the Current Economic Conditions Index (CECI) and the Consumer Expectations Index (CEI). The CECI reflects consumers' views of their current financial situation and the overall economy, while the CEI gauges their outlook for the future.
Current Economic Conditions Index (CECI)
The Current Economic Conditions Index fell to 46.7. This represents a 8.3 decrease from the previous month and a 20.3% drop from a year ago. The latest reading was lower than the forecast of 44.7.
Consumer Expectations Index (CEI)
The Consumer Expectations Index fell to 48.8. This represents a 5.4% increase from the previous month and a 3.0% drop from one year ago. The latest reading was higher than the forecast of 47.3.
University of Michigan Consumer Sentiment Index: Inflation Expectations
Year-ahead inflation expectations ticked up from 4.6% last month to 4.7% this month. The current reading substantially exceeds the 3.4% seen in February before the Iran conflict began, along with all 2024 readings. Long-run inflation expectations also stepped up from 3.4% in September to 3.5%, notably higher than their 2024 range of 2.8% to 3.2%. Inflation expectations over both time horizons increased for the second straight month to their highest readings since May.
The next update to this report will be published on October 23rd.
Other Sentiment Indicators
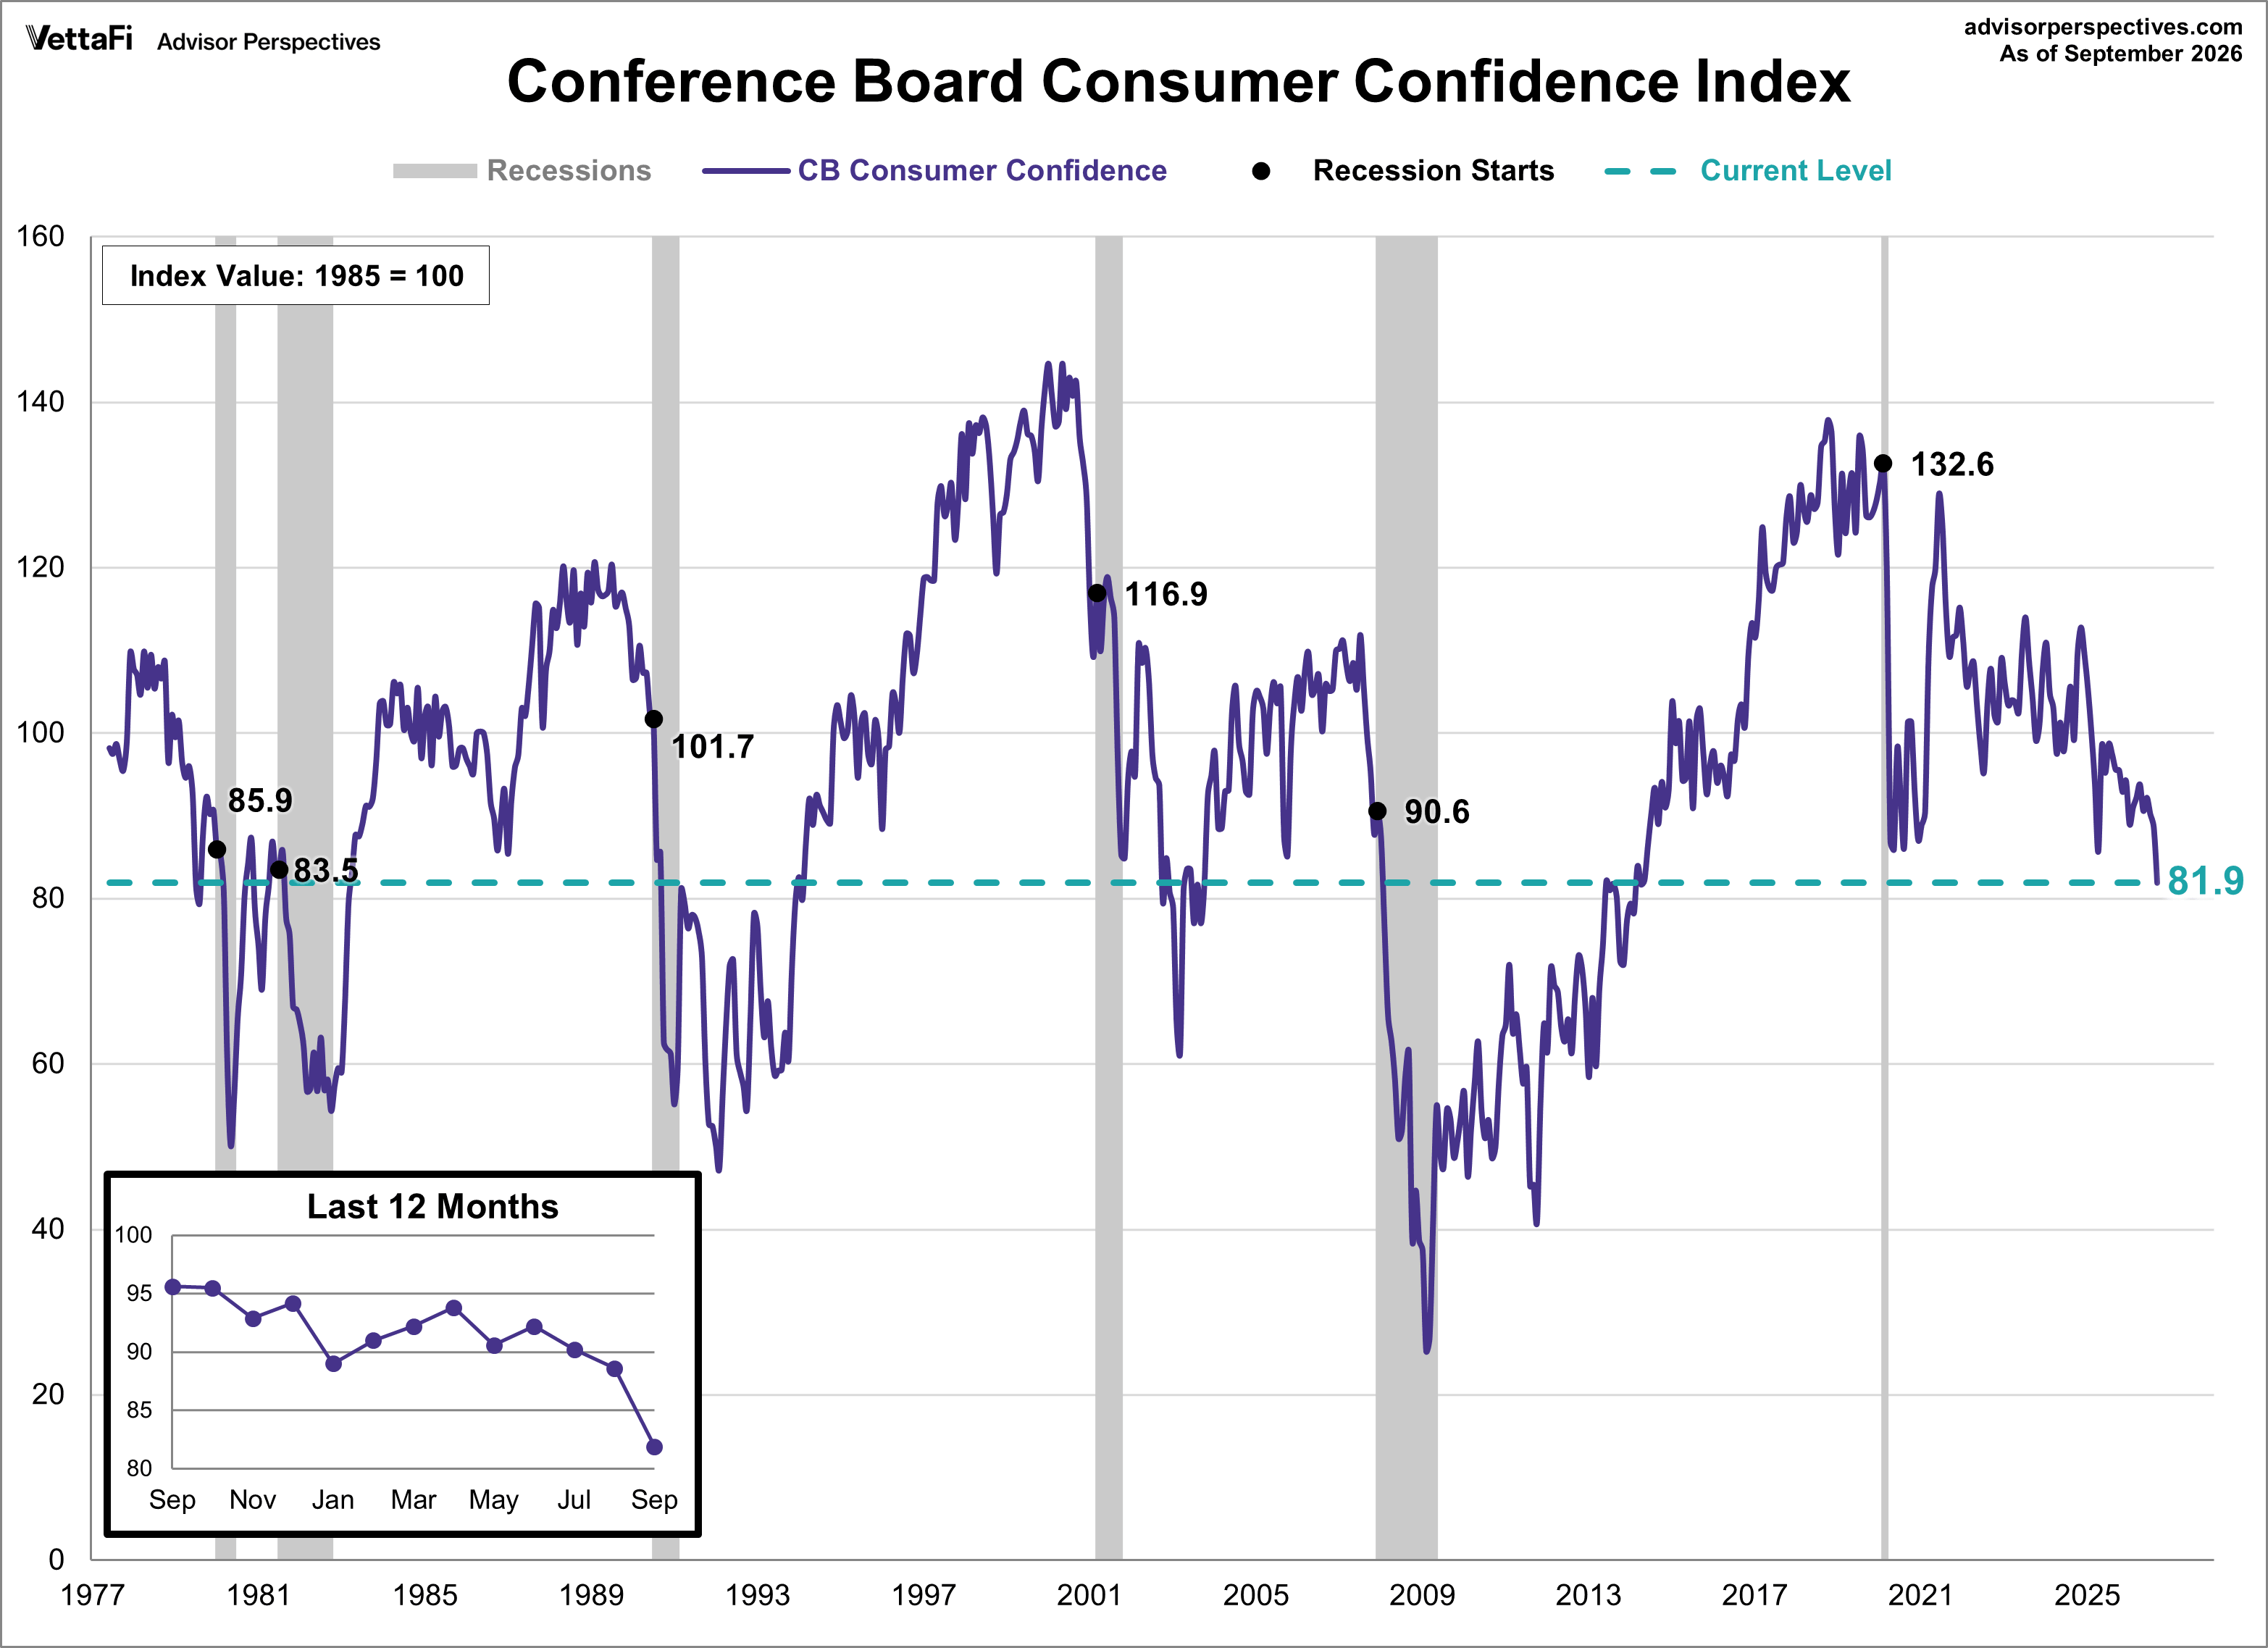
For an additional perspective on consumer attitudes, see the most recent Conference Board's Consumer Confidence Index. Both indexes gauge consumer attitudes toward the current and future strength of the economy. However, the Consumer Confidence Index is more influenced by employment and labor market conditions while the Michigan Sentiment Index is more focused on household finances and the impact of inflation.
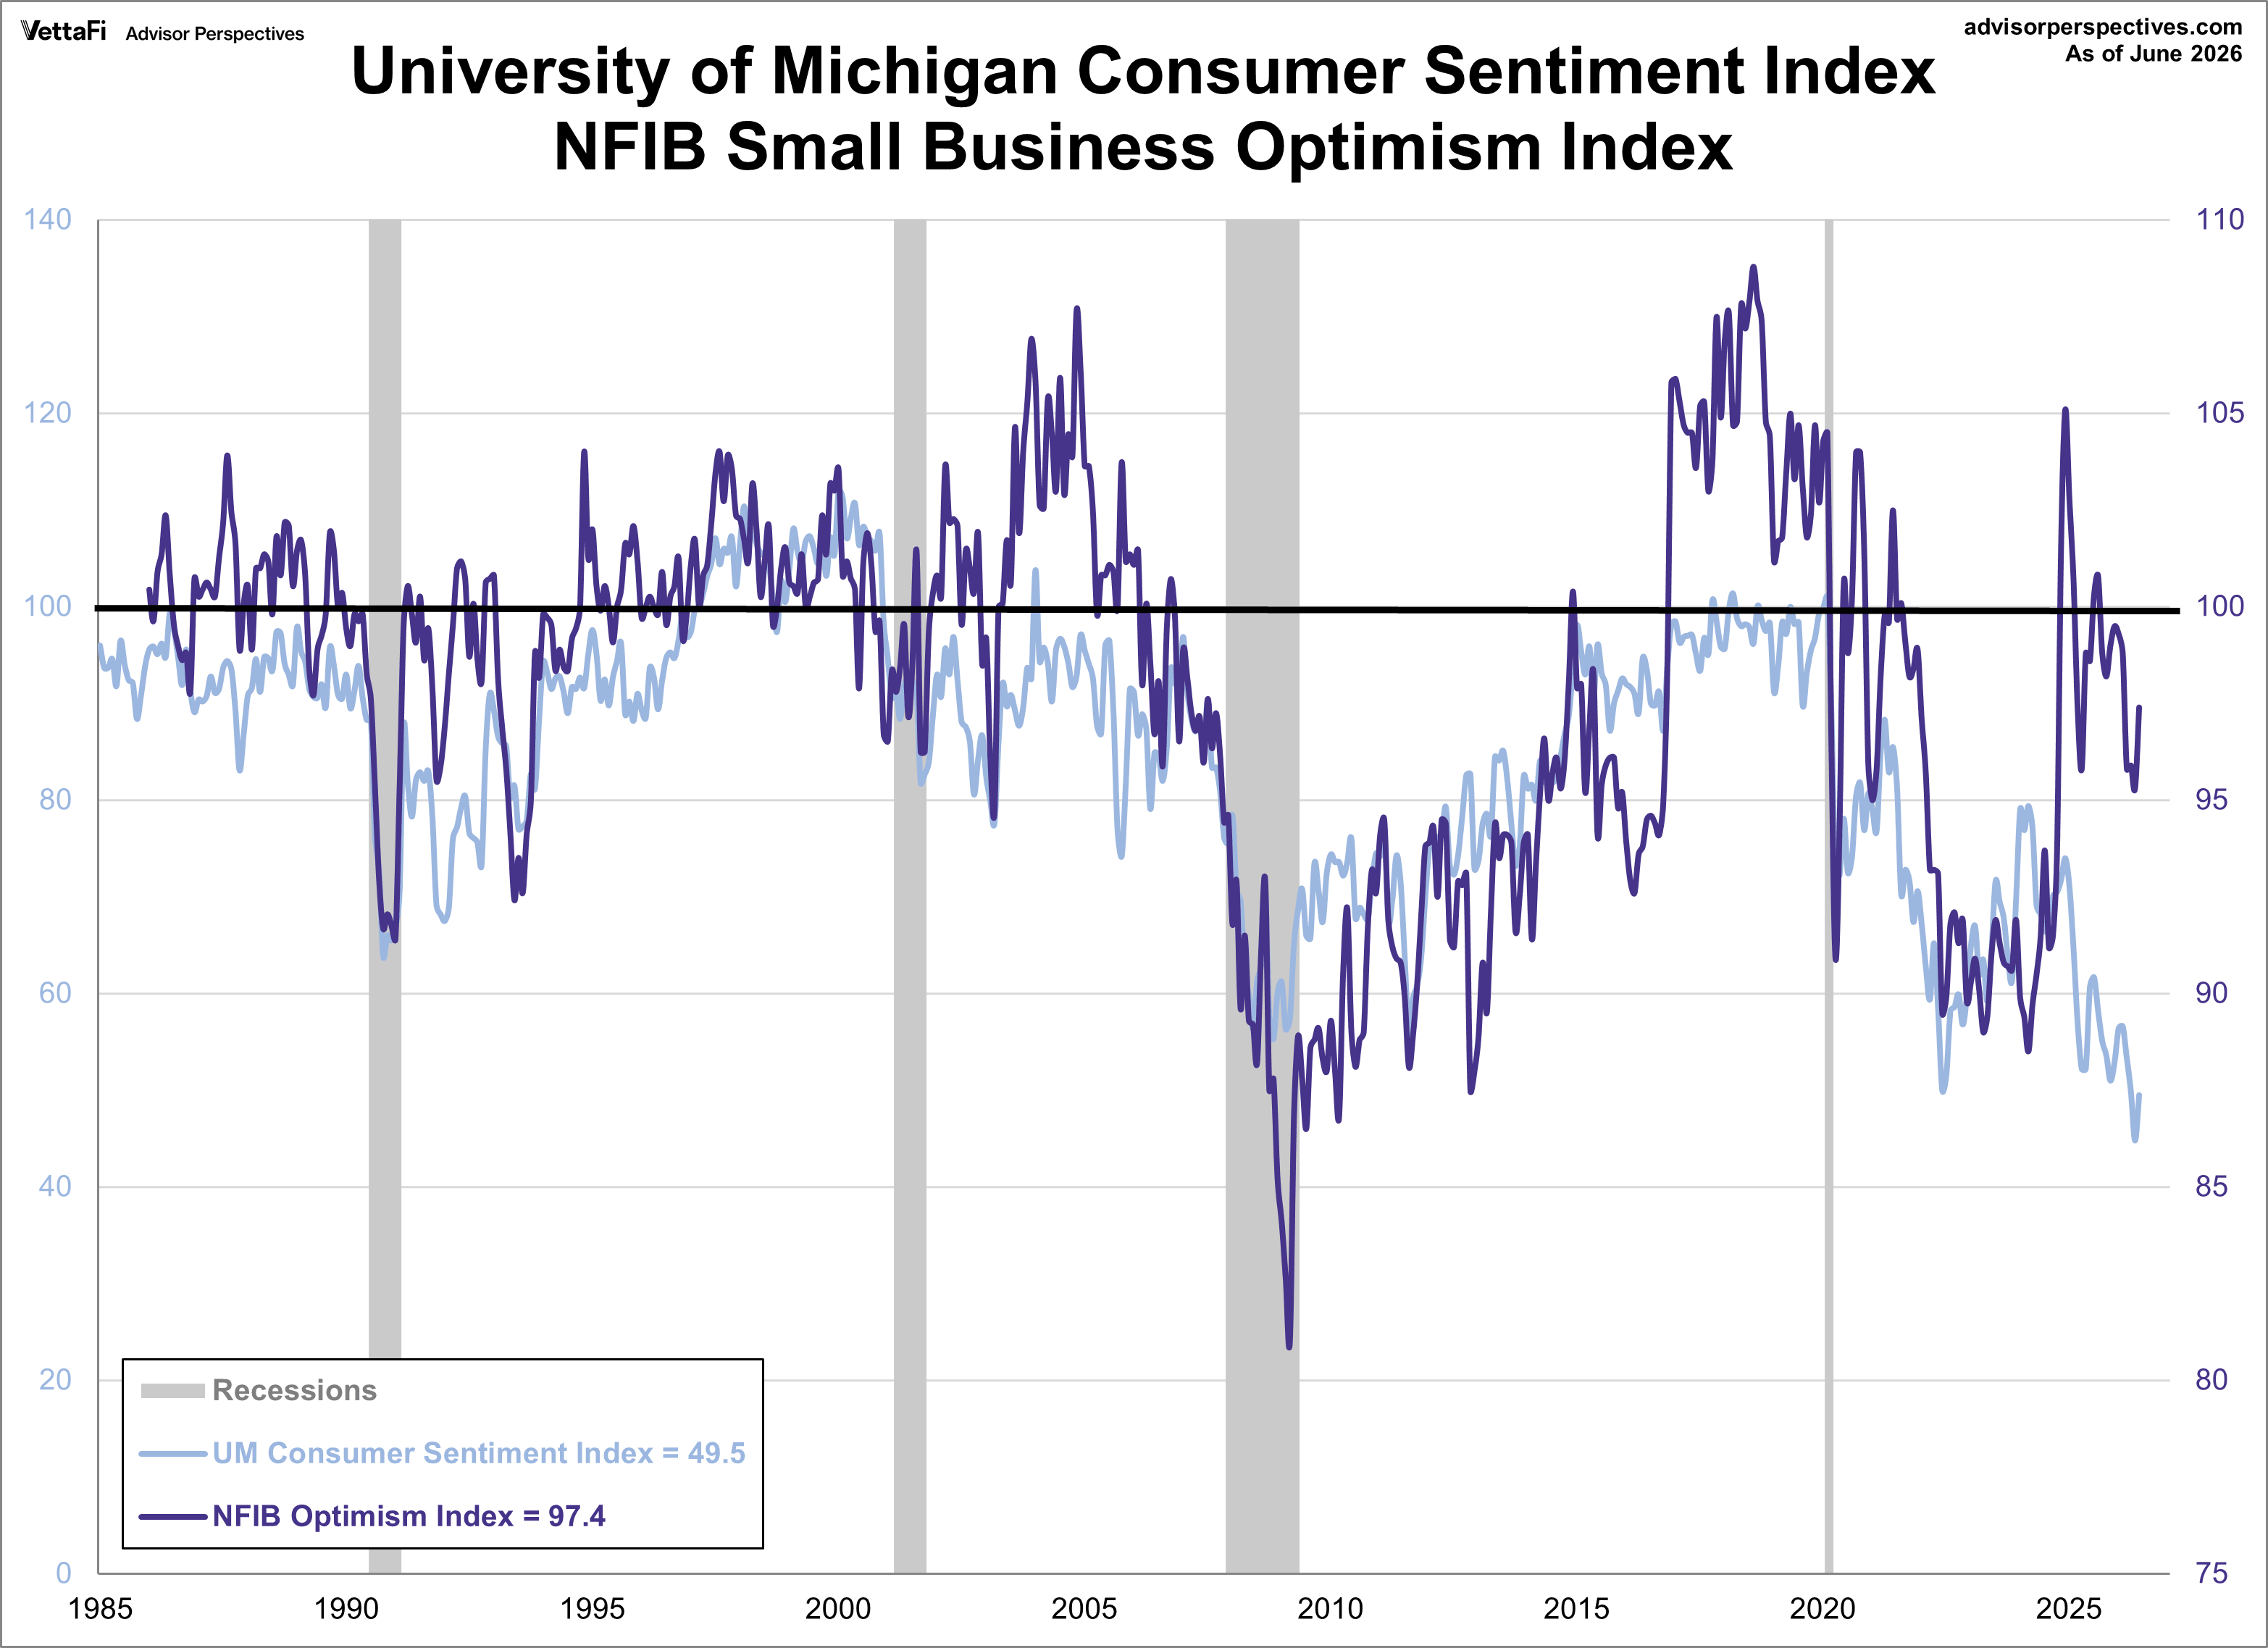
The Conference Board index is the more volatile of the two, but the broad pattern and general trends have been remarkably similar to the Michigan index.
And finally, the prevailing mood of the Michigan survey is also similar to the mood of small business owners, as captured by the NFIB business optimism Index (monthly update here).
ETFs associated with sentiment include: Consumer Discretionary Select Sector SPDR Fund (XLY).
Read more updates by Jen Nash