Key takeaways
- Infrastructure’s defensive characteristics, income potential and structural growth opportunities strengthen the case for a strategic portfolio allocation.
- We believe AI, electrification and network modernization are driving a multiyear investment cycle that can support growth in infrastructure earnings and dividends.
- Selectivity remains essential, as sound regulation, cost recovery and strong balance sheets help determine whether capital spending translates into shareholder returns.
Infrastructure has long been valued for its defensive characteristics, income potential and ability to protect against inflation. Essential assets such as electricity networks, pipelines, railways, airports and toll roads typically benefit from high barriers to entry and predictable revenues. Yet today’s opportunity extends beyond defense. Artificial intelligence (AI), data center construction, electrification, energy security and the modernization of aging networks are creating significant investment requirements. We believe this combination of resilience and structural growth suggests infrastructure may deserve a more strategic role in portfolios.
See more: AI: Where Will the Money Come From?
The Traditional Infrastructure Proposition
The defensive case for infrastructure should be familiar: Many infrastructure businesses provide essential services for which demand is relatively insensitive to economic conditions. Their revenues are often established through regulation, long-term contracts or concession agreements; this supports stable cash flows and dividends.
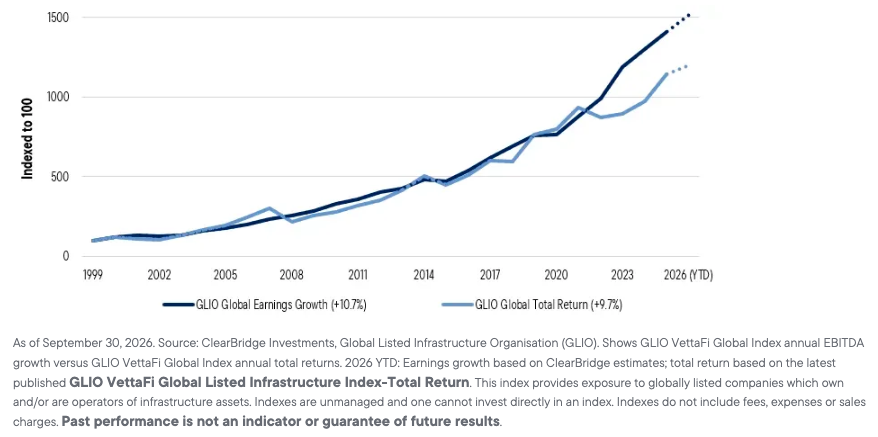
Infrastructure can also provide long-term inflation protection. Regulated utilities can recover prudently incurred expenditure through customer tariffs, while toll roads, airports and pipelines frequently have inflation-linked pricing mechanisms or contractual escalators. These adjustments can take time; meaning infrastructure share prices may initially weaken when inflation and bond yields rise. Over longer periods, however, higher costs and financing conditions can be reflected in tariffs, allowed returns and nominal earnings. Total returns for infrastructure have tended to follow earnings growth (Exhibit 1).
Exhibit 1: Earnings Growth, Not Yields, Drives Long-Term Results
The Emergence of a Structural Demand Cycle
Infrastructure capital expenditures are being driven by more than the replacement of existing assets, however. Electricity demand is accelerating as transport, manufacturing and heating become increasingly electrified, in part to allow renewable energy to power that electricity as part of the energy transition. Governments and companies are also seeking more secure and diversified energy supplies, while aging networks must be replaced and strengthened against extreme weather and other physical risks.
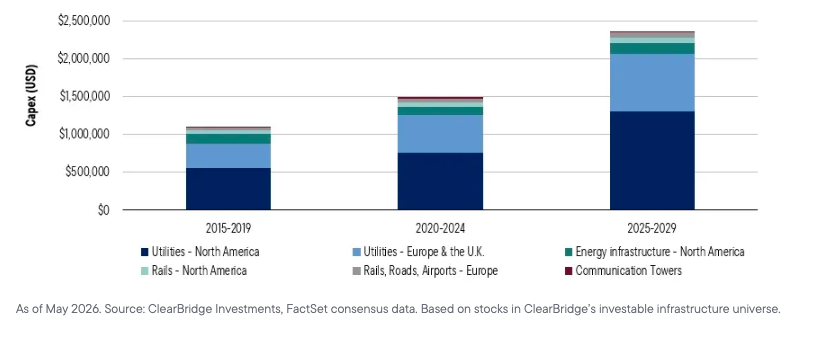
These forces are creating a broad investment cycle encompassing generation, transmission, distribution, pipelines, storage, railways and communications networks. ClearBridge believes infrastructure remains in the early stages of an accelerated investment cycle driven by rising energy demand, changing mobility needs, the evolving energy mix and network modernization (Exhibit 2). This investment can support multi-year growth in regulated asset bases, earnings and dividends.
Exhibit 2: Infrastructure Capex Super Cycle Is Just Beginning
AI, Electrification and the Grid
AI is commonly presented as a technology-sector opportunity, but its development also depends on physical infrastructure. Data centers require substantial electricity, together with transmission connections, substations, cooling systems, water, fiber networks and reliable backup generation.
This makes the electricity grid a critical link between several structural trends. Networks must connect new renewable generation, accommodate larger and less predictable loads and manage two-way flows created by distributed generation and storage. At the same time, data centers require dependable power around the clock, supporting investment not only in renewables but also in nuclear generation, natural gas infrastructure, battery storage and other sources of firm power.
The potential opportunity is significant, although it must be assessed selectively. Data center projects can face permitting delays, grid connection constraints and questions over who ultimately bears their costs. Expectations for hyperscaler demand may also prove too optimistic in some locations.
How Investment Becomes Earnings and Dividends
Large capital requirements do not automatically translate into shareholder returns. The crucial question is whether companies can invest at attractive returns and recover their costs through regulation or contracts.
For regulated utilities, approved expenditure generally expands the rate base on which the company earns an allowed return. Pipelines and other contracted assets can secure long-term customer commitments before construction begins. User-pays infrastructure may fund investment through tariffs linked to inflation or traffic volumes.
The quality of the regulatory framework, balance sheet and management team therefore matters as much as the size of the investment opportunity. Affordability is an important constraint; regulators and politicians must balance infrastructure reliability with the effect of higher tariffs on households and businesses. Poorly structured projects can leave shareholders carrying construction, financing or political risk. This argues for an active approach to investing in infrastructure.
Resilience Across Inflation and Interest-Rate Regimes
Listed infrastructure can be sensitive to changes in bond yields. Higher fixed income returns compete with infrastructure dividends, while rising discount rates reduce the present value of long-duration cash flows. This can create short-term pressure even when operating fundamentals remain sound.
Over time, however, the earnings response may become more supportive. Regulators can recalibrate allowed returns to reflect financing conditions, while contractual escalators and tariff reviews can raise nominal revenue. Existing assets may also become more valuable as replacement and construction costs increase. This is essentially a sequencing issue—valuation adjustments frequently occur before higher allowed earnings become visible.
The Case for a Strategic Allocation
Infrastructure should not be viewed simply as a bond proxy or a tactical shelter during equity-market weakness. Its potential portfolio role now combines essential service resilience, income, dividend growth, inflation linkage and participation in a long-duration capital investment cycle.
Nor is infrastructure a single macroeconomic trade. Regulated utilities, contracted pipelines and GDP-sensitive airports, railways and toll roads respond differently to changes in growth, inflation and interest rates. Diversification across these business models can create multiple sources of return.
The asset class’s traditional defensive foundation therefore remains relevant, but it is no longer the whole story. As infrastructure becomes essential to AI, digitalization, electrification, energy security and economic resilience, we believe its role is shifting from a peripheral diversifier to a strategic portfolio core.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
DEFINITIONS
A user-pays infrastructure model is a system where the direct users of a physical facility or service pay fees, tolls, tariffs, or user charges to cover its construction, operation, and maintenance, rather than relying purely on general taxpayer funds or government subsidies.
Listed infrastructure refers to publicly traded companies or investment trusts listed on major stock exchanges that own, manage, or operate essential physical infrastructure assets.
Hyperscalers are companies that own and operate massive data centers to provide highly scalable cloud computing services like Infrastructure as a Service (IaaS) and Platform as a Service (PaaS).
WHAT ARE THE RISKS?
All investments involve risks, including possible loss of principal. No assurance can be given that any forecast, projection or prediction regarding economies or financial markets will be realized.
Equity securities are subject to price fluctuation and possible loss of principal.
The allocation of assets among different strategies, asset classes and investments may not prove beneficial or produce the desired results.
Commodities and currencies contain heightened risk that include market, political, regulatory, and natural conditions and may not be suitable for all investors. To the extent the portfolio invests in a concentration of certain securities, regions or industries, it is subject to increased volatility.
Diversification does not guarantee a profit or protect against a loss. Dividends may fluctuate and are not guaranteed, and a company may reduce or eliminate its dividend at any time.
Companies in the infrastructure industry may be subject to a variety of factors, including high interest costs, high degrees of leverage, effects of economic slowdowns, increased competition, and impact resulting from government and regulatory policies and practices.
Important Information
This material is intended to be of general interest only and should not be construed as individual investment advice or a recommendation or solicitation to buy, sell or hold any security or to adopt any investment strategy. It does not constitute legal or tax advice. This material may not be reproduced, distributed or published without prior written permission from Franklin Templeton.
The views expressed are those of the investment manager and the comments, opinions and analyses are rendered as at publication date and may change without notice. The underlying assumptions and these views are subject to change based on market and other conditions and may differ from other portfolio managers or of the firm as a whole. The information provided in this material is not intended as a complete analysis of every material fact regarding any country, region or market. There is no assurance that any prediction, projection or forecast on the economy, stock market, bond market or the economic trends of the markets will be realized. The value of investments and the income from them can go down as well as up and you may not get back the full amount that you invested. Past performance is not necessarily indicative nor a guarantee of future performance. All investments involve risks, including possible loss of principal.
Any research and analysis contained in this material has been procured by Franklin Templeton for its own purposes and may be acted upon in that connection and, as such, is provided to you incidentally. Data from third party sources may have been used in the preparation of this material and Franklin Templeton ("FT") has not independently verified, validated or audited such data. Although information has been obtained from sources that Franklin Templeton believes to be reliable, no guarantee can be given as to its accuracy and such information may be incomplete or condensed and may be subject to change at any time without notice. The mention of any individual securities should neither constitute nor be construed as a recommendation to purchase, hold or sell any securities, and the information provided regarding such individual securities (if any) is not a sufficient basis upon which to make an investment decision. FT accepts no liability whatsoever for any loss arising from use of this information and reliance upon the comments, opinions and analyses in the material is at the sole discretion of the user.
Franklin Templeton has environmental, social and governance (ESG) capabilities; however, not all strategies or products for a strategy consider “ESG” as part of their investment process.
Products, services and information may not be available in all jurisdictions and are offered outside the U.S. by other FT affiliates and/or their distributors as local laws and regulation permits. Please consult your own financial professional or Franklin Templeton institutional contact for further information on availability of products and services in your jurisdiction.
Issued in the U.S. by Franklin Templeton, One Franklin Parkway, San Mateo, California 94403-1906, (800) DIAL BEN/342-5236, franklintempleton.com. Investments are not FDIC insured; may lose value; and are not bank guaranteed.
You need Adobe Acrobat Reader to view and print PDF documents. Download a free version from Adobe's website.
CFA® and Chartered Financial Analyst® are trademarks owned by CFA Institute.
More Economic Insights Topics >