Reasonable minds can disagree about the ideal scope of government, but no one argues against nations providing for their defense. As conflicts emerge and tensions rise, defense spending will take a larger role in all nations’ budgets, with effects that will flow across the economy.
While no one wishes for war, spending on national security creates jobs and may make nations more productive in peacetime. Research that starts in the defense sector can pay off broadly; the internet and GPS began as defense technologies.
The broader benefit (or drag) from this spending is known as a multiplier effect: does a dollar spent on defense generate more (or less) than a dollar of gross domestic product (GDP)? The defense spending multiplier can be greater than one, but not in all circumstances.
Import dependencies can turn defense spending into an economic drag. Military contracting is a concentrated sector. Major defense firms have been through decades of consolidation; smaller nations often lack domestic producers of arms and defense technology. More imports leave less upside to the domestic economy, with benefits accruing externally.
Procurement expenses must also be paid for upon receipt. If the expense is paid through higher taxes, it weighs on economic activity immediately. Funding with debt defers the downside but adds to longer-term burdens, especially in a higher-rate environment.
See more: Could the Dollar Be in Trouble – If So, What Then?
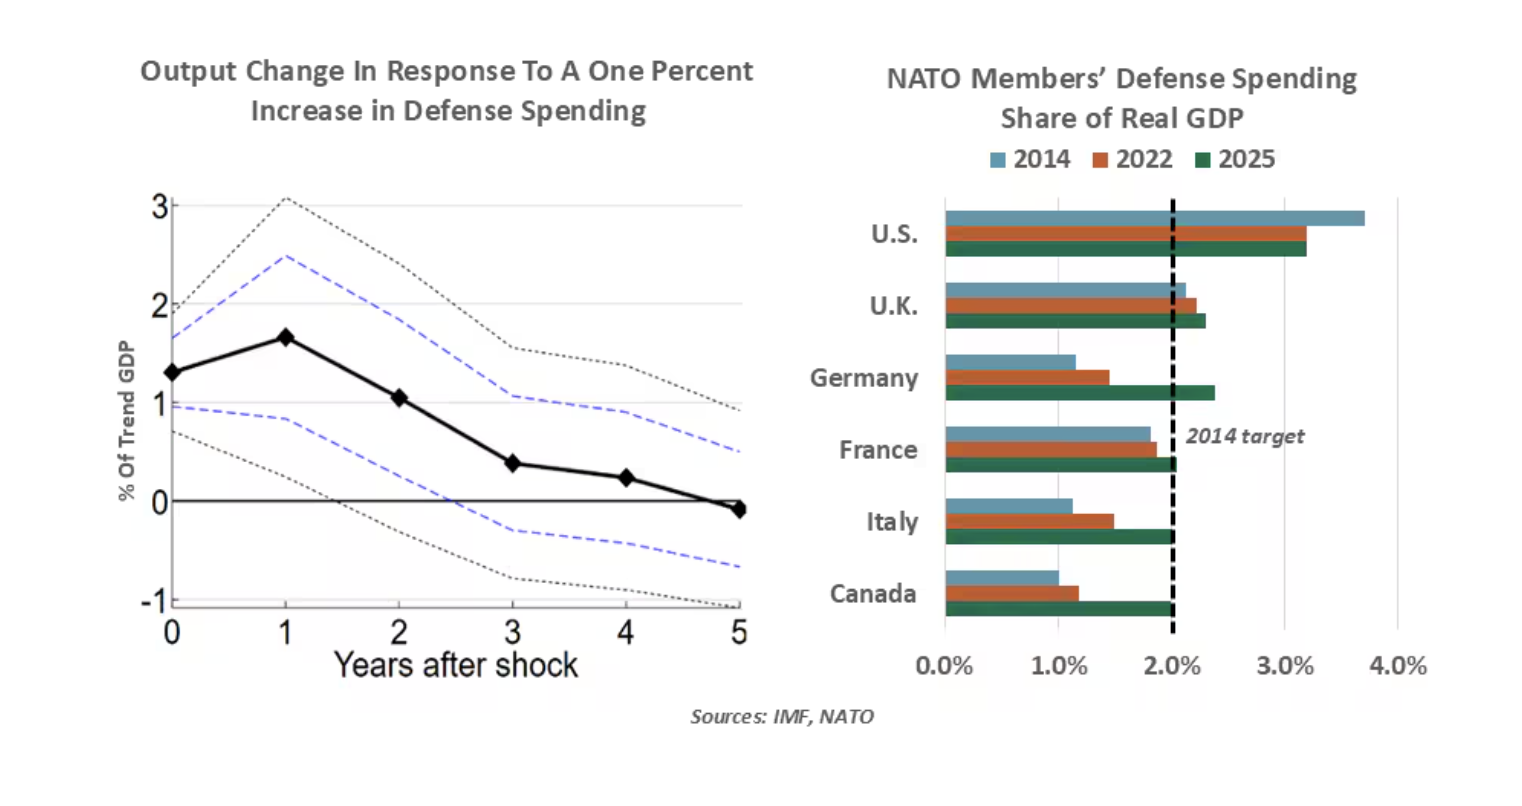
A comprehensive study of European defense spending since 1989 by the International Monetary Fund shows a sequential multiplier trend: A nation’s total output increases, peaking in the first year after a spending boost, with the effect fading to zero within five years.
Productive potential notwithstanding, defense investments are made in preparation for a darker turn. If conflict arises, the economic outlook for involved nations changes rapidly to a wartime footing. Government expenditure rises dramatically to recruit soldiers and acquire supplies, crowding out public spending on other budget categories. Though disruptive, the net effect is a near-term stimulus. Real GDP in Russia has grown in most quarters since 2022 (though Ukraine has not estimated its GDP since 2023).
Significant economic damage is done to nations near the war but not a party to it. Their trade routes may become unreachable; their residents may flee areas near the battlefront. This risk is most clearly manifest today in Middle East nations whose commerce has been impacted by the Iran conflict: Saudi Arabia’s GDP fell by 6.1% in the first half of 2026 and is still reeling.
Several areas of the world are set for substantial increases in their defense spending. Members of the North Atlantic Treaty Organization (NATO) agreed last year to expand their target military spending from 2% of GDP to 5% by 2035. Of that new higher threshold, 1.5 percentage points may be allocated to “broader defence- and security-related areas,” which can include infrastructure, communications networks and civil resilience.
Rearmament in the U.S. is coming into focus. The Iran conflict has consumed over three thousand advanced U.S. missiles. Each will cost at least $2 million (and at least 42 months) to replace. Improvements to shipbuilding capacity, cyber capabilities and greater deterrent weaponry will also add to spending demands.
The U.S. Department of Defense requested a record-high $1.5 trillion budget for fiscal 2027. The approved value will likely be lower, but no less than last year’s $839 billion appropriation. With a heavily domestic defense supply chain, this spending will be accretive to U.S. economic activity. However, this will add to the U.S. debt burden just as borrowing costs come under closer scrutiny.
As fiscal pressures increase, policymakers will look for opportunities to cut budgets. Defense spending will be the least likely to face reductions. In the absence of national security, economic security cannot be achieved.
Ryan James Boyle is the Chief U.S. Economist within the Global Risk Management division of Northern Trust.
Information is not intended to be and should not be construed as an offer, solicitation or recommendation with respect to any transaction and should not be treated as legal advice, investment advice or tax advice. Under no circumstances should you rely upon this information as a substitute for obtaining specific legal or tax advice from your own professional legal or tax advisors. Information is subject to change based on market or other conditions and is not intended to influence your investment decisions.
© 2026 Northern Trust Corporation. Head Office: 50 South La Salle Street, Chicago, Illinois 60603 U.S.A. Incorporated with limited liability in the U.S. Products and services provided by subsidiaries of Northern Trust Corporation may vary in different markets and are offered in accordance with local regulation. For legal and regulatory information about individual market offices, visit northerntrust.com/terms-and-conditions.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© Northern Trust
More Alternative Investments Topics >