Middle Eastern oil exports are approaching pre-war levels, but oil prices certainly aren’t. Brent remains above $100 a barrel, as the concern increasingly is not just how much oil is flowing today, but how much is left in reserve if supplies are disrupted again.
At the start of October, the Group of Seven nations pledged to release 100 million barrels of crude oil and diesel to cool prices. So far, markets appear unimpressed.
See more: Higher Oil Prices and Inflation Concerns Weigh on Both Bonds and Stocks
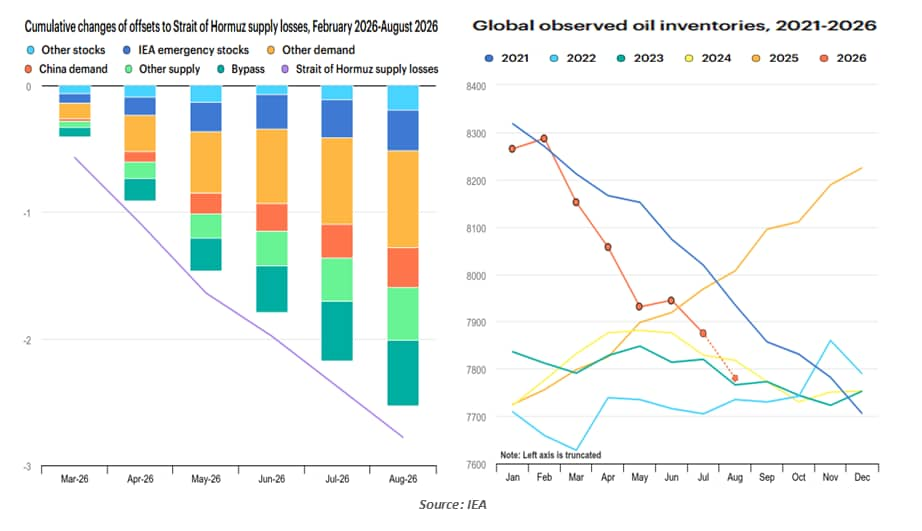
Since the Middle East conflict began, governments and energy companies have drawn heavily on stockpiles to compensate for disrupted supplies. According to the International Energy Agency, observed global inventories fell by 507 million barrels between February and August, an average draw of 2.8 million barrels a day. August alone accounted for a depletion of 95 million barrels. U.S. Strategic Petroleum Reserve crude stocks are around their lowest level since the start of available data in 1982. Commercial inventories have also been drawn down globally.
The pressure is even greater further down the barrel. Lost Middle Eastern and Russian refined product exports, stretched refining capacity and elevated freight costs have pushed diesel and jet fuel prices sharply higher. Diesel, which accounts for nearly 30% of global demand, surpassed $200 a barrel in the U.S. in early September, nearly double pre-war levels; Europe and Asia were not far behind. Jet fuel prices have also been hovering around $200 per barrel.
Saudi Aramco’s CEO has warned that inventories could take up to two years to replenish, leaving markets vulnerable to another interruption. President Trump announced a plan for Russia to supply about 30 million barrels of diesel to the global market over the coming weeks and months. But the additional supply is unlikely to move the needle. The world consumes roughly 855 million barrels of diesel every month.
This creates a difficult trade-off. Drawing on reserves can buy time and take some heat out of prices today. But every barrel released means a little less insurance against tomorrow’s disruption.
Information is not intended to be and should not be construed as an offer, solicitation or recommendation with respect to any transaction and should not be treated as legal advice, investment advice or tax advice. Under no circumstances should you rely upon this information as a substitute for obtaining specific legal or tax advice from your own professional legal or tax advisors. Information is subject to change based on market or other conditions and is not intended to influence your investment decisions.
© 2026 Northern Trust Corporation. Head Office: 50 South La Salle Street, Chicago, Illinois 60603 U.S.A. Incorporated with limited liability in the U.S. Products and services provided by subsidiaries of Northern Trust Corporation may vary in different markets and are offered in accordance with local regulation. For legal and regulatory information about individual market offices, visit northerntrust.com/terms-and-conditions.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© Northern Trust
Read more commentaries by Northern Trust