Long before modern scanners and monitors became common, doctors often checked a patient's health with something as simple as a finger on the wrist. A pulse could reveal a surprising amount about a person's condition. Economists have their own version of this practice. Rather than relying solely on complex statistical models, they often look for signals that offer a quick health check.
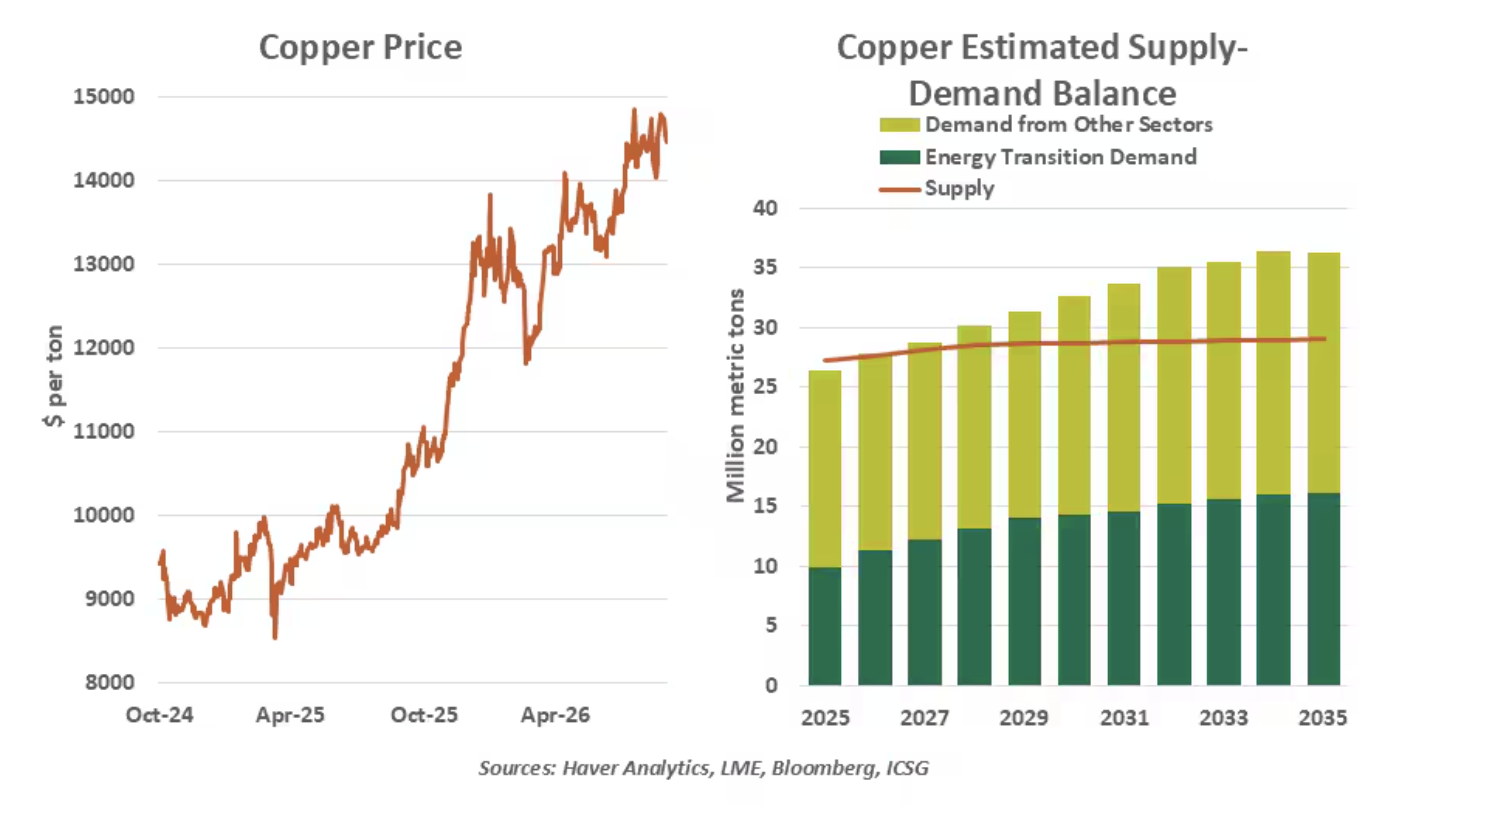
For decades, copper has been one of those barometers. Traders even dubbed it "Dr. Copper" for its perceived ability to diagnose the state of the world economy. Today, however, the red metal is signaling more than the economy's pulse. Prices have climbed more than 40% over the past year to reach record highs, reflecting a growing recognition that demand is changing in ways that may prove more durable, while supply is becoming harder to expand.
Historically, copper demand has largely tracked construction and industrial activity. Those drivers remain important, but the need is evolving. Once considered a cyclical commodity, copper is increasingly taking on strategic value. Every major trend shaping the modern economy requires more of it. The rapid buildout of data centers to support artificial intelligence is creating a substantial source of demand that barely existed a decade ago. Electric vehicles use significantly more copper than conventional automobiles. Renewable energy systems and expanding power grids require vast quantities of the metal. As a result, copper usage may be losing its link to the traditional business cycle.
China remains the world's largest copper user, accounting for more than half of global copper consumption. But the next phase of demand growth appears increasingly global. Massive investments in data centers and power infrastructure in countries like the United States, the energy transition in Europe, and India's push to modernize its electricity network and manufacturing base are all expected to compete for the world’s supply.
Copper mining is highly concentrated, with Chile and Peru accounting for roughly two-fifths of global mine production. Chile, the world's largest producer, has struggled with operational disruptions and declining ore grades in recent years. Many of the world's largest copper mines are ageing.
See more: The Dollar Is Older Than Shakespeare
Large copper deposits remain to be developed, particularly in Latin America and Africa. Bringing additional supply to market, however, is slow, costly and exposed to a multitude of risks. Copper projects are among the most expensive and time-consuming in the mining industry. Environmental approvals can take years, with local opposition becoming more common.
Trade policy has added another wrinkle. Expectations that the U.S. could impose tariffs on refined copper prompted a rush of shipments into the United States earlier this year. This drew inventories away from other markets.
These pressures are increasingly reflected in long-term forecasts. According to BloombergNEF, the global copper market is expected to move into a supply deficit beginning in 2026 and remain undersupplied throughout the next decade. Yet the nature of the challenge differs across countries. For the United States, the bottleneck lies less in securing raw copper than in refining and processing it. China faces the opposite problem. Despite its dominant position across many critical mineral supply chains, it remains heavily dependent on imported unrefined copper, creating a rare strategic vulnerability in an area where it otherwise enjoys considerable leverage.
Copper sits quietly at the center of many of the world's economic ambitions. The challenge is that technological progress can move quickly, while expanding resource supply rarely does. Just as a physician once learned a great deal from a patient's pulse, copper's recent strength offers a simple but revealing signal.
Vaibhav Tandon is the Chief International Economist within the Global Risk Management division of Northern Trust.
Information is not intended to be and should not be construed as an offer, solicitation or recommendation with respect to any transaction and should not be treated as legal advice, investment advice or tax advice. Under no circumstances should you rely upon this information as a substitute for obtaining specific legal or tax advice from your own professional legal or tax advisors. Information is subject to change based on market or other conditions and is not intended to influence your investment decisions.
© 2026 Northern Trust Corporation. Head Office: 50 South La Salle Street, Chicago, Illinois 60603 U.S.A. Incorporated with limited liability in the U.S. Products and services provided by subsidiaries of Northern Trust Corporation may vary in different markets and are offered in accordance with local regulation. For legal and regulatory information about individual market offices, visit northerntrust.com/terms-and-conditions.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
© Northern Trust
More Tax Planning Topics >