The secular theme of Geopolitical Fragmentation has roots in the shift to a multipolar world order where governments and companies are placing more weight on security, resilience, and political alignment when making trade and investment decisions.
In our view, globalization is being reorganized, not reversed, and could make growth, inflation, and corporate earnings more volatile. Duplicated capacity, larger inventories, and higher-cost supply chains may improve resilience but reduce efficiency.
Fragmentation does not call for major changes to strategic portfolios. Rather, it may strengthen the case for diversification and more active positioning across countries, sectors, and companies as investment opportunities shift.
From globalization to fragmentation
Geopolitical fragmentation is redirecting trade, investment, technology, and supply chains toward national security and strategic resilience. Globalization is not ending, but its structure is changing. Some cross-border ties may weaken while others could deepen within regions or among politically aligned power blocs.
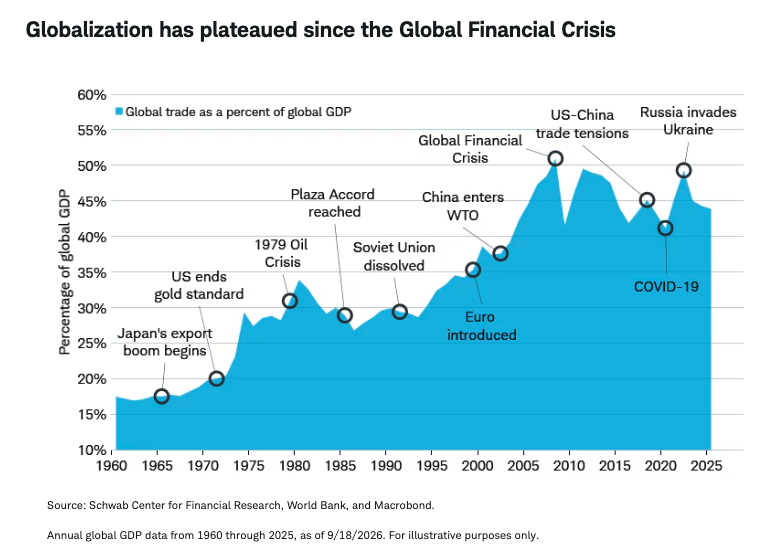
For much of the period between the end of the Cold War and the Global Financial Crisis (GFC), the United States sat at the center of a largely unipolar geopolitical system, where no other country or regional bloc commanded comparable military, economic, or political power. During this time, international institutions helped establish common rules, China's 2001 entry into the World Trade Organization accelerated globalization, and supply chains expanded rapidly.
That model began to change after the GFC. The COVID-19 pandemic, Russia's invasion of Ukraine, conflict in the Middle East, and intensifying competition between the United States and China exposed the risks of relying on a limited number of suppliers, transport routes, technologies, and energy sources. Governments and companies responded by placing greater value on national interests, strategic reserves, and domestic capacity, ushering in an era of greater strategic competition.
Why has the world become more multipolar?
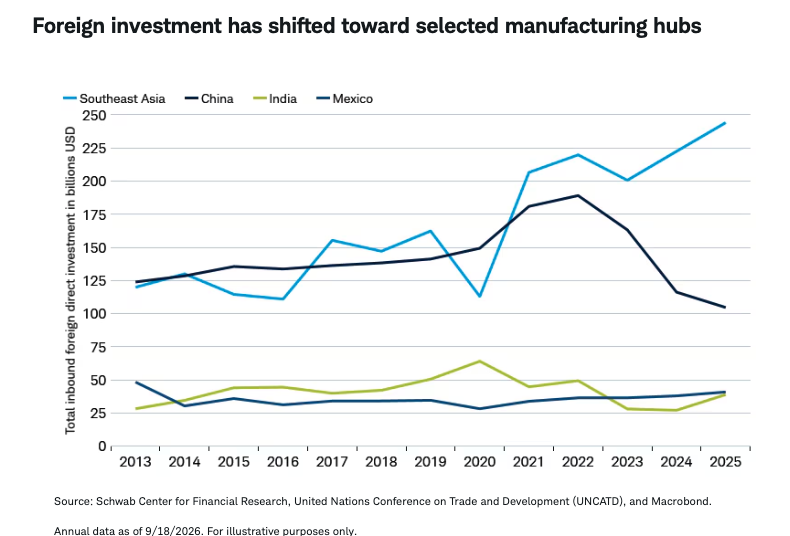
Economic and strategic influence has broadened beyond the United States. China has developed from an export manufacturing hub into a strategic competitor in technology, artificial intelligence (AI), industrial manufacturing, clean energy, critical minerals, and defense. India and Southeast Asia account for a growing share of manufacturing, trade, and technology activity, while Middle Eastern countries, Brazil, and Mexico have gained influence through their commodity resources.
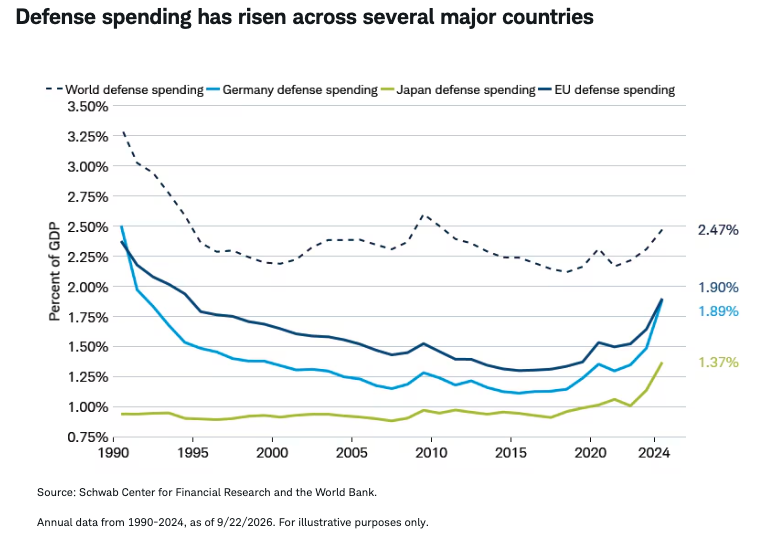
The role of multilateral institutions is also changing. Within NATO, according to the Associated Press, public debates over burden-sharing between country leaders have contributed to higher defense-spending commitments across several major economies as governments respond to a more contested security environment.
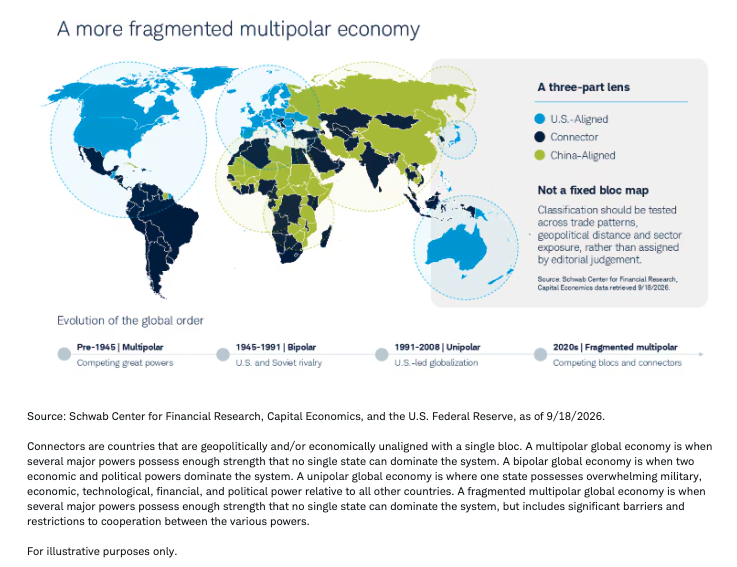
Today's alignments are unlikely to resemble the two-sided structure of the Cold War. Many countries may trade with both the United States and China while pursuing their own economic and security priorities. The result is a more complex system in which geopolitical considerations may have a greater influence on long-term investment risks and opportunities.
From a unipolar system to regional power blocs
Transitions between geopolitical systems can be unstable because established and rising powers compete over security, technology, resources, and influence, according to historians and geopolitical experts. Recent increases in armed conflict and defense spending are consistent with that broad risk, although they do not prove that multipolarity is the sole cause.
Economic growth may become more uneven
The global economy can continue to grow in a more fragmented system, but regional business cycles may become less synchronized. Globalization helped connect production, trade, and demand during the 1990s and 2000s leading to a more synchronized global business cycle. Since the GFC, slower trade integration, more domestically focused policies, and greater trade tension have contributed to wider regional differences.
Supply chains are also shifting through reshoring, nearshoring, and friend-shoring. These strategies move production closer to home, to nearby markets, or to trusted trading partners. They may improve resilience, but they also raise costs. Duplicated manufacturing capacity, larger inventories, new transport routes, higher-cost labor, and higher-tax jurisdictions can weigh on profitability.
Technology may offset part of that burden. AI, robotics, 3D printing, and automation can help companies redesign production processes and reduce some relocation costs.
Globalization is unlikely to reverse. Trade relationships are deeply established and remain economically productive, especially within regions and among aligned countries. We expect trade and investment to be rerouted rather than sharply reduced.
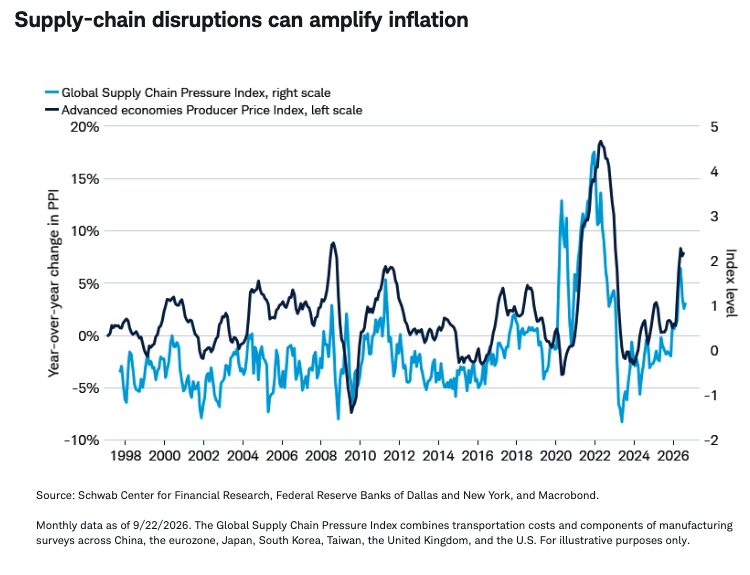
A more severe risk would emerge if geopolitical tension or abrupt trade restrictions disrupted supply chains. The immediate effects could include goods shortages, inflation spikes, and weaker growth. New investment opportunities could follow as companies and governments adjust, but the transition would likely be costly.
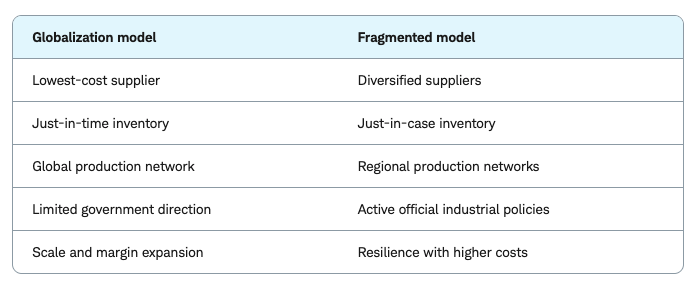
What are some differences in global trade between the globalization and fragmented periods?
Where could capital spending shift?
Corporate strategy is shifting from just-in-time efficiency toward a balance of cost, security, and continuity. Firms may diversify suppliers, build regional production networks, hold more inventory, or bring selected operations closer to end markets. Some may invest more heavily in automation to offset higher labor costs.
Government policy is becoming a more important influence on capital allocation. Defense readiness, energy security, semiconductor capacity, infrastructure, and access to critical materials are now economic and national security priorities. Public incentives may support investment, but they do not remove execution risk, valuation risk, or the possibility of excess capacity.
Economic outcomes are unlikely to be evenly distributed. Infrastructure, workforce skills, trade access, energy availability, policy stability, and links to existing networks will help determine which countries capture lasting investment. Countries able to trade across several blocs may serve as important connectors.
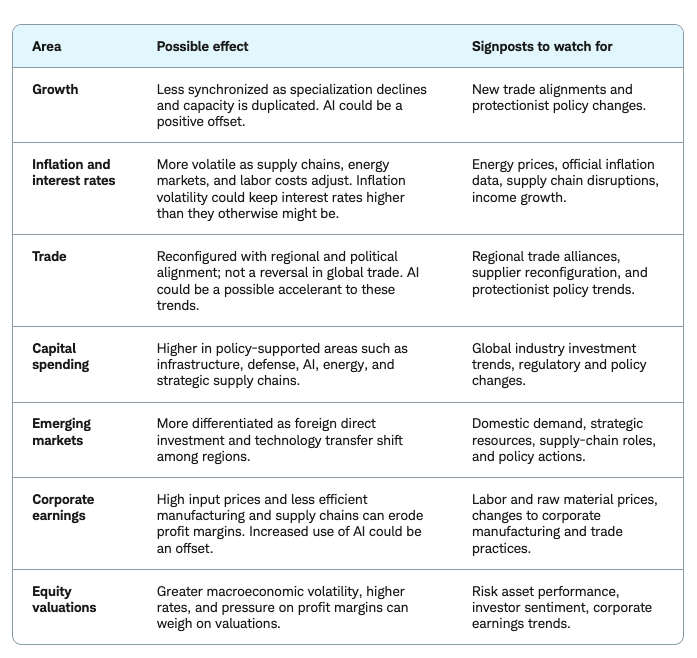
How fragmentation may affect the global economy and investors
Potential investment opportunities
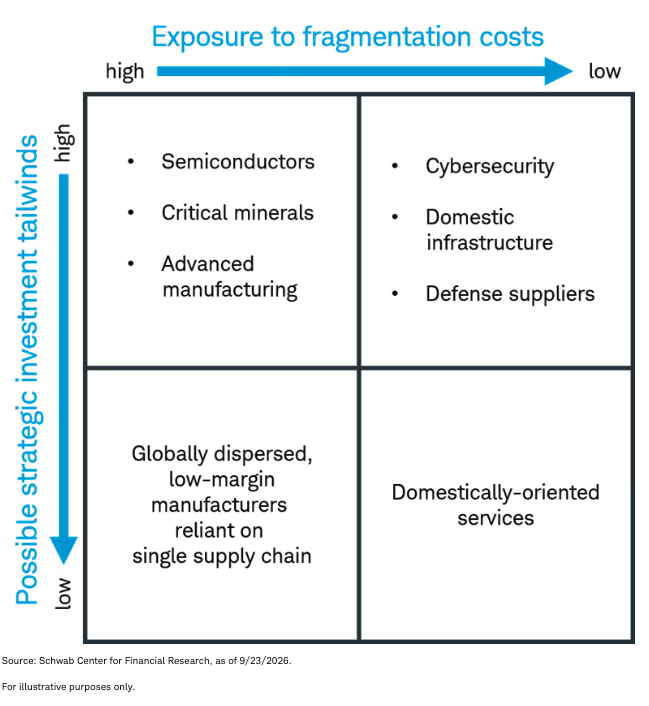
Geopolitical fragmentation is already driving shifts in capital spending that could continue for an indefinite period. The list below provides examples of areas that may offer potential investment opportunities, but they are not investment recommendations. Policy support can encourage spending and attract capital, yet it can also draw new competitors and create excess capacity. Fragmentation may improve the economics of some companies while weakening the economics of others. We suggest investors still evaluate individual companies carefully as not every company tied to these themes will benefit equally.
Defense and security: Higher spending on military readiness, aerospace, drones, space systems, and cybersecurity may support suppliers in the United States, Europe, and Asia.
Energy and power infrastructure: Energy, security and rising electricity demand may require investment across power generation and transmission, natural gas, nuclear power, and renewables. Supply shocks could cause disruption similar to what we're seeing today with the Iran war.
Technology: Efforts to participate in the growth of new technologies like AI have driven increased investment in domestic capacity of semiconductor equipment, fabrication, advanced packaging, data centers, AI infrastructure, and industrial automation. Statements from governing officials in the U.S., China, and other major countries cite these efforts as national security priorities.
Infrastructure and logistics: New factories and regional supply networks require engineering, construction, electrical equipment, industrial real estate, ports, transportation, and distribution capacity.
Critical materials: Competition for copper, lithium, rare earths, uranium, and processing capacity may raise the strategic value of resource-rich countries and the companies that produce or refine these inputs.
Digital services: Software, cloud infrastructure, and cybersecurity may face fewer physical trade frictions than goods, although data rules, export controls, and security requirements could still divide technology ecosystems.
Fragmentation creates trade-offs rather than clear winners
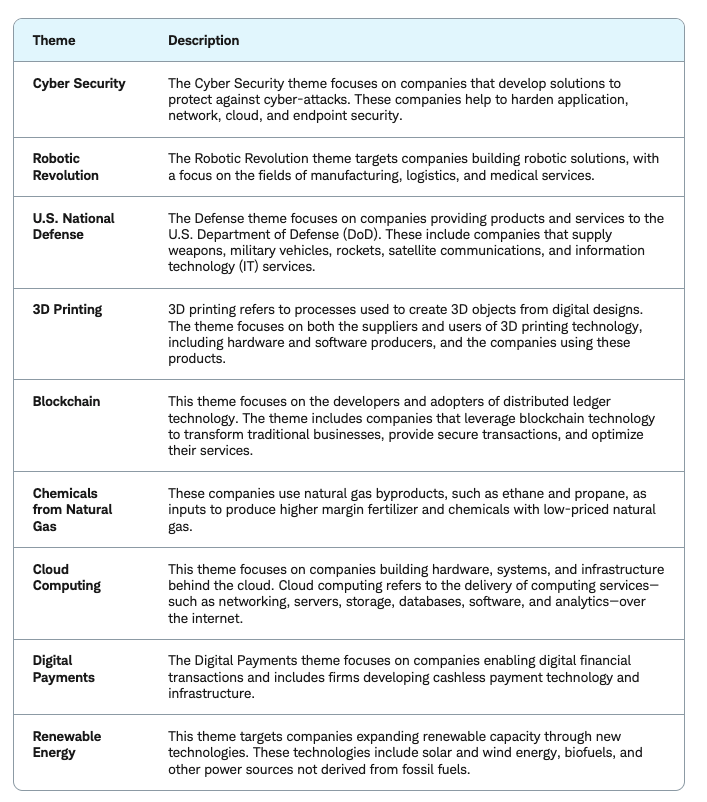
Exploring thematic investing
Thematic investing is a way for investors to invest in themes that tie to their ideas, personal values, or trends that don't necessarily fit into existing industry classifications.
Below is a sampling of investing themes that are directly or indirectly related to Geopolitical Fragmentation.
Sample investment themes related to Geopolitical Fragmentation
What could impede or accelerate fragmentation?
The pace of further geopolitical fragmentation is uncertain. On one side, the economic costs of rapid fragmentation are high. Existing financial and commercial ties tend to be difficult to unwind, and companies have strong incentives to preserve access to efficient global customers and suppliers. Productivity gains from technological advances—such as AI and automation—could offset some transition costs.
A more severe break between major blocs could accelerate change. Abrupt restrictions on energy, commodities, semiconductors, or other critical inputs could produce shortages, higher inflation, and weaker growth. The effects would depend on the breadth and duration of the disruption.
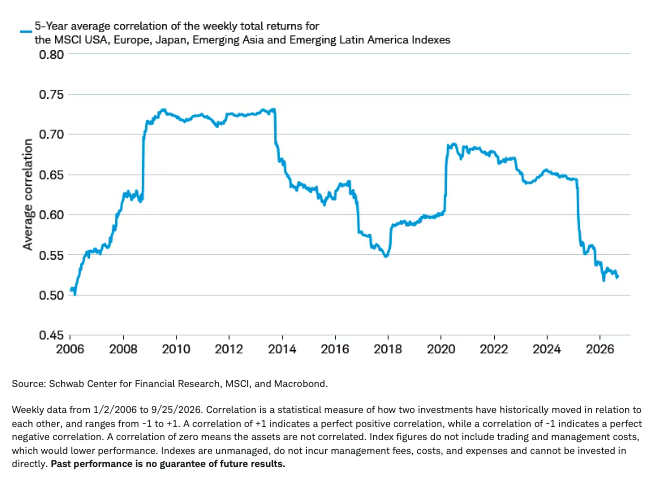
Regional equity correlations have declined from recent peaks
What should investors consider?
A multipolar world does not call for changes to strategic portfolio construction. It may strengthen the case for diversification across regions, sectors, asset classes, and economic drivers. If growth and inflation become less synchronized, and new trading alliances are formed, differentiated geographic exposures may provide access to different sources of return and risk.
Investors may also look beyond broad market exposure to more targeted opportunities. Supply-chain position, end-market exposure, access to strategic inputs, pricing power, and sensitivity to government policy may become more important in separating potential winners from losers. The investment needed to reconfigure production may support nominal economic growth, but higher operating and investment costs could weigh on companies' inflation-adjusted profits.
The broad Geopolitical Fragmentation investing theme has many facets and is one that we'll be monitoring going forward. Globalization is unlikely to end, but any reorganization of it may tend to make the global economy less efficient and less synchronized. The effects will vary across countries, industries, and companies. Investors are unlikely to need to rebuild portfolios around any singular geopolitical theme or forecast. Broad diversification and careful analysis of policy, supply-chain, and geopolitical exposures remain the more durable response.