Do Munis Still Deserve a Place in Your Portfolio?
Membership required
Membership is now required to use this feature. To learn more:
View Membership BenefitsKey takeaways
- Municipal bonds (munis) have stumbled recently as Treasury yields have moved higher, but we still believe they can play an important role for investors seeking relatively conservative, tax-advantaged income.
- Higher yields can be painful in the short run because bond prices fall when yields rise, but they might also improve the income potential and may support longer-term total returns.
- We suggest investors stay selective and consider a slightly shorter-than-benchmark duration, focus on higher-quality issuers, and watch whether demand can absorb elevated municipal bond supply.
Municipal bonds started the year on solid footing, but recent performance may have been frustrating for many investors. Year-to-date, the broad muni market is down 1.7%, compared with a 1.4% decline for U.S. Treasuries. That modest decline masks a sharper reversal: Munis were up 2.3% as of July 6, 2026, before rising rates weighed on returns. For investors who bought municipal bonds for stability and tax-advantaged income, the recent pullback may feel especially disappointing.
Municipal bond returns are down for the year, which is a reversal from earlier this year

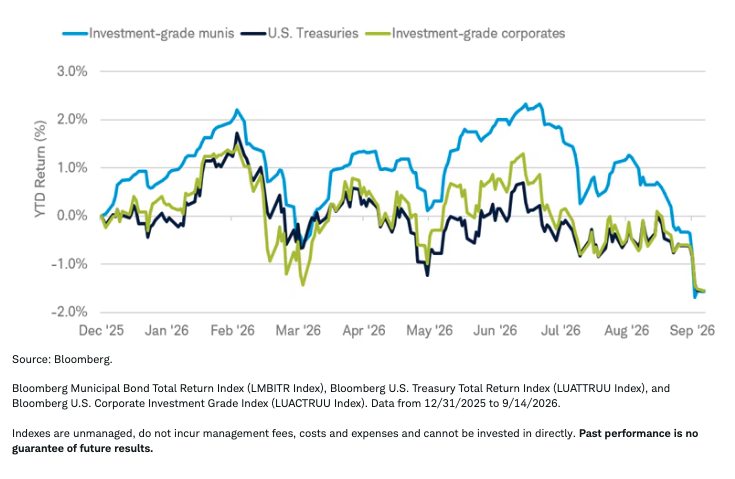
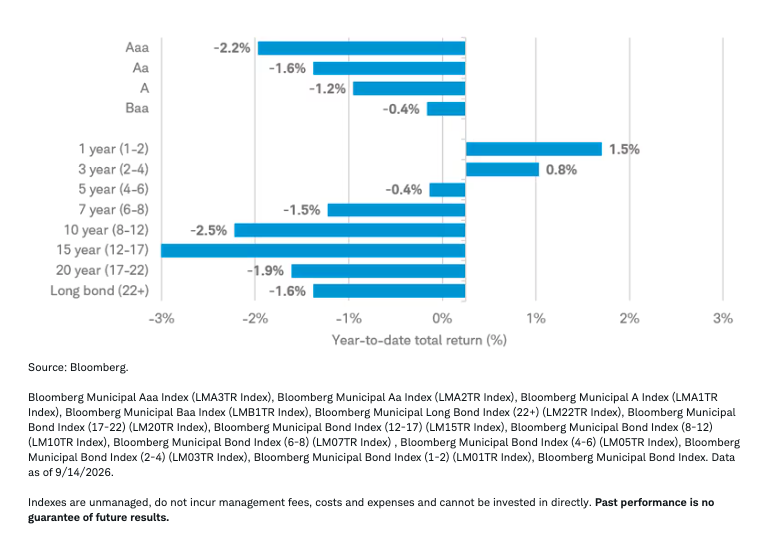
Under the surface, performance has varied. Shorter-term and lower-rated issuers have generally held up better than longer-term and higher-quality parts of the market. The primary reason for the recent slump has been rising Treasury yields. From February 27, 2026, the day before the Iran war began, through September 14, 2026, the 10-year Treasury yield rose from 3.9% to 5.0%, an increase of roughly 110 basis points. Over the same period, a generic index of 10-year AAA-rated1 munis increased from 2.5% to 3.7%, an increase of roughly 120 basis points—a contributing factor to munis underperforming Treasuries during that period.
See more: Should You Consider High-Yield Municipal Bonds?
Shorter-term and lower-rated munis are generally outperforming their counterparts this year
That move reflects a meaningful shift in fed funds rate expectations. Earlier in the year, markets were anticipating rate cuts in 2026; more recently, expectations have moved toward the possibility of rate hikes instead. Although the Federal Reserve directly controls short-term rates, it can also influence longer-term rates. When interest rates rise, bond prices generally fall, and longer-duration bonds tend to be more sensitive to those moves.
Given that backdrop, some investors may understandably be asking whether municipal bonds still deserve a place in their portfolios. We believe they might, particularly for those investing in a taxable account and looking for a relatively conservative investment option that produces tax-advantaged income. Municipal bonds, historically, have less volatility and default risk relative to corporate bonds of similar maturities. But the path may remain uneven, and investors should be thoughtful about where they find opportunities.
In our view, the answer depends less on the recent muni price declines and more on what role munis are meant to play. Municipal bonds are not designed to be return-maximizing assets. They are generally used to provide income, help preserve capital, and potentially reduce the tax burden for investors in higher tax brackets. When evaluated through that lens, the case for munis looks more constructive than recent performance alone might suggest.
Why munis can still make sense
There are two main reasons we believe municipal bonds can still make sense for more conservative investors: attractive tax-advantaged income and relatively stable credit quality. Neither eliminates short-term volatility, but both remain important longer-term supports.
We should not dismiss the recent weakness. Rising yields can create real mark-to-market losses, and those losses can be uncomfortable. However, focusing only on recent price declines can obscure one of the more important features of bonds: income. Unlike stocks, where returns depend heavily on price appreciation and dividends that can change, most municipal bonds make fixed interest payments, assuming the issuer doesn't default.
1. Try to look past short-term performance
Short-term losses can feel uncomfortable, especially in an asset class many investors view as defensive. But negative performance during the year has not always translated into negative performance for the full year. Since 2004, the broad municipal bond index has been negative at some point during the year in 17 instances. In 12 of those 17 years, the index went on to post a positive total return for the full year.
In the past, there have been instances where munis have declined during the year, then recovered to have a positive annual total return
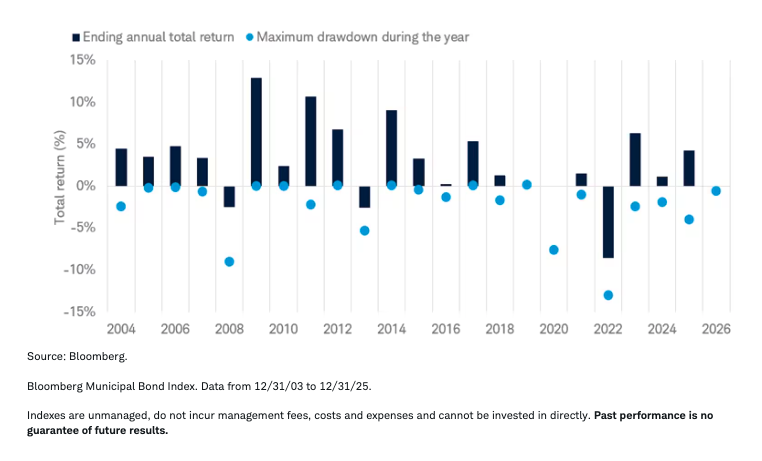
This point is particularly important for investors who do not need to sell immediately. If an investor has a reasonable time horizon and owns a diversified portfolio of higher-quality bonds or bond funds, the income generated over time may help offset some of the price volatility that occurs when rates move higher.
While past performance is no guarantee of future results, history illustrates why time in the market can matter. The longer an investor remains invested, the greater the potential for coupon income to build and help offset periods of negative price performance.
Higher yields have caused prices to move lower and total returns to suffer, but higher yields also improve the income backdrop going forward. Historically, coupon income has been the largest contributor to muni total returns over time and has helped offset negative price returns. For example, over the past 30 years, the price return for the Bloomberg Municipal Bond Index has been negative in 14 years. However, coupon income has always been positive and helped offset those declines, such that the index had a negative total return in only four instances since 1996.
Coupon income has historically made up the bulk of total returns and has helped to buffer negative price performance
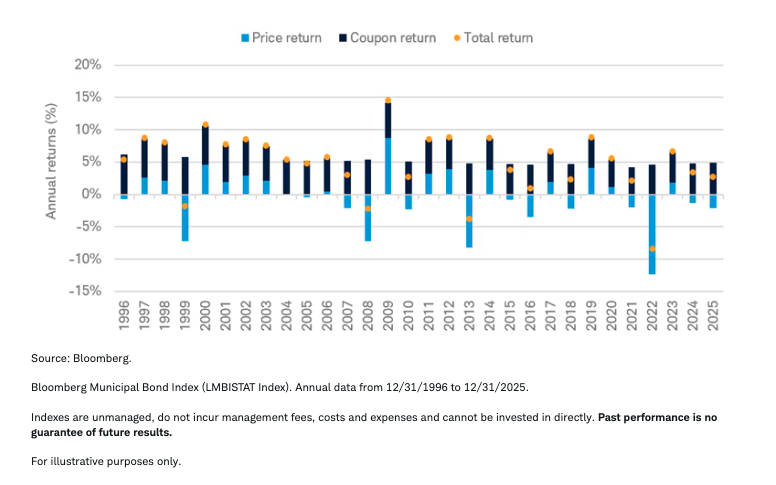
That is why we think the recent rise in yields is a double-edged sword. It has hurt recent returns, but it has also improved the income available today. For investors adding new money, reinvesting coupon income, or gradually building a muni allocation, higher starting yields can also be a benefit rather than only a problem.
2. Tax-advantaged income may remain attractive
Higher yields may not only be a positive for returns going forward; they can also be a welcome sign for investors focused on the income that munis pay. The yield to worst (the lowest possible yield an investor can receive from a callable bond, barring default) of the Bloomberg Municipal Bond Index was about 4.3% as of September 10, 2026. For an investor in the top federal tax bracket, that's roughly equivalent to a 7.2% yield on a fully taxable bond before considering state income taxes. Relative to other fixed income investments, we believe that might be attractive given the potential risks. There have been instances where munis only made sense for investors in the top tax brackets, but that isn't necessarily the case today—especially after considering the risks.
After adjusting for taxes, yields for muni bonds may be attractive relative to alternatives
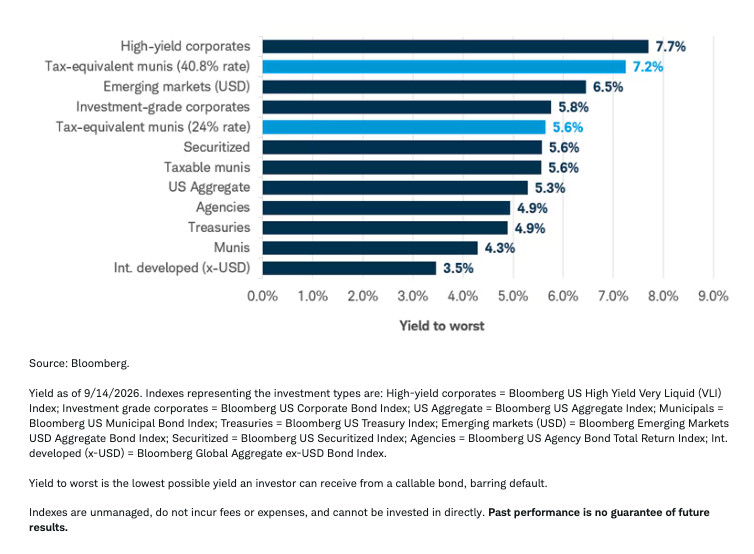
Tax-equivalent yield is a useful way to compare munis with taxable bonds. Because municipal bond interest is generally exempt from federal income taxes, and may also be exempt from state and local taxes for in-state residents, the stated yield on a muni can understate its value to a taxable investor. The higher an investor's tax rate, the more valuable that tax exemption generally becomes.
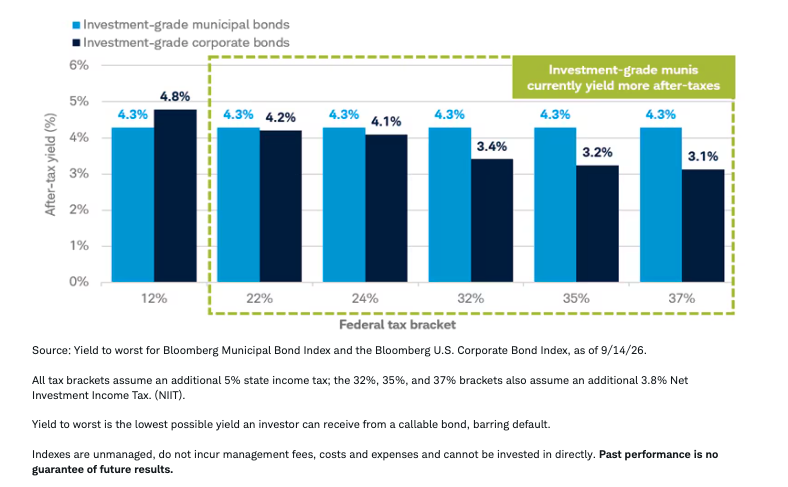
When munis are compared to corporate bonds, an investor may only need to be in the 22% or above federal tax bracket for the after-tax yield on a corporate bond to equal that of a generic muni bond. This threshold fluctuates over time, so we generally suggest that investors use it as a starting point rather than as an absolute cutoff. State taxes, the investor's holding period, credit quality, and liquidity all matter as well.
Municipal bonds currently yield more than corporates after taxes for investors in the 22% and above tax brackets
3. Credit quality generally remains supportive
We believe we are past the peak in municipal credit quality nationally, but the backdrop remains favorable. We don't expect economic growth to substantially slow, which should support state and local government tax revenues. Many states also continue to benefit from robust reserves built after the onset of the COVID-19 pandemic. For example, the average state can run off their rainy day funds for approximately 48 days. This is down from a peak of above 54 days but well above its low. A rainy day fund is akin to a savings account. If a state experiences a slowdown in revenues, they can generally tap into those liquidity sources to help offset the decline.
The average state can run on their savings alone for nearly 48 days
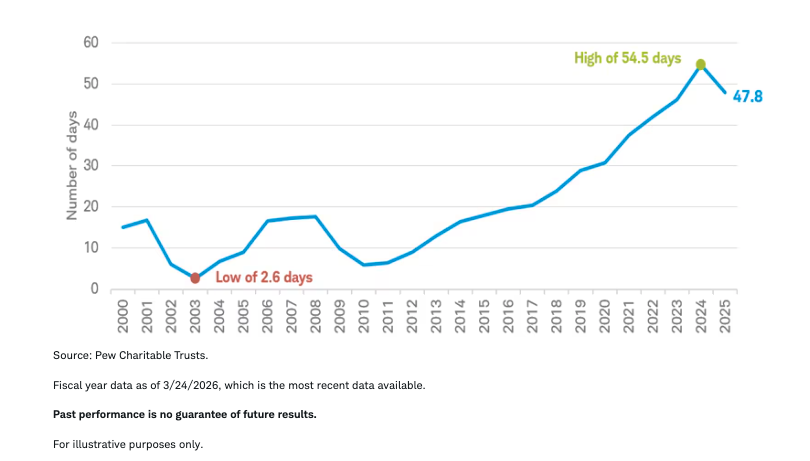
Those liquidity cushions matter. If the economy slows and tax revenues weaken, state and local governments may be able to draw on reserves to help offset declines. The starting point also matters: The muni market remains highly rated on average, and even if there were broad credit downgrades, which is not our base case, the market would likely remain highly rated overall.
That said, credit quality can vary substantially by issuer and sector. Essential-service revenue bonds, general obligation bonds, and certain highly rated state and local issuers can have different risk profiles than more economically sensitive projects. Investors should avoid assuming that all munis carry the same risk simply because they receive similar tax treatment.
The key risk: Can demand keep up with elevated supply?
That does not mean the broad market is free of headwinds. In our view, one key issue facing the muni market is whether demand can absorb elevated levels of supply.
Year-to-date through Sept. 4, municipalities have issued nearly $430 billion of tax-exempt debt—the highest amount for the same period in Bloomberg data going back to 2010. Given ongoing infrastructure needs and reduced post-pandemic federal aid, issuance may remain elevated in the near term.
Issuance of tax-exempt munis has been elevated in 2026
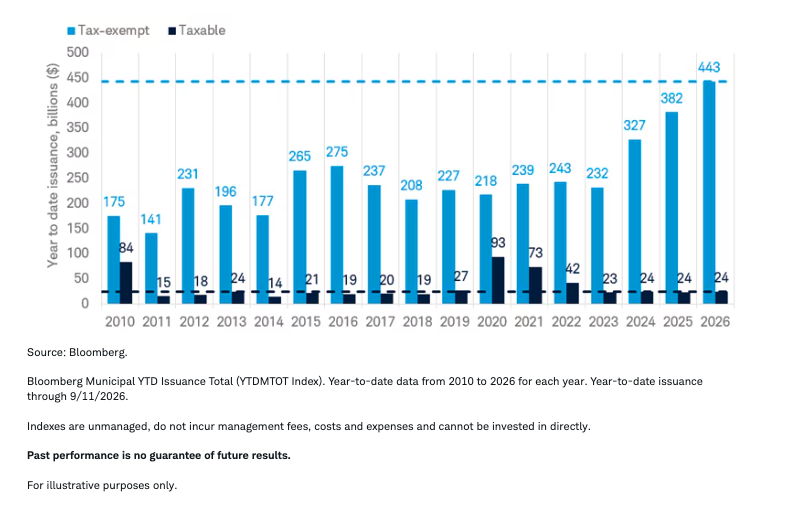
Municipalities are issuing debt at a record pace for several reasons. First, infrastructure costs, which many muni bonds are issued to fund, are higher after a prolonged period of elevated inflation and higher yields. Second, the fiscal aid granted to many states and local governments after the onset of COVID-19 has largely been spent. Some of that shortfall is being replaced with bond issuance. These factors are unlikely to change quickly, suggesting issuance may remain elevated.
For investors, the important takeaway is that the muni market may need sustained demand to absorb continued issuance. If demand falters, yields may have to move higher, and prices lower, to attract buyers and support returns.
Low relative yields may weigh on demand
One factor that may weigh on demand is the level of muni yields relative to Treasuries. A common metric for gauging relative value is the muni-to-Treasury ratio, also known as the municipals-over-bonds (MOB) spread. It compares the yield on a generic AAA-rated muni with the yield on a comparable Treasury bond before taxes.
Ratios for munis with maturities of three years or less are in the upper 50s or low 60s. As investors move further out the maturity spectrum, ratios increase and are near the highs of the year.
Yield ratios for short-term munis remain low
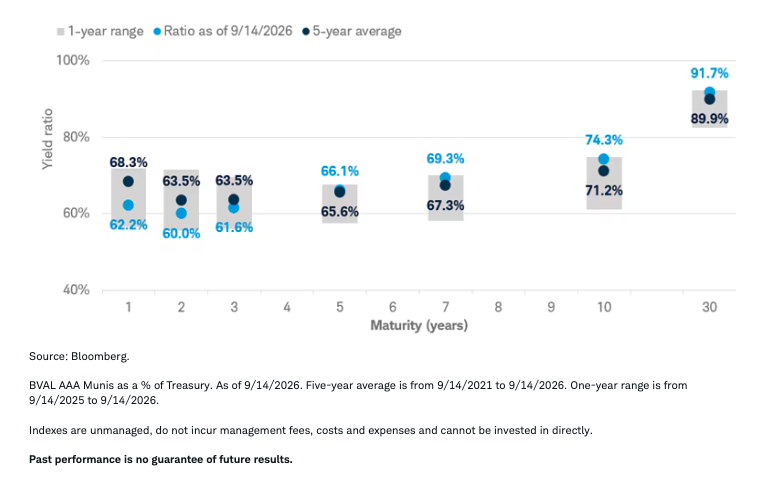
This matters because the muni market is largely dominated by retail investors, many of whom prefer staying short term or not moving too far out on the yield curve. For munis with maturities under five years, yields are near the level where an investor would need to be subject to the maximum tax rate for the yield on a generic AAA muni to equal that of a comparable Treasury bond after taxes. For example, the two-year ratio is about 60%, meaning an investor would need a tax rate of about 40% to make a generic AAA two-year muni equal to a two-year Treasury on a tax-adjusted basis. The top federal tax rate is 37%, plus a 3.8% Net Investment Income Tax (NIIT) tax for certain investors, for a combined rate of 40.8%.
Keep duration close to your time horizon
Duration is one important lever that investors can control. Longer-duration bonds are more sensitive to changes in interest rates, which can help when rates fall, but hurt when rates rise. Investors who are concerned about additional rate volatility may want to avoid extending too far beyond their investment horizon.
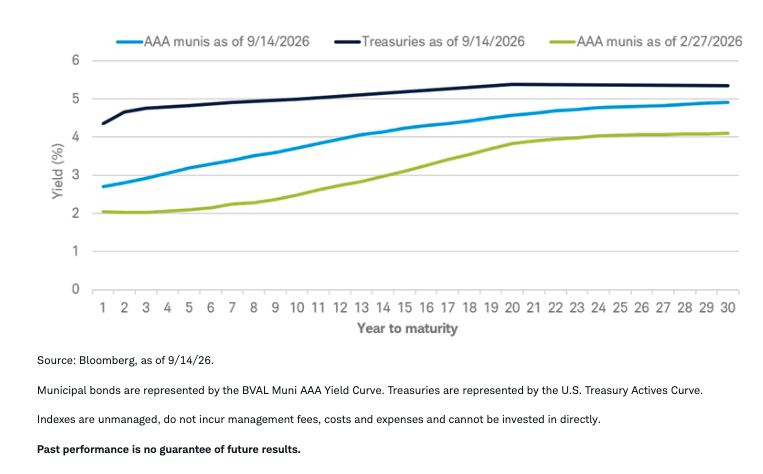
We generally suggest slightly shorter-than-benchmark duration due to the potential for higher yields and interest-rate volatility. For muni investors, a useful starting point is the duration of the Bloomberg Municipal Bond Index, which is about 6.4 years. Investors may want to target a duration modestly below that level, depending on their financial situation, time horizon, and risk tolerance. For investors focused on income, one positive is that yields, especially for shorter-term munis, have moved higher over the past six months. That means investors may not need to extend too far out the maturity spectrum to generate attractive tax-advantaged income.
The muni yield curve has flattened, meaning investors might not have to extend maturity too much to get higher yields
Be careful about reaching for yield
Higher yields can make riskier parts of the muni market look more appealing, but investors should ask what risks they are being paid to take. A higher yield may reflect longer duration, weaker credit quality, lower liquidity, or a combination of all three. For investors who rely on munis for stability, the goal might be to earn reasonable income without taking risks that are inconsistent with the role munis are meant to play in the portfolio.
What to consider now
Recent muni performance has been disappointing, but we do not think it changes the longer-term case for the asset class. Municipal bonds can still offer attractive tax-advantaged income and relatively stable credit quality for investors who understand the risks and can look beyond short-term price volatility. The recent move higher in yields has made prices weaker, but it has also improved the income available to investors today.
Given higher yields, elevated supply, and uncertainty around demand, we believe investors should stay disciplined. That might mean avoiding reaching too far for yield in either lower-rated or longer-term bonds, considering a slightly shorter-than-benchmark duration, and focusing on highly rated issuers.
1 The Moody's investment-grade rating scale is Aaa, Aa, A, and Baa, and the sub-investment-grade scale is Ba, B, Caa, Ca, and C. Standard and Poor's investment-grade rating scale is AAA, AA, A, and BBB and the sub-investment-grade scale is BB, B, CCC, CC, and C. Ratings from AA to CCC may be modified by the addition of a plus (+) or minus (-) sign to show relative standing within the major rating categories. Fitch's investment-grade rating scale is AAA, AA, A, and BBB and the sub-investment-grade scale is BB, B, CCC, CC, and C.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcast
This material is intended for general informational and educational purposes only. This should not be considered an individualized recommendation or personalized investment advice. The investment strategies mentioned are not suitable for everyone. Each investor needs to review an investment strategy for his or her own particular situation before making any investment decisions.
All expressions of opinion are subject to change without notice in reaction to shifting market, economic or political conditions. Data contained herein from third party providers is obtained from what are considered reliable sources. However, its accuracy, completeness or reliability cannot be guaranteed.
For illustrative purposes only. Not intended to be reflective of results you can expect to achieve.
Past performance is no guarantee of future results.
Investing involves risk, including loss of principal.
Fixed income securities are subject to increased loss of principal during periods of rising interest rates. Fixed income investments are subject to various other risks including changes in credit quality, market valuations, liquidity, prepayments, early redemption, corporate events, tax ramifications, and other factors. Lower rated securities are subject to greater credit risk, default risk, and liquidity risk.
Diversification and asset allocation strategies do not ensure a profit and do not protect against losses in declining markets.
Tax-exempt bonds are not necessarily a suitable investment for all persons. Information related to a security's tax-exempt status (federal and in-state) is obtained from third parties, and Charles Schwab & Co., Inc. does not guarantee its accuracy. Tax-exempt income may be subject to the Alternative Minimum Tax (AMT). Capital appreciation from bond funds and discounted bonds may be subject to state or local taxes. Capital gains are not exempt from federal income tax.
International investments involve additional risks, which include differences in financial accounting standards, currency fluctuations, geopolitical risk, foreign taxes and regulations, and the potential for illiquid markets. Investing in emerging markets may accentuate this risk.
Emerging Markets Risk. Emerging market countries may be more likely to experience political turmoil or rapid changes in market or economic conditions than more developed countries. Such countries often have less uniformity in accounting and reporting requirements and greater risk associated with the custody of securities. In addition, the financial stability of issuers (including governments) in emerging market countries may be more precarious than in other countries. As a result, there will tend to be an increased risk of price volatility associated with the fund's investments in emerging market countries and, at times, it may be difficult to value such investments.
This information is not a specific recommendation, individualized tax, legal, or investment advice. Tax laws are subject to change, either prospectively or retroactively. Where specific advice is necessary or appropriate, individuals should contact their own professional tax and investment advisors or other professionals (CPA, Financial Planner, Investment Manager, Estate Attorney) to help answer questions about specific situations or needs prior to taking any action based upon this information.
Indexes are unmanaged, do not incur management fees, costs, and expenses and cannot be invested in directly. For more information on indexes, please see schwab.com/indexdefinitions.
The Schwab Center for Financial Research is a division of Charles Schwab & Co., Inc.
Source: Bloomberg Index Services Limited. BLOOMBERG® is a trademark and service mark of Bloomberg Finance L.P. and its affiliates (collectively "Bloomberg"). Bloomberg or Bloomberg's licensors own all proprietary rights in the Bloomberg Indices. Neither Bloomberg nor Bloomberg's licensors approves or endorses this material, or guarantees the accuracy or completeness of any information herein, or makes any warranty, express or implied, as to the results to be obtained therefrom and, to the maximum extent allowed by law, neither shall have any liability or responsibility for injury or damages arising in connection therewith.
The Bloomberg Municipal Bond Total Return Index (LMBITR Index) is a broad-based benchmark that measures the investment-grade, U.S. dollar-denominated, fixed-rate, tax-exempt municipal bond market.
The Bloomberg U.S. Treasury Total Return Index (LUATTRUU Index) measures the performance of U.S. dollar-denominated, fixed-rate nominal debt issued by the U.S. Treasury.
The Bloomberg U.S. Corporate Investment Grade Index (LUACTRUU Index) measures the performance of U.S. dollar-denominated, investment-grade, fixed-rate, taxable corporate bonds.
The Bloomberg Municipal Bond Statistics Index (LMBISTAT Index) is a Bloomberg municipal bond market data series that tracks return components for the municipal bond market, including price return, coupon return, and total return.
The Bloomberg US Securitized Index measures the performance of U.S. dollar-denominated, investment-grade securitized debt.
The Bloomberg US Agency Bond Total Return Index measures the total return of U.S. dollar-denominated, investment-grade debt issued by U.S. government agencies, government-sponsored enterprises, and government-owned corporations.
The Bloomberg Municipal YTD Issuance Total Index (YTDMTOT Index) is a Bloomberg municipal market data series that tracks year-to-date municipal bond issuance.
The BVAL AAA Municipal Yield Curve is a Bloomberg evaluated yield curve that reflects estimated yields for AAA-rated municipal bonds across a range of maturities.
The U.S. Treasury Actives Curve is a Bloomberg yield curve that reflects yields on actively traded U.S. Treasury securities across a range of maturities.
BVAL AAA Munis as a % of Treasury is a Bloomberg relative-value measure that compares yields on AAA-rated municipal bonds with yields on comparable U.S. Treasury securities.
The Charles Schwab Corporation provides a full range of brokerage, banking and financial advisory services through its operating subsidiaries. Its broker-dealer subsidiary, Charles Schwab & Co., Inc. (member SIPC), and its affiliates offer investment services and products. Its banking subsidiary, Charles Schwab Bank, SSB (member FDIC and an Equal Housing Lender) provides deposit and lending services and product. Its banking subsidiary, Charles Schwab Premier Bank, SSB (member FDIC) provides cryptocurrency services and products.
This site is designed for U.S. residents. Non-U.S. residents are subject to country-specific restrictions. Learn more about our services for non-U.S. residents, Charles Schwab Hong Kong clients, Charles Schwab U.K. clients.
© 2026 Charles Schwab & Co., Inc. All rights reserved. Member SIPC. Unauthorized access is prohibited. Usage will be monitored.
Membership required
Membership is now required to use this feature. To learn more:
View Membership Benefits