Key takeaways
- Strong equity market starts have historically tended to carry on through year-end, and today’s higher yields appear less threatening amid a resilient economic and earnings backdrop and ClearBridge US Recession Dashboard flashing a green, expansionary signal.
- The recent rise in the 10-year Treasury yield has been driven primarily by higher real rates, not a surge in inflation expectations or term premium, suggesting this is not a fiscal or credibility shock.
- With nominal growth still solid and inflation expectations well anchored, a pause or decline in yields could ease financial conditions and help support the next leg higher in risk assets.
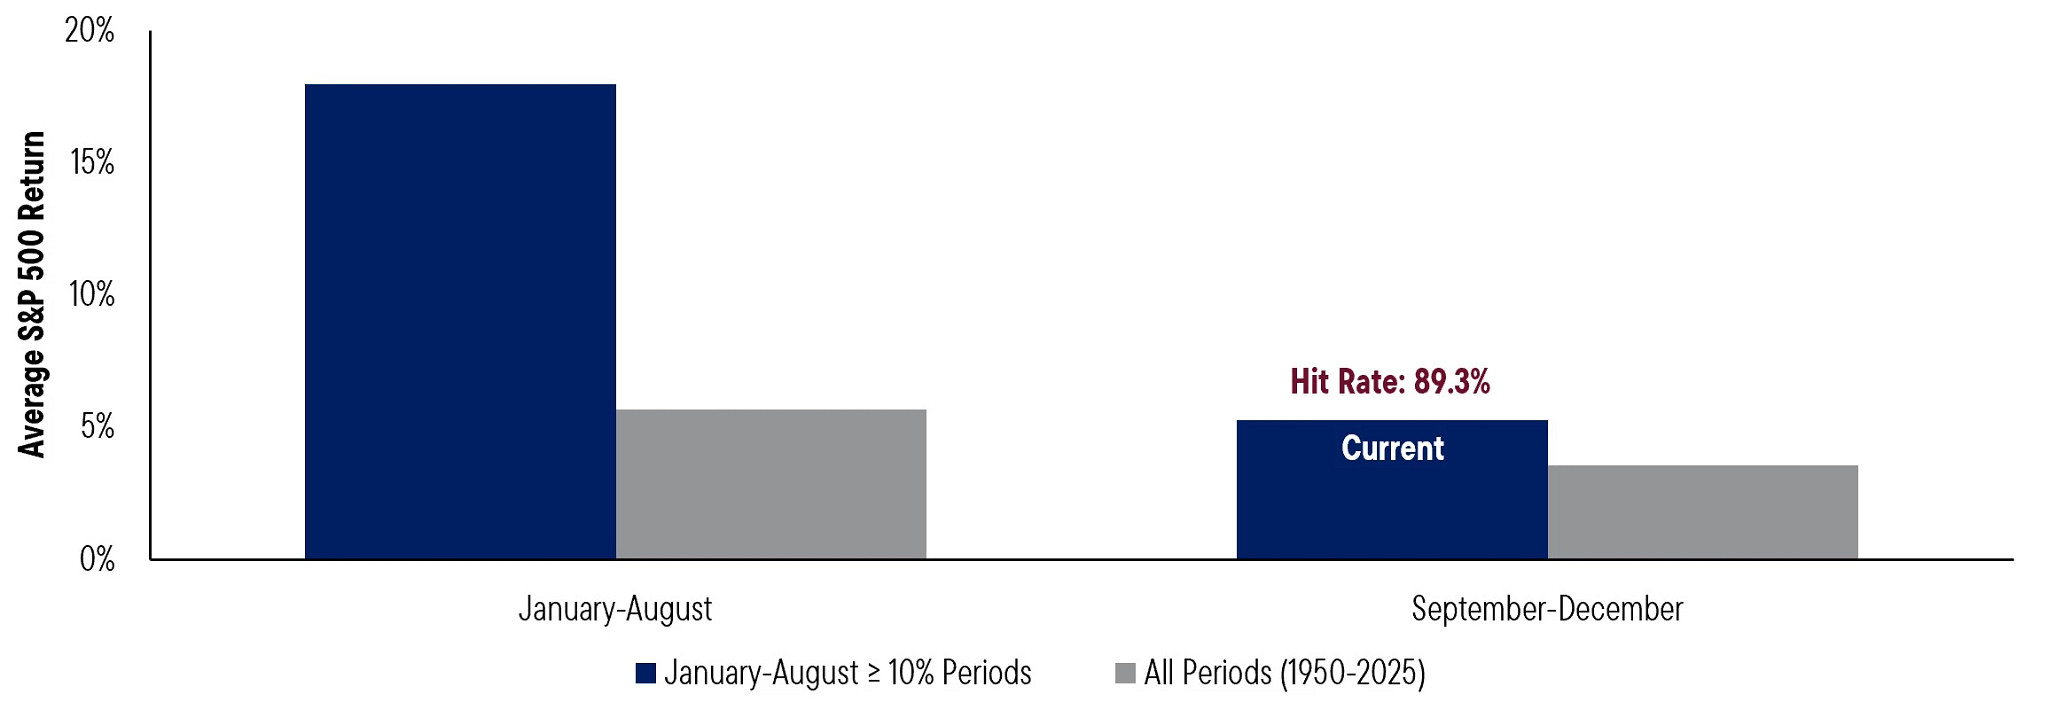
Some investors are questioning how much further this year’s rally can run with the S&P 500 Index up 12.3% through the first eight months of the year. Encouragingly, history suggests that strong starts tend to persist; when the S&P 500 has gained more than 10% through August it has advanced from September through December in 25 of 28 instances, an 89% positive hit rate. These periods produced an average rest-of-year return of approximately 5.3%, well above the 3.6% average for all observations since 1950.
Exhibit 1: Start Strong, End Strong
This should give investors little reason for pessimism, although two of the three negative periods (1979 and 1987) were marked by sharp increases in long-term interest rates that contributed to difficult trading conditions for US equities. That historical caveat feels especially relevant today, with the 10-year Treasury yield up more than 80 bps from its late-February low and nearing 5%. As a result, concerns have lingered that the bond market could disrupt what is typically a strong final stretch of the year for stocks.
See more: What’s Driving the Rise in Global Bond Yields?
The persistence of higher long-end yields is particularly notable because both the US Citi Economic Surprise Index and the US Citi Inflation Surprise Index rolled over at the end of June, i.e., data releases in aggregate are no longer beating expectations as frequently. Ordinarily, weaker economic and inflation data versus expectations (surprises) push yields lower, not higher, meaning the recent divergence warrants a closer look.
Some market observers point to increased bond supply as the culprit, with heavy investment-grade issuance from hyperscalers drawing in capital as the supply of Treasurys themselves are rising. However, this dynamic has been well understood for months, and investment-grade spreads are nearly at the tightest levels of this cycle. At least so far, this suggests demand remains adequate to absorb the elevated issuance (supply).
Others argue that yields are rising because of concerns surrounding US fiscal sustainability, Federal Reserve credibility and/or currency debasement. However, longer-term credit default swap (CDS) spreads on US Treasury debt are essentially unchanged from late February when the 10-year Treasury yield was last below 4%, suggesting limited supporting evidence that investors are demanding additional compensation to for these risks.
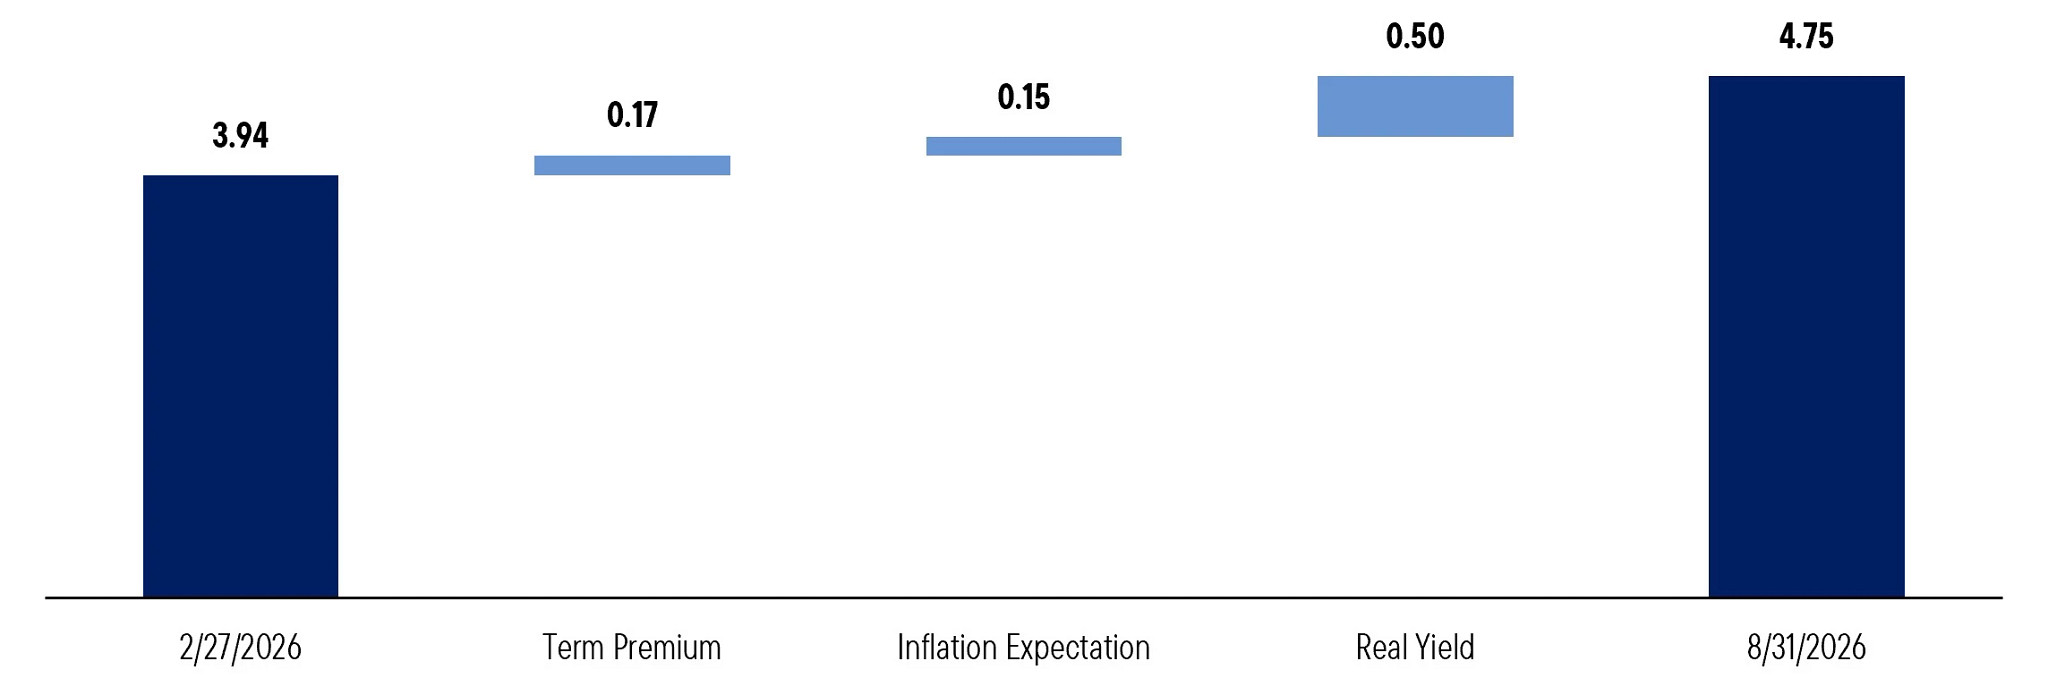
A decomposition of the recent rise in the 10-year Treasury yield offers further evidence against that interpretation. Since the late February lows, the increase in long-term Treasury yields has come primarily from real rates, which are up 50 bps. By comparison, inflation expectations have risen just 15 bps and the term premium has increased by 17 bps.
Exhibit 2: 10-Year Treasury Yield Decomposition
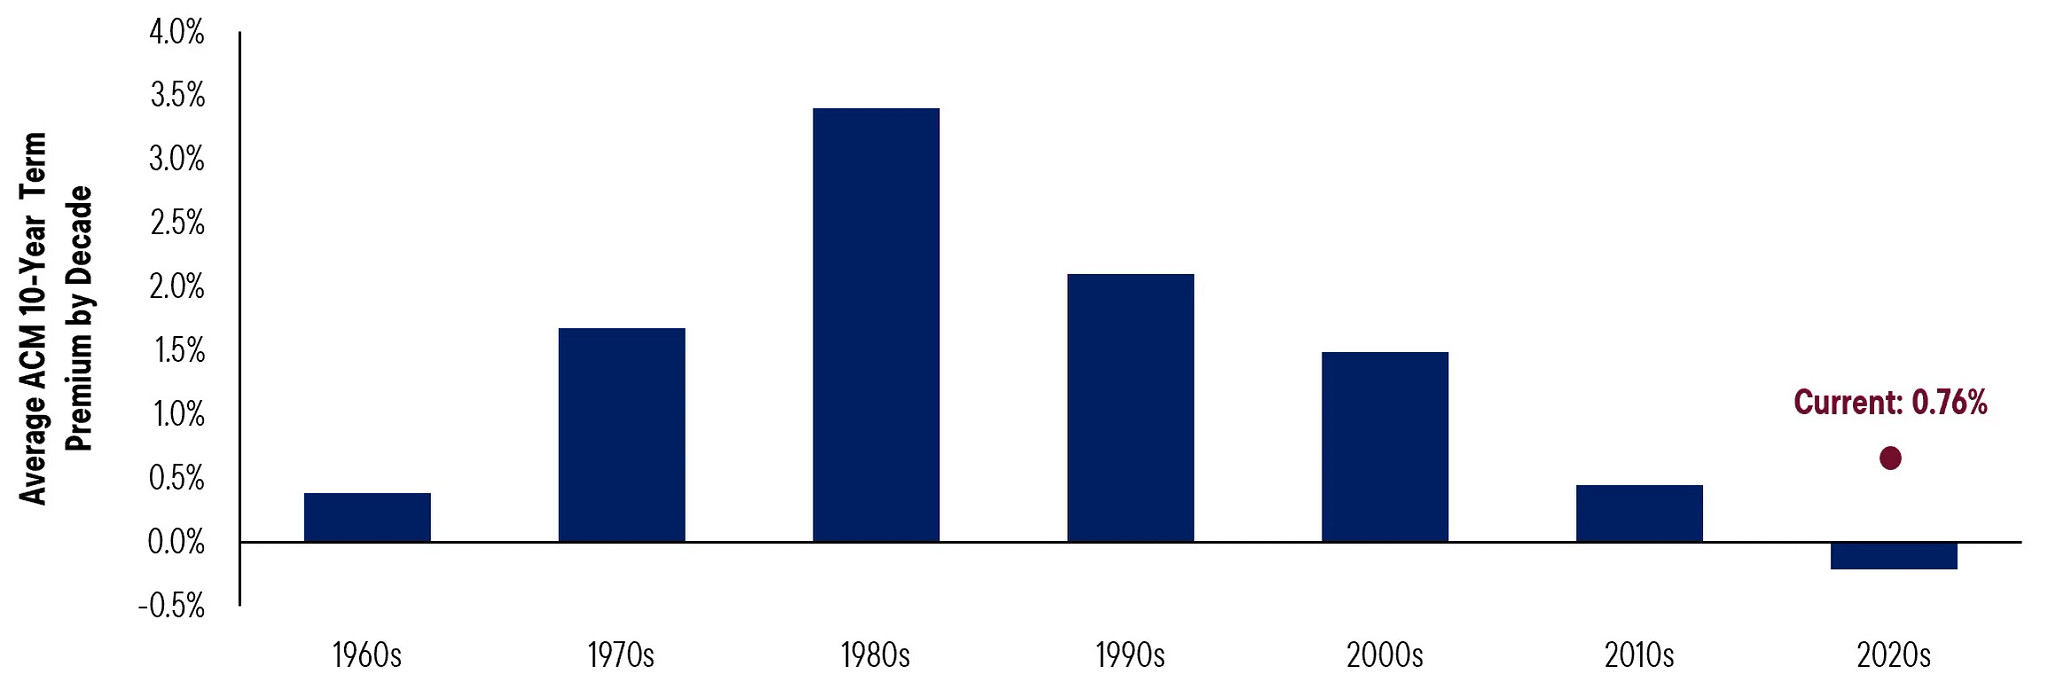
In this framework, the term premium mainly captures uncertainty and typically rises when investors have less confidence in the inflation outlook. While the term premium has moved higher since 2022, it started from a very low base after spending much of last decade in negative territory amid persistent deflation risks. At roughly 80 bps currently, today’s term premium remains moderate by historical standards.
Exhibit 3: Term Premium Higher, but Not Back to the 1980s
Taken together, stable long-term inflation breakeven rates and a still-modest term premium suggest the bond market is not pricing a persistent inflation or credibility shock. Instead, real yields appear to be doing the heavy lifting with economic growth holding up better than expected on the back of a resilient consumer and the AI infrastructure buildout.
Upward pressure on real long-term yields in recent months is also, in part, reflecting the substantial repricing of the monetary policy path, with investors moving from pricing multiple rate cuts in federal-funds futures in February to multiple hikes today. The expected federal-funds rate in July 2027, for example, has risen by nearly 135 bps. While there is no single smoking gun behind why real long-bond yields have risen, what does appear clear is that several catalysts are contributing, as opposed to the bond vigilantes riding into town.
Higher Yields in a Higher Nominal Growth World
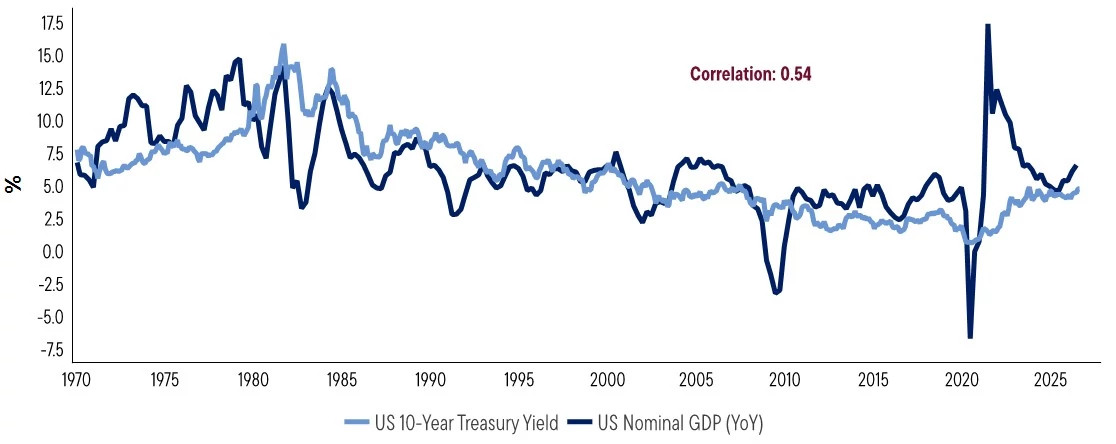
We believe bond yields should be viewed in the context of nominal economic growth, rather than independently. Long-term Treasury yields have historically tracked nominal GDP closely, and through this lens today’s levels do not look particularly concerning.
Nominal GDP is currently running at a roughly 6% pace, well above the 10-year Treasury yield around 4.75%. This marks the strongest persistent nominal GDP growth in years and is comparable to what was witnessed during the 2001–2007 economic expansion — the last multiyear period in which nominal GDP growth exceeded 5%. During the final four years of that expansion, nominal GDP was close to 6%, and the 10-year Treasury yield averaged 4.5% and was largely rangebound between 4.0% and 5.0%, similar to today.
Exhibit 4: 10-Year Treasury Yield and Nominal GDP Growth
The stronger economic growth environment is also likely contributing to the rise in bond yields globally. The 10-year Treasury has not moved in isolation, with many major developed market countries also seeing upward pressure on their sovereign long-bond yields alongside an improving global economic outlook. Similarly, the last time the US, Japan, the U.K., and the eurozone and had three-year average nominal GDP growth rates near today’s levels, their respective government bond yields were also similar to current levels. Japan stands out as the exception, however, with yields lower today than in its last comparable period of strong nominal growth. From this perspective, the global rise in long-bond yields looks less like a market hiccup and more like normalization following the period of secular stagnation that emerged after the Global Financial Crisis.
Much of the prior decade (2010s) was defined by deleveraging, tepid economic growth, lingering deflation risks and unconventionally loose monetary policy — a highly unusual economic backdrop. We believe today’s higher nominal and real yields suggest economic normalization, underpinned by stronger economic momentum, buoyant consumer spending and robust business investment. Major central banks have also taken steps to normalize monetary policy over the past few years, removing a key force that suppressed global long-term bond yields.
Equities Are Looking Through the Rate Move
Recent equity performance is consistent with this interpretation, with the bull market persisting even as higher yields have lowered valuations. If current yields were signaling a material threat to the economy, stocks would likely be much lower due to a corresponding reduction in earnings expectations. Instead, the S&P 500 delivered blowout second-quarter results, with EPS up 52% YoY. However, the index barely reacted to this strength and is less than 3% above the level it entered at the beginning of second-quarter earnings season. The combination of stronger earnings and limited price appreciation has lowered the valuation hurdle for further market gains.
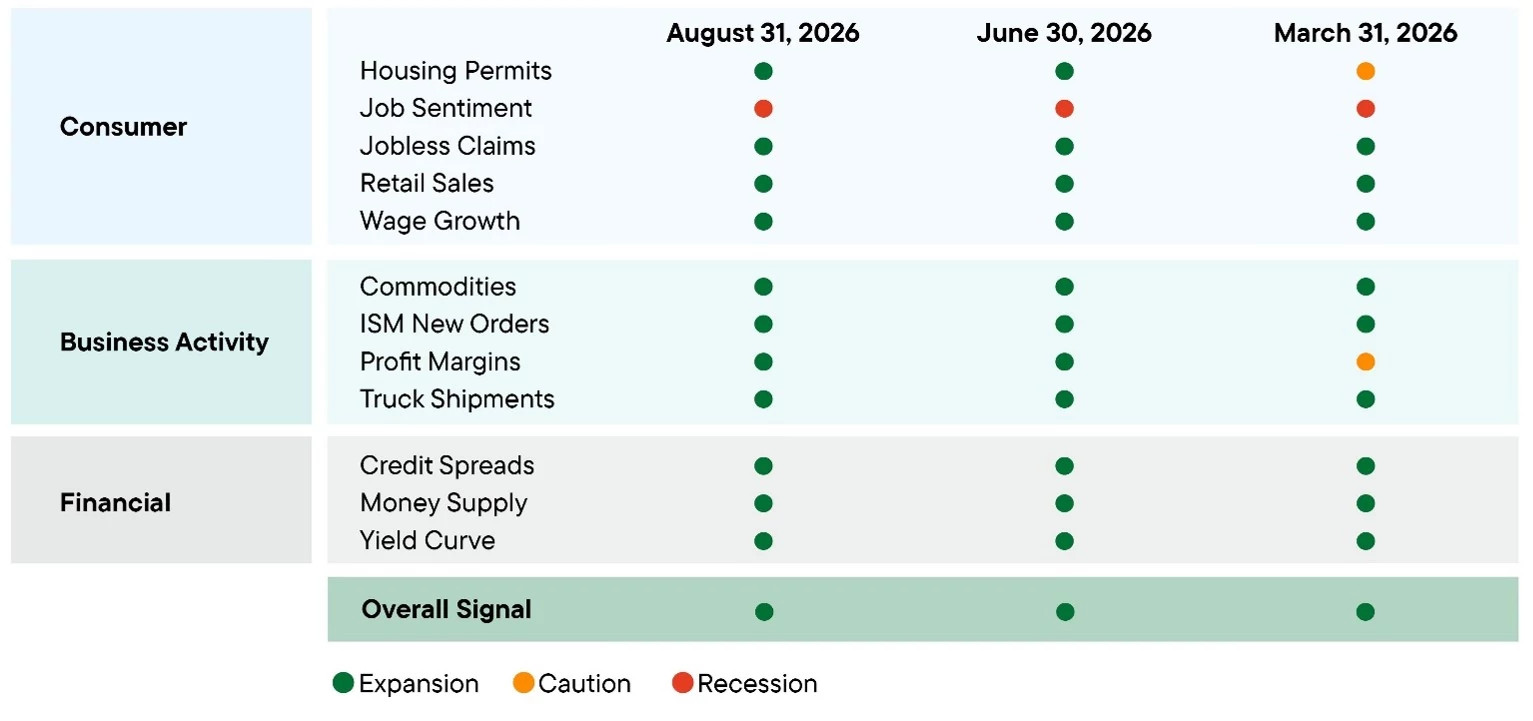
This signal of underlying fundamental strength is confirmed by the firmly green expansionary signal from the ClearBridge US Recession Dashboard. There were no indicator changes in August, and the strength of the dashboard underpins our belief that the economy will remain on solid footing in the coming year.
Exhibit 5: ClearBridge US Recession Dashboard
Lower Yields Could Provide the Next Catalyst
A drop in long-term bond yields in the coming quarters could provide the catalyst for further equity market upside. Even though the futures market is pricing odds of a rate hike at 65% at the Fed’s September meeting, we believe a path to lower long-term yields exists should consumer spending moderate as energy and real-income pressures continue to build. Additionally, inflation expectations appear to remain well anchored, meaning any disinflationary surprises in the coming months could pull the expected monetary policy path lower. Additionally, the emergence of AI-driven productivity gains could help support economic growth without reigniting inflation.
Ultimately, a decline in yields would ease financial conditions, support valuations and complement a still-solid earnings backdrop. In that environment, higher rates are unlikely to prove a lasting “real” problem. Instead, a subsequent decline or even pause in yields could set the stage for the next leg higher in risk assets.
A message from Advisor Perspectives and VettaFi: Discover something new! Click here to register for our upcoming webcasts.
DEFINTIONS
The ClearBridge Recession Risk Dashboard is a group of 12 indicators that examine the health of the US economy and the likelihood of a downturn.
The S&P 500 Index is an unmanaged index of 500 stocks that is generally representative of the performance of larger companies in the United States.
The ISM New Orders Index is a major component of the Institute for Supply Management (ISM) PMI reports, acting as a leading indicator for the broader US economy.
The One Big Beautiful Bill Act of 2025 is a US federal statute passed by the 119th United States Congress containing tax and spending policies that form the core of President Donald Trump's second-term agenda. The bill was signed into law by President Trump on July 4, 2025.
Capital expenditure (capex) refers to investment spending in long-term assets (fixed assets). These expenditures include new buildings, machinery, and other equipment needed for an organization's day-to-day operations. Most companies use capex financing to fund their long-term investments.
WHAT ARE THE RISKS?
All investments involve risks, including possible loss of principal. Past performance is no guarantee of future results. Please note that an investor cannot invest directly in an index. Unmanaged index returns do not reflect any fees, expenses or sales charges.
Equity securities are subject to price fluctuation and possible loss of principal. Large-capitalization companies may fall out of favor with investors based on market and economic conditions. Small- and mid-cap stocks involve greater risks and volatility than large-cap stocks.
Commodities and currencies contain heightened risk that include market, political, regulatory, and natural conditions and may not be suitable for all investors.
US Treasuries are direct debt obligations issued and backed by the “full faith and credit” of the US government. The US government guarantees the principal and interest payments on US Treasuries when the securities are held to maturity. Unlike US Treasuries, debt securities issued by the federal agencies and instrumentalities and related investments may or may not be backed by the full faith and credit of the US government. Even when the US government guarantees principal and interest payments on securities, this guarantee does not apply to losses resulting from declines in the market value of these securities.
More Tax Planning Topics >